
 Pocket Otoscope Market | 2026-2036
Pocket Otoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Otoscope Market Analysis
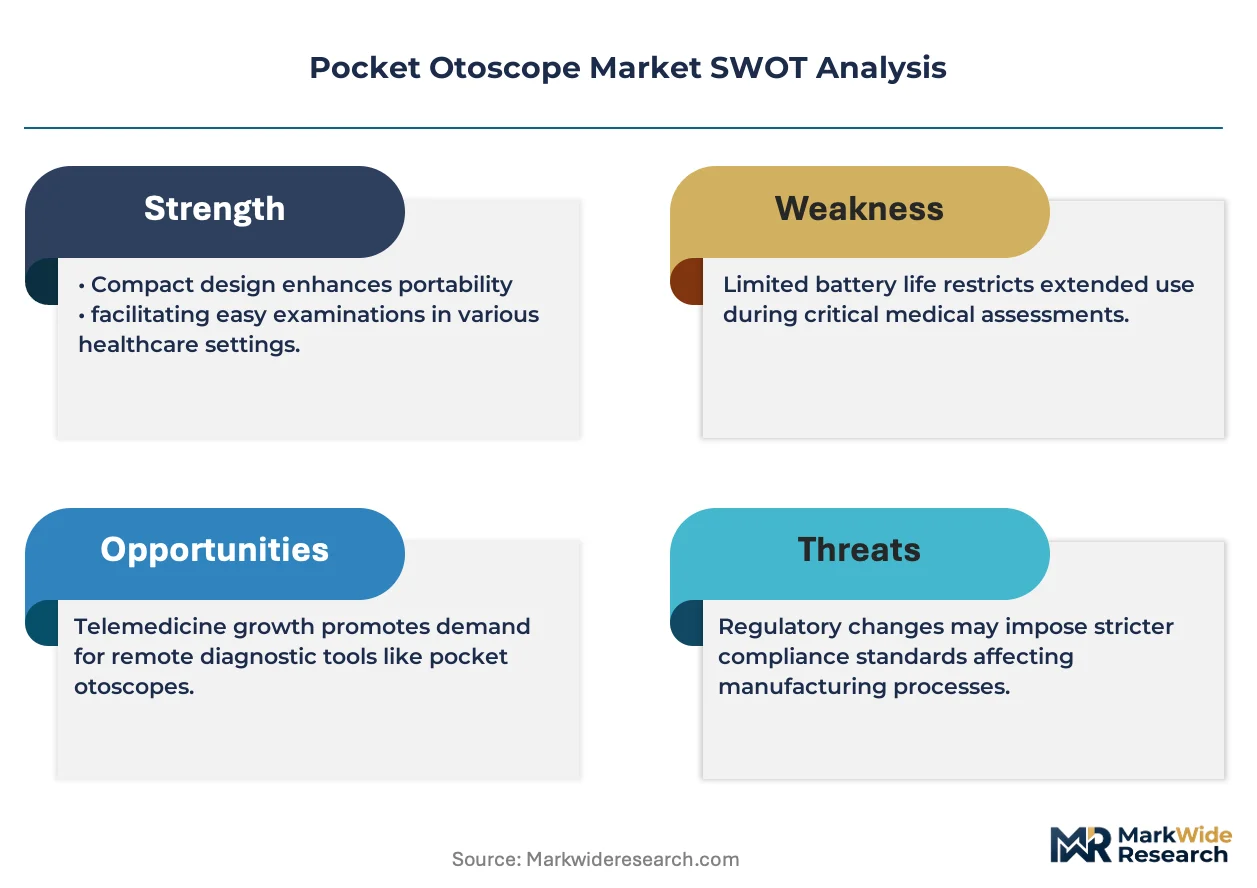
LED illumination modules are restructuring cost profiles across pocket otoscope manufacturing, displacing traditional halogen bulb assemblies with solid-state alternatives that cut replacement frequency and energy draw. Heine Optotechnik leverages German precision optics heritage to sustain premium positioning in European ENT practices. Welch Allyn, Inc. anchors North American distribution through institutional procurement channels serving hospital systems. Rudolf Riester GmbH competes on modularity, offering interchangeable specula heads that extend instrument lifespan across primary care deployments.
A pocket otoscope is a handheld, battery-powered auriscope designed for visual examination of the external auditory canal and tympanic membrane, typically incorporating 3V to 4.5V power systems, 2.5V to 3.5V lamp or LED sources, and 2.5x to 3.5x magnification optics through disposable or reusable specula of 2.5mm to 4.0mm diameter. Digital otoscope segments lead value generation as camera-equipped variants command price premiums and integrate with electronic health record workflows. Wireless transmission technology represents the fastest-expanding capability dimension, enabling real-time image sharing between rural clinics and urban referral centers. Fiber optics technology occupies a mature position in premium manual instruments where durability and color fidelity justify higher unit economics.
FDA 510(k) premarket notification requirements govern digital and video otoscope introductions in the United States, while the EU Medical Device Regulation (MDR) imposes clinical evidence and post-market surveillance obligations on manufacturers distributing within European Economic Area member states. ISO 13485 quality management certification functions as a baseline market access credential across both jurisdictions, with notified body audits intensifying following MDR transition deadlines. Stakeholders must monitor convergence between AI-enabled diagnostic algorithms and existing regulatory frameworks for software-as-medical-device classification.
Market Dynamics
LED module standardization is compressing manufacturing cost structures while wireless transmission protocols are unlocking telehealth integration across outpatient networks, fundamentally restructuring how diagnostic value migrates through distribution channels.
Growth Catalysts
- FDA 510(k) pathway compression:Digital otoscope accessories now clear premarket notification faster than full device submissions, accelerating accessory vendor entry into US outpatient clinic procurement cycles.
- ENT clinic fleet expansion:Specialized practices across Germany, Japan, and Brazil are scaling portable diagnostic inventories to serve ambulatory patient volumes.
- Telehealth service provider procurement:Remote diagnostic platforms operating in North American and Western European metropolitan corridors are standardizing on camera-equipped variants for real-time specialist consultation.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control high-grade lens assemblies, creating single-source vulnerability for premium instrument manufacturers.
- EU MDR clinical evidence requirements:Post-market surveillance obligations and notified body audit intensification are extending certification timelines for European Economic Area market entry.
- Disposable specula cost volatility:Medical-grade polymer feedstock price fluctuations directly compress margin structures in high-volume primary care deployments.
Strategic Opportunities
- Rural-urban referral network integration:Wireless transmission-enabled devices create white space for real-time image sharing between peripheral clinics and central hospital systems in underpenetrated corridors.
- AI-enabled diagnostic algorithm convergence:Software-as-medical-device classification frameworks are opening regulatory pathways for automated tympanic membrane analysis integrated with electronic health record workflows.
- Modular instrument lifespan extension:Interchangeable specula head architectures reduce total cost of ownership for cash-constrained primary care deployments in emerging outpatient networks.
Industry Challenges
- ISO 13485 quality management certification backlog:Notified body capacity constraints following MDR transition deadlines are delaying baseline market access credential acquisition for new market entrants.
- Legacy halogen-to-LED manufacturing retooling:Solid-state illumination module integration requires production line reconfiguration and technician retraining across established assembly facilities.
- Software-hardware regulatory boundary navigation:Convergence between AI diagnostic tools and physical otoscope hardware creates classification uncertainty under existing FDA and EU MDR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Otoscope Market |
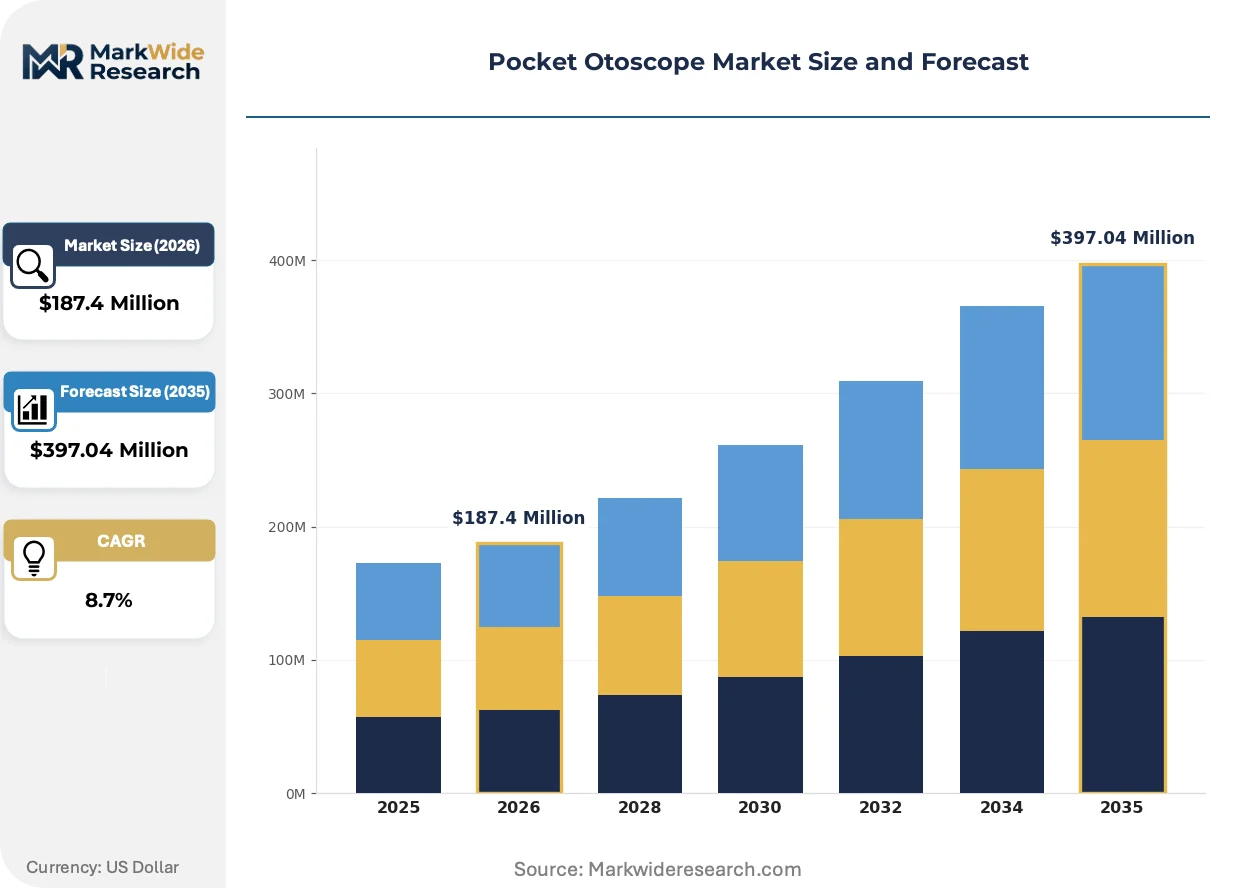
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Otoscope, Standard Otoscope, Wireless Otoscope, Video Otoscope End User: Healthcare Professionals, Home Care Users, Hospitals, Clinics Application: ENT Diagnosis, Patient Monitoring, Education, Telehealth Technology: LED Lighting, Fiber Optics, Wireless Transmission, Camera Technology |
| Companies Covered | Welch Allyn, Inc., Heine Optotechnik, Rudolf Riester GmbH, American Diagnostic Corporation, SyncVision Technology Corporation, Luxamed, Olympus Corporation, Medline Industries, LP, Hill-Rom Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Otoscope Market Emerging Trajectories
Diagnostic capability is migrating from centralized hospital settings toward distributed point-of-care locations, with hardware miniaturization and connectivity protocols enabling new service delivery architectures.
Wireless transmission technology is decentralizing diagnostic expertise across geographically dispersed care networks. Camera-equipped pocket otoscopes now stream high-resolution tympanic membrane imagery from rural clinics to urban otolaryngology specialists in real time. Primary care networks across the United States and Germany are adopting these systems to reduce unnecessary specialist referrals while maintaining diagnostic confidence.
EU Medical Device Regulation post-market surveillance obligations are intensifying clinical evidence requirements for digital otoscope manufacturers distributing within European Economic Area member states. Notified body audits now demand systematic post-launch performance data collection, compressing product lifecycle management timelines. German and Swiss precision instrument manufacturers are restructuring quality management systems to accommodate sustained regulatory scrutiny.
Telehealth platform procurement is consolidating vendor selection around electronic health record integration capabilities. Outpatient clinic networks now prioritize otoscope systems with direct HL7 FHIR connectivity over standalone diagnostic hardware. This specification shift is most visible across North American metropolitan corridors where health system procurement functions centralize medical device standardization decisions.
Pocket Otoscope Market Segmentation
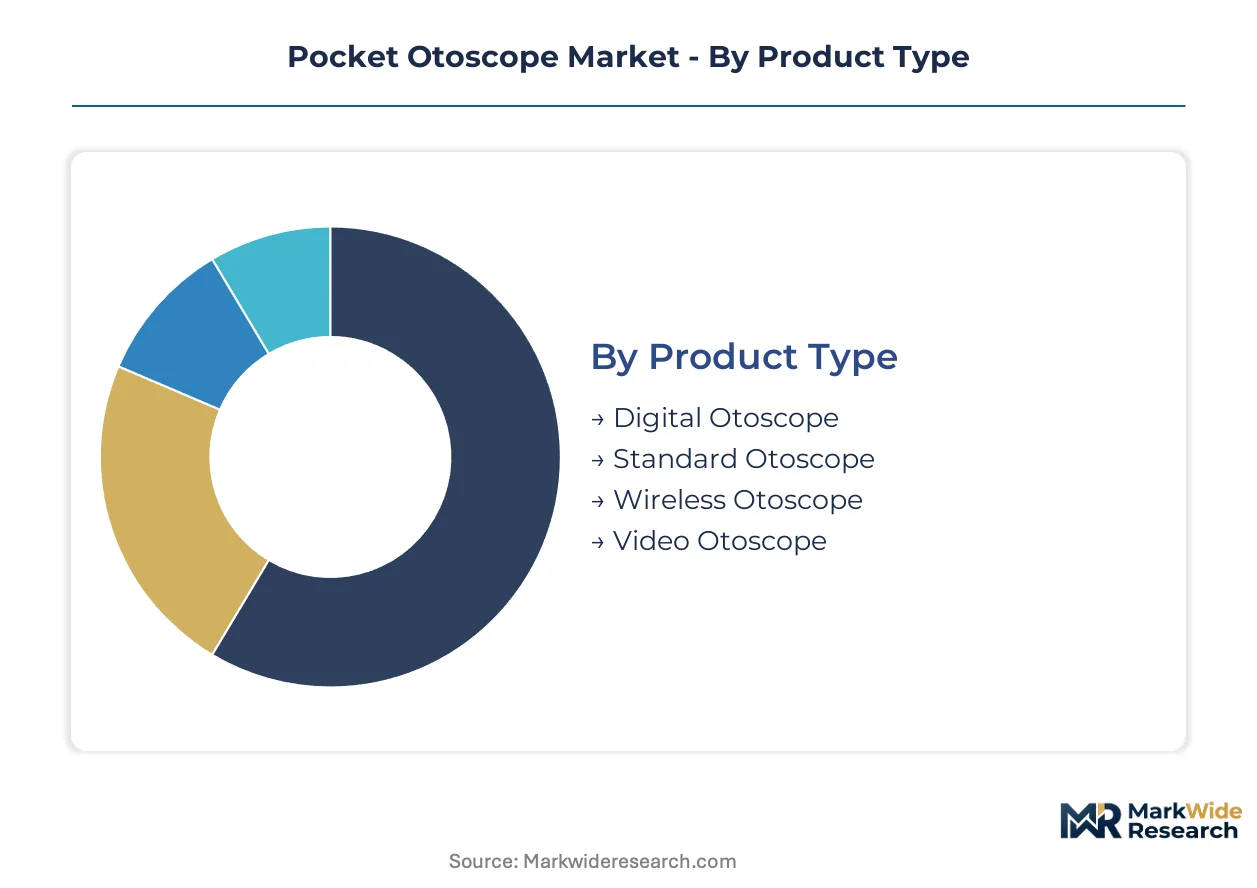
Product configuration, user environment, and connectivity architecture determine procurement specifications across pocket otoscope deployments. Healthcare systems prioritize EHR integration and diagnostic fidelity when allocating capital to portable examination instruments.
Product Type:
Purchase volume concentrates in camera-equipped variants that command reimbursement eligibility and specialist consultation workflows.
- Digital Otoscope:Solid-state imaging sensors capture high-resolution tympanic membrane visualization with direct electronic health record upload capability. ENT clinics across Germany and Japan standardize procurement on these units to support ambulatory diagnostic throughput.
- Wireless Otoscope:Bluetooth and Wi-Fi transmission protocols enable real-time image streaming from primary care settings to urban referral centers. Telehealth service providers in North American metropolitan corridors drive demand acceleration for untethered examination workflows.
- Standard Otoscope:Conventional battery-powered instruments with halogen or LED illumination serve cost-constrained primary care inventories.
- Video Otoscope:Integrated display screens and recording functionality support medical education and remote consultation documentation.
Digital otoscope leads on scale; wireless otoscope leads on momentum.
End User:
Institutional procurement channels dominate volume, though direct-to-consumer channels are expanding with telehealth platform integration.
- Healthcare Professionals:Physicians, nurse practitioners, and physician assistants in outpatient settings require diagnostic-grade optical performance and speculum compatibility across pediatric and adult anatomies. FDA 510(k) clearance status shapes purchasing decisions in US clinic networks.
- Clinics:Federally qualified health centers and urgent care chains standardize on mid-tier digital units with disposable speculum systems to minimize cross-contamination protocols.
- Hospitals:Emergency departments and pediatric wards maintain wired and wireless inventories for bedside examination efficiency.
- Home Care Users:Direct-to-consumer sales concentrate in smartphone-connected variants for parental ear infection monitoring and remote pediatric consultation.
Healthcare professionals lead on scale; home care users lead on momentum.
Application:
Diagnostic reimbursement codes and telehealth parity legislation determine which use cases justify capital expenditure.
- ENT Diagnosis:Otolaryngology practices require 3.5x magnification and pneumatic insufflation capability for differential diagnosis of otitis media and tympanic membrane perforation. German precision optics manufacturers supply premium lens assemblies for this segment.
- Telehealth:Remote diagnostic platforms demand HL7 FHIR connectivity and encrypted image transmission to satisfy HIPAA technical safeguards. Metropolitan health systems in the United States prioritize this specification for virtual visit expansion.
- Patient Monitoring:Home-based otitis media tracking and post-operative tympanostomy tube surveillance drive recurring image capture workflows.
- Education:Medical schools and simulation centers procure video-output units for procedural training and competency assessment.
ENT diagnosis leads on scale; telehealth leads on momentum.
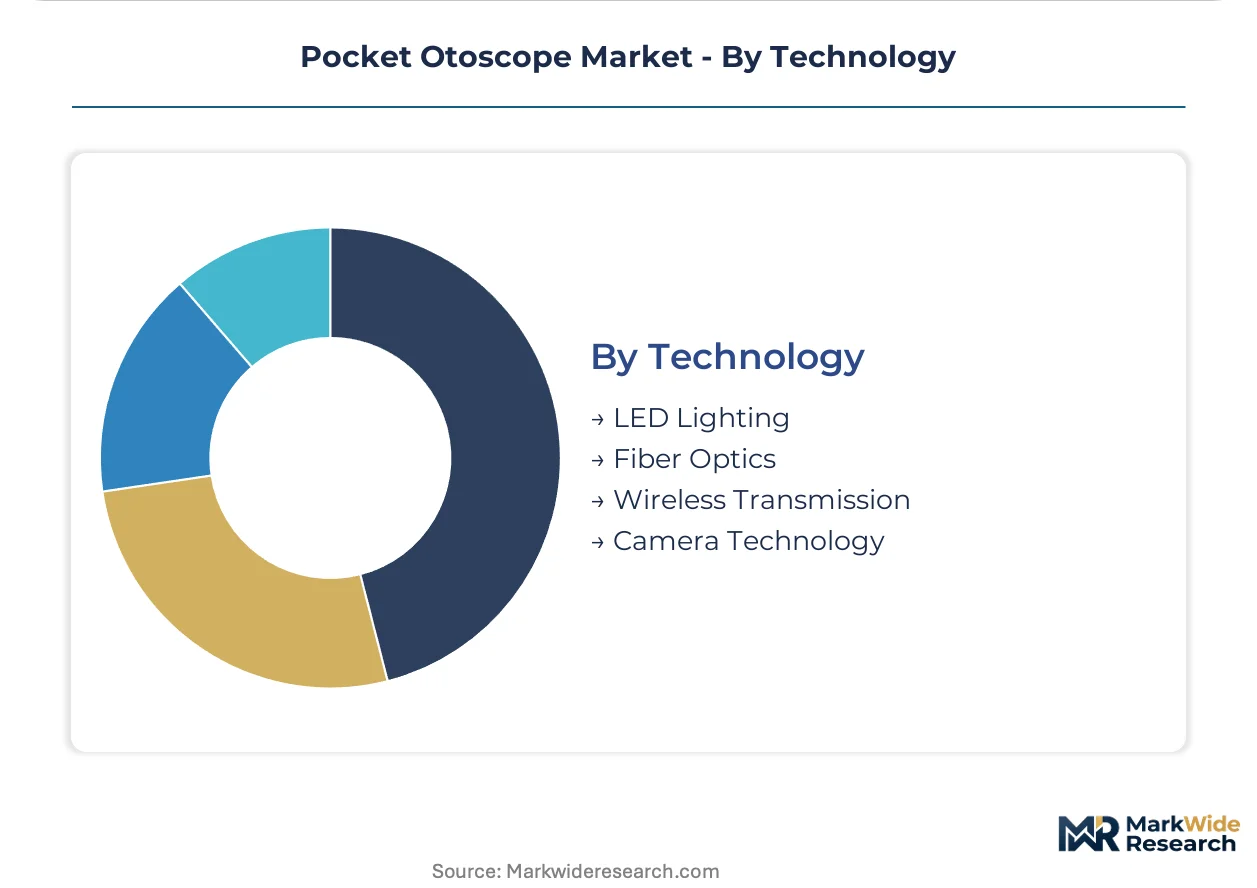
Technology:
Illumination efficiency and data transmission security separate premium tier from commodity positioning.
- LED Lighting:Solid-state modules deliver 50,000-hour operational lifespan with minimal heat generation, eliminating bulb replacement inventory and reducing energy draw in battery-powered instruments. Assembly lines across established manufacturers are retooling from legacy halogen configurations.
- Camera Technology:CMOS and CCD sensors with 720p to 1080p resolution enable diagnostic-grade image capture for electronic health record integration and specialist referral documentation. EU MDR clinical evidence requirements now govern software-as-medical-device classification for AI-enhanced image analysis.
- Fiber Optics:Glass fiber bundles transmit cool illumination in premium manual instruments where color fidelity and durability justify higher unit economics.
- Wireless Transmission:Bluetooth 5.0 and Wi-Fi protocols support real-time consultation and store-and-forward telemedicine architectures.
LED lighting leads on scale; camera technology leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics clusters anchor manufacturing capacity for premium pocket otoscope components. ENT clinic networks across developed economies are standardizing procurement on camera-equipped variants with electronic health record integration.
United States
Telehealth service providers in metropolitan corridors drive procurement acceleration for wireless-enabled diagnostic units. FDA 510(k) clearance pathways compress product development timelines for digital otoscope accessories. Boston and Minneapolis health system procurement functions centralize standardization decisions around HL7 FHIR connectivity specifications.
Germany
ENT clinic fleet expansion concentrates demand for portable diagnostic instruments with pneumatic insufflation capability. EU MDR post-market surveillance obligations intensify clinical evidence requirements for manufacturers distributing within the European Economic Area. Tuttlingen surgical instrument cluster sustains premium manual otoscope production for export markets.
Japan
Ambulatory diagnostic throughput growth in specialized otolaryngology practices supports premium instrument demand. PMDA medical device regulations govern software-as-medical-device classification for AI-enhanced image analysis tools. Tokyo and Osaka metropolitan hospital networks prioritize CMOS sensor-equipped units for specialist consultation workflows.
Brazil
Primary care network expansion under federal health programs generates volume demand for cost-optimized standard otoscope units. ANVISA medical device registration requirements structure market access timelines for imported diagnostic instruments. São Paulo state outpatient clinic networks represent the dominant procurement concentration for portable examination equipment.
United Kingdom
NHS procurement frameworks standardize primary care diagnostic inventories around mid-tier digital otoscope specifications. MHRA post-Brexit medical device regulations maintain alignment with EU MDR clinical evidence standards. London and Manchester health system procurement hubs centralize vendor selection for outpatient clinic networks.
Pocket Otoscope Market Vendor Landscape
Strategic partnerships dominate the current landscape as component suppliers align with distribution channels serving institutional procurement. The vendor base organizes around three tiers: German precision optics specialists, North American institutional channel anchors, and Asian electronics-integrated manufacturers. Two strategic archetypes prevail: heritage instrument makers leveraging optical engineering legacies, and technology-forward entrants exploiting wireless transmission module standardization. Portfolio diversification and geographic expansion represent the dominant competitive moves as manufacturers extend from core ENT instruments into connected diagnostic platforms.
Among heritage German precision instrument fabricators, Heine Optotechnik GmbH and Rudolf Riester GmbH exemplify the premium-tier archetype built on optical engineering lineage. Welch Allyn, Inc. occupies a position as the North American institutional channel anchor. These three companies represent distinct competitive positioning vectors: German precision heritage, modular instrument architecture, and health system procurement integration respectively.
| Leading Market Players |
|---|
| Welch Allyn, Inc. |
| Heine Optotechnik |
| Rudolf Riester GmbH |
| American Diagnostic Corporation |
| SyncVision Technology Corporation |
| Luxamed |
| Olympus Corporation |
| Medline Industries, LP |
| Hill-Rom Holdings |
| Others |
Supply Flow & Price Mechanics
Institutional procurement channels serving North American hospital systems and European ENT clinic networks anchor pricing power for premium pocket otoscope tiers, while cost-optimized variants compete on volume through primary care fleet standardization programs.
Pricing Analysis
Medical-grade polymer feedstock volatility and precision optical component sourcing costs pass through directly to disposable specula and lens assembly pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared digital units with EHR integration from basic LED-illuminated manual instruments. Cost compression in standard otoscope tiers is intensifying because Brazilian and Indian primary care procurement programs prioritize lowest-unit-cost sourcing. Federally qualified health centers exhibit highest price sensitivity; German precision instrument manufacturers serving academic medical centers exhibit lowest.
Supply Chain Analysis
Freight cost fluctuations from German and Japanese optical component hubs to North American assembly facilities compress margin structures for premium instrument manufacturers. Manufacturing concentrates in Germany, Japan, and China, with Tuttlingen precision optics clusters and Shenzhen electronics integration centers serving distinct tier requirements. Supply chains draw from medical-grade polymers, CMOS imaging sensors, and solid-state LED modules. Single-source vulnerability in high-grade lens assemblies from German suppliers creates structural risk. Distribution runs through institutional procurement channels and specialized medical device distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR post-market surveillance obligations and FDA 510(k) pathway compression simultaneously extend certification timelines for entrants while accelerating accessory vendor penetration.
For Market Incumbents: Acquire wireless transmission module capabilities to defend against telehealth-native entrants exploiting connectivity standardization. Consolidate precision optics supply relationships through long-term offtake agreements with Tuttlingen and Tokyo lens fabricators. Deepen backward integration into LED illumination assembly to offset polymer feedstock volatility. For New Entrants and Emerging Players: Enter via smartphone-connected home care variants targeting parental ear infection monitoring workflows in North American direct-to-consumer channels. Brazil's primary care network expansion under federal health programs represents the most penetrable geography. Pursue ANVISA registration partnerships with established Brazilian distributors to compress market access timelines. For Investors and Strategic Acquirers: Health system procurement functions are the most active acquirer in this space, consolidating vendor selection around EHR integration capabilities. Long-term viability hinges on AI-enabled diagnostic algorithm convergence under software-as-medical-device classification frameworks. Target acquisition archetype: wireless-enabled otoscope platforms with HL7 FHIR connectivity and established telehealth platform partnerships. Watch for FDA guidance clarity on AI diagnostic tool classification as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Digital otoscope accessories clear premarket notification faster than full device submissions, accelerating US outpatient clinic procurement cycles. |
| CE Marking Pathway | EU MDR clinical evidence requirements intensify post-market surveillance obligations for manufacturers distributing within European Economic Area member states. |
| Hospital System Partnership | Boston and Minneapolis health system procurement functions centralize standardization decisions around HL7 FHIR connectivity specifications. |
| Software Companion Development | AI-enabled diagnostic algorithm convergence opens regulatory pathways for automated tympanic membrane analysis integrated with EHR workflows. |
| Reimbursement Strategy | Telehealth parity legislation and diagnostic reimbursement codes determine which camera-equipped variants justify capital expenditure in clinic networks. |
Methodological Framework
Direct dialogue with ENT clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative assessment, cross-referenced with FDA 510(k) filings, EU MDR notified body audit records, hospital procurement databases, and CMS Medicare reimbursement data. Secondary validation drew from SEC filings of listed medical device manufacturers and customs records of optical component trade flows. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates.
Segment-level projections across product type, end user, application, and connectivity architecture dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis against ENT clinic fleet expansion rates and telehealth platform procurement velocity. Modeling incorporated PMDA regulatory timeline assumptions for Japanese market entry and ANVISA registration patterns for Brazilian demand.
Inputs from notified body audit records and hospital procurement databases were available through the study window; gaps in real-time telehealth platform procurement data introduce uncertainty bands around wireless otoscope adoption curves. Forecasts reflect documented assumptions regarding regulatory pathway compression and polymer feedstock stability. A model refresh is warranted upon material change in FDA software-as-medical-device classification guidance for AI diagnostic tools.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Neurotechnology Market
Medical Devices
China Ophthalmic Devices Market