
 Global Cardiac Pacemakers Market | 2026-2036
Global Cardiac Pacemakers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Pacemakers Market Foresight
The EU Green Deal is recalibrating medical device supply chains toward lower-carbon manufacturing and extended producer responsibility frameworks. Medtronic leverages its vertically integrated manufacturing footprint to sustain cost advantages across dual-chamber and leadless product lines. Abbott Laboratories differentiates through wireless telemetry platforms that enable remote patient monitoring without clinic visits.
A cardiac pacemaker is an active implantable medical device that generates electrical impulses to regulate abnormal heart rhythms, typically incorporating lithium-iodine batteries with operational lifespans exceeding seven years and hermetically sealed titanium enclosures to ensure biocompatibility. Its primary purpose is to restore adequate cardiac output in patients with bradycardia, atrioventricular block, or heart failure with conduction system disease. Dual chamber systems currently occupy the largest revenue share due to their physiological pacing algorithms, while leadless pacemakers represent the fastest-expanding category by eliminating transvenous lead complications. MRI-compatible technology commands premium positioning as health systems prioritize uninterrupted diagnostic access for aging implant populations.
The FDA enforces rigorous premarket approval pathways under the Code of Federal Regulations for active implantable devices, while the EU Medical Device Regulation mandates unique device identification and enhanced clinical evidence requirements. Japan's PMDA maintains stringent quality management system inspections that shape market entry timelines for foreign manufacturers. Stakeholders must monitor evolving cybersecurity guidance from regulators as wireless connectivity becomes standard in next-generation devices.
Market Dynamics
The cardiac pacemaker market is undergoing structural compression as leadless technology eliminates transvenous lead complications while MRI-compatible systems become non-negotiable for hospital procurement committees managing aging implant populations.
Growth Catalysts
- EU Medical Device Regulation:Enhanced post-market surveillance requirements under MDR are accelerating hospital upgrades to next-generation devices with superior traceability and clinical evidence packages.
- Specialty hospital expansion:Electrophysiology departments in Germany and Japan are adding capacity specifically for leadless and MRI-compatible implant procedures.
- Lithium-iodine battery chemistry:Operational lifespans exceeding seven years are reducing replacement surgery frequency and total cost of ownership for payers.
Market Restraints
- Titanium enclosure costs:Hermetic sealing requirements and biocompatibility-grade titanium sourcing create persistent margin pressure on device manufacturers.
- PMDA inspection timelines:Japan's quality management system audits extend market entry timelines for foreign manufacturers by 18-24 months versus FDA pathways.
- Transcatheter delivery systems:Leadless pacemaker retrieval and revision complexity limits adoption in patient populations with anticipated longevity beyond single-device lifespan.
Strategic Opportunities
- Remote monitoring convergence:Wireless telemetry platforms enabling clinic-free patient surveillance are creating subscription revenue streams alongside hardware sales.
- India's cardiac infrastructure:Underpenetrated electrophysiology capacity in tier-2 cities offers expansion potential as domestic hospital chains build catheterization laboratories.
- EU Green Deal alignment:Extended producer responsibility frameworks reward manufacturers with lower-carbon manufacturing footprints and recyclable battery recovery programs.
Industry Challenges
- Cybersecurity certification:FDA guidance on wireless connectivity security is creating compliance timeline uncertainty as next-generation devices incorporate Bluetooth and cellular modules.
- Electrophysiologist training pipelines:Leadless implant and retrieval procedures require specialized catheter skills that outpace current fellowship program output in most markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Pacemakers Market |
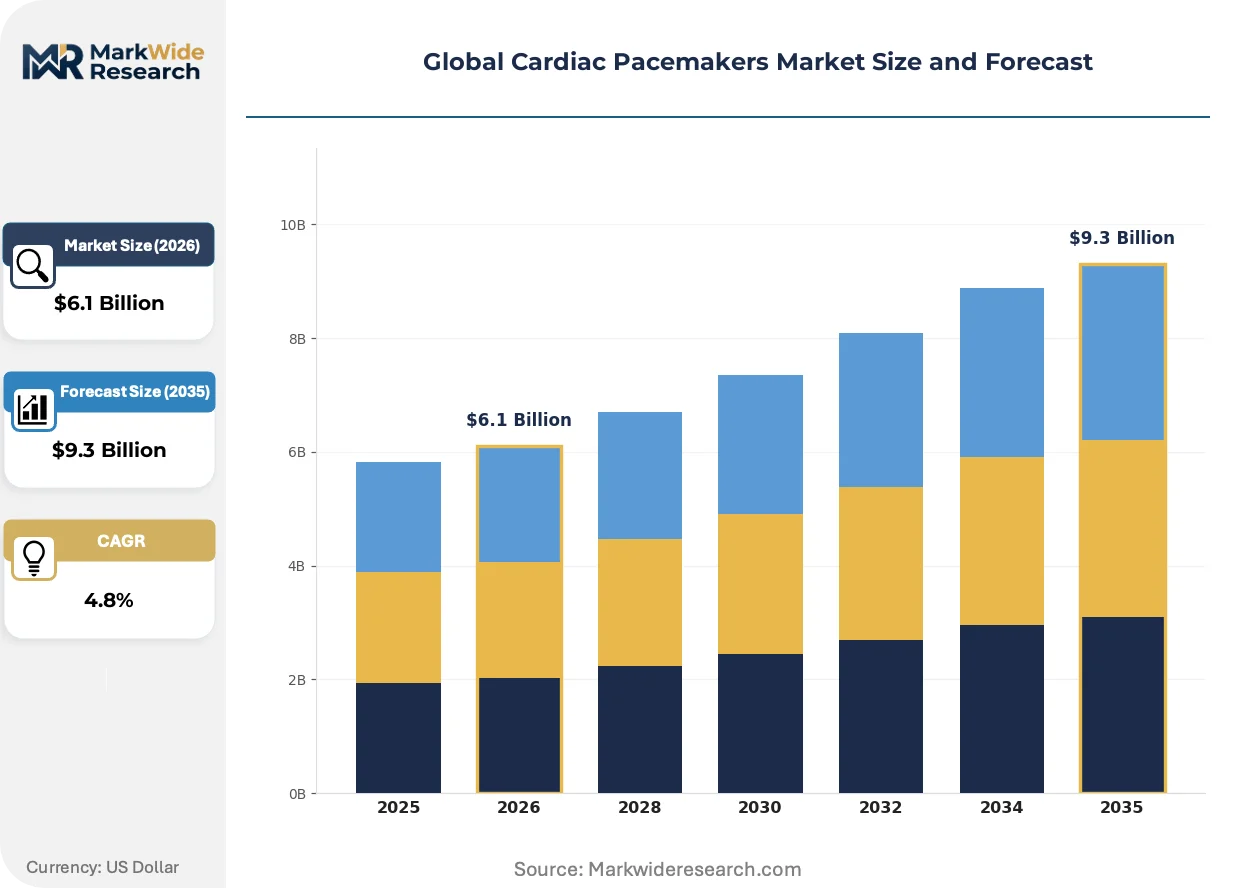
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $9.3 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Dual Chamber, Biventricular, Leadless Technology: MRI Compatible, Rate Responsive, Wireless, Rechargeable Application: Bradycardia Management, Heart Failure Treatment, Arrhythmia Control, Syncope Prevention End User: Cardiology Clinics, Specialty Hospitals, Diagnostic Centers, Academic Medical Centers |
| Companies Covered | BIOTRONIK SE & Co. KG, LivaNova PLC, Medtronic, ZOLL Medical Corporation, MicroPort Scientific Corporation, Abbott Laboratories, Lepu Medical Technology, Japan Lifeline Co. Ltd., Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Pacemakers Market Shifts & Advancements
Cardiac rhythm management is pivoting toward seamless diagnostic compatibility and decentralized patient surveillance, with hardware miniaturization and connectivity standards converging to redefine post-implant care economics.
Leadless pacemaker technology is integrating multi-chamber synchronization capabilities through wireless communication between separate implant units. Electrophysiology departments in the United States and Western Europe are prioritizing these systems for patients with lead-related complications or vascular access limitations. This convergence is compressing the addressable market for traditional transvenous systems while expanding procedural candidacy to populations previously excluded.
REACH and RoHS compliance requirements in Europe are forcing reformulation of solder materials and battery chemistries to eliminate restricted substances. Device manufacturers are requalifying supply chains and resubmitting technical documentation to notified bodies. Dual-chamber and leadless product lines face the steepest revalidation burden due to their higher material complexity and longer regulatory histories.
Hospital purchasing committees are unbundling device procurement from long-term remote monitoring contracts, creating separate vendor selection processes for hardware and surveillance services. Cardiology service lines in Germany and Japan are leading this bifurcation, negotiating direct telemetry platform agreements independent of implant manufacturer relationships. This shift is fragmenting vendor lock-in and elevating interoperability as a decisive procurement criterion.
Global Cardiac Pacemakers Market Segmentation
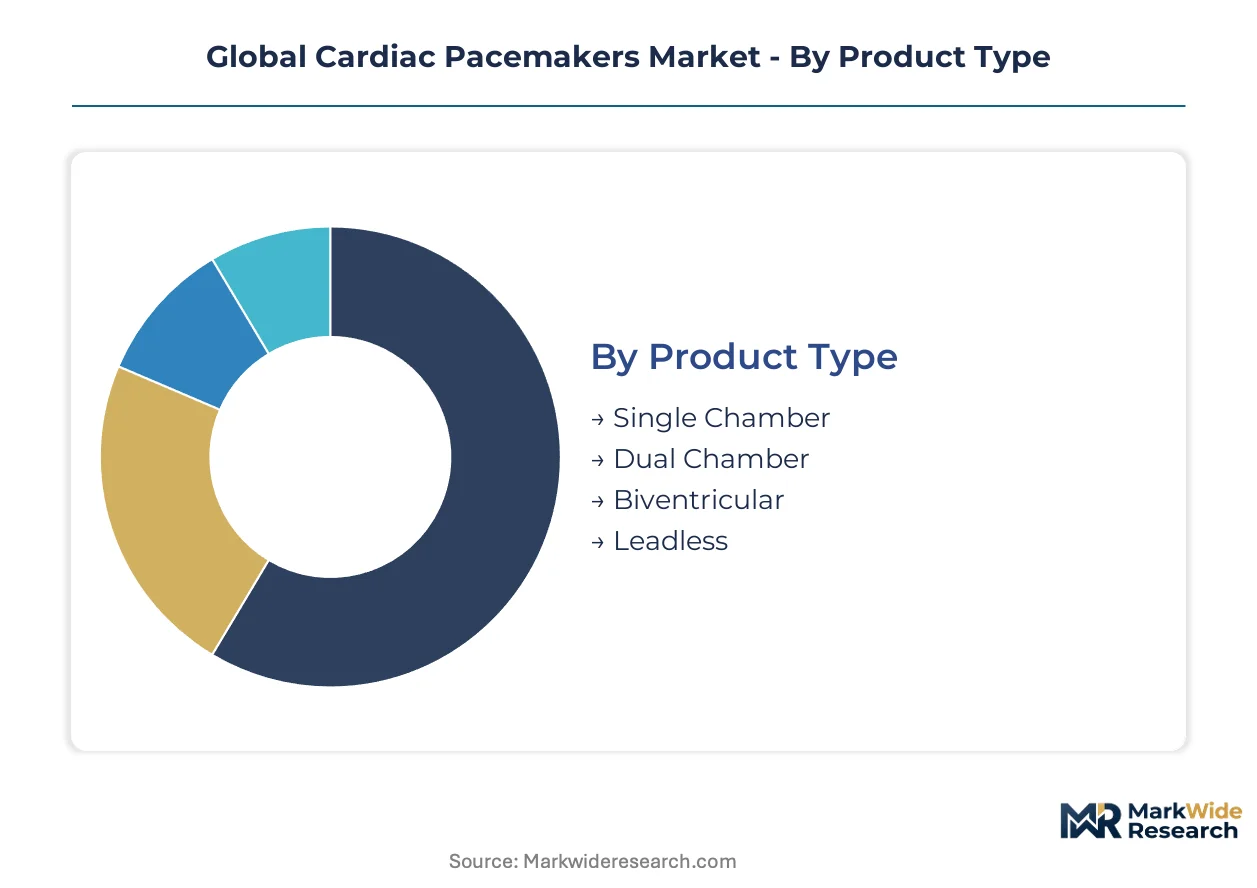
Cardiac pacemaker purchasing decisions split sharply between volume-driven standard systems and premium-positioned advanced technologies. Procurement committees weight physiological sophistication against total cost of ownership across replacement cycles. Segment boundaries are blurring as leadless devices absorb dual-chamber functionality and MRI compatibility becomes baseline rather than premium.
Product Type:
Volume concentration sits with established transvenous systems, while premium capture belongs to leadless platforms eliminating lead complications.
- Dual Chamber:Physiological pacing algorithms synchronize atrial and ventricular contraction through separate leads. Demand concentrates in United States Medicare populations where reimbursement pathways favor proven longevity data. Hospital procurement committees treat these as the default for patients without vascular access limitations.
- Leadless:Miniaturized units deploy directly into the right ventricle via femoral catheter, eliminating lead fracture and extraction risks. Specialty hospitals in Germany and Japan are expanding electrophysiology capacity specifically for these implants. Retrieval complexity for device revision limits candidacy in younger patients.
- Single Chamber:Simplified ventricular-only pacing for chronic atrial fibrillation with slow ventricular response.
- Biventricular:Cardiac resynchronization therapy coordinating both ventricles for heart failure with reduced ejection fraction.
Today's leader: Dual Chamber. Tomorrow's challenger: Leadless.
Technology:
Application context determines technology stacking — diagnostic access requirements and connectivity infrastructure shape bundling decisions.
- MRI Compatible:Ferromagnetic shielding and filtered circuitry permit full-body magnetic resonance imaging without device deactivation. Aging implant populations in United States and Western Europe drive non-negotiable procurement status. FDA premarket approval pathways enforce rigorous electromagnetic compatibility testing.
- Wireless:Bluetooth and cellular telemetry enable remote monitoring without clinic visits. Germany's cardiology service lines negotiate telemetry contracts independent of hardware vendors. Cybersecurity certification timelines create compliance uncertainty as connectivity modules proliferate.
- Rate Responsive:Accelerometer or minute-ventilation sensors adjust pacing rate to metabolic demand.
- Rechargeable:Transcutaneous energy transfer extends operational lifespan for pediatric and young adult populations.
Current procurement baseline: MRI Compatible. Emerging differentiator: Wireless.
Application:
Clinical indication severity correlates with reimbursement intensity and device sophistication requirements.
- Bradycardia Management:Primary indication for permanent pacing in sinus node dysfunction and atrioventricular block. United States Medicare pathways standardize coverage for symptomatic bradycardia. Dual-chamber systems dominate this segment due to physiological pacing benefits.
- Heart Failure Treatment:Cardiac resynchronization therapy requires biventricular pacing with specialized lead placement. Academic medical centers in Japan concentrate implant volume for complex heart failure cases. Device longevity reduces replacement surgical risk in frail populations.
- Arrhythmia Control:Pacing algorithms preventing atrial fibrillation or terminating tachyarrhythmias.
- Syncope Prevention:Rate-drop response and closed-loop stimulation for vasovagal and carotid sinus syndromes.
Volume anchor: Bradycardia Management. Complexity premium: Heart Failure Treatment.
End User:
Facility type determines case mix complexity and procurement negotiation leverage.
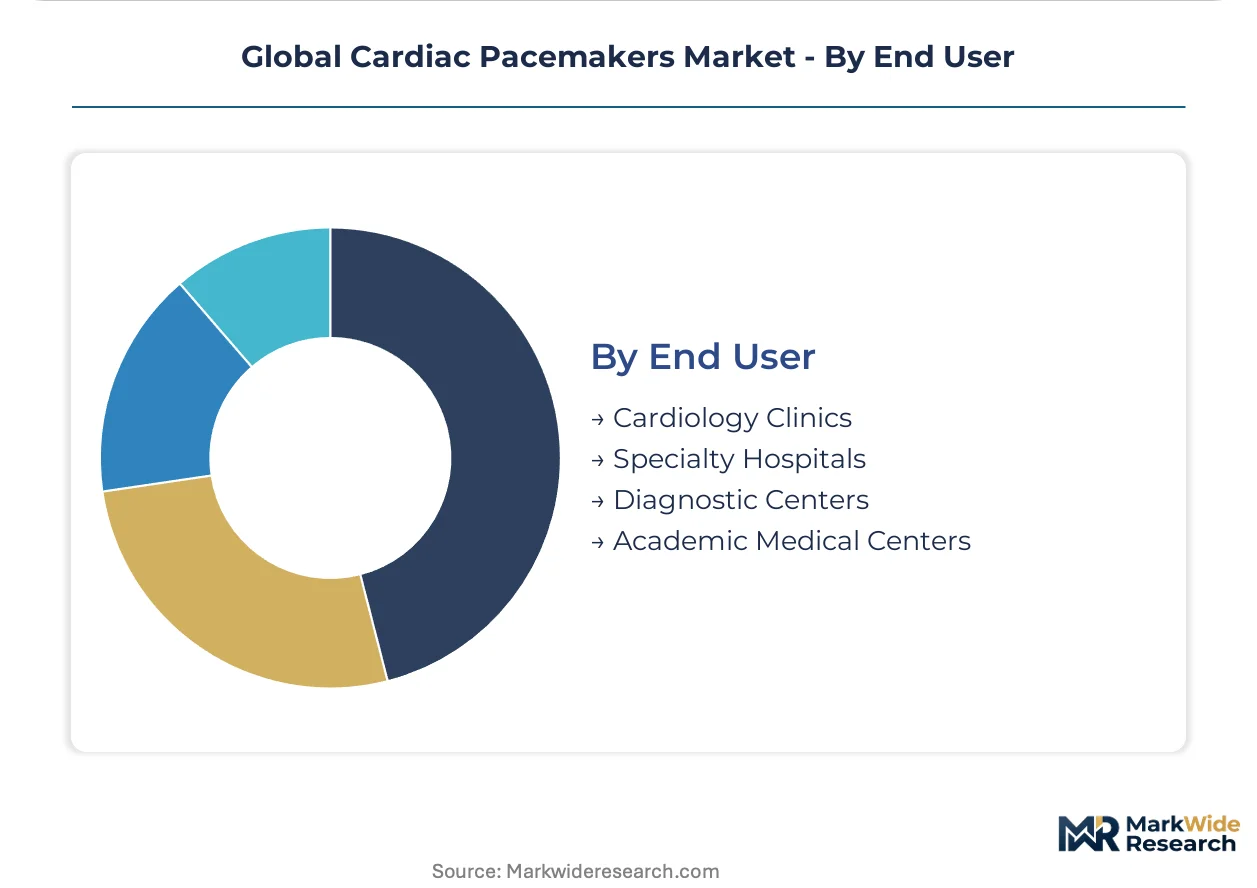
- Specialty Hospitals:Dedicated electrophysiology departments handle high-volume implant and revision procedures. Germany's specialty hospitals are adding capacity for leadless and MRI-compatible systems. EU Medical Device Regulation post-market surveillance requirements accelerate upgrade cycles.
- Academic Medical Centers:Training programs and research protocols drive early adoption of next-generation technologies. Japan's PMDA inspection timelines shape foreign manufacturer market entry strategies through these sites. Complex retrieval procedures concentrate at tertiary referral centers.
- Cardiology Clinics:Outpatient follow-up and remote monitoring management for stable implant patients.
- Diagnostic Centers:Pre-implant electrophysiology studies and post-implant device interrogation services.
Procedure volume leader: Specialty Hospitals. Innovation access point: Academic Medical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiologist density and specialized catheterization laboratory networks determine regional pacemaker implant volumes. Germany and the United States concentrate the highest per-capita specialist counts. Japan's aging demographics and PMDA regulatory pathways create distinct market entry dynamics for foreign manufacturers.
United States
Medicare reimbursement pathways for leadless and MRI-compatible systems drive hospital procurement standardization. FDA premarket approval pathways enforce rigorous electromagnetic compatibility testing for wireless telemetry modules. Academic medical centers in Boston and Cleveland anchor complex retrieval procedure training for next-generation device platforms.
Germany
Specialty hospital electrophysiology departments in Munich and Heidelberg are expanding capacity specifically for leadless implant procedures. EU Medical Device Regulation post-market surveillance requirements accelerate device upgrade cycles across statutory health insurance networks. REACH and RoHS compliance mandates force reformulation of solder materials and battery chemistries in domestic manufacturing.
Japan
PMDA quality management system inspections extend foreign manufacturer market entry timelines by 18-24 months versus FDA pathways. METI industrial policy supports domestic cardiac rhythm management device production through targeted procurement preferences. Tokyo and Osaka metropolitan areas concentrate implant volume for complex heart failure resynchronization cases.
India
Underpenetrated electrophysiology capacity in tier-2 cities offers expansion potential as domestic hospital chains build catheterization laboratories. CDSCO medical device registration pathways are streamlining for active implantable devices under revised 2017 rules. Maharashtra and Karnataka state health systems are prioritizing cardiac device procurement in public-private partnership hospital networks.
China
NMPA innovative medical device approval pathways are accelerating for leadless pacemaker platforms with domestic clinical trial data. MIIT industrial policy targets cardiac rhythm management technology in strategic emerging industry catalogs. Shanghai and Beijing municipal health commissions are standardizing MRI-compatible device procurement across tertiary hospital networks.
Global Cardiac Pacemakers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cardiac pacemaker landscape. Vertically integrated manufacturers with captive battery and enclosure supply chains sustain cost advantages across dual-chamber and leadless product lines. Three strategic archetypes dominate: diversified medical technology conglomerates with rhythm management divisions, pure-play cardiac device specialists, and emerging Asia-Pacific manufacturers leveraging domestic market scale. Competitive moves center on wireless telemetry platform development and electrophysiology service line partnerships.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories occupy positions exemplifying vertically integrated manufacturing footprints and wireless telemetry platform differentiation. Boston Scientific Corporation and BIOTRONIK SE & Co. KG represent pure-play cardiac rhythm management specialists with concentrated electrophysiology portfolios. MicroPort Scientific Corporation and Lepu Medical Technology anchor the Asia-Pacific manufacturer archetype, leveraging domestic regulatory pathways and hospital network relationships in China.
| Leading Market Players |
|---|
| BIOTRONIK SE & Co. KG |
| LivaNova PLC |
| Medtronic |
| ZOLL Medical Corporation |
| MicroPort Scientific Corporation |
| Abbott Laboratories |
| Lepu Medical Technology |
| Japan Lifeline Co. Ltd. |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between MRI-compatible premium systems and standard dual-chamber devices manifests in divergent supply chain sourcing and procurement negotiation leverage across hospital purchasing committees. Germany's statutory health insurance networks and United States Medicare pathways enforce distinct reimbursement ceilings that reshape manufacturer margin structures and raw material grade selections.
Pricing Analysis
Bundled hardware-plus-telemetry contracts are unbundling into separate procurement streams across Germany's cardiology service lines and Japanese specialty hospitals. Price differentiation rests on electromagnetic compatibility certification tier and wireless connectivity module sophistication, with MRI-compatible systems commanding substantial premiums over baseline dual-chamber alternatives. Pricing pressure stems from lithium-iodine battery chemistry standardization reducing replacement cycle frequency. Academic medical centers exhibit lowest price sensitivity due to research protocol requirements, while tier-2 hospital networks in India demonstrate acute cost consciousness.
Supply Chain Analysis
Single-source vulnerability sits with biocompatibility-grade titanium enclosure suppliers concentrated in Switzerland and Germany. Device manufacturing draws from lithium-iodine cell production anchored in Japan and the United States, with hermetic sealing equipment sourced from specialized German precision engineering firms. Tariff exposure on titanium raw materials creates margin volatility for manufacturers without captive smelting arrangements. Distribution runs through regional cardiac rhythm management distributors holding consignment inventory at major electrophysiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's PMDA inspection timelines extend market entry by 18-24 months versus FDA pathways, creating cost arbitrage opportunities for manufacturers prioritizing United States commercialization before addressing Japanese statutory health insurance procurement.
For Market Incumbents: To counter leadless pacemaker technology compressing transvenous system addressable markets, Medtronic and Abbott Laboratories should deepen backward integration into lithium-iodine battery cell production and secure long-term titanium supply agreements with Swiss metallurgical specialists. Wireless telemetry platform standardization represents the critical defensive lever against hardware commoditization. For New Entrants and Emerging Players: CDSCO streamlined registration pathways under India's 2017 medical device rules open a window for tier-2 city electrophysiology capacity expansion through domestic hospital chain partnerships. Maharashtra and Karnataka public-private partnership networks offer the most penetrable hospital procurement entry points. Leadless implant retrieval training partnerships with academic medical centers provide essential credibility for complex procedure candidacy. For Investors and Strategic Acquirers: Consolidation pressure builds where wireless telemetry platform development costs outpace standalone cardiac rhythm management specialist revenue bases. Long-term viability favors diversified medical technology conglomerates with rhythm management divisions over pure-play specialists lacking subscription revenue diversification. Watch FDA cybersecurity guidance finalization as inflection indicator for compliance cost escalation and acquisition target distress.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance requirements accelerate device upgrade cycles across statutory health insurance networks. |
| Hospital System Partnership | Germany's specialty hospitals negotiate telemetry contracts independent of hardware vendor relationships. |
| Software Companion Development | Bluetooth and cellular telemetry modules enable clinic-free patient surveillance creating subscription revenue streams. |
| Reimbursement Strategy | United States Medicare pathways for leadless and MRI-compatible systems drive hospital procurement standardization. |
| Backward Integration | Captive lithium-iodine battery production sustains cost advantages across dual-chamber and leadless product lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining electrophysiologist interviews, hospital purchasing committee discussions, and biomedical engineer consultations with secondary validation against FDA premarket approval databases, EU MDR notified body technical documentation, and CMS Medicare reimbursement pathway records. Bottom-up implant volume modeling and top-down market sizing triangulated across product type, technology stack, clinical indication, and end-user facility categories.
Segment-weighting approaches applied differential growth assumptions across leadless versus transvenous system trajectories and MRI-compatible versus standard technology penetration curves throughout the projection horizon. CAGRs derived from logistic diffusion modeling of leadless adoption S-curves and replacement cycle compression effects. Forecast inputs incorporated electrophysiologist training pipeline output constraints and PMDA inspection timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Green Deal carbon border adjustment implementation and lithium raw material export restriction scenarios. Forecasts reflect documented assumptions regarding leadless retrieval procedure learning curve progression and wireless connectivity cybersecurity certification timeline resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Liver-On-Chip Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Intracranial Stents Total Addressable Market