
 Wearable Computing Devices Market | 2026-2036
Wearable Computing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Computing Devices Market Intelligence
Asian contract manufacturers is hardening as the dominant production base for sensor modules and display assemblies. Apple Inc. leverages vertical integration across silicon design and operating systems to sustain premium positioning. Samsung Electronics Co. Ltd. anchors its portfolio through in-house display and semiconductor capabilities across multiple wearable form factors. Garmin Ltd. specializes in GPS-differentiated devices for outdoor and aviation segments where accuracy commands loyalty.
Wearable computing devices integrate microprocessors, biosensors, wireless transceivers, and power management circuits into body-worn form factors, typically operating on sub-1-watt budgets with continuous Bluetooth Low Energy connectivity for data relay to smartphones or cloud platforms. Their primary purpose spans real-time physiological monitoring, geolocation services, and hands-free information access across consumer, medical, and industrial contexts. Smartwatches dominate current revenue pools as multipurpose platforms, while smart eyewear represents the fastest-expanding frontier where optical waveguide and micro-LED innovations are reducing unit weight below 80 grams. Fitness trackers occupy a mature volume tier with compressed margins, whereas health monitoring applications command premium pricing through regulatory-grade sensor certification and clinical workflow integration.
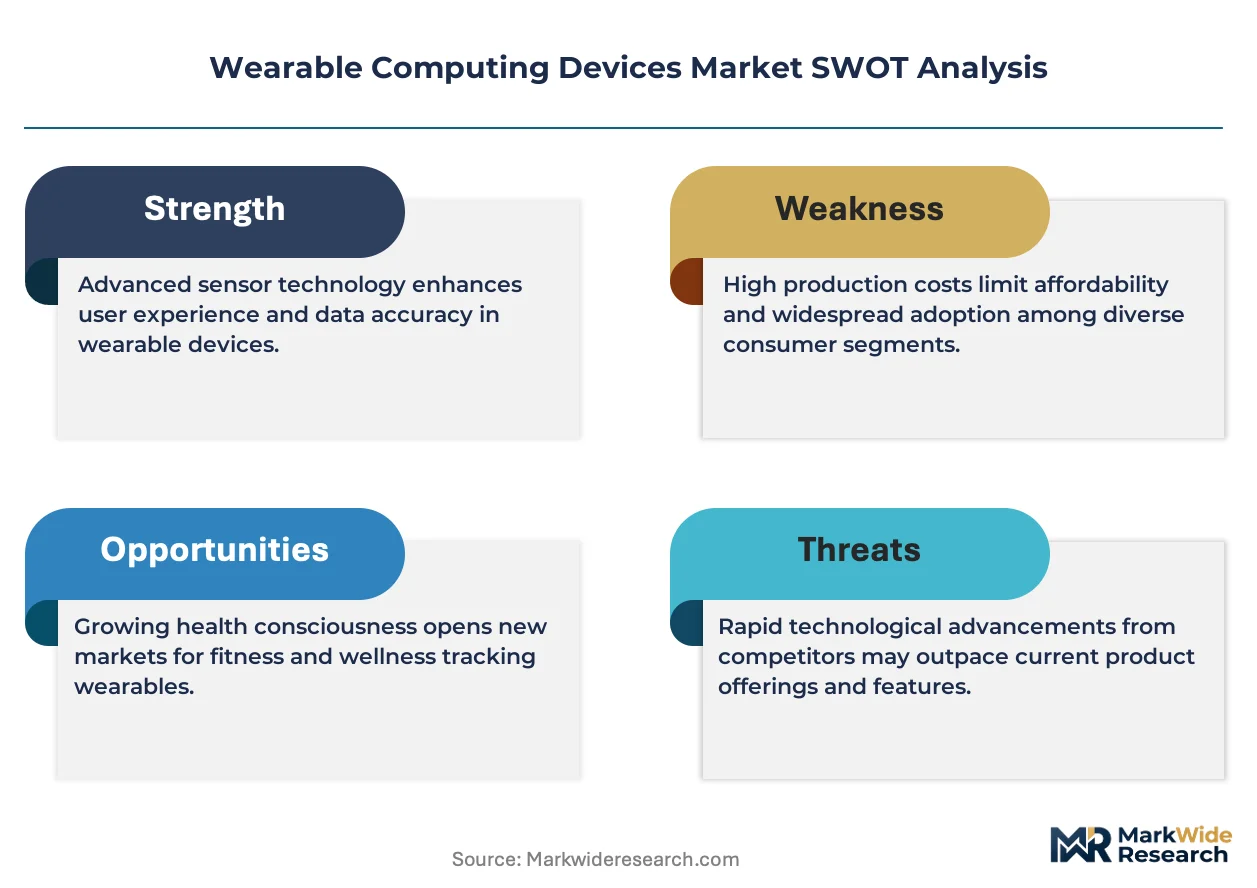
FDA 510(k) clearance requirements shape product development timelines and clinical validation costs for health-focused entrants in the United States. EMA Medical Device Regulation and EU AI Act compliance in Europe impose additional algorithm transparency and post-market surveillance obligations on predictive health analytics features. China's NMPA and GB standards mandate electromagnetic compatibility and battery safety testing for domestic sale. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of go-to-market sequencing and R&D allocation.
Market Dynamics
Bluetooth Low Energy and ultra-wideband protocols are compressing power budgets below 1 watt, forcing component suppliers to redesign sensor architectures around continuous physiological monitoring demands.
Growth Catalysts
- FDA 510(k) Clearance Pathway:Streamlined premarket notification for Class II medical wearables accelerates clinical validation timelines for continuous glucose monitors and cardiac event detectors in the United States.
- Optical Waveguide Miniaturization:Micro-LED and diffractive optics integration is reducing smart eyewear mass below 80 grams, unlocking enterprise augmented reality deployments in manufacturing and field service.
- China NMPA Electromagnetic Compatibility Mandates:Domestic GB standards testing requirements for battery safety and RF emissions are standardizing component sourcing for brands targeting the Chinese consumer base.
Market Restraints
- Lithium-Polymer Cell Cost Volatility:Cobalt and lithium carbonate price swings from Democratic Republic of Congo and Chilean supply corridors compress margins on sub-$200 fitness trackers.
- Taiwan Semiconductor Foundry Concentration:Advanced node fabrication for biometric sensor ASICs depends on TSMC capacity allocation, creating 26-week lead time exposure for wearable OEMs.
- EU AI Act Algorithm Transparency Requirements:Post-market surveillance obligations for predictive health analytics features impose documentation burdens that delay European launches by 8-14 months.
Strategic Opportunities
- India PLI Scheme for Electronics Manufacturing:Production-linked incentives for semiconductor assembly and testing are attracting wearable brands to establish Bengaluru and Chennai production hubs.
- Remote Patient Monitoring Reimbursement Codes:CMS CPT billing codes for chronic care management create payment pathways for FDA-cleared wearables in Medicare populations.
- Ultra-Wideband and Radar Sensor Fusion:Converging spatial awareness and vital sign detection enables contactless fall detection and sleep apnea screening without wrist-worn form factors.
Industry Challenges
- Biomedical Algorithm Validation Talent Scarcity:FDA predicate device equivalence studies require clinical data scientists with ISO 14155 trial design expertise, a skill set concentrated at ten contract research organizations.
- Multi-Jurisdiction Certification Parallel Processing:Simultaneous FDA 510(k), EMA MDR, and NMPA submissions demand redundant clinical evidence packages that strain early-stage R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Computing Devices Market |
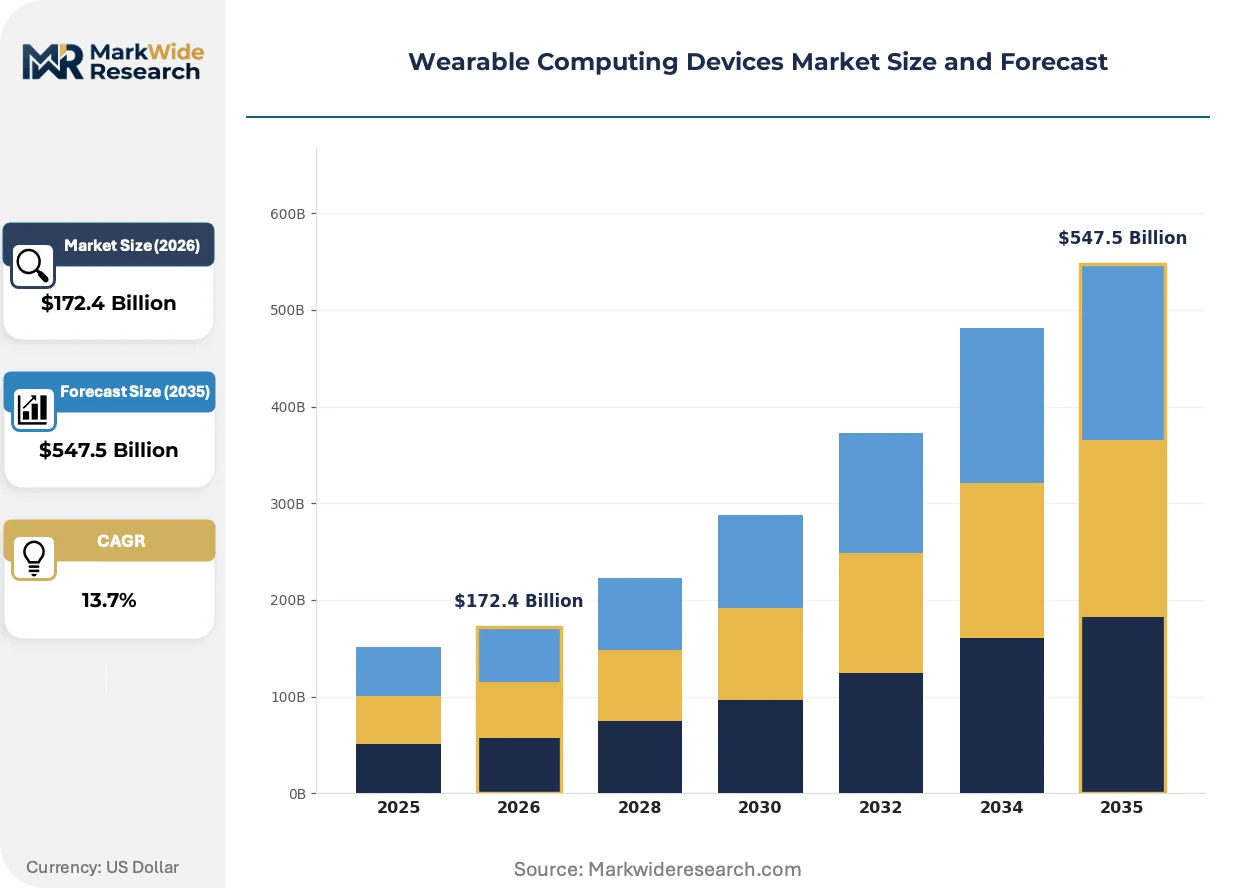
| Market Size in 2026 | $172.4 Billion |
| Market Size in 2035 | $547.5 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Eyewear, Smart Clothing Technology: Bluetooth, Wi-Fi, NFC, RFID End User: Individuals, Healthcare Professionals, Fitness Enthusiasts, Corporate Users Application: Health Monitoring, Fitness Tracking, Navigation, Communication |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Garmin Ltd., Huawei Technologies Co. Ltd., Xiaomi Corp., Fossil Group Inc., Sony Corp., Alphabet Inc., Fitbit LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Computing Devices Market Strategic Shifts & Innovations
Edge AI inference engines are migrating from smartphones onto wearable silicon, enabling real-time anomaly detection without cloud latency. This architectural shift redefines competitive advantage around on-device processing efficiency.
Photoplethysmography sensor arrays with green and infrared LED multiplexing are decentralizing heart rate variability monitoring from clinical Holter systems to consumer wristbands. Marathon training programs and corporate wellness administrators are adopting these devices for recovery metrics. The technology is decentralizing cardiovascular data ownership toward individual users and their designated coaches.
EMA Medical Device Regulation post-market surveillance requirements are mandating algorithm performance dashboards for AI-enabled wearables sold in Europe. Manufacturers must submit annual safety reports and update clinical evidence for software-as-a-medical-device classifications. Cardiac arrhythmia detection features face the steepest compliance burdens, with several vendors withdrawing non-critical algorithms from EU markets.
Direct-to-employer contracting is replacing retail channel dependence for clinical-grade wearables. Self-insured corporations in the United States are negotiating volume agreements for diabetes prevention and hypertension management programs. This bypasses traditional distributor markups and aligns device procurement with health outcome guarantees.
Wearable Computing Devices Market Segmentation
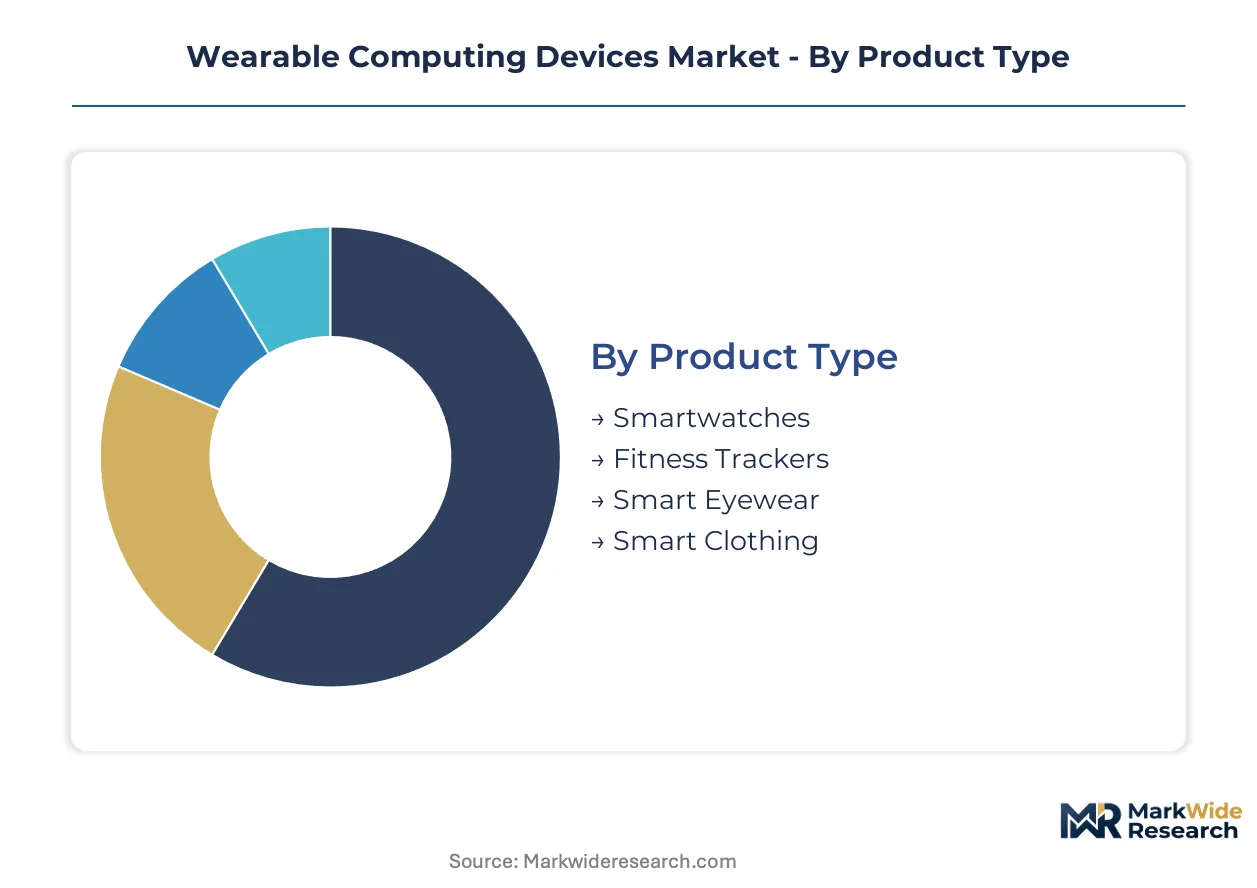
Wearable computing devices fragment across four critical dimensions: product form factor, wireless protocol, user archetype, and functional application. These segment boundaries determine pricing power, regulatory pathway, and component sourcing strategy for manufacturers.
Product Type:
Integration depth varies sharply—smartwatches and fitness trackers operate as standalone ecosystems, while smart eyewear and smart clothing embed into broader enterprise or industrial systems.
- Smartwatches:Multipurpose platforms combining microprocessors, biosensors, and AMOLED displays in wrist-worn form factors. Demand concentrates among healthcare professionals in the United States seeking FDA 510(k) cleared cardiac monitoring capabilities for remote patient management.
- Smart Eyewear:Optical waveguide and micro-LED architectures reduce unit mass below 80 grams, enabling hands-free augmented reality. German automotive manufacturers and Chinese logistics operators drive enterprise procurement for assembly-line guidance and warehouse picking applications.
- Fitness Trackers:Stripped-down sensor arrays prioritize step counting and sleep staging at sub-$100 price points. Indian corporate wellness programs and US marathon training collectives represent volume purchasers.
- Smart Clothing:Conductive thread and textile-integrated electrodes enable full-body biomechanical capture. Professional sports franchises in Germany and rehabilitation clinics in China adopt these for movement analysis without joint-mounted hardware.
Volume placements concentrate in smartwatches; the faster expansion belongs to smart eyewear.
Technology:
Protocol selection determines power budget, data throughput, and interoperability with existing smartphone infrastructure across consumer and medical deployments.
- Bluetooth:Bluetooth Low Energy dominates continuous physiological monitoring with sub-1-watt power envelopes. FDA-cleared glucose monitors and cardiac event detectors in the United States rely on this protocol for smartphone relay.
- Wi-Fi:Higher throughput enables direct cloud synchronization without smartphone intermediation. Hospital IT departments in Germany prefer Wi-Fi for inpatient telemetry systems requiring real-time central station visibility.
- NFC:Near-field protocols support contactless payment and access control use cases. Chinese transit authorities and Japanese payment networks have standardized NFC for wearable wallet functionality.
- RFID:Passive and active radio-frequency identification enables inventory tracking and personnel location in industrial settings. German manufacturing plants deploy RFID-enabled wearables for tool tracking and zone-based safety compliance.
Bluetooth captures the highest shipment volumes; Wi-Fi is climbing the fastest in clinical-grade deployments.
End User:
User archetype determines pricing tolerance, feature requirements, and channel strategy—from retail consumer to institutional procurement.
- Individuals:Consumer purchasers prioritize aesthetics and smartphone ecosystem compatibility. Chinese and US retail channels move the highest absolute units through electronics superstores and direct-to-consumer online platforms.
- Healthcare Professionals:Physicians, nurses, and remote monitoring technicians demand regulatory-grade sensor accuracy. US Medicare reimbursement codes for chronic care management create institutional procurement pathways.
- Fitness Enthusiasts:Amateur and semi-professional athletes track training load and recovery metrics. Marathon collectives in Germany and triathlon clubs in the United States drive replacement cycles for GPS-accurate devices.
- Corporate Users:Self-insured employers and industrial safety managers procure at volume. Direct-to-employer contracting in the United States bypasses retail markups for diabetes prevention program deployments.
Individual consumers dominate absolute volumes; healthcare professionals command the steepest pricing premiums.
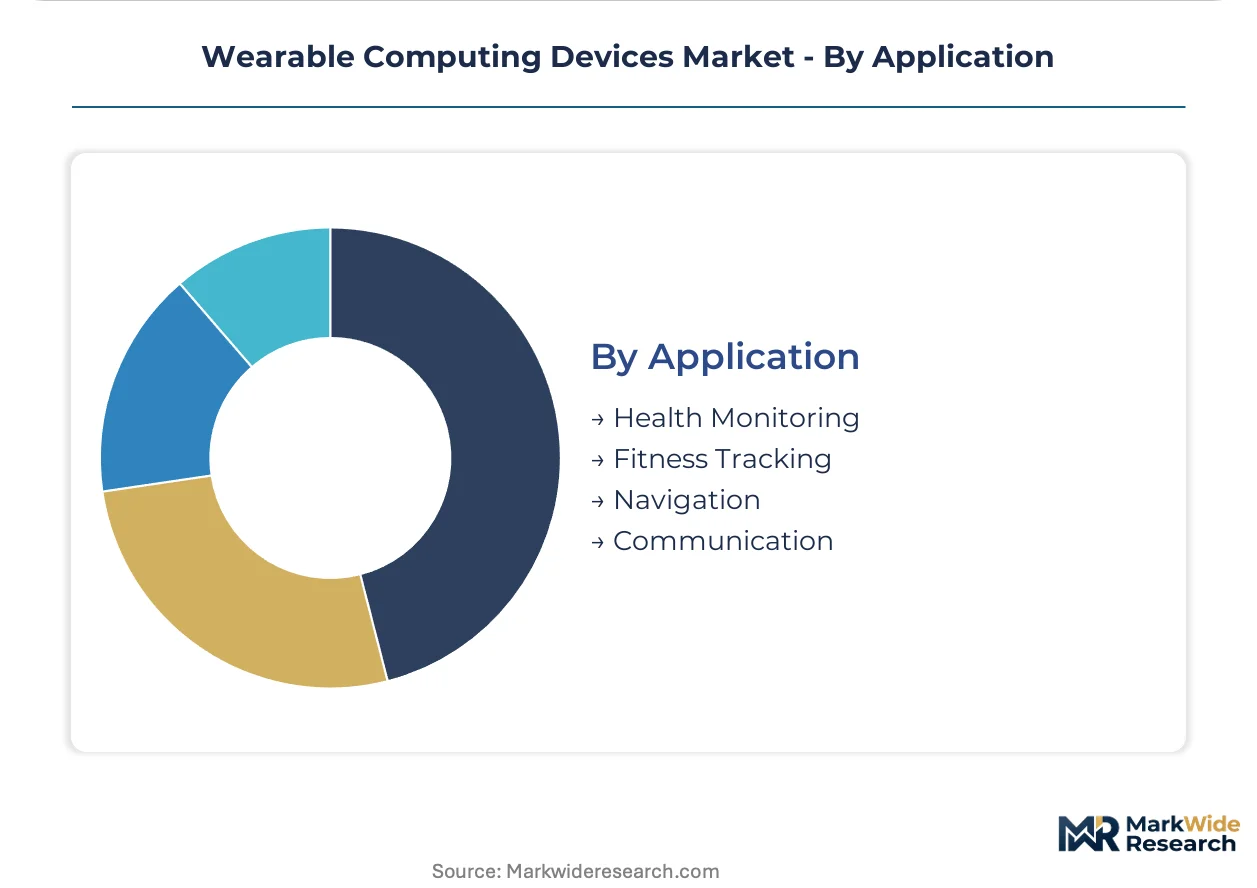
Application:
Functional use case determines sensor configuration, algorithm complexity, and regulatory classification burden for manufacturers.
- Health Monitoring:Continuous glucose, cardiac arrhythmia, and blood oxygen detection require FDA 510(k) or EMA MDR clearance. US remote patient monitoring reimbursement codes and EU AI Act algorithm transparency obligations shape product development timelines.
- Fitness Tracking:Step counting, calorie estimation, and sleep staging operate under lighter regulatory scrutiny. Chinese fitness app ecosystems and US corporate wellness administrators drive feature standardization.
- Navigation:GPS-differentiated positioning serves outdoor recreation and aviation segments. German hiking associations and US general aviation pilots demand sub-meter accuracy for safety-critical routing.
- Communication:Hands-free calling, messaging, and voice assistant access integrate with smartphone notification pipelines. Chinese and US consumer bases prioritize seamless ecosystem connectivity.
Fitness tracking holds the broadest installed base; health monitoring carries the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate from Chilean salt flats and cobalt from the Democratic Republic of Congo feed battery supply chains that concentrate final assembly in East Asian manufacturing corridors. Device demand clusters where healthcare reimbursement codes, consumer purchasing power, and industrial automation investments intersect.
United States
Medicare remote patient monitoring reimbursement codes drive institutional procurement of FDA 510(k) cleared cardiac wearables. The FDA maintains stringent predicate device equivalence requirements for glucose monitors and arrhythmia detectors. Austin and Boston host clusters of digital health startups integrating wearable data into electronic health record workflows.
China
Domestic brands command consumer loyalty through ecosystem integration with super-app platforms. NMPA electromagnetic compatibility testing and GB standards battery safety mandates standardize component sourcing. Shenzhen and Dongguan manufacturing hubs produce sensor modules and display assemblies for global brands.
Germany
Automotive manufacturers procure smart eyewear for assembly-line augmented reality guidance. EMA Medical Device Regulation post-market surveillance obligations impose algorithm transparency requirements on predictive health features. Munich and Stuttgart anchor industrial wearable deployments in precision manufacturing and logistics operations.
India
Corporate wellness programs and marathon training collectives drive fitness tracker volume at sub-$100 price points. PLI scheme production-linked incentives attract semiconductor assembly and testing investment to Bengaluru and Chennai. CDSCO medical device rules are tightening for imported health monitoring wearables.
Japan
Aging demographics accelerate demand for fall detection and medication adherence wearables. METI standards guide interoperability between consumer devices and hospital information systems. Tokyo and Osaka metropolitan areas concentrate telemedicine platform integration with wrist-worn physiological monitors.
Wearable Computing Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized health monitoring niches and enterprise augmented reality applications. The vendor base stratifies across three tiers: integrated technology conglomerates with captive silicon and display capabilities; specialized positioning and fitness brands with GPS-differentiated portfolios; and contract manufacturing-dependent challengers competing on price. Dominant competitive moves include backward integration into sensor ASIC design and strategic partnerships with healthcare systems for clinical validation.
Among technology conglomerates with vertical silicon control, Apple Inc. and Samsung Electronics Co. Ltd. exemplify the premium-tier archetype through in-house semiconductor and display capabilities. Garmin Ltd. occupies a specialist position in GPS-differentiated outdoor and aviation segments where positional accuracy commands user loyalty. These three anchors represent distinct competitive vectors: ecosystem lock-in, component integration depth, and vertical specialization.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Garmin Ltd. |
| Huawei Technologies Co. Ltd. |
| Xiaomi Corp. |
| Fossil Group Inc. |
| Sony Corp. |
| Alphabet Inc. |
| Fitbit LLC |
| Others |
Cost & Logistics Intelligence
Biomedical algorithm validation talent concentration in Boston and Austin labor pools widens pricing-tier spreads, as FDA 510(k) predicate device equivalence expertise commands premium compensation that health-monitoring OEMs pass through to institutional buyers while fitness tracker producers absorb margin compression.
Pricing Analysis
Warranty and clinical validation service bundling separates premium health-monitoring wearables from unbundled fitness trackers. Three-tier pricing structure across premium, standard, and economy levels tracks FDA certification grade and volume procurement scale. Pricing pressure stems from lithium-polymer cell cost volatility in sub-$100 fitness tiers. Corporate wellness administrators exhibit highest price sensitivity; Medicare reimbursement pathways shield healthcare professional segments.
Supply Chain Analysis
Dual-sourcing mandates from Apple and Samsung OEMs require TSMC and Samsung Foundry qualification for biometric sensor ASICs simultaneously. Component flows draw from Taiwan for advanced node fabrication, China for display assemblies and battery cells, and Vietnam for final device integration. Cobalt and lithium carbonate dependencies tether margins to Chilean and DRC supply corridors. Single-source vulnerability concentrates in TSMC capacity allocation. Distribution runs through direct-to-employer contracting and electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance timelines and clinical validation expenditures erect barrier-to-entry moats that favor incumbent players with established regulatory affairs infrastructure.
For Market Incumbents: Cement ecosystem lock-in through backward integration into sensor ASIC design and captive silicon production. Expand FDA-cleared cardiac monitoring portfolios to defend against emerging optical waveguide specialists. Prioritize hospital system partnerships for electronic health record workflow integration.
For New Entrants and Emerging Players: Ultra-wideband radar sensor fusion for contactless vital sign detection offers technology-first wedge into sleep apnea screening and fall detection white spaces. Target German automotive manufacturers for smart eyewear augmented reality deployments. Pursue direct-to-employer contracting channels bypassing retail markups.
For Investors and Strategic Acquirers: Re-rating potential sits with clinical-grade wearable specialists given CMS remote patient monitoring reimbursement code expansion. Five-to-ten year viability favors FDA-cleared glucose monitoring and cardiac arrhythmia detection platforms over consumer fitness trackers. Watch algorithm transparency enforcement under EU AI Act as inflection indicator for European market withdrawal patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses clinical validation timelines for cardiac event detectors. |
| Optical Waveguide Miniaturization | Micro-LED integration below 80 grams unlocks German automotive assembly-line AR deployments. |
| Hospital System Partnership | Electronic health record workflow integration secures institutional procurement pathways. |
| Backward Integration into Sensor ASICs | In-house biometric chip design reduces TSMC foundry concentration exposure. |
| Direct-to-Employer Contracting | Volume agreements with self-insured US corporations bypass traditional distributor markups. |
Research Approach
Document review covered FDA 510(k) clearance databases, EMA Medical Device Regulation submissions, NMPA GB standards filings, and CMS reimbursement code updates, complemented by interviews with wearable OEM product managers, hospital biomedical engineers, contract research organization clinical data scientists, and electronics manufacturing services procurement leads. Secondary validation drew from SEC filings, customs trade records, and semiconductor foundry capacity disclosures. Bottom-up shipment estimates triangulated against top-down healthcare expenditure allocations.
Historical volume trajectories cross-referenced against expert panel inputs on regulatory pathway timelines and sensor technology substitution curves. Segmentation modeling spanned product form factor, wireless protocol, end user archetype, and functional application across the projection horizon. CAGRs derived from regression analysis of adoption rates correlated with reimbursement policy changes and battery chemistry cost curves. Forecast inputs incorporated Bluetooth Low Energy power budget constraints and optical waveguide weight reduction trajectories.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, novel biomarker sensor breakthroughs, and healthcare reimbursement code eliminations. Forecasts reflect documented assumptions on FDA predicate device equivalence study durations and lithium supply corridor stability. A model refresh is warranted upon material change in EU AI Act enforcement severity or TSMC advanced node capacity allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Smart Band Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Europe Watch Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Kids Watch Market
Wearable Technology
Wearable Camera Market