
 Europe Pet Smart Tracker Market | 2026-2036
Europe Pet Smart Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Smart Tracker Market Insights
Silicon-based microcontrollers are repositioning product economics as manufacturers replace legacy GPS modules with integrated low-power system-on-chip designs. Tractive leverages proprietary firmware to sustain real-time tracking accuracy across dense urban environments. Garmin anchors its position through ruggedized hardware architectures designed for working dog applications. Datamars competes via deep specialization in RFID-based identification systems that bridge companion and livestock monitoring segments.
Europe Pet Smart Tracker devices combine location sensors, biometric monitors, and wireless transceivers into wearable form factors that transmit data to cloud-based dashboards for pet owners and veterinary professionals. Cellular-enabled units typically operate on narrowband IoT protocols with sub-50 mW power draw to achieve multi-day battery life in compact collar-mounted enclosures. GPS trackers dominate current revenue flows due to established consumer familiarity and carrier subscription bundling across Germany, France, and the United Kingdom. Health trackers represent the fastest-expanding category as veterinary clinics in the Netherlands and Switzerland integrate remote patient monitoring into preventive care protocols. Bluetooth-based devices occupy a mature niche for short-range indoor applications where cost sensitivity limits cellular adoption.
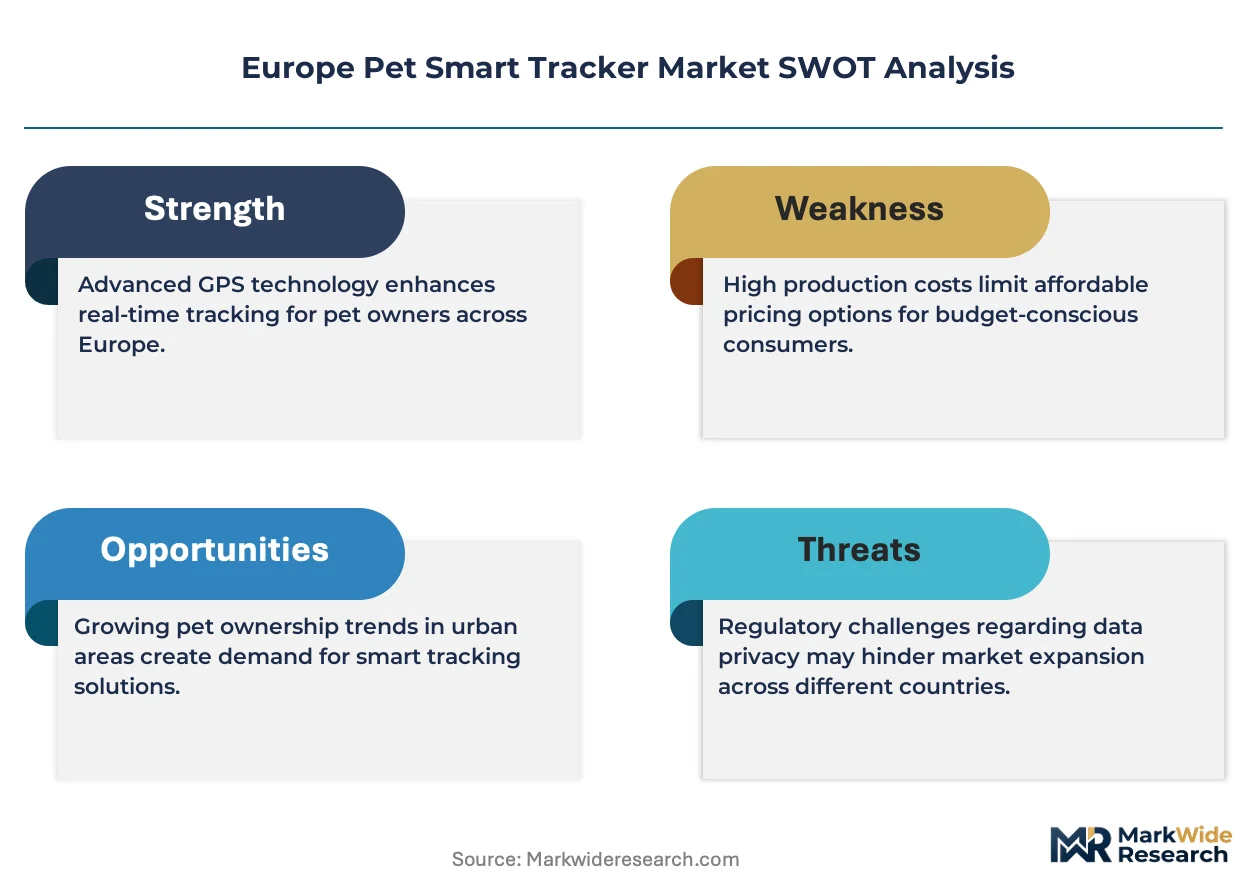
CE marking requirements under the EU Radio Equipment Directive shape hardware compliance timelines for all devices transmitting in European spectrum bands. REACH restrictions on hazardous substances in electronics housings compel material selections that satisfy both environmental and pet-safety criteria. The EU AI Act's emerging provisions on algorithmic decision-making will require scrutiny of automated health alert systems that classify behavioral anomalies without human veterinary review. Stakeholders must decide whether to build in-house regulatory affairs capabilities or outsource conformity assessment to notified bodies as device complexity escalates.
Market Dynamics
Silicon integration and EU regulatory pressure on sustainable electronics are compressing hardware margins while expanding service revenue pools for European pet tracker vendors.
Growth Catalysts
- Narrowband IoT deployment:Carrier infrastructure rollouts across Germany, France, and the United Kingdom enable real-time tracking at sub-50 mW power draw, extending battery life without hardware bulk.
- EU Green Deal procurement standards:Public veterinary service contracts increasingly mandate recyclable polymer housings and low-power chipsets, advantaging compliant vendors in institutional channels.
- Veterinary remote monitoring adoption:Clinics in the Netherlands and Switzerland integrate biometric data streams into preventive care protocols, creating recurring subscription demand.
Market Restraints
- Lithium cell supply concentration:Compact battery sourcing depends heavily on East Asian cell manufacturers, exposing European assemblers to input cost volatility and logistics friction.
- REACH substance restrictions:ECHA limitations on flame retardants and plasticizers in wearable housings constrain material selection, extending R&D cycles for enclosure designs.
- Smartphone-based substitution:Bluetooth-tethered phone apps for short-range pet location satisfy cost-sensitive owners, capping addressable market for cellular-enabled premium units.
Strategic Opportunities
- Eastern European underpenetration:Poland, Czech Republic, and Romania exhibit rising pet ownership rates with minimal cellular tracker adoption, presenting first-mover expansion potential.
- Livestock monitoring convergence:RFID-to-cellular bridge devices enable vendors to serve both companion animal and agricultural segments with shared hardware platforms.
- CSRD data transparency mandates:Corporate sustainability reporting requirements create demand for supply chain traceability tools that pet tracker vendors can repackage as B2B offerings.
Industry Challenges
- Embedded firmware talent scarcity:Real-time location algorithms require specialized low-power optimization expertise concentrated in semiconductor hubs, forcing vendors to compete for limited engineering capacity.
- CE marking timeline compression:EU Radio Equipment Directive compliance for new spectrum bands demands concurrent hardware and documentation preparation, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Smart Tracker Market |
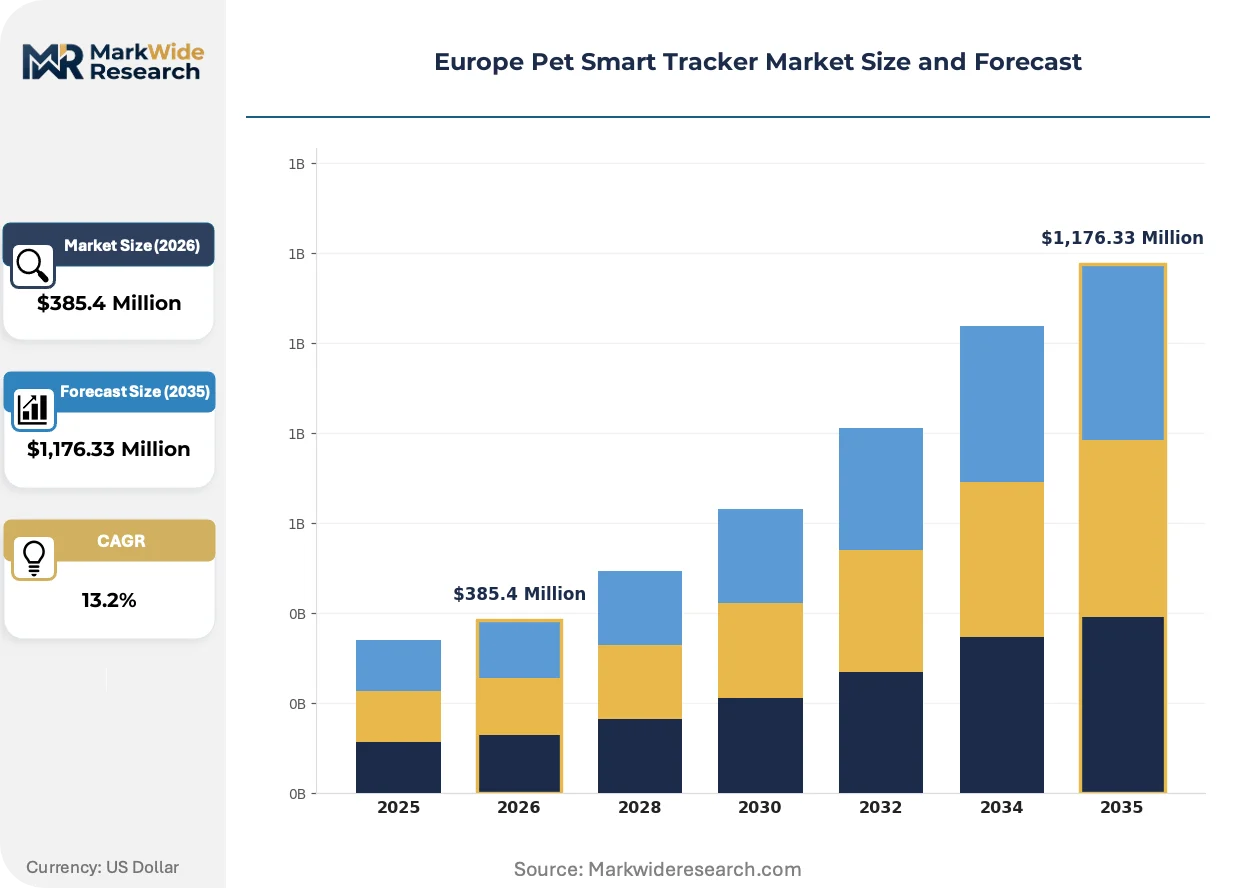
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,176.33 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, Activity Monitors, Health Trackers, Smart Collars Technology: Bluetooth, RFID, Cellular, Wi-Fi End User: Pet Owners, Veterinarians, Pet Care Facilities, Pet Rescuers Application: Tracking, Health Monitoring, Training, Safety Alerts |
| Companies Covered | Felcana, Allflex Livestock Intelligence, Tractive, Trovan Ltd., Loc8tor Ltd., Garmin Ltd., Avid Identification Systems, FitBark, Datamars, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Smart Tracker Market Trends and Innovations
Hardware commoditization is pushing competitive differentiation toward software services and data analytics, with vendors restructuring around recurring revenue models rather than device margins.
Ultra-wideband positioning chipsets are modularizing location stack architectures, allowing manufacturers to swap ranging technologies without redesigning baseband firmware. German and Swiss premium brands adopt this flexibility fastest, enabling rapid response to veterinary demands for centimeter-accurate indoor tracking. The structural result is collapsing development cycles for specialized form factors.
REACH restrictions on persistent organic pollutants in electronics housings are tightening material specifications for pet-wearable enclosures. Manufacturers must now validate biocompatible polymer alternatives through ECHA notification procedures before commercialization. Small and mid-sized vendors in Southern Europe face disproportionate compliance cost burdens relative to scaled competitors.
Veterinary procurement is consolidating around bundled device-plus-platform contracts that unbundle hardware from data analytics subscriptions. Independent clinics in Belgium and Austria increasingly source through group purchasing organizations rather than direct vendor relationships. This channel shift compresses pricing power for standalone hardware vendors while elevating software-integrated suppliers.
Europe Pet Smart Tracker Market Segmentation
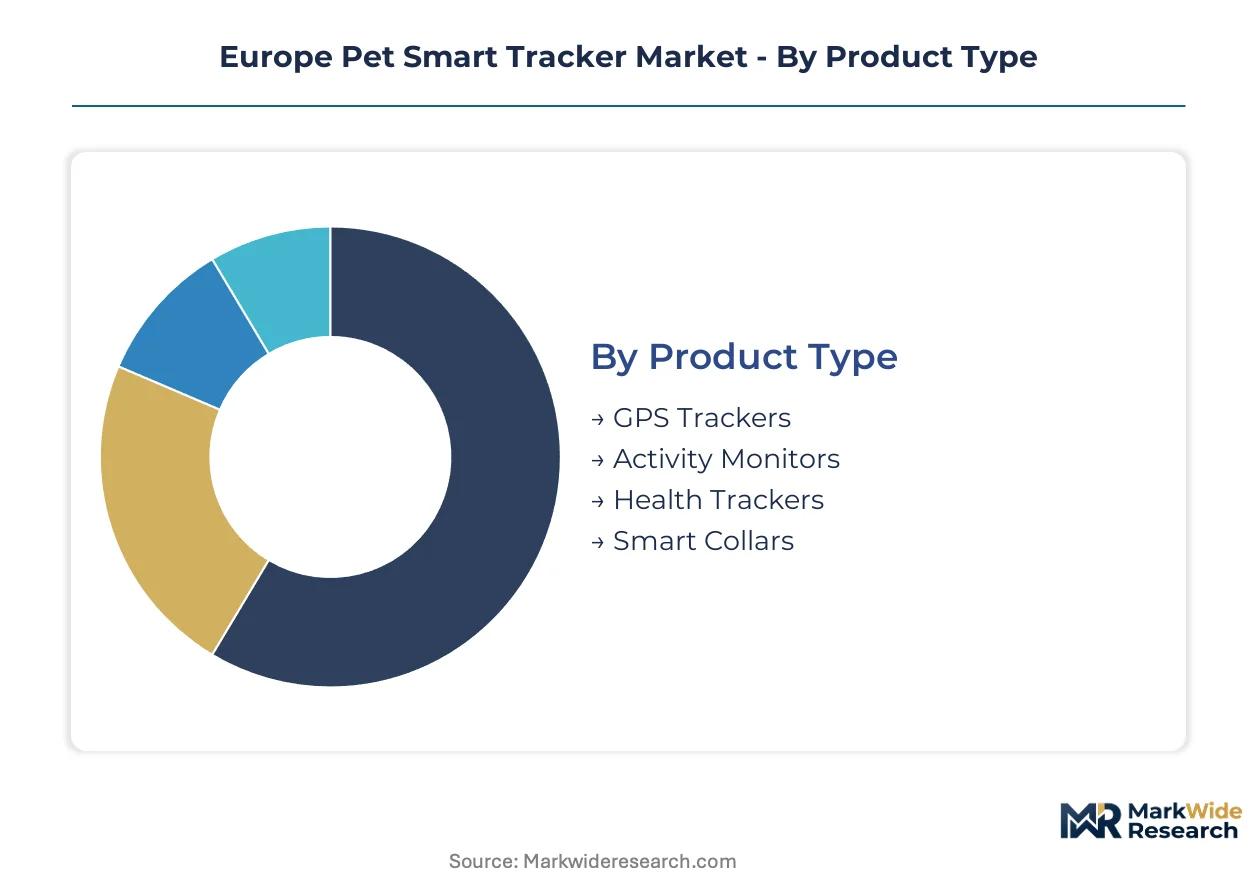
Pet tracker segmentation reflects divergent technical requirements across companion animal use cases. Hardware specifications vary sharply between urban location tracking and clinical health monitoring applications.
Product Type:
Standardization dominates GPS and activity units, while health trackers demand bespoke sensor configurations for veterinary integration.
- GPS Trackers:Devices integrate multi-constellation satellite receivers with cellular modems for real-time positioning. Demand concentrates in Germany, France, and the United Kingdom where carrier subscription bundling reduces consumer friction. CE marking under the EU Radio Equipment Directive shapes hardware compliance timelines for spectrum transmission.
- Health Trackers:Wearables embed photoplethysmography sensors and accelerometers for biometric monitoring. Clinics in the Netherlands and Switzerland drive procurement through remote patient monitoring protocols. The EU AI Act's algorithmic decision-making provisions will scrutinize automated anomaly alerts lacking veterinary review.
- Activity Monitors:Step-counting and sleep-pattern devices serve fitness-conscious owners with simplified hardware.
- Smart Collars:Multi-function units combine location, health, and training features in premium form factors.
Leading the category by volume: GPS Trackers. Expanding most quickly: Health Trackers.
Technology:
Power draw and range specifications sort technologies across indoor proximity versus outdoor tracking applications.
- Cellular:Narrowband IoT protocols achieve sub-50 mW consumption for multi-day battery life in compact enclosures. Carrier infrastructure rollouts across Germany, France, and the United Kingdom enable real-time data transmission without Wi-Fi dependency. REACH restrictions on battery housing materials constrain enclosure design options.
- Bluetooth:Short-range protocols serve indoor proximity applications with minimal hardware cost. Smartphone-tethered solutions satisfy price-sensitive owners in Southern Europe, capping cellular premium unit penetration. The technology occupies a mature niche where cost sensitivity dominates purchasing decisions.
- RFID:Passive identification systems bridge companion animal and livestock monitoring through Datamars specialization.
- Wi-Fi:Higher-bandwidth connectivity supports firmware updates and data synchronization in home environments.
Cellular hardware commands premium pricing. Bluetooth maintains volume leadership through cost accessibility.
End User:
Procurement sophistication varies from individual consumer purchases to institutional veterinary contracts.
- Pet Owners:Individual purchasers drive mass-market volume through retail and direct-to-consumer channels. German and French owners exhibit highest cellular tracker adoption rates correlated with disposable income and pet expenditure indices.
- Veterinarians:Clinical professionals source through group purchasing organizations in Belgium and Austria. Bundled device-plus-platform contracts unbundle hardware from analytics subscriptions, compressing standalone vendor pricing power.
- Pet Care Facilities:Boarding and daycare operators deploy fleet tracking for liability management.
- Pet Rescuers:Shelter and rescue organizations prioritize low-cost identification for population management.
Pet Owners generate absolute unit volume. Veterinarians deliver highest recurring revenue per deployment.
Application:
Functional requirements dictate sensor selection and data processing architectures across use cases.
- Tracking:Location services dominate current revenue through established consumer familiarity with GPS functionality. Urban density in London, Paris, and Berlin challenges real-time accuracy, driving proprietary firmware development for signal optimization.
- Health Monitoring:Biometric data streams integrate into preventive care protocols through cloud-based veterinary dashboards. Swiss and Dutch clinics lead adoption of remote patient monitoring for chronic condition management.
- Training:Behavioral feedback systems incorporate vibration and tone stimuli for obedience conditioning.
- Safety Alerts:Geofencing and escape notifications serve containment-focused owners in suburban and rural settings.
Tracking anchors current revenue. Health Monitoring demonstrates steepest expansion trajectory through veterinary channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the Netherlands and Germany concentrate pet technology manufacturing through R&D tax incentives and streamlined CE marking pathways. These zones attract firmware developers and polymer specialists serving wearable device supply chains. Regulatory harmonization across the EU single market enables cross-border distribution from these hubs.
Germany
German pet owners drive premium cellular tracker adoption through high disposable income and dense veterinary service networks. The KBA oversees device certification for automotive-grade GPS modules repurposed in ruggedized pet hardware. Munich and Stuttgart host clusters of low-power IoT firmware developers supplying Tractive and Garmin engineering centers.
United Kingdom
British consumers respond strongly to carrier subscription bundling that reduces upfront hardware costs for GPS-enabled collars. Post-Brexit UKCA marking requirements run parallel to retained EU CE standards, creating dual compliance obligations for importers. London's fintech ecosystem spawns payment-integrated pet service platforms that bundle tracker subscriptions.
France
French veterinary clinics accelerate health tracker procurement through ANSM-regulated remote patient monitoring frameworks. The EU Green Deal procurement standards mandate recyclable polymer housings in public veterinary contracts. Lyon and Toulouse concentrate injection molding specialists adapting biocompatible enclosures for wearable applications.
Netherlands
Dutch clinics lead European adoption of biometric monitoring through integrated preventive care protocols subsidized by national health frameworks. ECHA's REACH restrictions on flame retardants shape material selection for Amsterdam-based hardware assemblers. Eindhoven's semiconductor corridor supplies narrowband IoT chipsets achieving sub-50 mW power draw.
Switzerland
Swiss pet owners demonstrate highest willingness-to-pay for health-integrated trackers correlating with veterinary expenditure indices. Swissmedic oversight of algorithmic health alerts anticipates EU AI Act provisions on automated anomaly detection. Zurich and Basel host precision sensor manufacturers supplying photoplethysmography modules for cardiac monitoring wearables.
Europe Pet Smart Tracker Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among integrated hardware-software vendors and volume production outsourced to polymer enclosure specialists. The vendor base organizes into three tiers: cellular-enabled platform operators, RFID identification incumbents, and Bluetooth-tethered commodity producers. Dominant competitive moves include M&A for veterinary channel access and strategic partnerships with narrowband IoT carriers for subscription bundling.
Within the cellular-platform tier, Tractive and Garmin exemplify divergent specialization strategies, while Datamars occupies a distinct position bridging companion animal and livestock monitoring applications. Tractive represents the Austria-based firmware-integrated model leveraging proprietary algorithms for urban signal optimization. Garmin anchors the ruggedized-hardware archetype through working-dog applications demanding impact-resistant enclosures. Datamars, a Swiss-Italian specialist, exemplifies cross-segment RFID-to-cellular platform convergence serving both veterinary and agricultural channels.
| Leading Market Players |
|---|
| Felcana |
| Allflex Livestock Intelligence |
| Tractive |
| Trovan Ltd. |
| Loc8tor Ltd. |
| Garmin Ltd. |
| Avid Identification Systems |
| FitBark |
| Datamars |
| Others |
Pricing and Supply Chain Analysis
Veterinary procurement consolidation in Belgium and Austria toward bundled device-plus-platform contracts is forcing hardware vendors to unbundle component sourcing from final assembly, compressing standalone pricing power while elevating integrated suppliers with captive firmware capabilities.
Pricing Analysis
Lead-time premiums for REACH-compliant biocompatible polymer housings now separate rapid-deployment contracts from standard-cycle procurement. Three-tier pricing structure across cellular-enabled premium, Bluetooth-tethered standard, and RFID-based economy levels reflects certification grade and after-sales analytics bundling. Cost compression in cellular hardware is intensifying because carrier infrastructure rollouts narrow differentiation around narrowband IoT chipsets. Individual pet owners in Southern Europe exhibit highest price sensitivity, while Swiss veterinary clinics demonstrate lowest.
Supply Chain Analysis
Firmware engineering talent shortages in Munich and Stuttgart clusters are extending development timelines for vendors dependent on local semiconductor corridors. Narrowband IoT chipsets draw from Eindhoven's semiconductor corridor, biocompatible polymers from Lyon injection molding specialists, and lithium cells from East Asian manufacturers. Single-source vulnerability in compact battery supply exposes European assemblers to logistics friction. Distribution runs through carrier retail partnerships in Germany, France, and the United Kingdom, supplemented by veterinary group purchasing organizations in Belgium and Austria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Pet Smart Tracker Market sits in a technology-transition phase as ultra-wideband positioning chipsets displace legacy GPS modules for centimeter-accurate indoor tracking demanded by German and Swiss premium brands.
For Market Incumbents: Lock in veterinary channel control through exclusive data platform partnerships before independent clinics in Belgium and Austria complete their shift to group purchasing organization procurement. Invest in proprietary firmware development for urban signal optimization to defend against smartphone-based Bluetooth substitution. Backward integration into biocompatible polymer enclosure production reduces REACH compliance timeline exposure. For New Entrants and Emerging Players: Eastern European pet owners in Poland, Czech Republic, and Romania represent an underserved buyer archetype with rising companion animal ownership and minimal cellular tracker penetration. Agricultural livestock operators seeking RFID-to-cellular bridge devices offer a second white-space target with shared hardware platform economics. A direct-to-veterinary sales model bypasses saturated carrier retail channels. For Investors and Strategic Acquirers: The window for entry favors firmware-integrated platform operators with established narrowband IoT carrier relationships over standalone hardware vendors facing margin compression. Long-term viability hinges on recurring subscription revenue pools rather than device margins. Watch for EU AI Act enforcement actions against automated health alert systems as an inflection indicator for regulatory compliance valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Platform Integration | Creates recurring revenue lock-in through ANSM-regulated remote patient monitoring frameworks in France. |
| Ultra-wideband Chipset Adoption | Enables rapid response to Swiss and German veterinary demands for centimeter-accurate indoor positioning. |
| Eastern European Geographic Expansion | Captures first-mover advantage in Poland, Czech Republic, and Romania before carrier infrastructure matures. |
| REACH-compliant Material Transition | Secures eligibility for EU Green Deal procurement standards in public veterinary service contracts. |
| Livestock Monitoring Convergence | Extends addressable market to agricultural segments through Datamars-style RFID-to-cellular bridge platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by primary interviews with veterinary procurement managers, firmware engineering directors at IoT chipset developers, carrier narrowband IoT product leads, polymer enclosure manufacturers, and ECHA regulatory affairs specialists. Secondary sources included CE marking documentation under the EU Radio Equipment Directive, REACH substance restriction notifications, carrier infrastructure deployment disclosures, and veterinary clinic procurement databases. Bottom-up unit shipment estimates triangulated against top-down service revenue projections.
Data-stream reconciliation across device shipment volumes, carrier subscription activations, and veterinary platform deployments informed the analytical framework. Segmentation dimensions modeled included product type, connectivity technology, end-user archetype, and application function across the analysis window. CAGRs derived from fitted growth curves incorporating narrowband IoT carrier rollout schedules, EU AI Act implementation timelines, and REACH enforcement patterns. Industry-specific inputs comprised Eindhoven semiconductor corridor capacity expansion and KBA automotive-grade GPS module certification pathways.
Revisions become necessary when carrier narrowband IoT infrastructure deployment stalls, EU AI Act enforcement actions disrupt automated health alert systems, or East Asian lithium cell supply experiences sustained logistics friction. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Pet Tech Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
South America Pet Treats Market