
 Hand Wash Station Market | 2026-2036
Hand Wash Station Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Wash Station Market Analysis
The shift from single-source to multi-source component procurement is recalibrating supply chain economics for hand wash station manufacturers. Elkay leverages captive metalworking capacity to control stainless steel basin quality. Satellite Industries anchors its position through geographic dominance in portable sanitation rentals. Meritech differentiates via automated hygiene validation systems for healthcare compliance.
A hand wash station is a purpose-built fixture or mobile unit engineered for water delivery, soap dispensing, and wastewater capture, typically constructed with 304-grade stainless steel basins, ABS polymer enclosures, or fiberglass-reinforced shells rated for 15-50 psi inlet pressure. Its primary commercial purpose is to satisfy health code hand hygiene requirements in environments lacking permanent plumbing. Portable stations lead volume in construction and outdoor event applications where temporary setup configurations dominate procurement. Wall-mounted units with automatic sensors command premium positioning in healthcare settings due to touchless infection control protocols. Stainless steel material grades capture the highest margin pools because of durability mandates in permanent installations.
OSHA workplace sanitation standards, FDA Food Code handwashing provisions, and EPA water-efficiency regulations collectively shape product specifications and market access thresholds across the United States. The EPA WaterSense program drives low-flow faucet integration, while OSHA field sanitation rules mandate minimum hand wash station counts per worker cohort on construction sites. Stakeholders must monitor evolving state-level plumbing code amendments and healthcare facility accreditation standards to anticipate specification shifts before competitive bidding cycles.
Market Dynamics
OSHA workplace sanitation mandates are compressing procurement cycles for portable hand wash infrastructure across United States construction sites. Federal infrastructure spending is accelerating permanent fixture upgrades in commercial facilities where infection control protocols now specify touchless sensor activation.
Growth Catalysts
- OSHA Field Sanitation Standards:Construction sites across the United States must maintain minimum hand wash station counts per worker cohort, creating baseline demand for portable units with self-contained water tanks and wastewater capture.
- Healthcare Infection Control Protocols:Hospitals and outpatient clinics are specifying automatic sensor-activated basins to eliminate touchpoints, with 304-grade stainless steel construction meeting Joint Commission accreditation requirements.
- Water-Efficiency Mandates:The EPA WaterSense program is integrating low-flow faucet specifications into federal procurement guidelines, pushing manufacturers to redesign valve assemblies for 0.5 gpm output thresholds.
Market Restraints
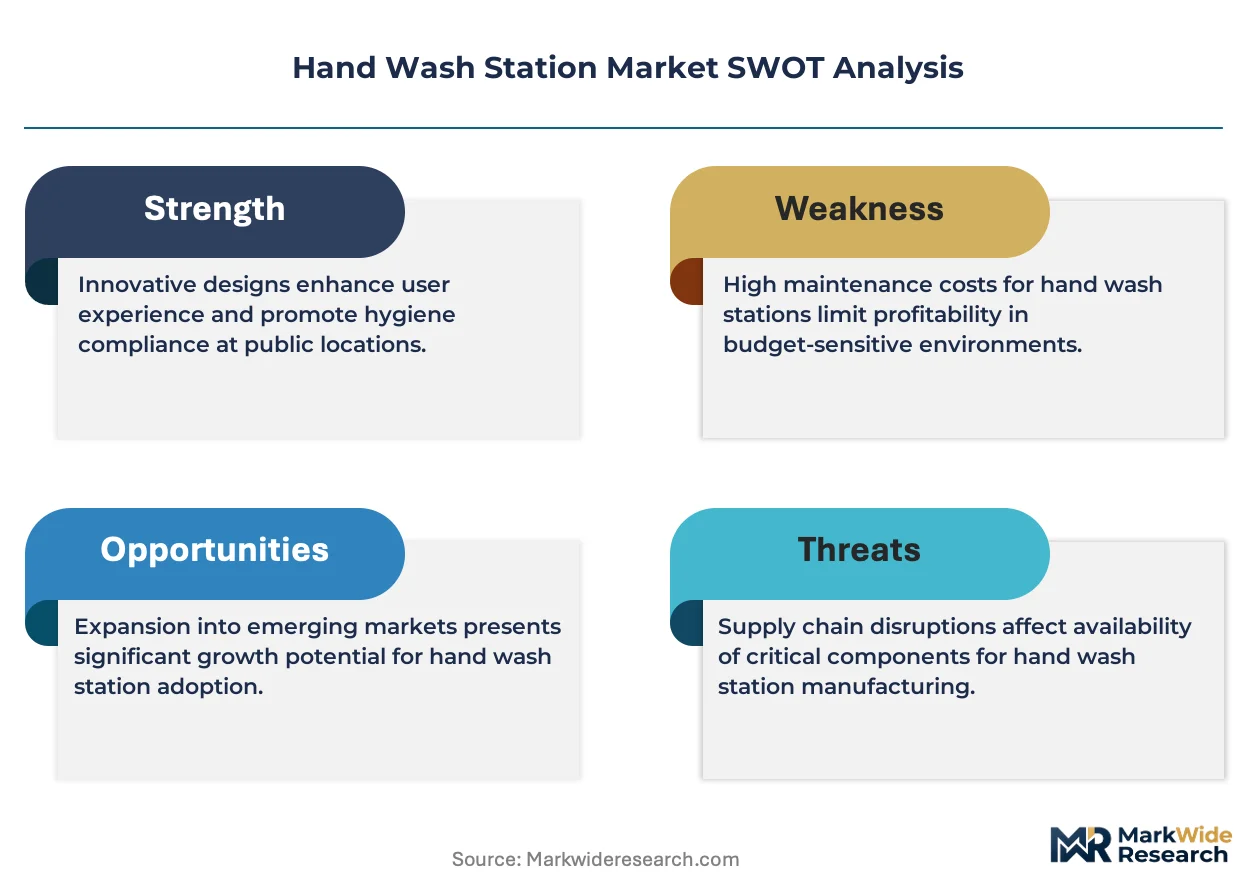
- Stainless Steel Input Volatility:304-grade sheet metal pricing fluctuates with nickel commodity markets, squeezing margin pools for basin fabricators who lack captive metalworking capacity.
- Regional Supply Concentration:Domestic production of NSF-certified polymer enclosures clusters in the Midwest industrial corridor, exposing distributors to single-source risk during logistics disruptions.
- Plumbing Code Fragmentation:State-level amendments to IPC and UPC standards create specification friction, forcing manufacturers to maintain multiple product variants for code-compliant market access.
Strategic Opportunities
- Underserved Rural Healthcare:Federally qualified health centers in Appalachian and Southwestern states lack permanent plumbing infrastructure, creating demand for mobile hand hygiene units with battery-powered pumps.
- Outdoor Event Infrastructure:Music festivals and agricultural fairs are specifying rental fleets with solar-heated water capacity, opening service-contract revenue streams beyond equipment sales.
- Green Building Certification:LEED v4.1 Indoor Water Use Reduction credits reward low-flow fixture installation, positioning compliant hand wash stations for premium specification in commercial new construction.
Industry Challenges
- Certification Timeline Compression:NSF/ANSI 372 lead-free compliance testing creates 8-12 week validation bottlenecks for new valve designs, delaying product launches against competitive bidding cycles.
- Sensor Integration Complexity:Infrared activation modules from third-party suppliers require firmware coordination with basin electronics, generating field failure rates that strain warranty reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Wash Station Market |
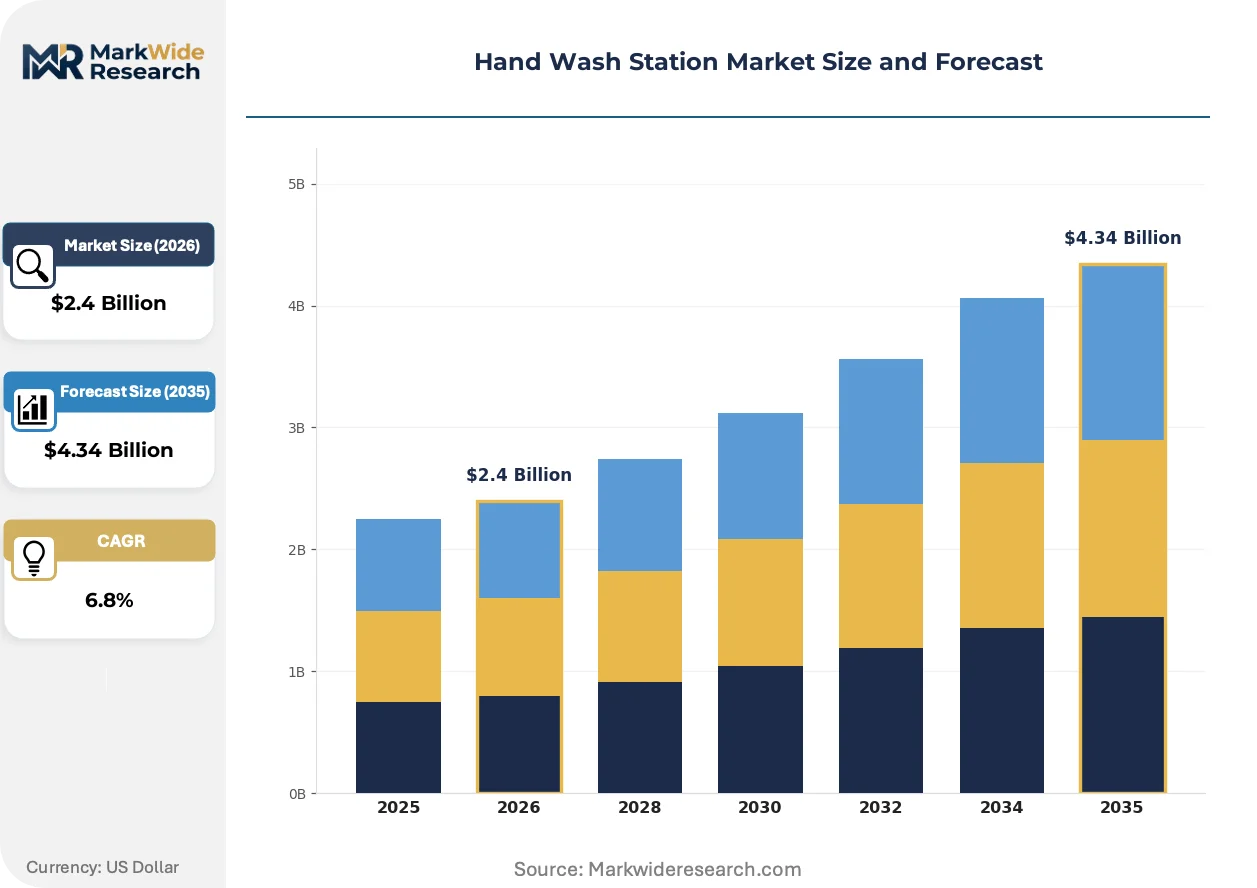
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Stations, Wall-Mounted Units, Foot-Pedal Operated, Automatic Sensors End User: Residential Use, Commercial Facilities, Construction Sites, Healthcare Settings Installation: Indoor, Outdoor, Temporary Setup, Permanent Installation Material: Plastic, Stainless Steel, Fiberglass, Aluminum |
| Companies Covered | Elkay, Satellite Industries, Meritech, Monsam, Berl's, Murdock Manufacturing, PolyJohn, Acorn Engineering Company, Bradley Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Wash Station Market Emerging Trajectories
Touchless activation systems are displacing manual lever handles across both permanent and portable hand wash station categories. Sensor miniaturization and battery efficiency gains are enabling retrofit installations in legacy facilities lacking electrical rough-in.
Ultraviolet-C LED modules are integrating into basin assemblies for continuous surface disinfection between uses. Hospital procurement teams are specifying these units for isolation room installations where terminal cleaning protocols demand enhanced pathogen control. The technology is integrating with building automation systems to log activation cycles for compliance documentation.
The EPA WaterSense program is tightening flow-rate thresholds for lavatory faucet certification, compressing allowable output to 0.5 gallons per minute. Manufacturers are redesigning aerator geometries and pressure-compensating valves to maintain user satisfaction at reduced volume. Healthcare facilities in water-stressed Western states are prioritizing these fixtures for both new construction and renovation specifications.
Rental and service-contract models are displacing capital purchase for construction site applications. General contractors are bundling hand wash station provisioning with portable sanitation services to reduce upfront project costs and transfer maintenance liability. This shift is most visible in Texas and California infrastructure projects where labor mobility creates demand volatility across job phases.
Hand Wash Station Market Segmentation
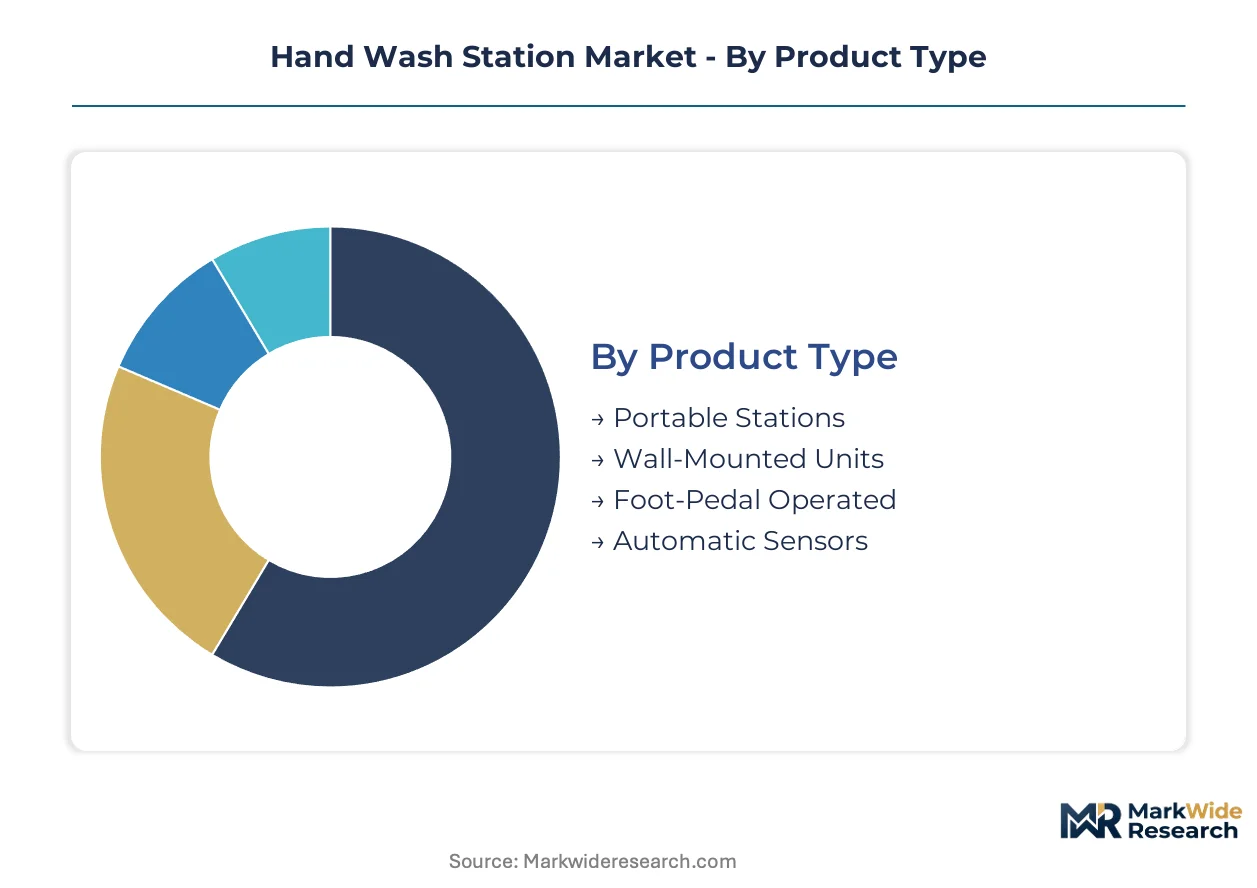
Hand wash station procurement diverges sharply across end-use environments, with specification requirements driven by plumbing availability, mobility needs, and infection control mandates. Material selection and installation modality determine margin structures and competitive positioning for manufacturers serving distinct buyer cohorts.
Product Type:
Buyer selection hinges on mobility requirements versus permanence of installation, with regulatory compliance thresholds varying by operational context.
- Portable Stations:Self-contained units with integrated water tanks and wastewater capture systems, typically rated for 15-50 psi inlet pressure. Construction sites across the United States specify these for OSHA field sanitation compliance, with rental fleets dominating procurement in Texas and California infrastructure corridors.
- Wall-Mounted Units:Fixed installations requiring permanent plumbing rough-in, constructed with 304-grade stainless steel basins for healthcare accreditation. Hospitals specify touchless sensor variants to eliminate contamination vectors, with Joint Commission standards driving premium material selection.
- Foot-Pedal Operated:Mechanical activation systems eliminating hand contact through floor-mounted levers, common in food processing facilities where FDA Food Code handwashing provisions apply.
- Automatic Sensors:Infrared-activated valve assemblies with battery or hardwired power, integrating with building automation systems for compliance logging in acute care settings.
Portable Stations lead on scale; Automatic Sensors lead on momentum.
End User:
Facility type dictates specification intensity, with healthcare and construction presenting opposing demand profiles around permanence and mobility.
- Residential Use:Kitchen and utility room installations in single-family and multi-family dwellings, typically specifying economy-grade polymer enclosures with manual lever handles.
- Commercial Facilities:Restaurants, retail, and office buildings requiring NSF-certified fixtures for health code compliance, with EPA WaterSense low-flow specifications increasingly specified in Western states.
- Construction Sites:Temporary workforce hygiene infrastructure subject to OSHA field sanitation mandates, driving rental-model procurement with self-contained water delivery and graywater capture.
- Healthcare Settings:Acute care hospitals, outpatient clinics, and long-term care facilities specifying 304-grade stainless steel with touchless activation for Joint Commission infection control protocols.
Construction Sites dominate unit volume; Healthcare Settings command premium pricing tiers.
Installation:
Physical mounting context determines product architecture, with environmental exposure and duration of use shaping material and sealing specifications.
- Indoor:Climate-controlled environments permitting polymer enclosure use, with electrical rough-in enabling sensor-activated variants in permanent commercial and healthcare fixtures.
- Outdoor:Weather-exposed deployments requiring UV-stabilized enclosures and freeze-resistant plumbing, common in agricultural fairgrounds and festival infrastructure.
- Temporary Setup:Rapid-deployment configurations with no permanent utility connections, standard for construction phase sanitation and emergency response deployments.
- Permanent Installation:Hard-piped fixtures with dedicated drainage, specifying durable materials for 10-15 year service life in commercial facility buildouts.
Permanent Installation anchors replacement demand; Temporary Setup expands most quickly in infrastructure and event sectors.
Material:
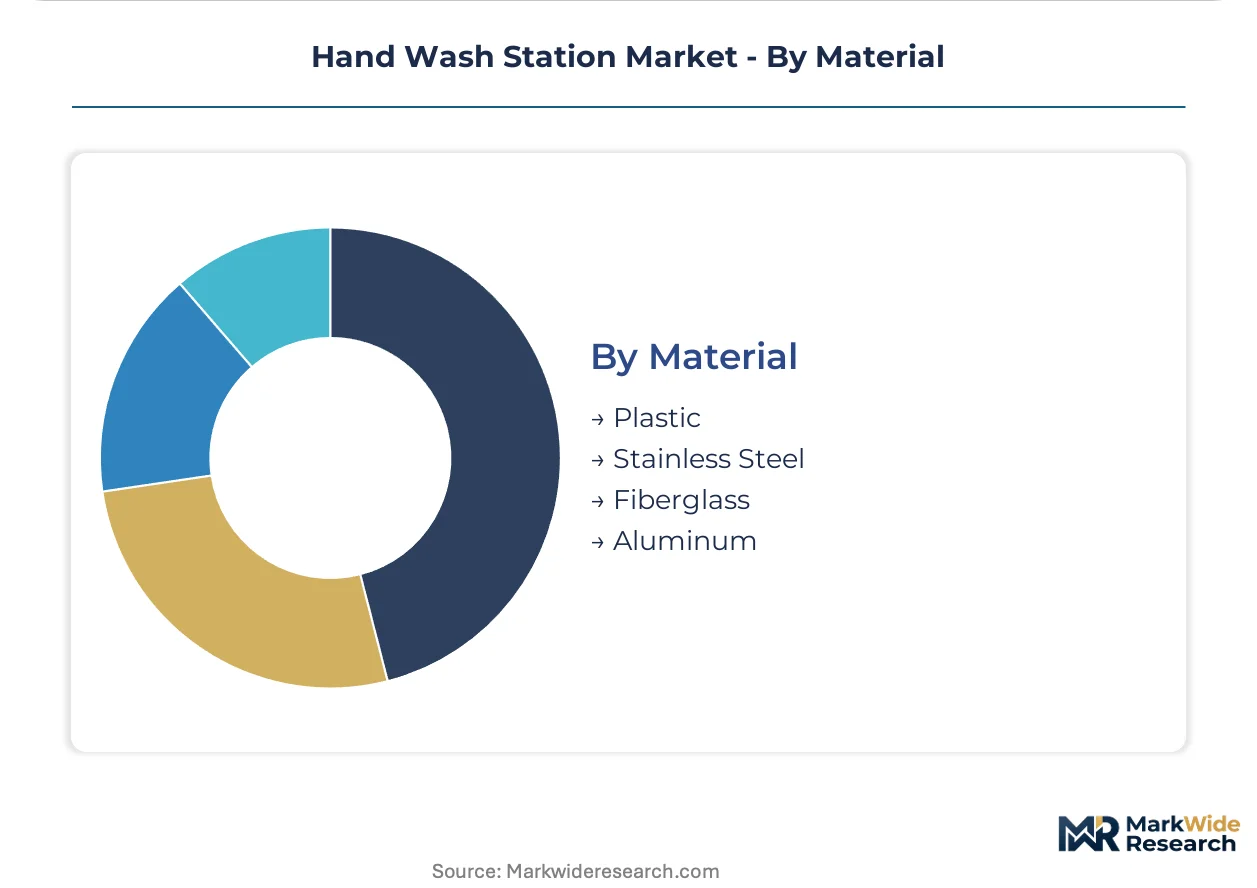
Material grade selection trades acquisition cost against durability mandates, with regulatory certification requirements narrowing acceptable inputs in healthcare and food service applications.
- Plastic:ABS polymer and high-density polyethylene enclosures offering corrosion resistance and lightweight portability, capturing economy-tier demand in construction and residential segments.
- Stainless Steel:304-grade and 316-grade sheet metal construction meeting NSF/ANSI 372 lead-free compliance, specified for healthcare accreditation and permanent commercial installations where durability mandates justify premium positioning.
- Fiberglass:Reinforced composite shells rated for chemical resistance and impact durability, deployed in industrial environments and outdoor temporary installations.
- Aluminum:Lightweight metal enclosures with anodized finishes for corrosion protection, specified in weight-sensitive portable units and aviation facility installations.
Stainless Steel leads on margin capture; Plastic leads on unit volume in price-sensitive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates procurement intensity for hand wash infrastructure, with federal construction spending and healthcare facility accreditation driving specification upgrades across multiple state-level markets.
United States
OSHA field sanitation mandates compress procurement cycles for portable units on infrastructure projects, while EPA WaterSense low-flow specifications reshape permanent fixture demand. Federal infrastructure spending accelerates commercial facility upgrades in Texas and California corridors. Construction rental fleets in Houston and Los Angeles scale sensor-activated portable stations for compliance documentation.
Germany
Industrial hygiene standards in food processing and pharmaceutical manufacturing sustain demand for foot-pedal and automatic sensor variants. REACH chemical compliance and CE marking requirements filter import competition for basin assemblies. Fabricators in Baden-Württemberg and North Rhine-Westphalia specialize in 316-grade stainless steel construction for cleanroom installations.
China
Urban construction velocity and hospital expansion programs absorb high volumes of economy-grade polymer enclosures. GB standards for plumbing fixtures and MIIT industrial water-efficiency targets shape domestic manufacturer output. Production clusters in Guangdong and Zhejiang provinces supply ABS-molded portable units for Southeast Asian export markets.
India
Rural healthcare infrastructure gaps and Swachh Bharat sanitation campaigns expand addressable demand for battery-powered mobile units. BIS certification requirements and CDSCO medical device rules segment quality tiers for hospital versus construction procurement. Manufacturing activity concentrates in Gujarat and Maharashtra for cost-competitive polymer enclosure fabrication.
United Kingdom
Post-pandemic healthcare facility renovation programs specify touchless sensor basins for NHS trust compliance. Building Regulations Part G water efficiency standards and HSE workplace welfare rules govern specification intensity. London and Southeast England anchor demand for premium-grade stainless steel installations in commercial redevelopment projects.
Hand Wash Station Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular service-contract models and sensor integration partnerships. The vendor base stratifies across captive metalworking specialists, rental fleet operators, and hygiene validation technology providers. Three archetypes dominate: stainless steel fabricators with backward integration into sheet metal supply, portable sanitation rental platforms with geographic density advantages, and automated compliance system developers targeting healthcare accreditation. Capacity expansion and strategic technology licensing represent the primary competitive vectors as specification complexity rises.
Among North American fabricators, Elkay exemplifies the captive metalworking archetype through basin quality control, while Satellite Industries anchors rental fleet density in portable sanitation markets. Meritech occupies a position within the automated hygiene validation segment for healthcare compliance. These three entities represent distinct capability vectors—materials mastery, service infrastructure scale, and software-hardware integration—that define competitive positioning across specification tiers.
| Leading Market Players |
|---|
| Elkay |
| Satellite Industries |
| Meritech |
| Monsam |
| Berl's |
| Murdock Manufacturing |
| PolyJohn |
| Acorn Engineering Company |
| Bradley Corp |
| Others |
Supply Flow & Price Mechanics
EPA WaterSense certification gates qualified supply for premium-tier hand wash stations, restricting basin and valve assemblies to low-flow specifications that command 15-25% price premiums over uncertified alternatives. Buyers in healthcare and commercial construction segments treat this environmental mandate as a non-negotiable procurement filter, compressing the addressable supplier base and amplifying pricing power for compliant fabricators.
Pricing Analysis
Input-cost pass-through from nickel-indexed 304-grade stainless steel sheet metal drives quarterly price adjustments for basin fabricators lacking captive metalworking capacity. Pricing stratifies across premium, standard, and economy tiers, with NSF/ANSI 372 lead-free certification and Joint Commission accreditation status as the primary differentiation drivers. Cost compression in the plastic enclosure segment is intensifying because of ABS polymer oversupply from Guangdong manufacturing clusters. Construction site rental fleets exhibit highest price sensitivity, while acute care hospitals demonstrate lowest sensitivity due to infection control liability exposure.
Supply Chain Analysis
Dual-sourcing requirements from GPOs and large healthcare systems mandate qualified suppliers for sensor modules, valve assemblies, and basin fabrication, extending procurement cycles but reducing single-source vulnerability. Production concentrates in the United States, China, and Germany, with 304-grade stainless steel sheet metal, infrared sensor modules, and NSF-certified polymer resins as critical inputs. Single-source vulnerability in third-party sensor firmware creates field failure risks that strain warranty reserves. Distribution runs through manufacturer-direct channels for large healthcare contracts and specialized sanitation rental platforms for construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand wash station market functions as a stable compounder, with OSHA field sanitation mandates and healthcare accreditation standards generating replacement demand cycles that insulate revenue from cyclical downturns.
For Market Incumbents: Lock in backward integration into stainless steel sheet metal supply to defend margin pools against nickel commodity volatility. Expand captive metalworking capacity in the Midwest industrial corridor to reduce exposure to regional supply concentration risks. Invest in NSF/ANSI 372 pre-certification for next-generation valve designs to compress competitive bidding timelines. For New Entrants and Emerging Players: Launch via service-contract models targeting federally qualified health centers in Appalachian and Southwestern states, where permanent plumbing gaps create demand for battery-powered mobile units. Focus initial penetration on outdoor event infrastructure rental fleets, where solar-heated water specifications remain undersupplied. Pursue white-label partnerships with established sanitation rental platforms to bypass direct distribution buildout costs. For Investors and Strategic Acquirers: Roll-up economics work for regional portable sanitation rental operators because fragmented local fleet ownership creates scale advantages in route density and maintenance centralization. The 5-10 year viability window favors platforms with established OSHA compliance documentation systems and healthcare GPO contract access. Watch for inflection in federal infrastructure spending appropriations as a signal for construction segment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Integration Partnership | Reduces field failure rates from firmware coordination gaps in infrared activation systems. |
| Captive Stainless Steel Fabrication | Elkay-style backward integration insulates margin pools from nickel commodity swings. |
| Solar-Heated Water Capacity Addition | Opens service-contract revenue streams in music festival and agricultural fair segments. |
| NSF/ANSI 372 Pre-Certification Investment | Compresses 8-12 week validation bottlenecks ahead of competitive bidding cycles. |
| Rental Fleet Geographic Expansion | Satellite Industries-style density buildout captures OSHA-mandated construction procurement. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each market informing demand calibration. The research combines structured interviews with procurement managers at hospital GPOs, construction site superintendents, portable sanitation rental fleet operators, and regulatory compliance officers with secondary validation from OSHA field sanitation directives, EPA WaterSense certification databases, Joint Commission accreditation standards, and NSF/ANSI testing protocols. Bottom-up unit demand estimates triangulate against top-down construction spending and healthcare capital expenditure flows.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models hand wash station demand by product type (portable, wall-mounted, foot-pedal, automatic sensor), end user (residential, commercial, construction, healthcare), installation modality (indoor, outdoor, temporary, permanent), and material grade (plastic, stainless steel, fiberglass, aluminum). CAGRs derive from regression against construction employment indices, hospital bed expansion rates, and regulatory compliance deadline clustering. Industry-specific inputs include OSHA field sanitation citation frequency and EPA WaterSense specification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility extremes and state-level plumbing code amendment acceleration. Deviation in federal infrastructure spending authorization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Disposable Cutlery Market
Household Items
India Digital Showers Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
US Soap Dispenser Market
Household Items
Toilet Care Wipes Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Europe Digital Showers Market
Household Items
Ironing Boards Market
Household Items
Car Air Freshener Market
Household Items
Towel Warmers Market
Household Items
Jet Hand Dryer Market
Household Items
Smart Memory Foam Market
Household Items
Domestic Sauna Heaters Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Pet Fur Remover Market