
 Global Smartwatch Battery Market | 2026-2036
Global Smartwatch Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartwatch Battery Market Outlook
Buyer concentration across the smartwatch battery value chain is rebalancing as fitness-tracking OEMs fragment demand while premium consumer electronics brands consolidate procurement power. CATL leverages its cylindrical cell expertise to anchor supply contracts with mid-tier wearable assemblers. Samsung SDI Co., Ltd competes through captive demand from its affiliated device ecosystem, while Enovix Corporation differentiates via silicon-anode architectures that extend runtime in compact form factors.
A smartwatch battery is a rechargeable electrochemical cell engineered to deliver sustained milliampere-hour capacity within sub-5-gram enclosures, typically employing lithium-polymer chemistry with cobalt or nickel-manganese cathodes to power always-on displays and biometric sensors. Its commercial purpose centers on enabling multi-day operation between charges while supporting high-pulse discharge for GPS and cellular modules. Lithium-polymer formulations dominate current volume due to their flexible pouch geometries, though solid-state architectures represent the fastest-growing technology segment as manufacturers pursue higher energy density without thermal runaway risk. Fast charging capabilities command premium positioning across fitness tracking and communication use cases where downtime tolerance has compressed to under sixty minutes.
China's SAMR enforces GB standards that govern lithium-ion cell cycle life and thermal stability, while the EU's REACH and RoHS frameworks restrict hazardous substances in battery assemblies sold across member states. India's BIS certification mandates safety testing for imported cells, creating compliance thresholds that filter low-specification suppliers. Stakeholders must monitor how solid-state pilot lines and regional certification divergence reshape sourcing geography and technology roadmaps.
Market Dynamics
Solid-state battery architectures are compressing development timelines as manufacturers race to eliminate thermal runaway risks while doubling energy density in sub-5-gram form factors. This chemistry transition is redrawing supplier qualifications and procurement criteria across fitness-tracking and medical-grade wearable segments.
Growth Catalysts
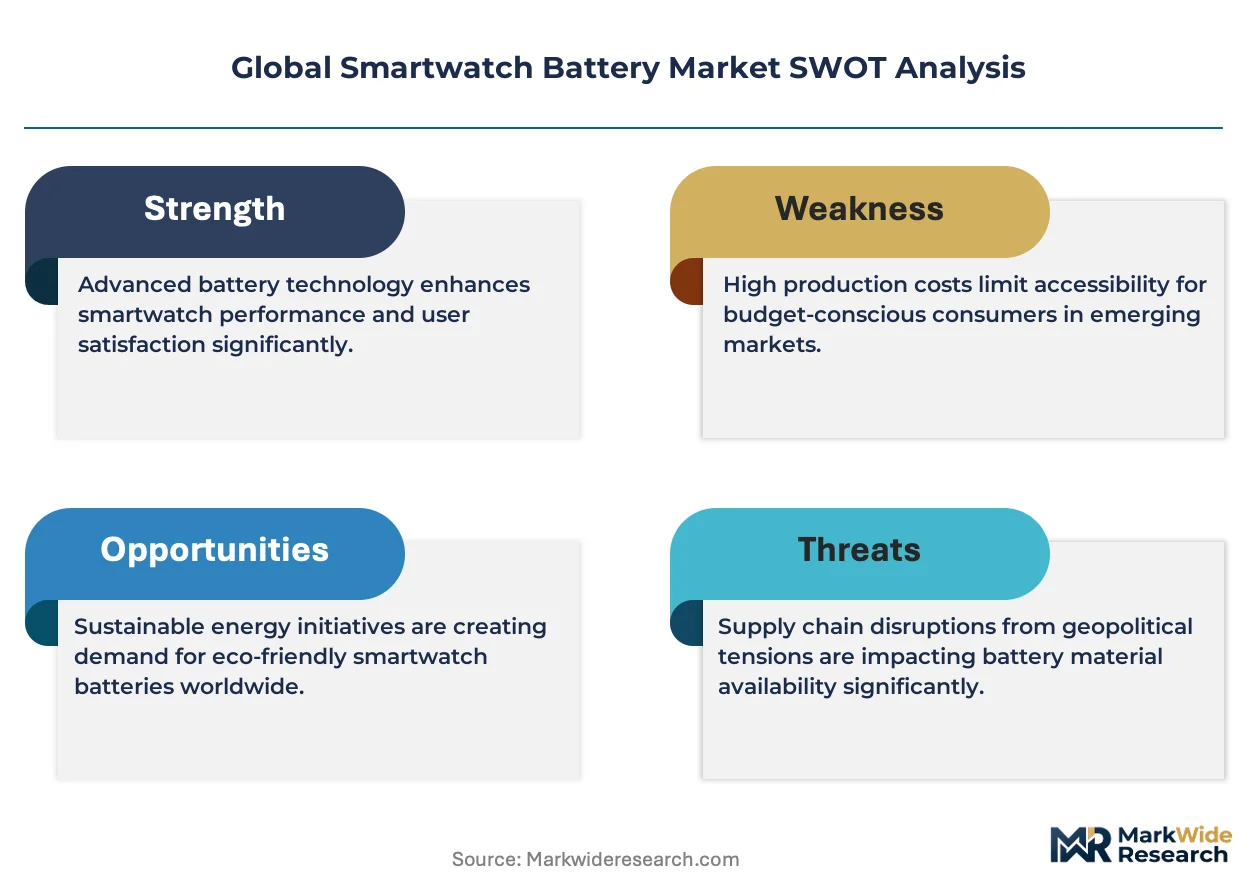
- EU Battery Regulation traceability mandates:Digital passport requirements for lithium cells are accelerating investments in supply chain visibility platforms among contract manufacturers serving European OEMs.
- Fitness-tracking OEM procurement expansion:Mid-tier wearable assemblers in India and Vietnam are diversifying supplier bases beyond captive sources to secure flexible pouch geometries for multi-sensor devices.
- Silicon-anode material maturation:Advanced lithiation techniques are enabling 40% capacity improvements in cylindrical cells without expanding physical footprint, attracting premium smartwatch brands.
Market Restraints
- Cobalt price volatility:Cathode material cost swings are compressing margins for lithium-polymer cell producers serving price-sensitive wearable tiers.
- East Asian supply concentration:Over 70% of high-grade separator film production sits with Korean and Japanese chemical conglomerates, creating single-source vulnerability for European battery packagers.
- Solid-state manufacturing yield gaps:Ceramic electrolyte sintering defects are limiting commercial-scale output, delaying mass adoption timelines by 24-36 months versus initial projections.
Strategic Opportunities
- India BIS certification localization:Domestic cell testing infrastructure expansion is enabling tariff-advantaged procurement for wearable assemblers in Tamil Nadu and Karnataka industrial corridors.
- Medical-wearable convergence:FDA-cleared continuous glucose monitoring smartwatches are creating demand for ultra-low self-discharge cells with 10-year shelf stability.
- China dual carbon policy alignment:SAMR green manufacturing incentives for water-based electrode coating are rewarding suppliers with carbon-verified production lines.
Industry Challenges
- Solid-state electrolyte engineering talent scarcity:Thin-film ceramic processing expertise resides with fewer than 200 specialists globally, constraining pilot line expansion.
- Multi-jurisdiction certification stacking:Simultaneous UL, IEC, and GB compliance testing adds 14-18 weeks to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartwatch Battery Market |
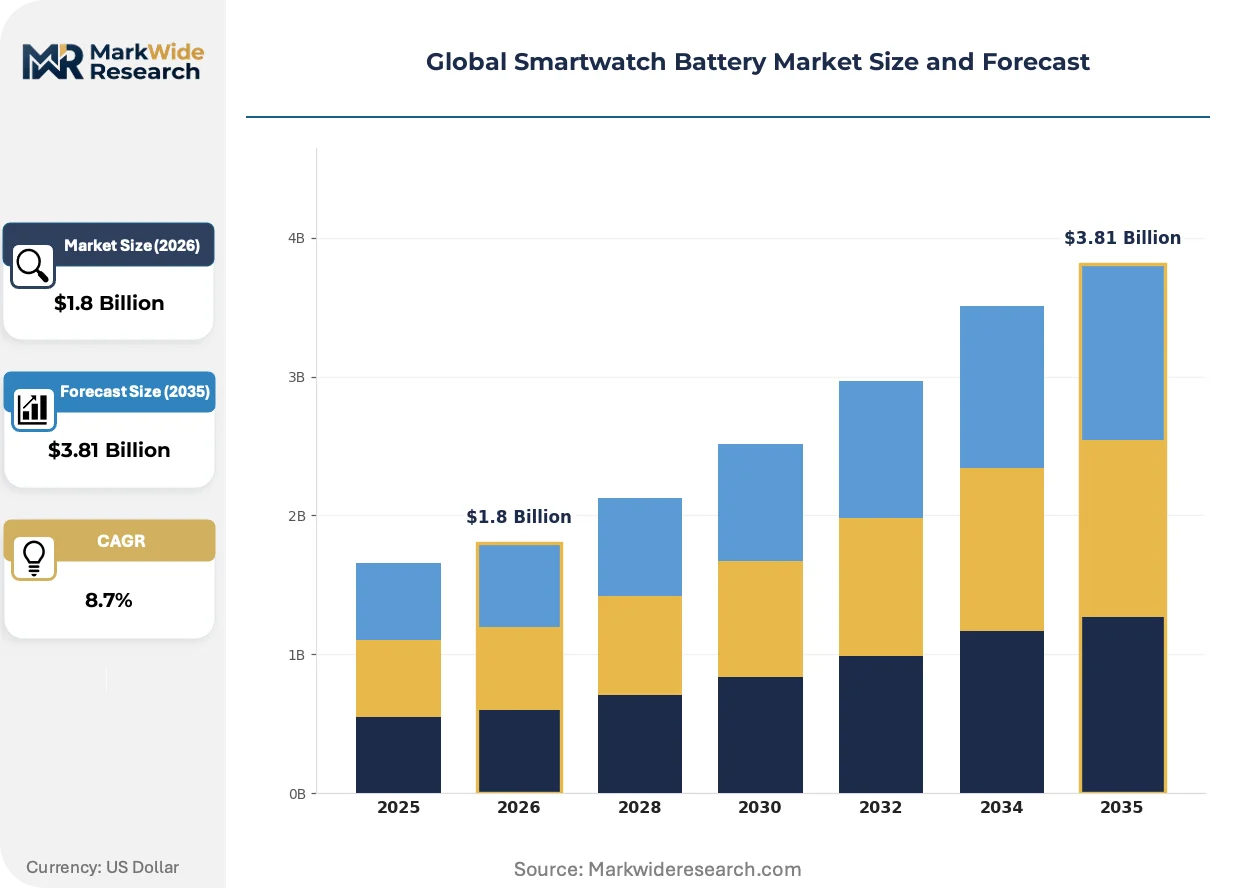
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lithium-Polymer, Nickel-Metal Hydride, Solid State Technology: Fast Charging, Wireless Charging, Solar Charging, Traditional Charging Use Case: Fitness Tracking, Sleep Monitoring, Navigation, Communication End User: Consumer Electronics, Fitness Enthusiasts, Professionals, Tech Savvy Users |
| Companies Covered | Grepow Battery, CATL, Samsung SDI Co., Ltd, BYD Company Limited, LG Energy Solution, Apple Inc., Enovix Corporation, Panasonic Energy, EVE Energy Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartwatch Battery Market Strategic Shifts
Silicon-anode integration is compressing the performance gap between cylindrical and pouch formats, while regulatory pressure on supply chain transparency is forcing material provenance upgrades. These forces are converging to reshape qualification protocols and buyer-supplier contracting structures.
Solid-state lithium-metal cells are unifying energy density and safety performance in wearable power systems. Premium fitness-tracking OEMs are accelerating qualification programs for thiophosphate electrolyte architectures. This unification is collapsing the traditional trade-off between compact form factors and thermal stability that has constrained medical-wearable designs.
China's GB 31241-2022 safety standard revision is tightening cycle-life verification and nail-penetration testing protocols for lithium-ion cells. Domestic packagers must now submit extended thermal abuse documentation to SAMR before market authorization. Premium smartwatch brands with China assembly exposure are consolidating supplier lists to pre-qualified cell producers with in-house testing laboratories.
Direct long-term contracting between wearable OEMs and cathode active material producers is displacing spot-market purchasing for cobalt and nickel-manganese formulations. Tier-one fitness device manufacturers in Shenzhen and Cupertino are locking 36-month supply agreements to insulate against EV sector demand surges. This pattern is most visible in procurement departments managing cellular-enabled smartwatch lines with 500mAh+ capacity requirements.
Global Smartwatch Battery Market Segmentation
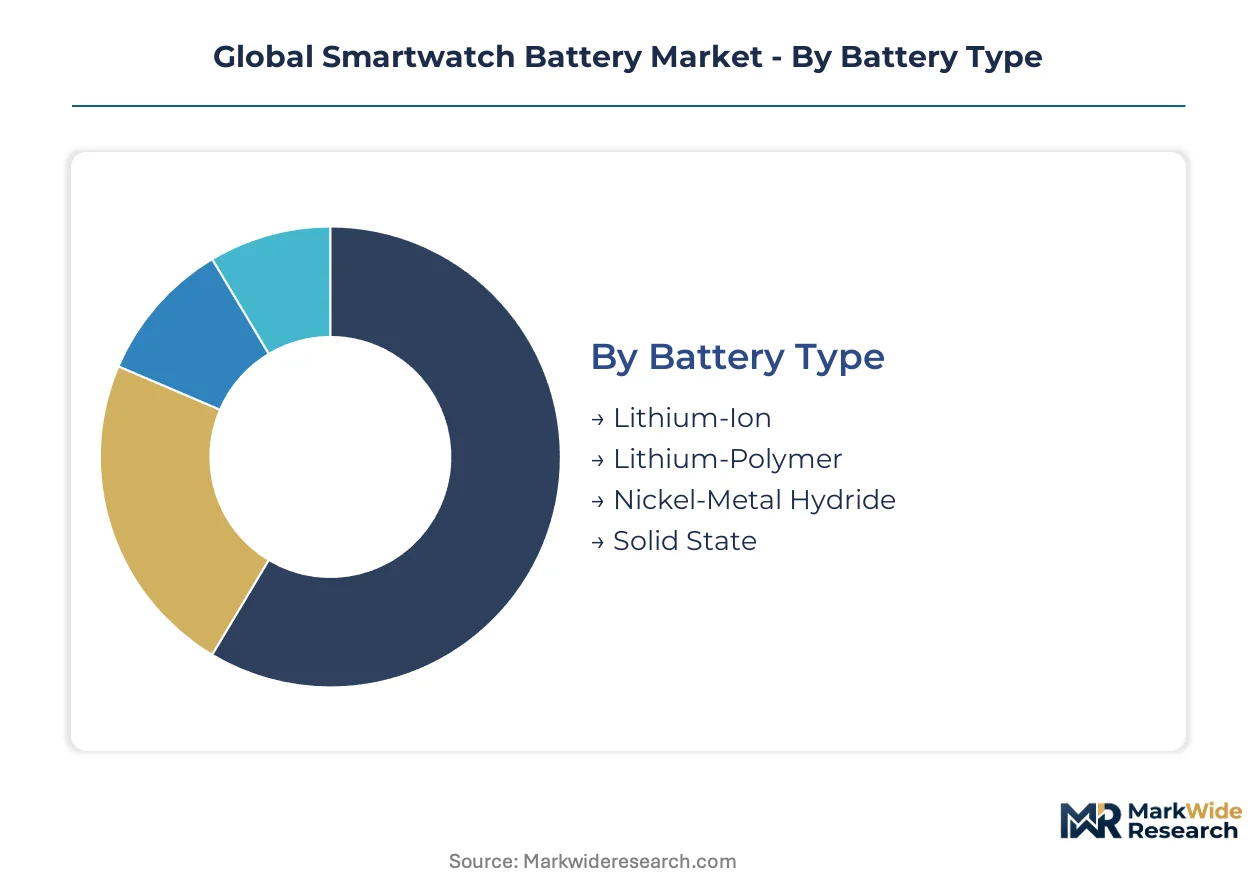
Smartwatch battery procurement patterns diverge sharply across chemistry formats and charging architectures. Segment boundaries determine supplier qualification protocols, certification requirements, and margin structures for wearable power systems.
Battery Type:
Supply concentration for cathode active materials and electrolyte formulations varies dramatically across chemistry families, reshaping sourcing geography and vertical integration incentives.
- Lithium-Ion:Cylindrical 18650 and 21700 formats with cobalt-nickel-manganese cathodes deliver stable 3.7V output for cellular-enabled smartwatches. Demand concentrates with premium consumer electronics brands in Cupertino and Shenzhen pursuing 500mAh+ capacities for GPS-heavy use cases, though cobalt price volatility compresses margins for mid-tier suppliers.
- Lithium-Polymer:Flexible pouch geometries with gel polymer electrolytes enable sub-5-gram enclosures that conform to wrist-worn form factors. Procurement from fitness-tracking OEMs in Vietnam and India is accelerating as domestic assembly lines require localized pouch cell sourcing under BIS certification timelines.
- Nickel-Metal Hydride:Lower energy density chemistry retains niche positioning in cost-optimized children's wearables and basic timekeeping devices with minimal sensor loads.
- Solid State:Thiophosphate and oxide ceramic electrolytes eliminate thermal runaway risks while doubling volumetric energy density. Pilot line yield gaps at Korean and Japanese producers delay mass adoption despite premium brand qualification programs.
Today's leader: Lithium-Polymer. Tomorrow's challenger: Solid State.
Technology:
Charging speed capabilities now function as primary purchase criteria, with downtime tolerance compressing to under sixty minutes across fitness and medical wearable segments.
- Fast Charging:Silicon-anode architectures and advanced battery management systems enable 0-80% charge cycles in 45 minutes. Premium smartwatch brands in Shenzhen are locking multi-year supply agreements with cell producers offering 2C+ charge rates.
- Wireless Charging:Inductive coil integration eliminates port corrosion risks for swim-proof devices. Adoption concentrates with lifestyle-oriented consumer electronics lines where aesthetic minimalism overrides cost premiums.
- Solar Charging:Amorphous silicon and gallium arsenide photovoltaic layers extend operational windows for outdoor navigation wearables. Garmin and Suunto procurement teams specify minimum 10% daily charge supplementation for expedition-tier devices.
- Traditional Charging:Pogo pin and magnetic dock interfaces persist in price-sensitive tiers where component cost minimization outweighs convenience premiums.
Fast Charging commands the steepest expansion trajectory as fitness OEMs prioritize workout-to-workout turnaround times.
Use Case:
Application-specific power profiles dictate cell selection, with GPS and cellular modules imposing high-pulse discharge demands that strain conventional lithium-polymer formulations.
- Fitness Tracking:Continuous heart rate and SpO2 monitoring requires sustained 50-100mA baseline draw with periodic 500mA+ spikes for GPS track logging. India's domestic wearable assembly surge is concentrating procurement for 200-300mAh cells with 5-day runtime targets.
- Sleep Monitoring:Ultra-low power architectures with sub-10µA sleep currents enable overnight wear without charging interruptions. Medical-grade device manufacturers specify 10-year shelf stability for FDA-cleared continuous glucose monitoring integrations.
- Navigation:Dual-frequency GPS and GLONASS reception demands 1A+ pulse capability that favors cylindrical lithium-ion formats over flexible pouches.
- Communication:LTE-M and NB-IoT cellular modules impose 2A+ transmit bursts that accelerate capacity fade without optimized cathode formulations.
Fitness Tracking anchors current volume. Sleep Monitoring is climbing the fastest as medical-wearable convergence deepens.
End User:
Buyer sophistication and price elasticity create distinct procurement channels, with enterprise and healthcare segments imposing qualification barriers that filter commodity suppliers.
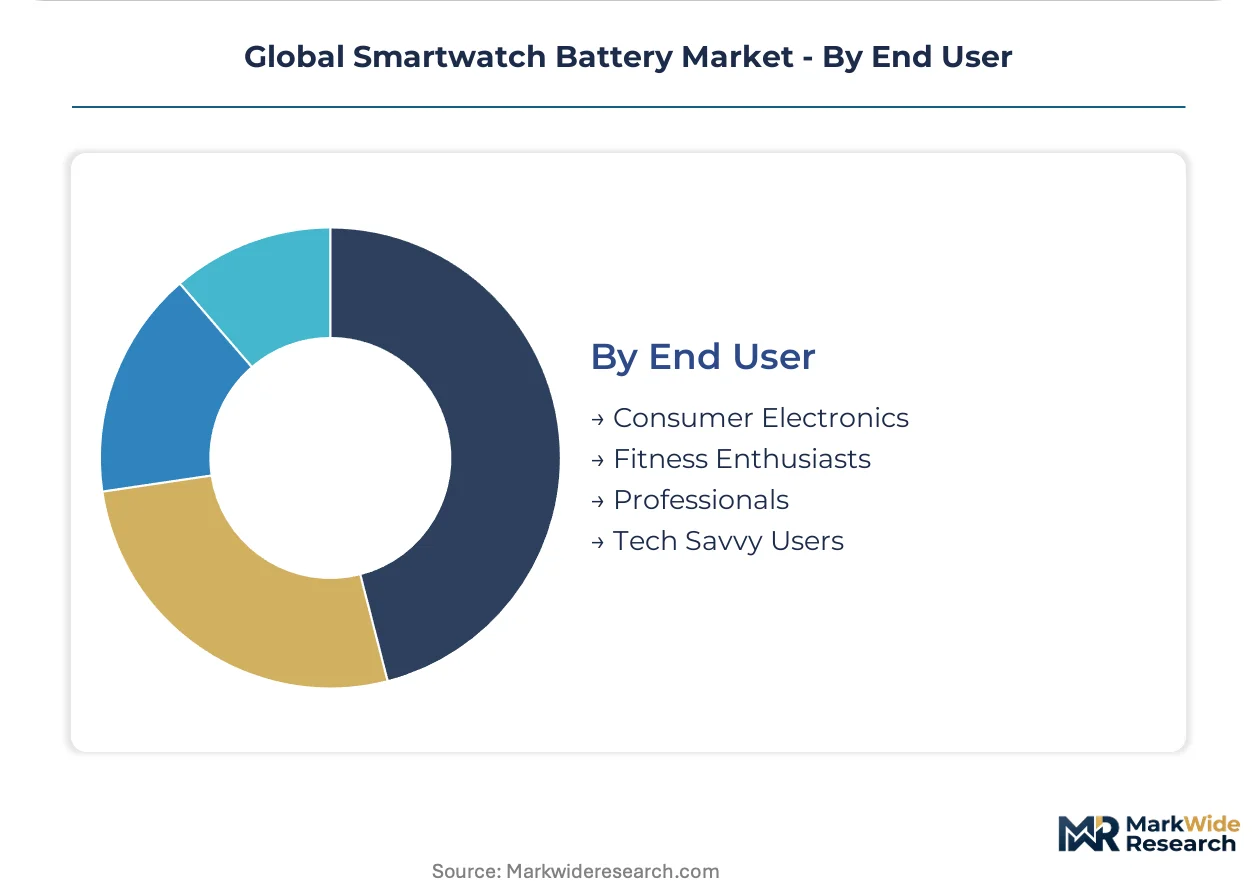
- Consumer Electronics:Mass-market smartwatch brands with 10M+ annual shipments negotiate tiered pricing based on volume commitments and exclusive supply arrangements. Apple's captive procurement from Samsung SDI and ATL sets benchmark terms for the segment.
- Fitness Enthusiasts:Specialized sports watch manufacturers prioritize runtime and durability over absolute thinness, accepting 8-10mm device profiles for multi-week expedition capability.
- Professionals:Healthcare, logistics, and field service deployments require IEC 60601-1 medical safety certification or ATEX intrinsically safe ratings that extend supplier qualification timelines by 6-9 months.
- Tech Savvy Users:Early adopter segments tolerate beta-grade solid-state cells and experimental charging architectures in exchange for performance bragging rights.
Consumer Electronics dominates revenue concentration. Professionals represent the most defensible margin tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic wearable assembly lines outpace India's emerging procurement hubs by a factor of three, yet India's BIS certification acceleration is compressing import timelines for Vietnam-based fitness OEMs. Battery packagers must navigate diverging regulatory velocities across these manufacturing poles.
China
Domestic smartwatch brands in Shenzhen and Dongguan consume cylindrical and pouch cells for 500mAh+ GPS-enabled devices. SAMR's GB 31241-2022 revision mandates extended thermal abuse documentation before market authorization. The Yangtze River Delta cluster hosts pre-qualified cell producers with in-house testing laboratories serving premium electronics assemblers.
India
Fitness-tracking OEM procurement is concentrating in Tamil Nadu and Karnataka as domestic wearable assembly accelerates. BIS certification mandates safety testing for imported cells, filtering low-specification suppliers from procurement lists. Chennai-based packagers leverage tariff-advantaged sourcing under localized cell testing infrastructure expansion.
United States
Premium consumer electronics brands in Cupertino negotiate tiered pricing based on volume commitments and exclusive supply arrangements. FDA clearance requirements for continuous glucose monitoring smartwatches impose 10-year shelf stability specifications on ultra-low self-discharge cells. The Austin semiconductor corridor attracts battery management system designers serving medical-wearable convergence.
South Korea
Korean chemical conglomerates control over 70% of high-grade separator film production, creating single-source vulnerability for European packagers. METI-aligned solid-state pilot lines target thiophosphate electrolyte architectures for premium fitness brand qualification. The Suwon-Gwangju industrial belt concentrates ceramic electrolyte sintering expertise among fewer than 200 global specialists.
Germany
EU Battery Regulation traceability mandates accelerate investments in supply chain visibility platforms among contract manufacturers. ECHA's REACH and RoHS frameworks restrict hazardous substances in battery assemblies sold across member states. Bavaria's automotive battery research centers transfer solid-state manufacturing protocols to wearable-scale production.
Global Smartwatch Battery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across chemistry formats and charging architectures. The vendor base organizes into three tiers: captive electronics ecosystem suppliers, independent cell producers with cylindrical expertise, and silicon-anode technology developers. Consolidation pressures intensify as fitness-tracking OEMs fragment demand while premium brands consolidate procurement power. Dominant competitive moves include strategic partnerships for solid-state pilot line access and geographic expansion into India BIS-certified manufacturing corridors.
Within the diversified conglomerate tier, CATL and BYD Company Limited occupy positions anchored by cylindrical cell expertise and captive demand integration. Samsung SDI Co., Ltd exemplifies ecosystem-locked supply architecture, while Enovix Corporation sits within the silicon-anode specialization vector. These three entities represent divergent strategic postures: scale-driven chemistry breadth, affiliated device ecosystem capture, and advanced material architecture differentiation.
| Leading Market Players |
|---|
| Grepow Battery |
| CATL |
| Samsung SDI Co., Ltd |
| BYD Company Limited |
| LG Energy Solution |
| Apple Inc. |
| Enovix Corporation |
| Panasonic Energy |
| EVE Energy Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Premium consumer electronics brands with 10M+ annual shipments negotiate tiered pricing based on volume commitments and exclusive supply arrangements, anchoring contract-based long-term offtake as the dominant pricing model across the smartwatch battery market.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for high-grade separator films while cobalt-nickel-manganese cathode cost volatility compresses margins for mid-tier suppliers. Pricing stratifies across premium silicon-anode cells with 2C+ charge rates, standard lithium-polymer pouches for fitness trackers, and economy cylindrical formats for basic wearables. Cost compression in the mid-tier intensifies because fitness-tracking OEMs fragment procurement across multiple suppliers. Consumer electronics giants with captive demand exhibit lowest price sensitivity; Vietnam-based wearable assemblers face highest pressure.
Supply Chain Analysis
Thin-film ceramic processing expertise concentrates in the Suwon-Gwangju industrial belt and select Japanese research corridors, constraining pilot line expansion for solid-state architectures. Manufacturing draws from China for lithium-polymer pouch cells, South Korea for separator films, and Japan for electrolyte formulations. Raw material dependencies center on cobalt from the DRC, nickel from Indonesia, and high-purity lithium carbonate from Chile. Single-source vulnerability pervades separator film procurement. Distribution runs through contract manufacturers in Shenzhen and Dongguan serving global OEM assembly networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartwatch battery market represents a late-cycle quality story as medical-wearable convergence drives demand toward FDA-cleared cells with 10-year shelf stability specifications.
For Market Incumbents: Extend backward integration into cathode active material production to insulate against EV sector demand surges that spike cobalt and nickel-manganese prices. Lock 36-month supply agreements with fitness-tracking OEMs in India before BIS certification timelines harden supplier lists. Solid-state manufacturing yield gaps threaten premium positioning if pilot lines fail to commercialize. For New Entrants and Emerging Players: Silicon-anode technology specialization offers entry into premium smartwatch brands seeking 40% capacity improvements without footprint expansion. Target medical-wearable convergence segments where FDA clearance requirements filter commodity competition and extend supplier qualification timelines. White-space exists in India BIS-certified domestic cell testing infrastructure. Go-to-market through Tamil Nadu industrial corridor partnerships with wearable assemblers accelerates tariff-advantaged procurement access. For Investors and Strategic Acquirers: Consumer electronics conglomerates with captive device ecosystems are the most active acquirers in this space, seeking to replicate Samsung SDI's affiliated demand model. Five-to-ten year viability hinges on solid-state chemistry transitions rather than incremental lithium-polymer optimization. Acquisition targets with thiophosphate electrolyte pilot lines and in-house GB 31241-2022 testing laboratories command scarcity premiums. Signal to monitor: FDA clearance timelines for continuous glucose monitoring smartwatches as inflection indicator for ultra-low self-discharge cell demand.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Investment | Thiophosphate electrolyte scale-up eliminates thermal runaway risks for premium fitness brands. |
| India BIS Certification Localization | Chennai testing infrastructure enables tariff-advantaged procurement for Vietnam-based fitness OEMs. |
| Silicon-Anode Capacity Expansion | Advanced lithiation techniques attract multi-year supply agreements from Shenzhen premium brands. |
| Backward Integration into Cathode Materials | Direct long-term contracting displaces spot-market purchasing for cobalt-nickel-manganese formulations. |
| Medical-Wearable Certification Investment | FDA-cleared continuous glucose monitoring integrations create 10-year shelf stability demand. |
Study Parameters
Bottom-up fitness-tracking and medical-wearable modeling reconciled against top-down cathode active material supply tracking forms the analytical core of this study. Primary interviews with battery packager procurement directors, OEM platform engineers, BIS certification consultants, and solid-state R&D leads combined with secondary validation from SAMR GB standard filings, ECHA REACH substance restrictions, FDA 510(k) clearance databases, and India DGFT import statistics. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of lithium-polymer pouch and cylindrical cell shipment patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include battery chemistry format, charging architecture, use case application, and end-user sophistication tier. CAGRs derived from fitted trend extrapolation adjusted for solid-state commercialization delays and regulatory certification timeline shifts. Industry-specific inputs incorporate cobalt price volatility indices and BIS laboratory expansion schedules.
The model holds under stable cobalt supply and gradual solid-state yield improvement; deviation in ceramic electrolyte sintering defect rates or India import tariff restructuring would shift volume and value trajectories. Forecasts reflect documented assumptions regarding SAMR enforcement intensity and EU Battery Regulation digital passport implementation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Camera Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Women's Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Wearable AI Devices Market