
 Kids Watch Market | 2026-2036
Kids Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Watch Market Foresight
Subscription-based parental control and location-monitoring services is realigning what families actually purchase beyond the hardware unit. Garmin leverages its GPS heritage to anchor premium positioning in outdoor-oriented family segments. Apple sustains ecosystem lock-in through tight iPhone integration and health-data continuity. BBK Electronics competes aggressively on price while extending distribution through Chinese e-commerce channels.
A kids watch is a wrist-worn timekeeping device engineered specifically for children, typically incorporating GPS receivers, cellular modems, accelerometers, and water-resistant enclosures rated between IP67 and 5ATM to enable location tracking, communication, and activity monitoring without requiring a paired smartphone. Smart variants now dominate value generation as parents prioritize two-way calling and geofencing over basic time display. GPS Tracking functionality commands the highest attach rates and renewal intensity across subscription tiers. The Preschool age bracket generates disproportionate replacement volume as children outgrow band sizes and feature needs within eighteen to twenty-four month cycles.
The FCC governs radio emissions and data privacy for connected wearables sold in the United States, while the EU AI Act and GDPR impose strict limits on biometric inference and parental consent architectures in European markets. China's SAMR enforces GB standard compliance for battery safety and electromagnetic compatibility in domestically manufactured units. Stakeholders must monitor how diverging data-localization mandates fragment cloud architecture requirements and force region-specific firmware builds.
Market Dynamics
Subscription bundling of GPS tracking and parental controls is restructuring unit economics away from hardware margins toward recurring revenue streams, forcing manufacturers to rebuild their go-to-market architectures around service retention rather than point-of-sale conversion.
Growth Catalysts
- COPPA Enforcement Intensification:The FCC's tightened children's privacy oversight is compelling vendors to invest in compliant data architectures, which paradoxically builds parent trust and reduces competitive churn from security incidents.
- Cellular Module Cost Compression:Declining LTE-M and NB-IoT chipset pricing is enabling two-way voice and real-time location at sub-premium price points, expanding addressable household penetration.
- Early School Age Demographic Expansion:Parents of children entering primary education represent the fastest-expanding buyer segment, driven by first-time independence needs and school policy communication requirements.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell manufacturing clusters heavily in East Asian supplier networks, exposing finished goods producers to input volatility and logistics bottlenecks.
- GDPR Biometric Inference Limits:The EU AI Act and GDPR impose strict constraints on heart-rate and behavioral inference algorithms, forcing region-specific firmware branches that fragment development resources.
- Smartphone Substitution Threat:Falling entry-level smartphone pricing and parental hand-me-down patterns erode the standalone kids watch value proposition for children above age ten.
Strategic Opportunities
- South Korean Digital Natives:High technology acceptance rates and dual-income household density create fertile ground for premium-tier subscription services with advanced geofencing.
- Health-Data Continuity Convergence:Integration between pediatric activity metrics and family health platforms is opening cross-sell pathways into insurance wellness programs.
- German Retail Channel Innovation:Electronics specialty chains are experimenting with bundled activation services that reduce parent setup friction and improve first-month retention rates.
Industry Challenges
- FCC Certification Timeline Compression:Radio equipment authorization delays are extending product launch windows and compressing seasonal selling periods.
- Multi-Region Firmware Complexity:Diverging data-localization mandates between the United States, European Union, and China are fragmenting cloud architecture requirements and inflating engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Watch Market |
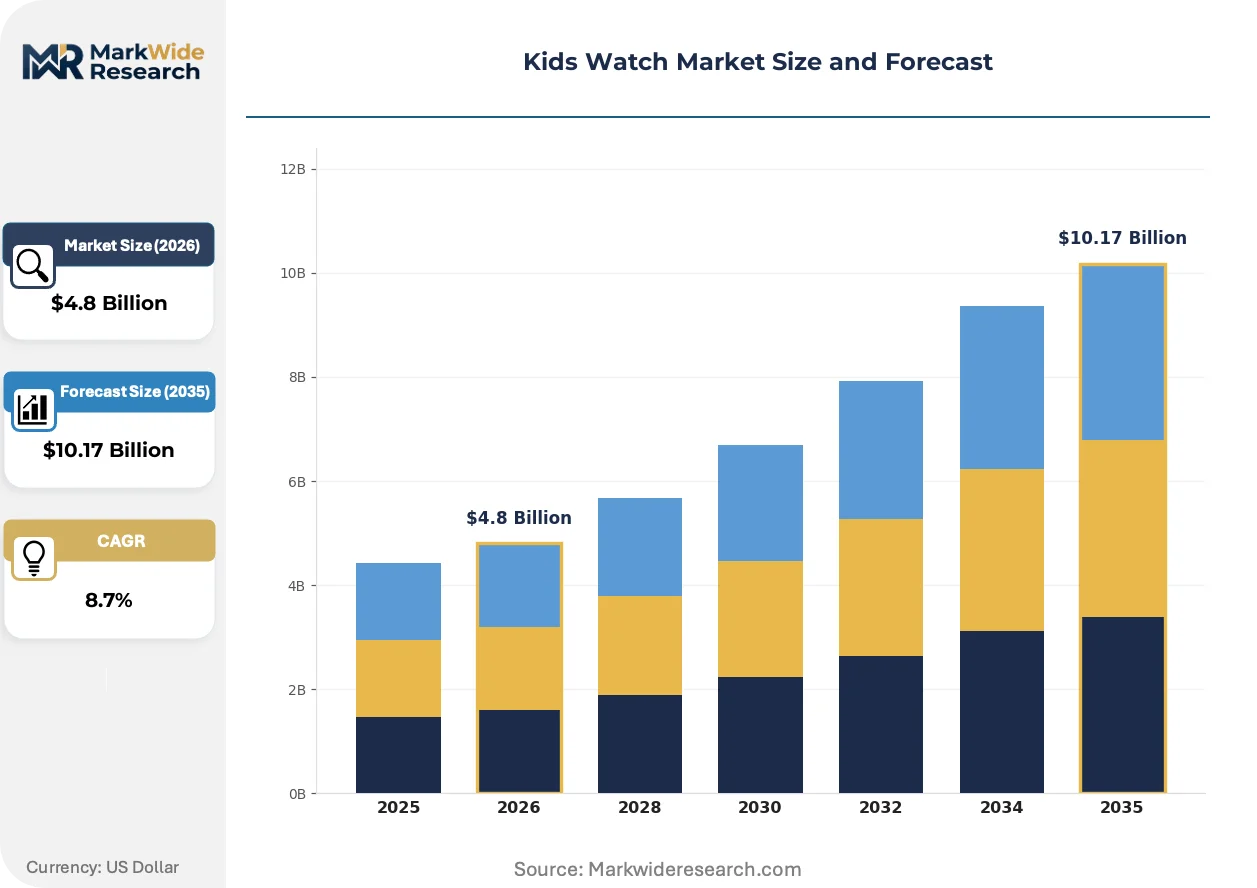
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Hybrid Feature: GPS Tracking, Fitness Monitoring, Waterproof, Alarm Function Age Group: Toddlers, Preschool, Early School Age, Teenagers Distribution Channel: Online Retail, Department Stores, Specialty Shops, Supermarkets |
| Companies Covered | Garmin, Apple, Xiaomi Corporation, Huawei Technologies, VTech Holdings, Fitbit, Xplora Technologies, Samsung, BBK Electronics (Imoo), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Watch Market Shifts & Advancements
Edge-based location processing and on-device AI inference are redistributing computational load away from cloud dependencies, altering how vendors architect subscription service tiers and parental dashboard responsiveness.
Ultra-wideband (UWB) positioning chips are decentralizing geofencing accuracy from cellular tower triangulation toward precise indoor location tracking. Parents of preschool-age children are adopting UWB-enabled models at accelerated replacement cycles. This technology is decentralizing the competitive moat from network coverage maps toward semiconductor integration depth.
The EU AI Act's prohibitions on biometric inference for minors are forcing algorithmic architecture redesigns across European-bound product lines. Vendors must now segment machine learning pipelines between regions, duplicating development tracks. Preschool-focused features requiring emotion or stress detection face the steepest compliance headwinds in Germany and France.
Direct-to-parent subscription onboarding is displacing retail-assisted activation as the dominant purchase completion pathway. Amazon and specialized parenting platforms are capturing an outsized share of initial setup and recurring billing relationships. This channel rotation is most pronounced in the United States, where carrier retail dependence has historically anchored distribution economics.
Kids Watch Market Segmentation
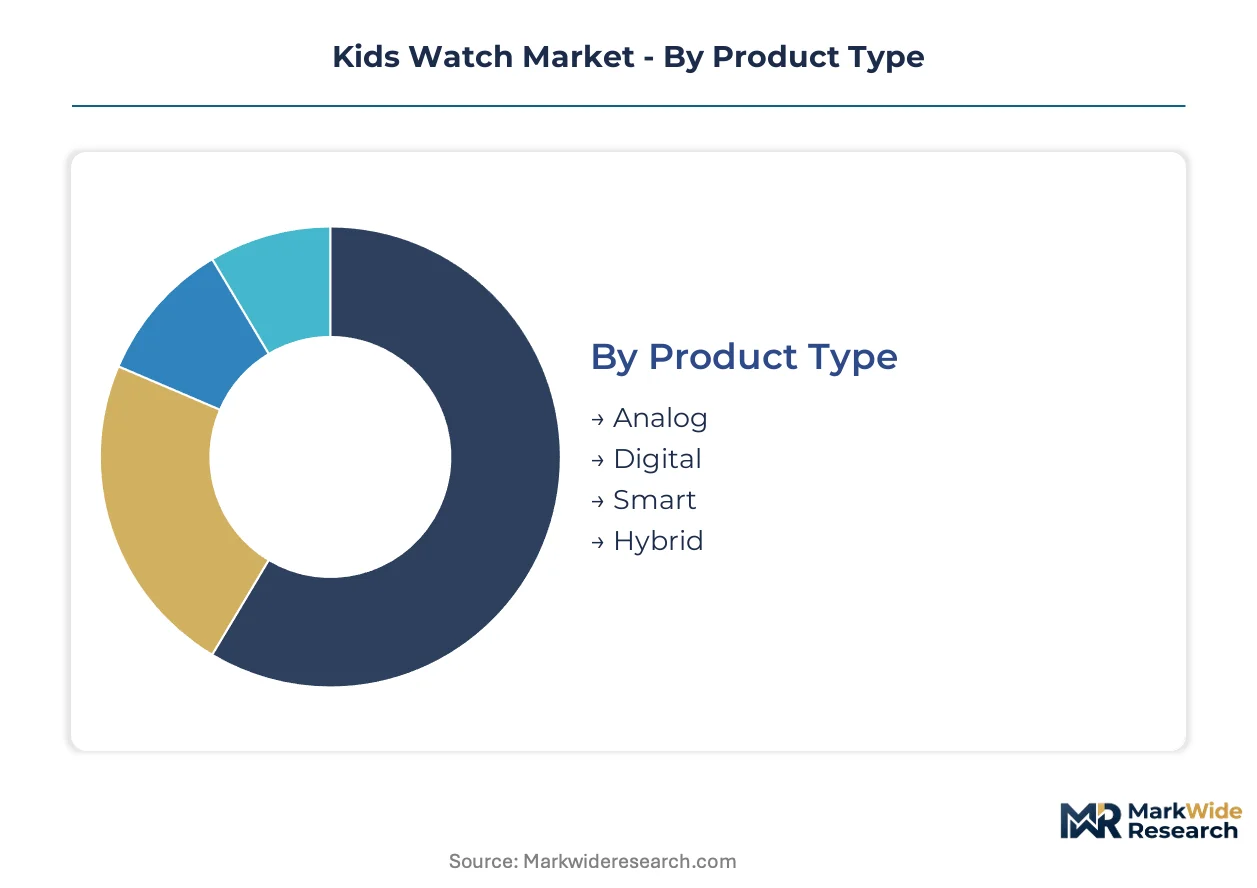
Segmentation in the kids watch market reveals how purchasing decisions bifurcate between safety-driven functionality and developmental appropriateness. Parents evaluate hardware durability against subscription service depth, creating distinct value tiers that manufacturers must address through differentiated product architectures.
Product Type:
Price-to-feature ratio determines household penetration across income brackets, with cellular connectivity serving as the primary cost escalator.
- Smart:Cellular-enabled wrist-worn devices integrate GPS receivers, two-way voice calling, and geofencing through embedded LTE-M modems. Parents of early school age children in the United States and South Korea concentrate demand here, driven by first-time independence needs and school communication policies.
- Digital:Electronic time displays with basic activity tracking and limited parental controls occupy the mid-market without recurring subscription requirements. German and South Korean retail channels move significant volume through electronics specialty chains bundling activation support.
- Analog:Traditional mechanical or quartz movements without electronic components address parents seeking minimal screen exposure for toddlers. Water-resistant enclosures rated to 5ATM satisfy poolside durability expectations.
- Hybrid:Mechanical watch faces conceal limited smart functionality such as step counting or Bluetooth-tethered notifications. This format attracts parents transitioning children away from full smart devices as they approach teenage years.
Smart leads on scale; Hybrid leads on momentum as smartphone hand-me-downs pressure the upper age bracket.
Feature:
Service attach rates vary dramatically by functional category, reshaping how vendors structure recurring revenue against hardware margins.
- GPS Tracking:Real-time location monitoring through multi-constellation satellite receivers commands the highest subscription renewal intensity across all tiers. FCC COPPA compliance investments by vendors paradoxically build parent trust and reduce churn from security incidents in the United States.
- Fitness Monitoring:Accelerometer-based step counting and activity goal-setting integrate with family health platforms for insurance wellness program cross-sells. GDPR biometric inference limits under the EU AI Act constrain heart-rate algorithm deployment in Germany and France.
- Waterproof:IP67 to 5ATM enclosure ratings enable swimming and bathing without device removal, a non-negotiable specification for preschool-age replacement cycles.
- Alarm Function:Programmable reminders and silent vibration alerts support medication schedules and routine establishment for children with developmental needs.
GPS Tracking leads on scale; Fitness Monitoring leads on momentum through health-data platform convergence.
Age Group:
Physical growth velocity and behavioral independence milestones dictate replacement frequency and feature complexity requirements.
- Early School Age:Children entering primary education generate the fastest-expanding buyer segment as parents confront first-time unsupervised travel and school communication gaps. Cellular-enabled models with geofencing dominate this cohort in the United States and South Korea.
- Preschool:Rapid wrist circumference growth and evolving durability needs produce eighteen-to-twenty-four month replacement cycles, the shortest in the market. UWB positioning chips are gaining traction among this group for precise indoor location tracking.
- Toddlers:Basic time-telling introduction and proximity alerts for parental peace of mind characterize this entry segment, with minimal subscription penetration.
- Teenagers:Smartphone substitution threat intensifies as falling entry-level handset pricing and hand-me-down patterns erode standalone watch value propositions above age ten.
Early School Age leads on scale; Preschool leads on momentum through accelerated replacement velocity.
Distribution Channel:
Channel economics are restructuring as direct-to-parent digital onboarding displaces retail-assisted activation.
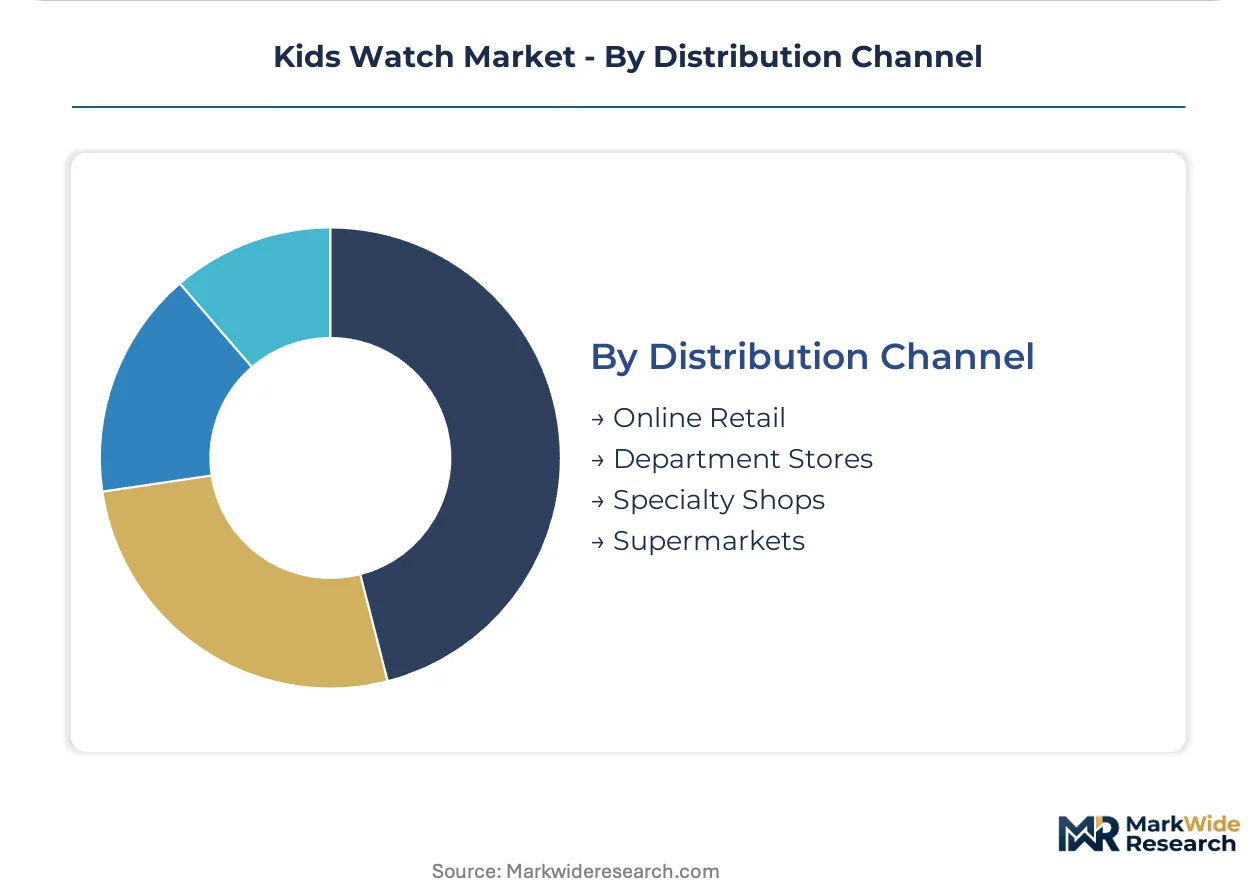
- Online Retail:Amazon and specialized parenting platforms capture outsized shares of initial setup and recurring billing relationships, particularly pronounced in the United States where carrier retail dependence historically anchored distribution.
- Specialty Shops:Electronics chains in Germany experiment with bundled activation services that reduce parent setup friction and improve first-month retention rates.
- Department Stores:Mid-tier family retailers maintain presence for gift-purchase occasions and in-person band fitting, though attach rates for subscription services lag digital channels.
- Supermarkets:Mass-market grocery and hypermarket chains move basic digital and analog models on promotional pricing with minimal service bundling.
Online Retail leads on scale; Specialty Shops leads on momentum through experiential service innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates higher subscription renewal intensity for GPS-enabled models than Germany, where GDPR biometric limits constrain feature deployment. South Korean dual-income households adopt premium tiers faster than any other market.
United States
Parents of early school age children drive cellular-enabled watch adoption as first-time independence needs intersect with school communication policies. FCC COPPA enforcement compels vendors to invest in compliant data architectures, paradoxically building parent trust. Silicon Valley hardware startups and Seattle-based cloud service providers anchor the domestic vendor ecosystem.
Germany
Electronics specialty chains experiment with bundled activation services that reduce parent setup friction and improve first-month retention rates. The EU AI Act and GDPR impose strict constraints on heart-rate and behavioral inference algorithms, forcing region-specific firmware branches. Bavaria's precision engineering clusters supply water-resistant enclosure components rated to 5ATM.
South Korea
High technology acceptance rates and dense dual-income household concentration create fertile ground for premium-tier subscription services with advanced geofencing. MFDS regulations govern wearable device safety certifications for domestic distribution. Seoul Capital Area retailers capture disproportionate volume through direct-to-parent digital onboarding channels.
China
BBK Electronics extends distribution through domestic e-commerce channels while competing aggressively on hardware pricing. SAMR enforces GB standard compliance for battery safety and electromagnetic compatibility in locally manufactured units. Shenzhen's electronics manufacturing ecosystem concentrates lithium-polymer cell sourcing and LTE-M module assembly.
Japan
Parents prioritize minimal screen exposure for toddlers, sustaining demand for analog and hybrid formats. METI standards guide electromagnetic compatibility testing for connected wearables. Tokyo-based consumer electronics retailers maintain strong gift-purchase positioning for mid-tier digital models.
Kids Watch Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated technology firms capturing premium tiers while volume-oriented OEMs dominate price-sensitive entry points. The vendor base concentrates around three strategic archetypes: GPS heritage specialists leveraging outdoor positioning credibility, smartphone ecosystem anchors exploiting platform lock-in, and Chinese electronics conglomerates optimizing manufacturing scale. Competitive moves center on subscription service bundling to escape hardware margin compression and multi-region firmware segmentation to satisfy diverging data-localization mandates.
Within the ecosystem-integrated tier, Apple and Samsung exemplify platform lock-in strategies through tight smartphone integration and health-data continuity. Garmin occupies a position among GPS heritage specialists, anchoring premium positioning in outdoor-oriented family segments. BBK Electronics sits within the manufacturing-scale tier, represented by its Imoo brand competing aggressively on price while extending distribution through Chinese e-commerce channels.
| Leading Market Players |
|---|
| Garmin |
| Apple |
| Xiaomi Corporation |
| Huawei Technologies |
| VTech Holdings |
| Fitbit |
| Xplora Technologies |
| Samsung |
| BBK Electronics (Imoo) |
| Others |
Supply & Pricing Matrix
Captive integration into Shenzhen-based lithium-polymer cell production anchors both supply security and margin structure for smart kids watch vendors, with BBK Electronics and domestic peers leveraging in-house battery assembly to undercut modular competitors on hardware pricing while funding subscription service losses.
Pricing Analysis
Capacity additions in China's LTE-M module foundries are reshaping price floors for cellular-enabled models, compressing entry-tier hardware margins and forcing subscription bundling as the dominant pricing model. Price differentiation hinges on FCC COPPA certification tier and geofencing algorithm sophistication. Cost compression in NB-IoT chipsets is intensifying because MediaTek and UNISOC are ramping 12-inch wafer output. Mass-market parents in supermarket channels exhibit highest price sensitivity; dual-income households in Seoul tolerate premium recurring fees.
Supply Chain Analysis
Direct-to-parent digital channels handle hyperscale demand from Amazon and specialized parenting platforms, bypassing traditional electronics retail markups. Manufacturing concentrates in China, South Korea, and Vietnam. Component sourcing draws from Taiwanese semiconductor foundries, Japanese precision motion sensors, and domestic Chinese enclosure molding. Single-source vulnerability in rare-earth magnet supply for vibration motors threatens production continuity. Distribution runs through cross-border e-commerce fulfillment centers with regional firmware flashing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's SAMR battery safety certification costs and Germany's EU AI Act compliance burdens creates divergent margin structures, rewarding vendors with modular firmware architectures that segment development tracks without duplicating hardware platforms.
For Market Incumbents: Acquire edge-AI inference IP to reduce cloud dependency and COPPA audit surface area. Incumbents must consolidate around subscription retention metrics rather than hardware shipment volume as smartphone hand-me-downs erode the teenage segment. Backward integration into UWB chip sourcing secures indoor positioning moats against GPS-heritage specialists. For New Entrants and Emerging Players: MFDS streamlined wearable certification in South Korea opens a window for premium-tier launches with advanced biometric features prohibited in EU markets. White-space exists in preschool-focused UWB-enabled models with accelerated replacement cycles. Target German specialty retail channels with bundled activation services that reduce parent onboarding friction. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-region firmware complexity fragments engineering resources across mid-tier vendors. Long-term viability favors platforms with health-data continuity integrations into insurance wellness programs. Watch for FCC certification timeline compression as inflection signal indicating vendor ecosystem distress.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Inference Integration | On-device processing reduces COPPA cloud audit exposure and improves parental dashboard latency. |
| Multi-Region Firmware Segmentation | Separate ML pipelines for EU AI Act compliance versus US feature deployment optimize regulatory capital. |
| UWB Chip Supply Agreement | Precision indoor positioning differentiates preschool models from cellular-triangulation competitors. |
| Direct-to-Parent Subscription Onboarding | Amazon and parenting platforms capture recurring billing relationships formerly held by carrier retail. |
| Health-Data Platform Integration | Pediatric activity metrics feed insurance wellness programs opening cross-sell revenue pathways. |
Research Methodology
Multiple input streams — vendor shipment disclosures, carrier activation records, and parental subscription renewal databases — were reconciled against secondary validation from FCC equipment authorization filings and EU CE marking registries. Primary interviews with product managers at GPS heritage specialists, regulatory affairs leads at smartphone ecosystem vendors, procurement directors at Chinese e-commerce platforms, and subscription service heads at parenting technology firms informed demand-side assumptions. Secondary sources included SAMR GB standard compliance bulletins, MFDS wearable safety certifications, and customs records for LTE-M module trade flows. Bottom-up unit shipment estimates triangulated against top-down household penetration models across income brackets.
Historical subscription attach rates were cross-referenced against panel input from parental focus groups in the United States, Germany, and South Korea to inform projection parameters. Segmentation modeling incorporated product type (smart, digital, analog, hybrid), age group cohorts, feature bundling tiers, and regional regulatory clusters. CAGRs were derived from logistic diffusion curves fitted to early school age demographic expansion patterns. Industry-specific inputs included replacement cycle velocity for preschool band sizing and geofencing service renewal intensity by subscription tier.
Revisions become necessary when COPPA enforcement actions, EU AI Act biometric inference rulings, or lithium-polymer supply disruptions materialize outside baseline assumptions. Forecasts reflect documented assumptions about cellular module cost compression trajectories and dual-income household formation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Europe Watch Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Latin America Smartwatch Market