
 Wearable Electronics Market | 2026-2036
Wearable Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Electronics Market Intelligence
Healthcare end-user demand is rebalancing the Wearable Electronics Market as clinical-grade monitoring displaces consumer fitness tracking. Samsung Electronics leverages its semiconductor supply chain to sustain component cost advantages across smartwatch SoCs. Garmin Ltd. anchors its position in sports performance through GPS-differentiated hardware and aviation-grade durability standards. Xiaomi Corporation competes on manufacturing scale, occupying the entry-tier price band in India and Southeast Asia.
Wearable electronics encompass body-mounted devices integrating sensors, microprocessors, and wireless transceivers to capture physiological or environmental data for real-time feedback or longitudinal analysis. These systems typically employ photoplethysmography for heart rate, accelerometry for motion, and Bluetooth Low Energy for sub-10mW data transmission to paired hosts. Smart watches and wearable medical devices capture the dominant margin pools, with the former maturing on replacement cycles and the latter accelerating on FDA 510(k) and EU MDR Class IIa clearances. Fitness trackers face compression as health monitoring functionality migrates upward into smartwatches and downward into smartphone-integrated applications.
FDA device classification rules and EU MDR conformity requirements determine market access timelines and clinical claim permissibility for wearable medical devices. ISO 13485 quality management standards and IEC 60601-1 electrical safety benchmarks constrain design architectures for vendors targeting regulated health segments. Stakeholders must monitor whether HIPAA-aligned data governance frameworks expand liability exposure for consumer-grade devices processing protected health information.
Market Dynamics
Clinical validation requirements are compressing development timelines for wearable medical devices as FDA 510(k) pathways tighten evidentiary standards for software-as-medical-device claims.
Growth Catalysts
- EU MDR Class IIa clearance pathways:Accelerated market access for continuous glucose monitoring and cardiac arrhythmia detection devices enables premium pricing in European reimbursement systems.
- Photoplethysmography sensor miniaturization:Reduced power consumption below 500µW enables multi-day battery life in ring and patch form factors, expanding addressable use cases.
- Remote patient monitoring:Medicare reimbursement codes in the United States now cover physiologic data transmission from home-based wearable systems, institutionalizing clinical workflow integration.
Market Restraints
- Advanced node semiconductor access:5nm and 3nm foundry capacity concentration in Taiwan constrains SoC supply for AI-enabled wearables, extending lead times.
- Lithium-polymer cell chemistry:Energy density plateauing at 250Wh/kg limits device autonomy despite compute demands rising with on-device inference workloads.
- FDA software pre-certification:Predicate device requirements for algorithm updates create regulatory friction for machine learning-enabled diagnostic features.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for wearable assembly attract component suppliers to Chennai and Noida industrial corridors.
- Non-invasive glucose monitoring:Spectroscopic sensing convergence with machine learning models addresses the largest unmet need in metabolic disease management.
- Specialty pharmacy distribution:Dispensing wearable medical devices through CVS and Walgreens clinics embeds hardware into pharmaceutical care pathways.
Industry Challenges
- Biomedical algorithm validation:FDA demands for prospective clinical trials to support cardiovascular diagnostic claims extend development cycles by 18-24 months.
- ISO 13485 quality system implementation:Medical device-grade documentation and supplier controls require organizational transformation for consumer electronics vendors.
- Legacy EHR integration:HL7 FHIR connectivity gaps force custom API development for each health system deployment, fragmenting technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Electronics Market |
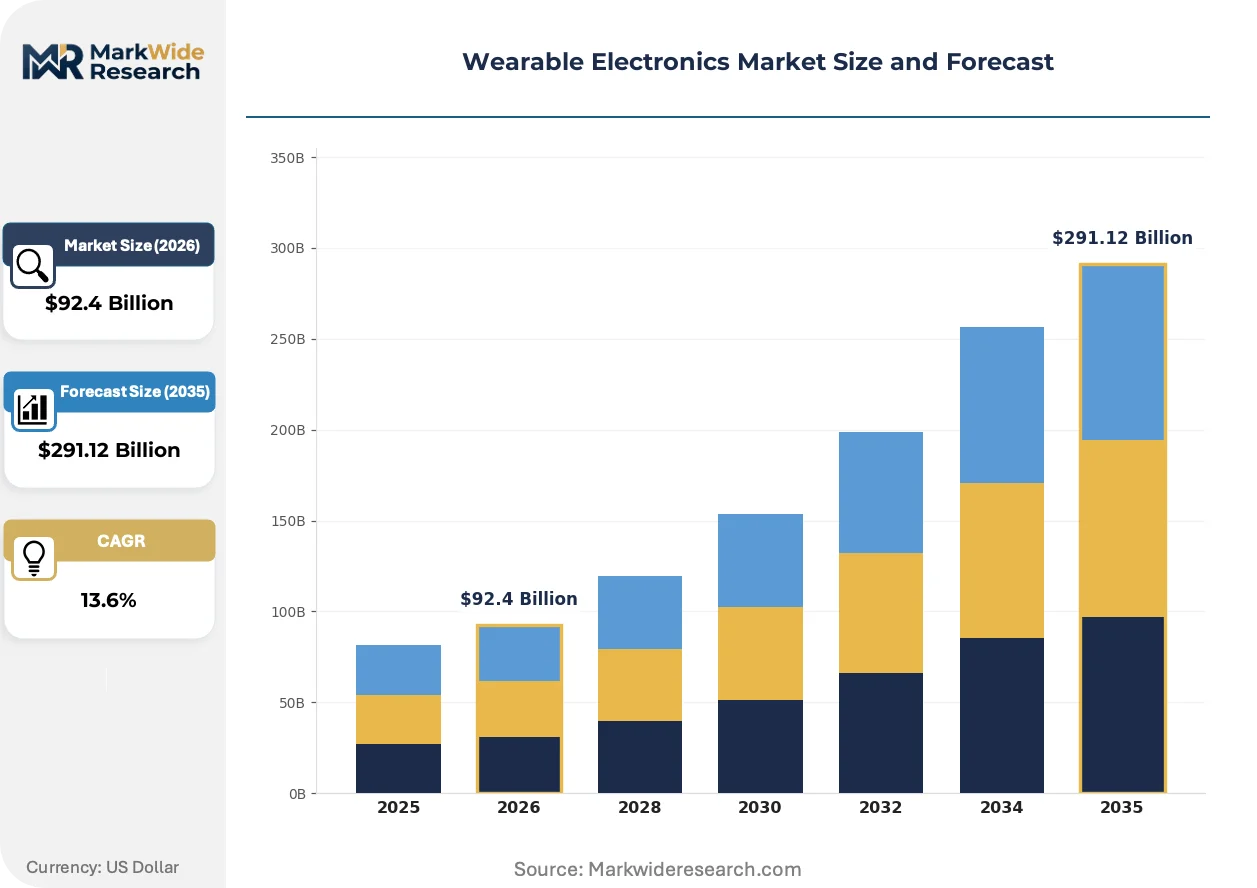
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $291.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Watches, Fitness Trackers, Smart Glasses, Wearable Medical Devices Technology: Bluetooth, NFC, Wi-Fi, GPS Application: Health Monitoring, Fitness Tracking, Sports Performance, Sleep Tracking End User: Individual Consumers, Healthcare Professionals, Athletes, Enterprises |
| Companies Covered | Apple Inc., Samsung Electronics, Fitbit (Google LLC), Xiaomi Corporation, Huawei Technologies Co. Ltd., Garmin Ltd., Imagine Marketing Limited, Sony Corporation, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Electronics Market Strategic Shifts & Innovations
Silicon photonics and edge AI architectures are redefining sensor fusion capabilities, enabling diagnostic-grade measurements from consumer-accessible form factors.
Photoplethysmography with multi-wavelength LED arrays is consolidating blood pressure estimation and arterial stiffness assessment into single-sensor modules. Cardiology departments in Germany and the United States are piloting these systems for hypertension management programs. This consolidation is compressing the market for standalone ambulatory blood pressure monitors.
FDA's software pre-certification pilot for AI/ML-enabled devices is tightening quality management requirements while streamlining post-market update pathways. Predicate device substantiation now demands real-world performance data rather than bench testing alone. Cardiac monitoring wearables face the steepest compliance burden as arrhythmia detection claims trigger Class II controls.
Enterprise procurement of wearable fleets for workforce health programs is displacing individual consumer purchases in mining, logistics, and manufacturing verticals. Mining operators in Australia and Canada now mandate fatigue-monitoring wearables for haul truck operators. This channel rotation concentrates volume with industrial distributors at the expense of retail electronics channels.
Wearable Electronics Market Segmentation
Wearable electronics segmentation reveals how hardware specifications, connectivity standards, and user workflows fragment addressable value pools. Technical differentiation in sensor arrays and wireless protocols determines margin capture across clinical and consumer use cases.
Device Type:
Form factor specifications dictate power budgets, sensor complement, and regulatory pathway complexity for wearable hardware vendors.
- Smart Watches:Multi-sensor platforms integrating PPG, accelerometry, and ECG electrodes dominate wrist-worn health monitoring. Demand concentrates in the United States and Germany as FDA 510(k) and EU MDR clearances enable clinical-grade arrhythmia detection claims.
- Fitness Trackers:Stripped-down accelerometer and optical heart rate modules serve calorie estimation and step counting at sub-$50 price points. Indian and Southeast Asian consumers drive volume as Xiaomi and local brands exploit manufacturing scale advantages.
- Smart Glasses:Waveguide displays and micro-projectors overlay contextual data for enterprise field technicians and logistics operators. Industrial procurement in Germany and Japan favors ANSI Z87.1 safety-rated optical systems.
- Wearable Medical Devices:ISO 13485-certified continuous glucose monitors and cardiac event recorders require predicate device substantiation for FDA clearance. Medicare reimbursement codes in the United States now cover remote physiologic monitoring from patch and ring form factors.
Smart watches lead on scale; wearable medical devices lead on momentum.
Technology:
Wireless protocol selection shapes interoperability, power consumption, and data throughput ceilings for wearable system architects.
- Bluetooth:BLE 5.3 stacks achieve sub-10mW transmission power for multi-day battery life in ring and patch devices. Fitness tracker and smart watch platforms standardize on this protocol for smartphone tethering.
- NFC:13.56MHz near-field channels enable contactless payment tokenization and medical device pairing in healthcare workflows. German and Japanese transit systems drive wearable wallet adoption.
- Wi-Fi:802.11ax implementations support direct cloud upload of high-fidelity ECG streams without smartphone intermediation. Hospital-at-home programs in the United States specify Wi-Fi for guaranteed bandwidth in remote patient monitoring.
- GPS:Multi-constellation receivers (GPS, GLONASS, Galileo) enable sub-5-meter position accuracy for sports performance and workforce safety applications. Australian mining operators mandate GPS-enabled fatigue monitors for haul truck compliance.
Bluetooth anchors volume; Wi-Fi is climbing the fastest as clinical workloads bypass smartphone gateways.
Application:
Use case specificity determines algorithm training requirements, regulatory claim permissibility, and reimbursement eligibility for wearable data services.
- Health Monitoring:Cardiovascular and metabolic parameter tracking requires FDA predicate alignment for diagnostic claims. Remote patient monitoring reimbursement in the United States institutionalizes clinical workflow integration.
- Fitness Tracking:Caloric expenditure and activity classification algorithms leverage accelerometer and gyroscope fusion without regulatory clearance. Consumer price sensitivity in India compresses margin at entry-tier positioning.
- Sports Performance:VO2 max estimation and lactate threshold detection demand validated biometric models. German cycling federations and US collegiate athletics programs drive premium hardware procurement.
- Sleep Tracking:SpO2 and heart rate variability metrics support sleep apnea screening claims under FDA enforcement discretion. EU MDR Class IIa pathways in Germany enable prescription-grade sleep disorder diagnostics.
Health monitoring leads on scale; sleep tracking gains share fastest as respiratory sensing migrates into consumer form factors.
End User:
Procurement authority and reimbursement access fragment demand across consumer retail, institutional healthcare, and enterprise safety channels.
- Individual Consumers:Direct-to-consumer sales through electronics retail and brand e-commerce dominate fitness tracker and basic smart watch volume. Price elasticity in India and Southeast Asia rewards manufacturing scale players.
- Healthcare Professionals:Hospital procurement departments and specialty pharmacy networks specify FDA-cleared devices for remote patient monitoring programs. Medicare reimbursement codes in the United States determine device eligibility.
- Athletes:Federations and collegiate programs mandate GPS and biometric monitoring for training load management. German Olympic training centers and US NCAA programs represent concentrated procurement authority.
- Enterprises:Mining, logistics, and manufacturing operators procure fatigue and environmental hazard monitors as safety compliance infrastructure. Australian and Canadian mining regulations now mandate wearable fatigue detection for heavy equipment operators.
Individual consumers lead on scale; enterprises represent the steepest expansion trajectory as safety compliance mandates displace voluntary wellness programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as vendors relocate assembly to jurisdictions with streamlined medical device clearance pathways and favorable tariff treatment for electronics components.
United States
Medicare reimbursement codes for remote patient monitoring drive hospital procurement of FDA-cleared wearable medical devices. FDA software pre-certification pilot programs tighten quality management requirements for algorithm updates. Boston and San Francisco metropolitan areas concentrate digital health startups developing cardiac monitoring wearables.
China
Domestic demand for smart watches and fitness bands sustains manufacturing scale as NMPA accelerates review timelines for Class II medical device registrations. MIIT standards for Bluetooth and Wi-Fi interoperability shape domestic connectivity specifications. Shenzhen and Dongguan industrial clusters anchor component sourcing and final assembly for global brands.
Germany
EU MDR Class IIa clearance pathways enable premium pricing for continuous glucose monitors and cardiac event recorders in statutory health insurance reimbursement. BfArM guidance on software-as-medical-device claims clarifies predicate device requirements. Munich and Stuttgart regions host precision sensor manufacturers supplying photoplethysmography modules.
India
PLI scheme production-linked incentives attract wearable assembly operations to Chennai and Noida corridors as import substitution policies reduce component duties. CDSCO streamlined medical device rules compress registration timelines for low-risk wearables. Bangalore and Hyderabad clusters concentrate firmware development and algorithm engineering talent.
Japan
Aging demographics and long-term care insurance coverage expand addressable demand for fall-detection and medication-adherence wearables. PMDA consultation programs guide foreign manufacturers through device classification and clinical evidence requirements. Tokyo-Osaka industrial belt hosts precision component suppliers for compact sensor modules.
Wearable Electronics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with medical-grade certification requirements concentrating premium positioning among vendors with established regulatory affairs capabilities. Consumer fitness trackers fragment across manufacturing-scale players competing at sub-dollar component economics. Three archetypes dominate: semiconductor-integrated platform vendors, GPS-specialized performance hardware makers, and manufacturing-scale entry-tier suppliers. Competitive moves center on FDA predicate alignment for diagnostic claims and foundry partnerships for advanced-node SoC access.
Within the platform-integrated tier, Apple Inc. and Samsung Electronics exemplify vertically controlled ecosystem strategies spanning silicon design through retail distribution. Garmin Ltd. occupies a specialized position in aviation-grade durability and multi-constellation GPS positioning for enterprise safety and sports federation procurement. Xiaomi Corporation anchors the manufacturing-scale archetype, leveraging component sourcing relationships and assembly automation to serve price-elastic demand in South and Southeast Asian retail channels.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Fitbit (Google LLC) |
| Xiaomi Corporation |
| Huawei Technologies Co. Ltd. |
| Garmin Ltd. |
| Imagine Marketing Limited |
| Sony Corporation |
| LG Electronics |
| Others |
Cost & Logistics Intelligence
Healthcare procurement departments now mandate FDA 510(k) clearance and ISO 13485 certification as baseline qualification criteria, forcing component suppliers to absorb compliance costs and medical-grade foundry premiums that compress margins at entry-tier positioning.
Pricing Analysis
Distributor margins of 15-25% for industrial safety wearables and 30-40% for consumer fitness trackers separate net pricing from manufacturer revenue realization. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and sensor fidelity, with FDA-cleared cardiac monitors commanding 3-5x premiums over consumer heart-rate bands. Cost compression in fitness trackers intensifies as Xiaomi and local brands exploit manufacturing scale in India. Healthcare professionals exhibit lowest price sensitivity due to reimbursement coverage, while individual consumers in Southeast Asia drive volume at sub-$50 entry points.
Supply Chain Analysis
Dual-sourcing requirements from Apple and Samsung for 5nm and 3nm SoC foundry capacity force qualification of secondary suppliers in South Korea and the United States, extending validation timelines. Taiwan, South Korea, and China anchor photoplethysmography sensor and lithium-polymer cell production. Supply chain risk centers on single-source vulnerability for advanced-node semiconductor access, with 90% of leading-edge foundry capacity concentrated in Taiwan. Distribution runs through industrial distributors for enterprise safety wearables and electronics retail chains for consumer devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical-grade certification has become the quality gate for premium positioning, with Medicare reimbursement codes and EU MDR Class IIa pathways concentrating margin capture among vendors with established regulatory affairs capabilities.
For Market Incumbents: To counter algorithm commoditization in basic heart-rate monitoring, Apple and Samsung must deepen backward integration into photoplethysmography sensor design and secure multi-year foundry allocation for 3nm SoC production. FDA software pre-certification pilot participation and predicate device libraries for cardiovascular claims provide defensive moats against consumer electronics vendors attempting medical-grade entry. For New Entrants and Emerging Players: Launch via specialty pharmacy distribution partnerships with CVS and Walgreens clinics to embed wearable medical devices into pharmaceutical care pathways. Enterprise safety procurement in Australian and Canadian mining represents the most penetrable segment, with mandated fatigue monitoring creating compliance-driven demand independent of consumer price sensitivity. White-space exists in non-invasive glucose monitoring spectroscopic sensing convergence with machine learning models. For Investors and Strategic Acquirers: Asymmetric upside sits with ISO 13485-certified sensor module suppliers serving multiple wearable OEMs, as foundry capacity constraints and regulatory complexity deepen vendor stickiness. Long-term viability favors vendors with predicate device libraries and established FDA 510(k) clearance pathways over consumer electronics brands attempting medical-grade transformation. Watch for EU MDR Class IIa clearance acceleration in Germany as inflection indicator for European reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Enables clinical-grade arrhythmia detection claims and Medicare reimbursement eligibility in the United States. |
| EU MDR Class IIa Pathway Investment | Unlocks statutory health insurance reimbursement for continuous glucose monitors in Germany. |
| Foundry Partnership for Advanced-Node SoC | Secures 3nm capacity allocation from TSMC or Samsung for AI-enabled diagnostic features. |
| Specialty Pharmacy Distribution Agreement | Embeds wearable medical devices into CVS and Walgreens pharmaceutical care workflows. |
| ISO 13485 Quality System Implementation | Enables medical device-grade documentation for consumer electronics vendors targeting regulated health segments. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at FDA-cleared device manufacturers were validated against secondary sources including FDA 510(k) filings, EU MDR notified body certificates, CMS Medicare reimbursement code databases, and hospital procurement records. Triangulation across these inputs ensures demand-side estimates align with component supply constraints.
Historical trendline analysis of smart watch replacement cycles and wearable medical device clearance timelines informed projection modeling across the analysis window. Segmentation dimensions include device type, wireless protocol, application use case, and procurement channel, with CAGRs derived from regression against semiconductor foundry capacity expansion and regulatory pathway velocity. Forecast inputs incorporate photoplethysmography sensor miniaturization trajectories and remote patient monitoring reimbursement code expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software pre-certification policy shifts or Taiwan semiconductor supply disruptions. Deviation in EU MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Smart Band Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Europe Wearable Technology Market