
 Wearable Computing Market | 2026-2036
Wearable Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Computing Market Analysis
Edge AI inference on-device is reshaping how wearable computing products process biometric data without cloud dependency. Apple Inc. leverages its custom silicon pipeline to sustain low-latency health analytics. Samsung Electronics Co. Ltd. anchors its Galaxy Watch lineup through FDA-cleared sleep apnea detection. Xiaomi Corporation competes on manufacturing scale to occupy the entry-level fitness band segment across emerging markets.
Wearable computing encompasses body-worn electronic devices integrating microprocessors, wireless transceivers, and multi-modal sensors to capture, process, and transmit physiological or environmental data for real-time user feedback or remote monitoring. These systems typically operate on sub-1-watt power budgets with MEMS accelerometers, PPG optical sensors, and Bluetooth Low Energy 5.3 connectivity enabling continuous multi-day operation. Smartwatches dominate value capture due to their multifunction convergence of health monitoring, mobile payments, and notification management. Health monitors represent the fastest-expanding application category as clinical-grade SpO2, ECG, and blood pressure sensing migrates from hospital equipment to wrist-worn form factors.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) Class IIa reclassification are elevating software documentation burdens for health-claim wearables. CE marking under the Radio Equipment Directive and FCC Part 15 emissions compliance further gate market access for wireless-enabled devices in Europe and the United States. Stakeholders must monitor evolving cybersecurity guidance from FDA and EMA as connected wearables face heightened scrutiny for data integrity and patient safety risks.
Market Dynamics
FDA's tightening software validation requirements for Class II medical wearables are forcing manufacturers to restructure development pipelines and documentation protocols before commercial release.
Growth Catalysts
- Remote Patient Monitoring Expansion:Healthcare systems across the United States are deploying continuous glucose monitoring and cardiac wearable programs under established reimbursement codes. This reimbursement infrastructure accelerates clinical validation timelines for new sensor modalities.
- EU Medical Device Regulation Reclassification:The MDR Class IIa designation for health-claim wearables elevates entry barriers but creates competitive moats for compliant manufacturers with robust quality management systems.
- Edge AI Inference:On-device neural processing is virtualizing biometric analytics without cloud dependency, reducing latency for real-time health alerts and enabling offline operation in connectivity-constrained environments.
Market Restraints
- MEMS Sensor Supply Concentration:Advanced accelerometer and gyroscope production concentrates among Asian contract manufacturers, creating vulnerability to geopolitical trade restrictions and capacity allocation decisions.
- PPG Optical Component Cost Volatility:Precision photodiodes and green LED arrays face pricing pressure from smartphone camera module demand competing for foundry capacity.
- Battery Energy Density Limitation:Lithium-polymer cell chemistry plateaus below 300 Wh/kg, constraining continuous multi-sensor operation to sub-72-hour cycles despite processing efficiency gains.
Strategic Opportunities
- Underpenetrated Clinical Sleep Diagnostics:FDA-cleared sleep apnea detection creates reimbursement pathways for wrist-worn polysomnography alternatives in United States sleep medicine practices.
- India PLI Scheme for Electronics Manufacturing:Production-linked incentive structures attract component assembly and testing operations to reduce import dependency for domestic wearable brands.
- Convergence of UWB and BLE 5.3:Ultra-wideband positioning integrated with Bluetooth Low Energy enables precise indoor location tracking for elderly fall detection and hospital patient wandering alerts.
Industry Challenges
- FDA 510(k) Documentation Burden:Software as a Medical Device submissions require exhaustive algorithm validation datasets, extending premarket notification timelines to 180 days or longer.
- Cybersecurity Compliance Complexity:FDA and EMA guidance on connected device data integrity demands dedicated security engineering headcount and third-party penetration testing budgets.
- Legacy Hospital EMR Integration:HL7 FHIR interoperability standards vary across Epic, Cerner, and Meditech deployments, forcing custom API development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Computing Market |
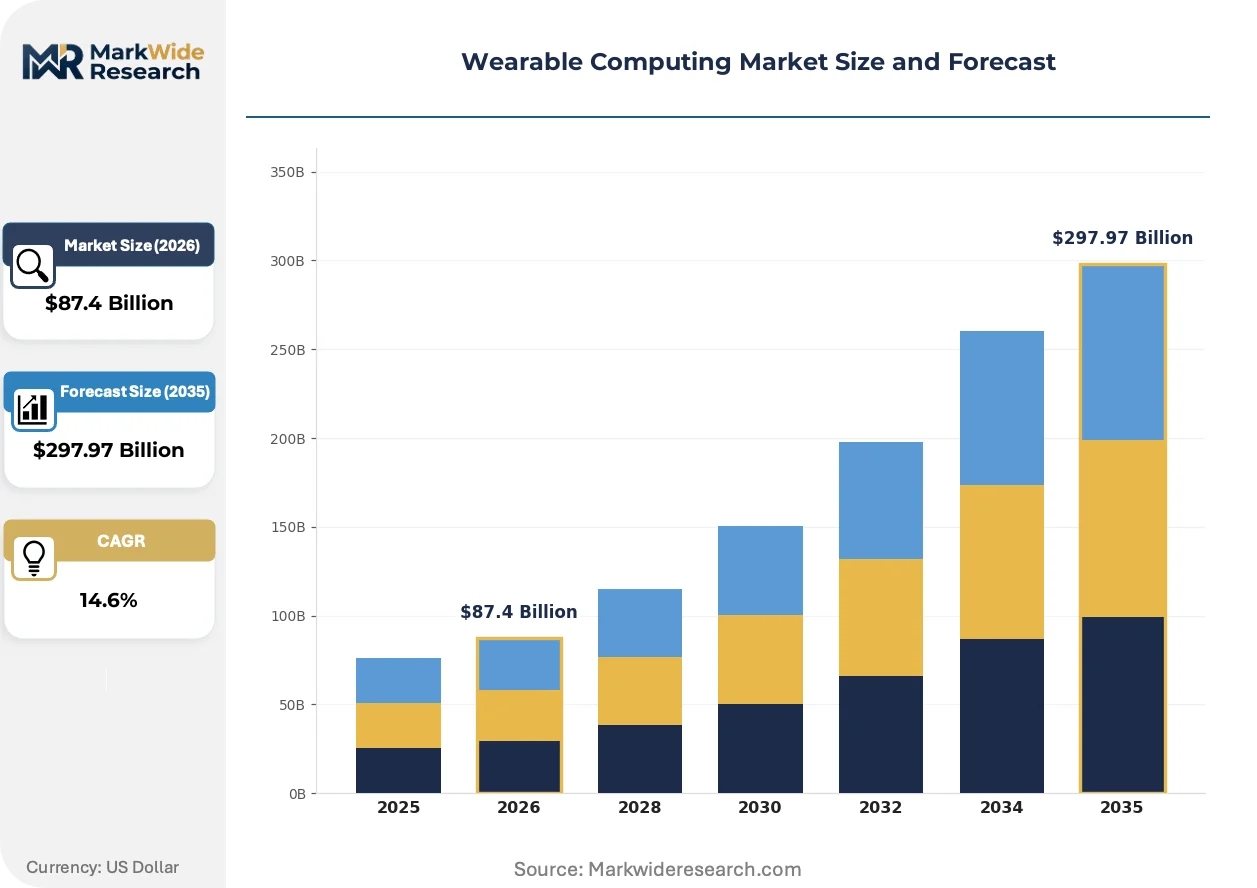
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $297.97 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Application: Fitness Tracking, Health Monitoring, Sports Analytics, Mobile Payments End User: Fitness Enthusiasts, Health Conscious Individuals, Professionals, General Consumers Technology: Bluetooth, Wi-Fi, NFC, Sensors |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Garmin Ltd., Fitbit Inc., Fossil Group Inc., Huawei Technologies Co. Ltd., Sony Corporation, Xiaomi Corporation, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Computing Market Emerging Trajectories
Edge computing architectures and regulatory harmonization efforts are compressing the gap between consumer fitness devices and clinical-grade monitors, reshaping competitive positioning across price tiers.
Photoplethysmography sensor fusion with electrical bioimpedance is virtualizing blood pressure estimation without cuff inflation, enabling continuous cardiovascular monitoring from wrist-worn form factors. Cardiology practices in Germany and the United States are piloting these devices for ambulatory hypertension management. This convergence is compressing the addressable market for traditional upper-arm oscillometric monitors in home health settings.
The EU AI Act's risk classification framework for biometric identification systems is mandating conformity assessments for wearables employing facial or gait recognition algorithms. Manufacturers must document training data provenance and algorithmic transparency before CE marking. Fitness and enterprise safety wearable segments are responding by segregating EU-bound product SKUs from unrestricted global variants.
Hospital procurement committees are consolidating vendor relationships around platforms with native Epic integration and FDA-cleared arrhythmia detection, displacing standalone fitness bands from clinical trial and remote monitoring contracts. This concentration is most visible in United States integrated delivery networks where reimbursement integrity depends on documented clinical validity.
Wearable Computing Market Segmentation
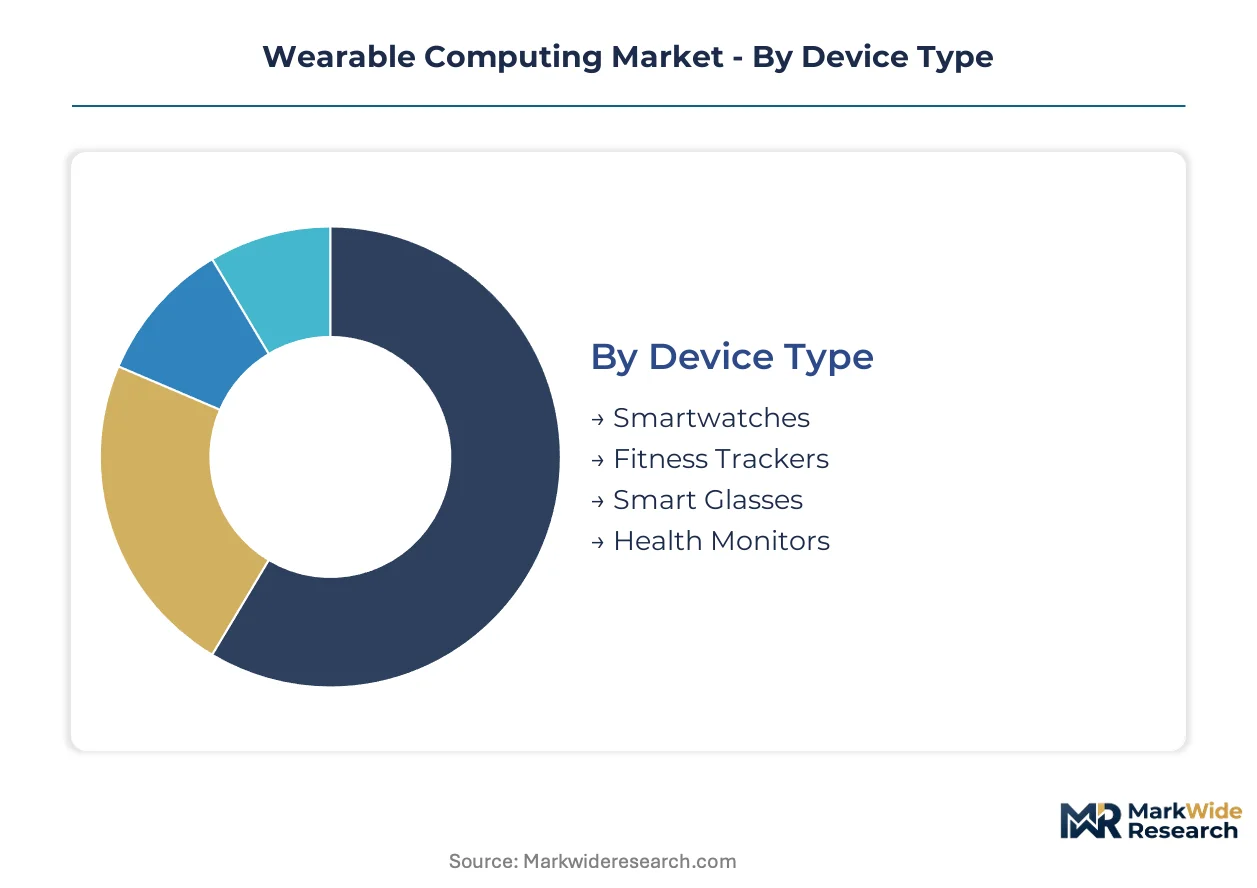
Wearable computing markets fragment across four critical dimensions where device capabilities, reimbursement pathways, and sensor convergence dictate purchasing decisions. Understanding these segment boundaries clarifies why smartwatches command premium pricing while health monitors capture clinical validation momentum.
Device Type:
The use-case spectrum spans casual fitness notification to FDA-cleared diagnostic monitoring, with form factor constraints determining sensor payload and battery architecture.
- Smartwatches:Multi-function wrist-worn platforms integrating PPG optical sensors, MEMS accelerometers, and payment NFC chips within sub-1-watt power envelopes. Demand concentrates in the United States among integrated delivery networks requiring Epic EHR compatibility and documented arrhythmia detection for remote patient monitoring reimbursement.
- Health Monitors:Purpose-built diagnostic devices with clinical-grade SpO2, ECG, and blood pressure estimation through photoplethysmography-electrical bioimpedance fusion. Cardiology practices in Germany and the United States are piloting these for ambulatory hypertension management, displacing traditional oscillometric home monitors.
- Fitness Trackers:Stripped-down activity logging bands prioritizing step counting and sleep staging over medical claims. Xiaomi Corporation dominates manufacturing scale for emerging market entry-level segments.
- Smart Glasses:Optical see-through displays with gaze tracking and camera modules for enterprise logistics and surgical navigation. Enterprise safety applications in manufacturing facilities drive current adoption.
Established volume favors smartwatches; emerging adoption favors health monitors.
Application:
Reimbursement infrastructure separates consumer wellness from clinical-grade deployments.
- Health Monitoring:Continuous glucose tracking, cardiac arrhythmia detection, and sleep apnea screening under FDA 510(k) and EU MDR Class IIa frameworks. United States reimbursement codes for CGM and cardiac wearables accelerate hospital procurement cycles.
- Fitness Tracking:Calorie expenditure, VO2 max estimation, and recovery metrics without diagnostic claims. Consumer subscription models monetize engagement rather than clinical outcomes.
- Sports Analytics:Biomechanical load monitoring and GPS-tracked performance metrics for professional athletes and amateur endurance competitors.
- Mobile Payments:Tokenized NFC transaction authorization from wrist-worn form factors, with transit authority integration driving adoption in urban Asian markets.
Clinical validation concentrates in health monitoring; consumer scale dominates fitness tracking.
End User:
Purchasing authority splits between institutional procurement committees and individual retail decisions.
- Health Conscious Individuals:Aging demographics seeking preventive biometric tracking with physician dashboard sharing. United States Medicare Advantage plans increasingly subsidize device costs for chronic condition management.
- Fitness Enthusiasts:Amateur athletes demanding granular training load metrics and recovery recommendations. Subscription fitness platforms bundle hardware with coaching services.
- Professionals:Enterprise safety mandates and hands-free workflow applications in logistics, healthcare, and field service operations.
- General Consumers:Notification management and convenience features without specific health or fitness objectives. Price sensitivity drives private-label and white-label brand selection.
Institutional purchasing favors health conscious individuals; retail volume concentrates among general consumers.
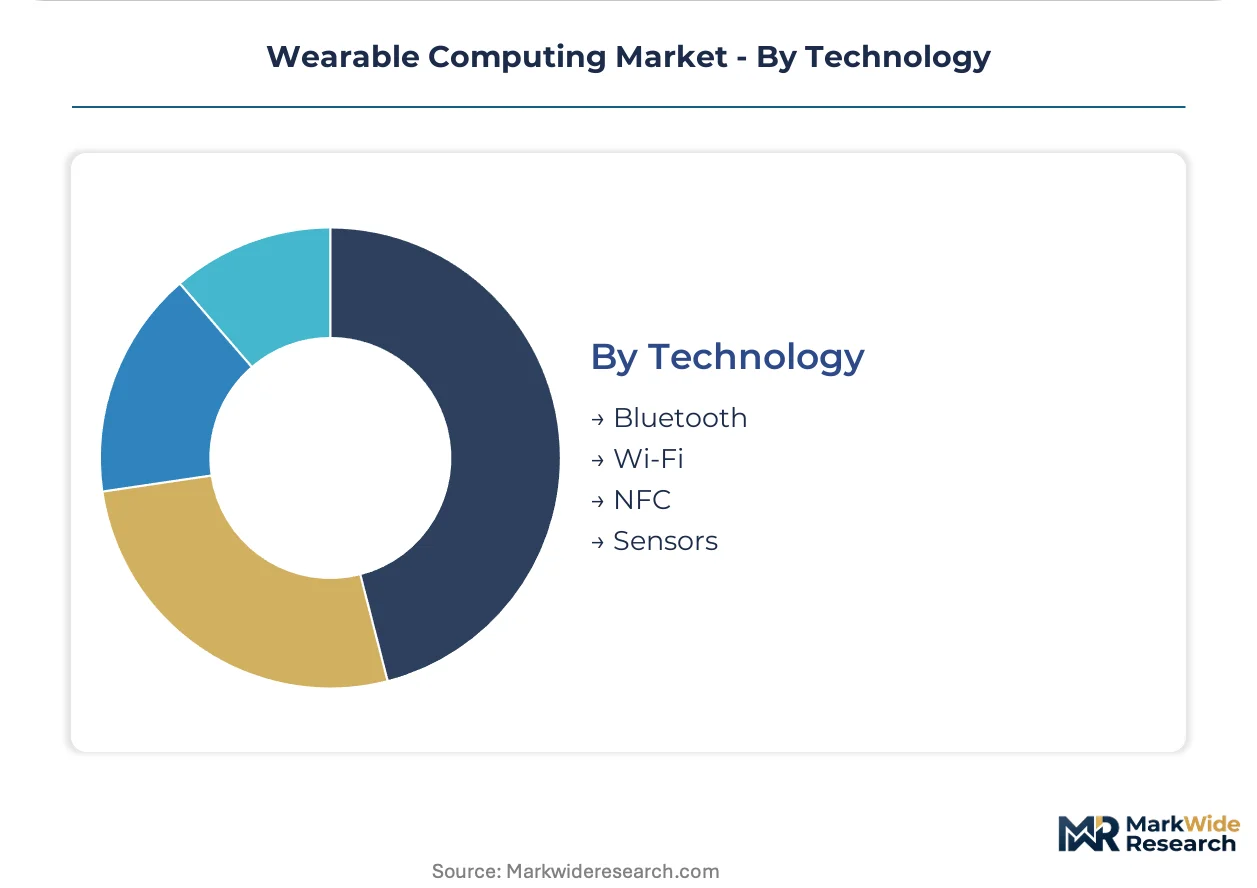
Technology:
Connectivity and sensing architectures determine interoperability boundaries and power budgets.
- Sensors:MEMS accelerometers, gyroscopes, PPG optical arrays, and emerging electrical bioimpedance modules for cardiovascular estimation. Foundry capacity competition with smartphone camera modules creates component pricing pressure.
- Bluetooth:BLE 5.3 low-energy stacks enabling multi-day operation with sub-10mW active transmit power. Samsung Electronics anchors Galaxy Watch connectivity through proprietary protocol optimizations.
- Wi-Fi:Higher bandwidth for firmware updates and cloud-synced health record uploads, reserved for devices with larger battery capacities.
- NFC:Payment tokenization and access control applications requiring secure element integration and EMVCo certification.
Sensor integration commands R&D investment; Bluetooth connectivity enables baseline functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for MEMS sensors and PPG optical components shapes trade flows, with finished device exports from Asian assembly hubs offsetting component purchases from specialized foundries. Reimbursement infrastructure and regulatory clearance timelines create divergent demand intensities across national healthcare systems.
United States
Medicare Advantage plans subsidize continuous glucose monitors and cardiac wearables for chronic condition management. FDA 510(k) premarket notification requirements enforce exhaustive software validation datasets, extending clearance timelines. The Boston-Cambridge corridor anchors health-tech venture formation, with startups clustering around Massachusetts General Hospital's clinical validation partnerships.
Germany
Ambulatory cardiology practices pilot wrist-worn blood pressure estimation devices for hypertension management. The EU Medical Device Regulation Class IIa reclassification elevates quality management system requirements for health-claim wearables. Baden-Württemberg's precision engineering cluster supplies MEMS accelerometer components to tier-one device manufacturers.
China
Domestic brands capture volume in entry-level fitness bands through manufacturing scale advantages. NMPA medical device registration pathways tighten clinical evidence requirements for diagnostic wearables. Shenzhen's electronics assembly ecosystem concentrates final device production and testing operations for export markets.
India
Production-linked incentive schemes attract component assembly and testing operations to reduce import dependency for domestic wearable brands. BIS certification requirements and CDSCO medical device rules govern market access for health-claim devices. Karnataka's Bengaluru-Tumkur corridor hosts emerging design centers for affordable health monitor development.
Japan
Aging demographics drive preventive biometric tracking adoption among health-conscious individuals. PMDA medical device approval processes emphasize clinical trial data from domestic patient populations. Tokyo-Osaka metropolitan areas concentrate enterprise safety wearable deployments in manufacturing and logistics facilities.
Wearable Computing Market Vendor Landscape
On the supply side, the industry is bifurcated between vertically integrated technology conglomerates controlling custom silicon pipelines and specialized health-device manufacturers competing on clinical validation depth. Tier-one players anchor premium positioning through FDA-cleared diagnostic claims, while scale-focused competitors occupy entry-level fitness segments. Dominant competitive moves include strategic partnerships with health systems for EMR integration and portfolio diversification into clinical-grade sensor modalities.
Within the integrated technology tier, Apple Inc. exemplifies custom silicon-driven health analytics capabilities, while Samsung Electronics Co. Ltd. anchors FDA-cleared sleep diagnostic positioning. Xiaomi Corporation occupies the manufacturing-scale archetype for emerging market volume capture. These three represent distinct strategic postures: premium ecosystem lock-in, clinical validation leadership, and cost-optimized scale penetration respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Garmin Ltd. |
| Fitbit Inc. |
| Fossil Group Inc. |
| Huawei Technologies Co. Ltd. |
| Sony Corporation |
| Xiaomi Corporation |
| Google LLC |
| Others |
Supply Flow & Price Mechanics
MEMS foundry undercapacity across Taiwan and South Korea is compressing component availability timelines while simultaneously hardening supplier pricing power for precision accelerometers and gyroscopes. This utilization squeeze cascades into finished device margins, forcing OEMs to absorb cost escalation or downgrade sensor specifications in entry-tier fitness bands.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers in wearable computing markets. FDA 510(k) clearance status and Epic EHR integration depth separate premium clinical-grade smartwatches from consumer fitness bands. Cost compression in entry-level fitness trackers is intensifying because Xiaomi Corporation's manufacturing scale advantages trigger race-to-bottom dynamics in emerging markets. General consumers exhibit highest price sensitivity, while integrated delivery networks prioritize clinical validation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for wearable computing OEMs dependent on Shenzhen assembly operations. Component sourcing draws from Taiwan for MEMS sensors, Japan for precision photodiodes, and South Korea for lithium-polymer cells. Single-source vulnerability concentrates in advanced accelerometer production where Asian contract manufacturers control specialized foundry capacity. Distribution runs through electronics retail chains, direct-to-consumer channels, and hospital procurement committees for clinical-grade devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated delivery networks consolidating vendor relationships around platforms with native EMR integration and FDA-cleared diagnostic claims, fragmenting purchasing authority away from individual retail consumers.
For Market Incumbents: Entrench FDA-cleared diagnostic positioning through expanded sleep apnea and arrhythmia detection claims before reimbursement codes tighten. Deepen backward integration into custom silicon pipelines to sustain low-latency health analytics advantages against emerging entrants dependent on commodity chipsets. Channel control through exclusive health system partnerships remains critical as hospital procurement committees displace retail channels for clinical-grade deployments. For New Entrants and Emerging Players: Pursue underpenetrated clinical sleep diagnostics in United States sleep medicine practices where wrist-worn polysomnography alternatives lack established vendors. India PLI scheme incentives offer manufacturing scale entry points for affordable health monitors targeting domestic chronic condition management programs. Go-to-market execution should emphasize CDSCO registration pathways and BIS certification to unlock institutional purchasing channels. For Investors and Strategic Acquirers: Long-term, this sits as a clinical-validation-arbitrage play because FDA 510(k) clearance timelines and EU MDR Class IIa reclassification create durable moats for compliant manufacturers. Acquisition targets should display robust quality management systems and documented algorithm validation datasets. The signal to watch is reimbursement code expansion for continuous cardiovascular monitoring modalities beyond glucose and cardiac arrhythmia.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Unlocks Medicare Advantage reimbursement pathways for continuous glucose monitoring in United States chronic care management. |
| CE Marking Pathway | Enables EU MDR Class IIa health-claim wearable access across German ambulatory cardiology practices. |
| Hospital System Partnership | Secures Epic EHR integration and displaces standalone fitness bands from remote patient monitoring contracts. |
| Software Companion Development | Supports HL7 FHIR interoperability standards for seamless data exchange with Cerner and Meditech deployments. |
| Reimbursement Strategy | Aligns device capabilities with established CPT codes for cardiac wearable and sleep apnea screening programs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wearable computing product managers, FDA regulatory affairs specialists, hospital biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment records, CMS Medicare reimbursement code listings, and SEC filings from tier-one device manufacturers. Bottom-up sensor shipment modeling and top-down healthcare IT expenditure analysis were triangulated to cross-verify market sizing.
Calibration against historical FDA clearance timelines and reimbursement code adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, application category, end-user purchasing authority, and connectivity technology architecture. CAGRs were derived from fitted growth curves incorporating MEMS sensor supply constraints, lithium-polymer energy density plateaus, and edge AI inference adoption rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by emerging Asian OEMs or accelerated EU AI Act enforcement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Women's Watch Market
Wearable Technology
Smart Bra Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Global Smart Wearable Market