
 Smart Band Market | 2026-2036
Smart Band Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Band Market Intelligence
Market Context
The split between premium medical-grade smart bands and commodity fitness trackers is realigning procurement patterns across enterprise and consumer channels. Apple dominates the premium tier through clinical-grade sensor arrays and FDA-cleared ECG functionality. Xiaomi anchors the volume tier with aggressive pricing and supply chain control across Southeast Asian retail networks. Garmin specializes in ruggedized outdoor segments where GPS accuracy and battery endurance differentiate product positioning.
Technical Definition and Structural Segments
A smart band is a wrist-worn wearable computing device incorporating accelerometers, photoplethysmography sensors, and Bluetooth Low Energy connectivity to capture biometric data and relay it to paired smartphones or cloud health platforms. These devices serve continuous physiological monitoring, activity quantification, and passive health screening functions for consumers and institutional wellness programs. Fitness trackers lead unit volume but face margin compression as health monitors command higher average selling prices through SpO2 and blood pressure estimation capabilities. The subscription-based pricing model is expanding recurring revenue pools as Withings and Fitbit bundle cloud analytics with hardware sales. Online retailers control the fastest-growing distribution channel, though electronic stores retain importance for premium product demonstrations and immediate technical support.
Regulatory Framework and Outlook
FDA 510(k) clearance requirements for arrhythmia detection and CE marking under the EU Medical Device Regulation are elevating compliance costs for vendors targeting clinical credibility. China's NMPA and SAMR enforce GB standard certifications for wireless transmission and battery safety, shaping market access for domestic and imported devices. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify algorithm-driven health insights as regulated clinical outputs.
Market Dynamics
Corporate wellness mandates and FDA 510(k) clearance requirements for pulse oximetry are bifurcating the smart band landscape into clinical-grade devices and basic fitness trackers, forcing vendors to choose between compliance investment and margin preservation.
Growth Catalysts
- Employee health monitoring mandates:Fortune 500 companies in the United States are deploying connected wearables to reduce insurance premiums and track workforce biometric baselines.
- FDA clearance for ECG functionality:Regulatory validation of arrhythmia detection algorithms is elevating consumer trust in medical-grade sensor arrays.
- Photoplethysmography advances:Improved optical heart rate monitoring is enabling continuous SpO2 and blood pressure estimation without invasive procedures.
Market Restraints
- Lithium polymer battery supply concentration:Cell production clusters in China's Guangdong province create single-source vulnerability for mid-tier manufacturers.
- CE marking under EU Medical Device Regulation:Elevated documentation and clinical evidence requirements are extending time-to-market for European distribution.
- Smartwatch substitution pressure:Full-featured wrist-worn computers with cellular connectivity are absorbing price-sensitive consumers seeking consolidated devices.
Strategic Opportunities
- Remote patient monitoring reimbursement:United States CMS coding for chronic care management is creating institutional procurement channels for clinically validated wearables.
- Bluetooth Low Energy and AI convergence:On-device inference for anomaly detection is reducing cloud dependency and enabling real-time health alerts without smartphone pairing.
- Direct-to-consumer telehealth bundling:Virtual care platforms are white-labeling hardware to capture recurring subscription revenue from continuous data streams.
Industry Challenges
- Firmware validation timelines:FDA software-as-medical-device classification for algorithm updates is slowing iterative development cycles.
- Photodiode calibration expertise:Specialized optical engineering talent for skin-tone inclusive sensor tuning remains scarce in Western labor markets.
- Legacy EHR integration complexity:Health system procurement committees demand HL7 FHIR compatibility that smaller vendors lack resources to certify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Band Market |
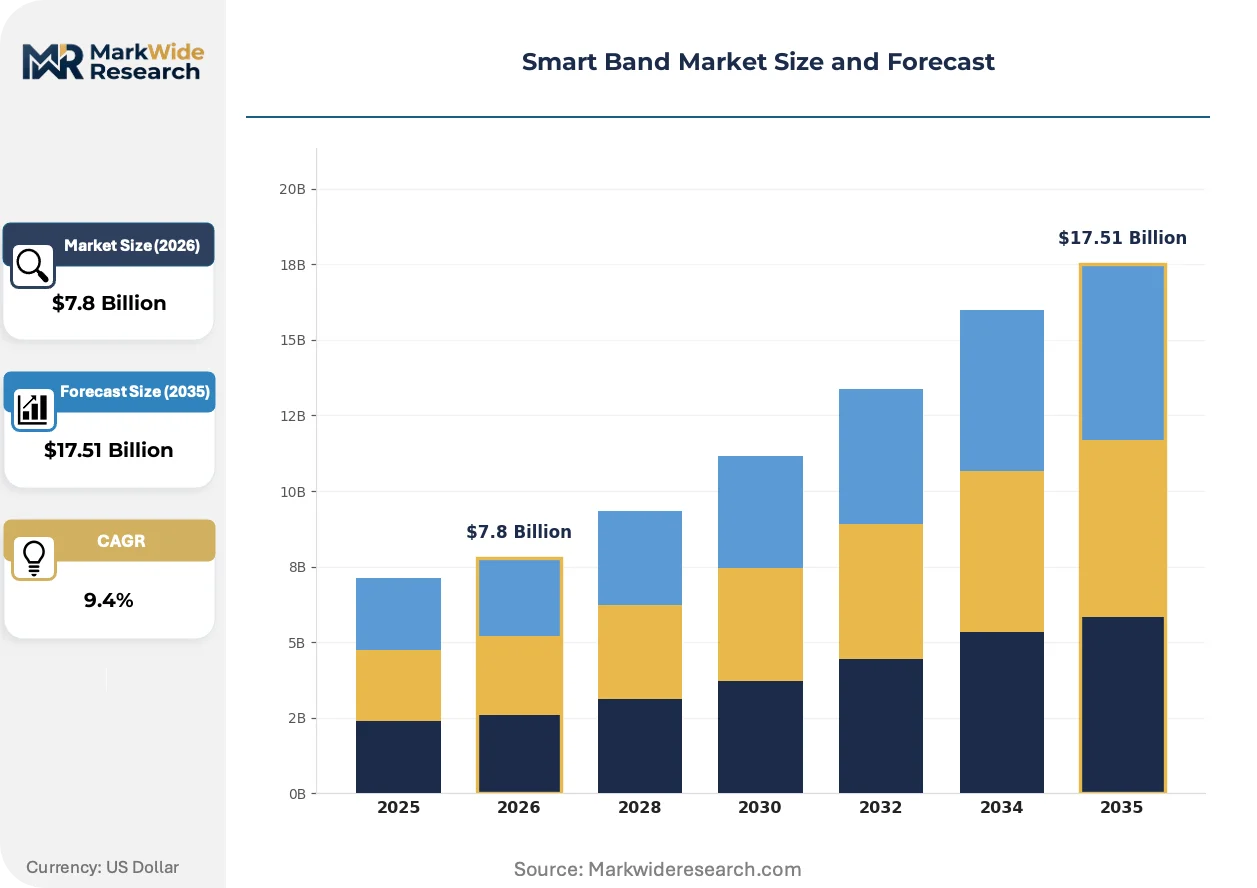
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smartwatches, Health Monitors, Hybrid Wearables End User: Fitness Enthusiasts, Health Conscious Consumers, Tech Savvy Individuals, Corporate Professionals Distribution Channel: Online Retailers, Electronic Stores, Fitness Centers, Supermarkets Pricing Model: Premium, Mid-Range, Budget, Subscription-Based |
| Companies Covered | Amazfit, Huawei, Fitbit (Google), Withings, Samsung, Xiaomi, Apple, Honor, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Band Market Strategic Shifts & Innovations
Sensor miniaturization and edge computing architectures are dissolving the boundary between consumer wellness devices and clinical monitoring equipment, creating new product categories that serve both markets simultaneously.
Photoplethysmography sensor arrays is modularizing across multi-wavelength LED configurations to capture richer cardiovascular datasets. Hospital-at-home programs in the United States are adopting these enhanced optical modules for post-discharge patient surveillance. The technology is modularizing what was once bedside equipment into wrist-worn form factors that patients tolerate for continuous wear.
China's NMPA and SAMR enforcement of GB standard certifications for wireless transmission and battery safety is tightening market access protocols. Domestic manufacturers with established testing relationships are accelerating certification timelines while foreign entrants face extended review queues. Premium vendors targeting clinical credibility are prioritizing NMPA registration to unlock procurement contracts with Chinese hospital networks.
Employer-sponsored wellness subsidies are displacing direct consumer purchases as the dominant acquisition channel for mid-tier fitness bands. Benefits administrators at self-insured corporations are negotiating volume pricing with device manufacturers and integrating biometric dashboards into existing HR platforms. This channel migration is most pronounced in the United States where healthcare cost containment drives C-suite investment in preventive monitoring infrastructure.
Smart Band Market Segmentation
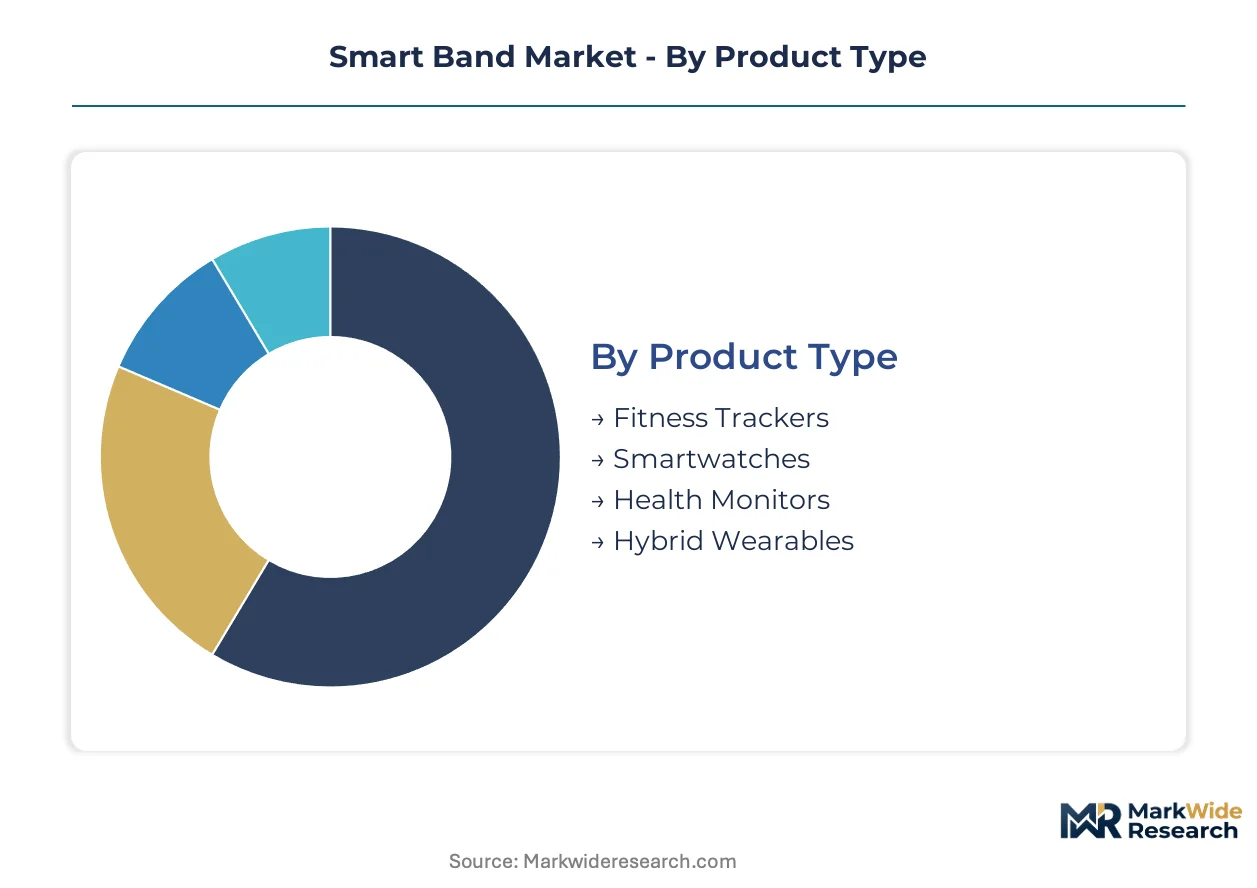
Smart band procurement patterns diverge sharply between clinical-grade institutional buyers and price-sensitive consumer segments. Device certification tiers and distribution channel economics create distinct competitive arenas that vendors must navigate simultaneously.
Product Type:
Buyers in this category separate by clinical validation requirements versus lifestyle tracking preferences.
- Fitness Trackers:Accelerometer and gyroscope-based devices quantify step counts, sleep stages, and calorie expenditure through proprietary algorithms. Demand concentrates in Southeast Asian retail networks where Xiaomi controls volume through supply chain integration and localized health platform partnerships.
- Health Monitors:Photoplethysmography sensor arrays enable continuous SpO2 tracking, blood pressure estimation, and arrhythmia detection that meets FDA 510(k) thresholds. Hospital-at-home programs in the United States are accelerating procurement of these clinical-grade wearables for post-discharge patient surveillance under CMS chronic care management reimbursement codes.
- Smartwatches:Full-featured wrist-worn computers with cellular connectivity and app ecosystems that consolidate multiple device functions.
- Hybrid Wearables:Analog watch aesthetics combined with discrete sensor modules targeting fashion-conscious buyers unwilling to accept utilitarian industrial design.
Fitness trackers lead volumes today; health monitors are gaining share fastest.
End User:
Procurement authority in this category splits between individual purchasing decisions and employer-sponsored wellness program administrators.
- Corporate Professionals:Fortune 500 benefits administrators negotiate volume pricing for connected wearables and integrate biometric dashboards into existing HR platforms to reduce insurance premiums. Self-insured corporations in the United States drive the dominant acquisition channel for mid-tier devices through preventive monitoring infrastructure investment.
- Health Conscious Consumers:Individuals prioritizing longitudinal health data accumulation and clinical-grade sensor accuracy over price minimization. China's domestic brands capture this segment through NMPA-registered devices and localized health platform integrations that foreign entrants struggle to replicate.
- Fitness Enthusiasts:Activity-focused buyers demanding GPS accuracy, waterproofing, and extended battery endurance for outdoor training scenarios.
- Tech Savvy Individuals:Early adopters seeking cutting-edge sensor configurations and developer-accessible APIs for custom health analytics.
Corporate professionals dominate procurement volume; health conscious consumers show the steepest expansion trajectory.
Distribution Channel:
Channel selection in this category tracks buyer need for immediate technical support versus price transparency and convenience.
- Online Retailers:E-commerce platforms control the fastest-growing distribution channel through price comparison tools and algorithmic recommendation engines. Direct-to-consumer telehealth platforms are white-labeling hardware to capture recurring subscription revenue from continuous data streams.
- Electronic Stores:Brick-and-mortar retailers retain importance for premium product demonstrations, immediate technical support, and tactile evaluation of build quality before purchase commitment.
- Fitness Centers:Gym chains and boutique studios bundling devices with membership packages and personal training services.
- Supermarkets:Mass retail channels moving budget-tier inventory through impulse purchase placement and promotional pricing.
Online retailers lead volume today; fitness centers are climbing the fastest.
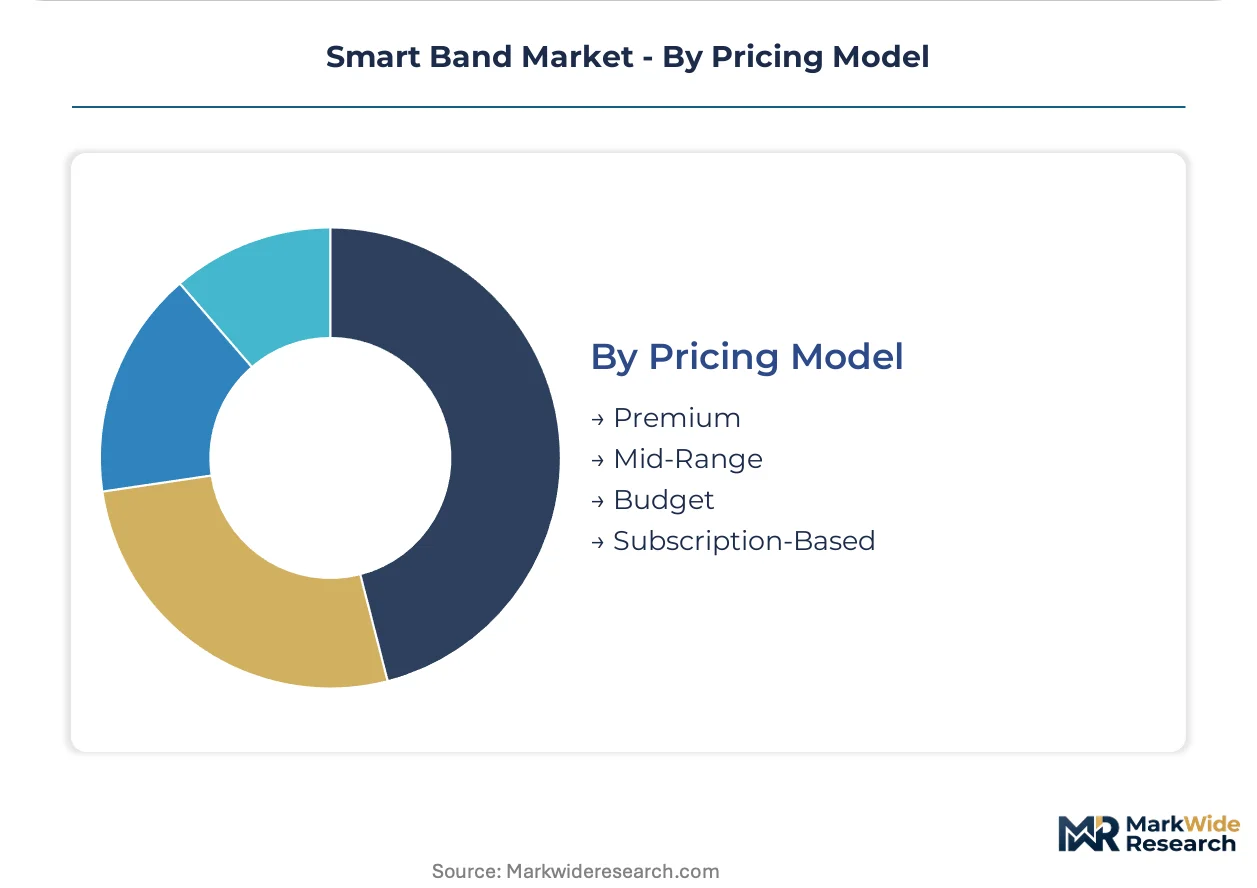
Pricing Model:
Payment structure in this category differentiates by hardware margin capture versus recurring revenue generation through attached services.
- Subscription-Based:Bundled cloud analytics, personalized health coaching, and predictive algorithm access creating recurring revenue pools that decouple vendor economics from hardware replacement cycles. Withings and Fitbit have established this model's viability in European and North American markets.
- Premium:Clinical-grade sensor arrays with FDA-cleared ECG functionality and medical device certifications commanding substantial price premiums for institutional procurement.
- Mid-Range:Balanced feature sets targeting health-conscious consumers unwilling to pay medical-device premiums but demanding SpO2 and advanced sleep tracking.
- Budget:Stripped-down accelerometer-only devices competing on manufacturing scale and supply chain efficiency in emerging markets.
Budget tiers lead volumes today; subscription-based models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in Shenzhen and Cupertino anchor sensor development for clinical-grade wearables, while regulatory validation expertise concentrates near FDA offices in Maryland and NMPA facilities in Beijing.
United States
Fortune 500 benefits administrators drive institutional procurement through self-insured corporate wellness mandates. FDA 510(k) clearance requirements for ECG and pulse oximetry functions elevate compliance costs for vendors seeking clinical credibility. Greater Boston hosts hospital-at-home pilot programs integrating continuous biometric monitoring from wrist-worn devices.
China
Domestic brands capture health-conscious consumers through NMPA-registered devices and localized health platform integrations. SAMR enforcement of GB standard certifications for wireless transmission and battery safety shapes market access protocols. Guangdong province manufacturing clusters accelerate production scale for mid-tier fitness bands distributed across Southeast Asian retail networks.
Germany
Industrial employers incorporate connected wearables into occupational health and safety compliance frameworks. CE marking under EU Medical Device Regulation demands extensive clinical evidence documentation for arrhythmia detection algorithms. Munich and Stuttgart engineering centers specialize in photodiode calibration for skin-tone inclusive sensor tuning.
Japan
Aging demographics drive demand for continuous health monitoring among elderly populations managing chronic conditions. PMDA medical device registration requirements parallel FDA stringency for clinical-grade wearable certification. Tokyo and Osaka metropolitan areas concentrate telehealth platform development integrating hardware with virtual care delivery.
India
Price-sensitive consumers in tier-2 and tier-3 cities favor budget-tier accelerometer devices through online retail channels. CDSCO medical device rules are evolving to classify algorithm-driven health insights as regulated clinical outputs. Bengaluru and Hyderabad technology hubs develop AI-enabled anomaly detection for on-device health alerts.
Smart Band Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the smart band landscape, with vertically integrated Asian manufacturers controlling component supply while Western specialists focus on algorithm development and clinical validation. The vendor base stratifies into three tiers: premium medical-grade players commanding FDA-cleared ECG functionality, mid-range health monitors with SpO2 and advanced sleep tracking, and budget fitness trackers competing on manufacturing scale. Dominant competitive moves include backward integration into photoplethysmography sensor production and strategic partnerships with telehealth platforms for direct-to-consumer distribution.
Within the premium medical-grade tier, Apple and Withings exemplify clinical credibility through regulatory validation and subscription-based cloud analytics bundling. Xiaomi and Amazfit occupy positions at the scale-driven volume tier, leveraging Guangdong manufacturing clusters and localized health platform integrations to capture price-sensitive segments across emerging markets.
| Leading Market Players |
|---|
| Amazfit |
| Huawei |
| Fitbit (Google) |
| Withings |
| Samsung |
| Xiaomi |
| Apple |
| Honor |
| Garmin |
| Others |
Cost & Logistics Intelligence
Lithium polymer cell costs cascade through three distinct pricing tiers, with Guangdong manufacturing clusters feeding mid-tier fitness bands while FDA-cleared ECG modules command premium positioning for institutional procurement in the United States.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from recurring revenue architectures. Subscription-based cloud analytics bundling from Withings and Fitbit decouples vendor economics from replacement cycles, while unbundled fitness trackers compete on manufacturing scale. Price differentiation hinges on FDA 510(k) certification tier and photoplethysmography sensor array complexity. Cost compression in the budget tier intensifies because Xiaomi's supply chain integration enables aggressive Southeast Asian retail pricing. Corporate wellness administrators show lowest price sensitivity, while individual consumers in tier-2 Indian cities exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Fortune 500 benefits administrators, while electronic stores manage premium product demonstrations requiring tactile evaluation. Component supply concentrates in China, South Korea, and Japan, with photodiode arrays and multi-wavelength LED modules drawing from specialized optical engineering foundries. Raw material dependencies include lithium polymer cells, sapphire glass substrates, and medical-grade silicone bands. Single-source vulnerability persists around Guangdong battery cell production. Distribution runs through online retailers for fastest-growing volume, though hospital procurement committees demand direct vendor relationships for clinical-grade devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart band market reads as a late-cycle quality story, with employer-sponsored wellness subsidies displacing direct consumer purchases and elevating procurement authority toward benefits administrators demanding clinical-grade specifications.
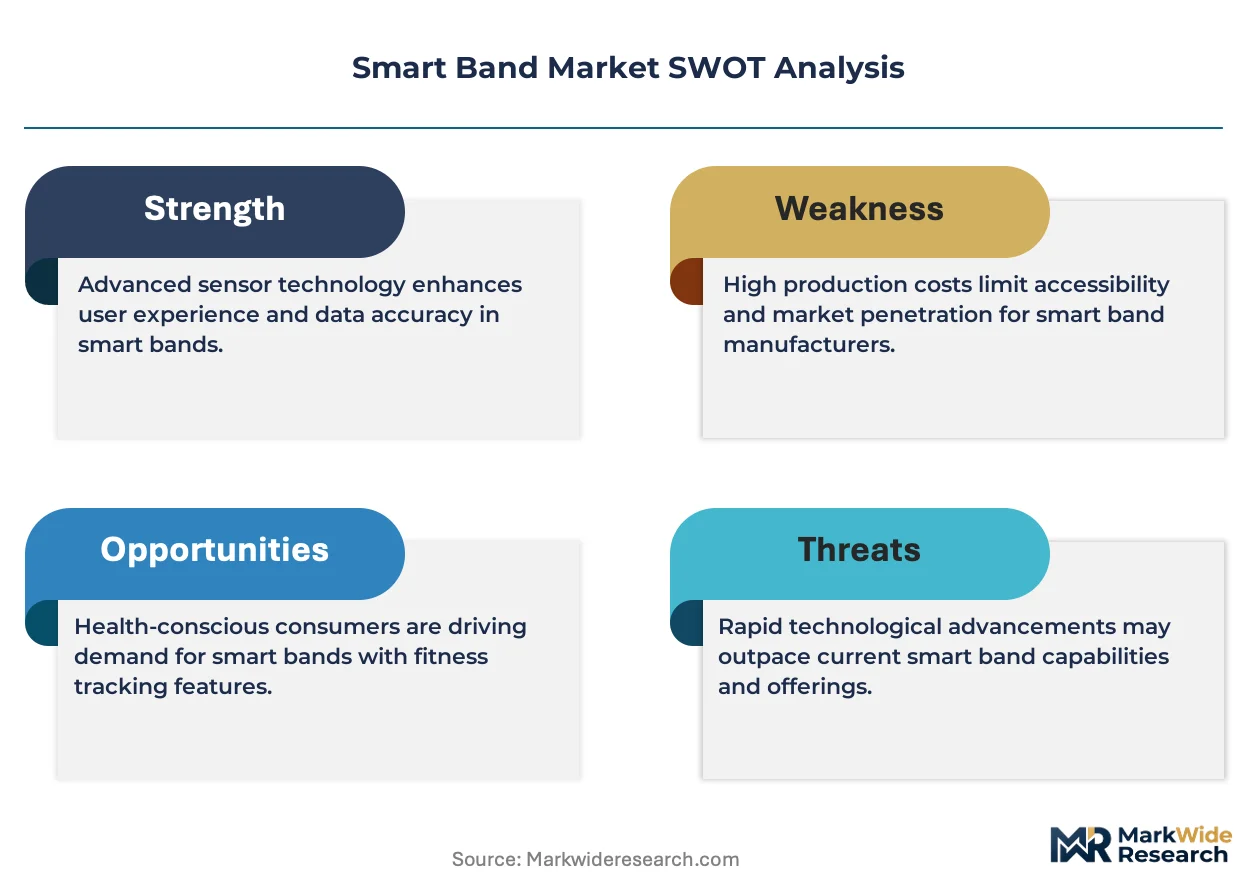
For Market Incumbents: Anticipate smartwatch substitution pressure by deepening FDA 510(k) certification moats around arrhythmia detection algorithms and securing backward integration into photoplethysmography sensor production. Hospital-at-home program expansion in the United States creates institutional lock-in for vendors with HL7 FHIR compatibility, while firmware validation timelines under software-as-medical-device classifications threaten iterative development velocity. Priority levers include NMPA registration in China and captive supply of optical calibration expertise. For New Entrants and Emerging Players: The price-point gap between premium medical-grade devices and commodity fitness trackers offers white-space entry for mid-range health monitors with SpO2 and advanced sleep tracking. Southeast Asian retail networks remain penetrable through localized health platform partnerships, while direct-to-consumer telehealth bundling provides go-to-market acceleration without brick-and-mortar infrastructure investment. Target benefits administrators at self-insured mid-cap corporations underserved by Fortune 500-focused incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware validation expertise and photodiode calibration talent concentrate in Western labor markets. Long-term viability favors vertically integrated specialists with in-house optical engineering and established regulatory submission track records across FDA, CE marking, and NMPA jurisdictions. Acquisition target archetypes include AI-enabled anomaly detection developers with on-device inference capabilities. The signal to watch is CMS reimbursement coding expansion for continuous biometric monitoring in chronic care management.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Regulatory validation of ECG functionality unlocks institutional procurement from hospital-at-home programs. |
| Photoplethysmography Backward Integration | In-house sensor production reduces dependency on Guangdong optical component suppliers and accelerates skin-tone inclusive calibration. |
| Telehealth Platform Partnership | White-label hardware distribution captures recurring subscription revenue from virtual care data streams. |
| NMPA Registration Acceleration | Chinese hospital network procurement contracts require SAMR-compliant GB standard certifications for wireless transmission. |
| HL7 FHIR Compatibility Investment | Health system procurement committees mandate EHR integration that smaller vendors lack resources to certify. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, benefits administrators at self-insured corporations, and optical sensor R&D directors with secondary validation from FDA 510(k) filings, NMPA registration databases, CMS reimbursement coding updates, and hospital procurement contract disclosures. Bottom-up vendor shipment estimates and top-down wellness program spending analysis provided cross-verification.
Segment-weighting approaches distributed value and volume across fitness trackers, health monitors, smartwatches, and hybrid wearables by end-user category and distribution channel. The analytical framework modeled pricing tier dynamics, certification grade premiums, and regional regulatory cluster variations across the projection horizon. CAGRs derived from historical shipment trajectories, corporate wellness program adoption curves, and reimbursement policy evolution. Industry-specific forecast inputs included photoplethysmography sensor cost curves and FDA software-as-medical-device classification timelines.
Caveats apply where FDA software-as-medical-device reclassifications, lithium polymer supply disruptions, or smartwatch substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions about employer wellness mandate expansion and optical engineering talent availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Europe Watch Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Smart Bra Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Kids GPS Trackers and Wearables Market