
 Wearable Smart Device Market | 2026-2036
Wearable Smart Device Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Smart Device Market Insights
Asian contract manufacturers is restructuring capacity allocation toward medical-grade wearable assembly lines. Apple Inc. leverages its silicon design ecosystem to sustain margins across smartwatch portfolios. Samsung Electronics Co., Ltd. anchors display innovation in foldable and curved-screen form factors. Xiaomi Corporation competes aggressively on cost-engineered fitness trackers for emerging markets.
Wearable smart devices integrate sensors, microprocessors, wireless transceivers, and power management circuits into body-worn form factors, typically operating via Bluetooth Low Energy with continuous heart rate sampling at 100 Hz and accelerometer data fusion for motion classification; their primary purpose is real-time physiological and environmental data capture for health optimization, safety alerting, and workflow automation. Smartwatches dominate value capture due to premium pricing and ecosystem lock-in, while smart clothing represents the fastest-expanding margin pool as textile-integrated electrodes mature for clinical-grade ECG monitoring. Fitness tracking applications retain the largest installed base though remote patient monitoring is displacing consumer-grade revenue concentration toward reimbursable healthcare channels.
The FDA governs Class II medical device clearances for arrhythmia-detection wearables in the United States, while the EU MDR and GDPR impose clinical evidence and data residency requirements that lengthen approval timelines but raise competitive barriers for European market entry. China's NMPA and GB standards mandate electromagnetic compatibility testing and cybersecurity review for networked health devices sold domestically. Stakeholders must monitor whether reimbursement codes for continuous glucose monitoring and blood pressure wearables expand beyond diabetic populations to capture preventive care budgets.
Market Dynamics
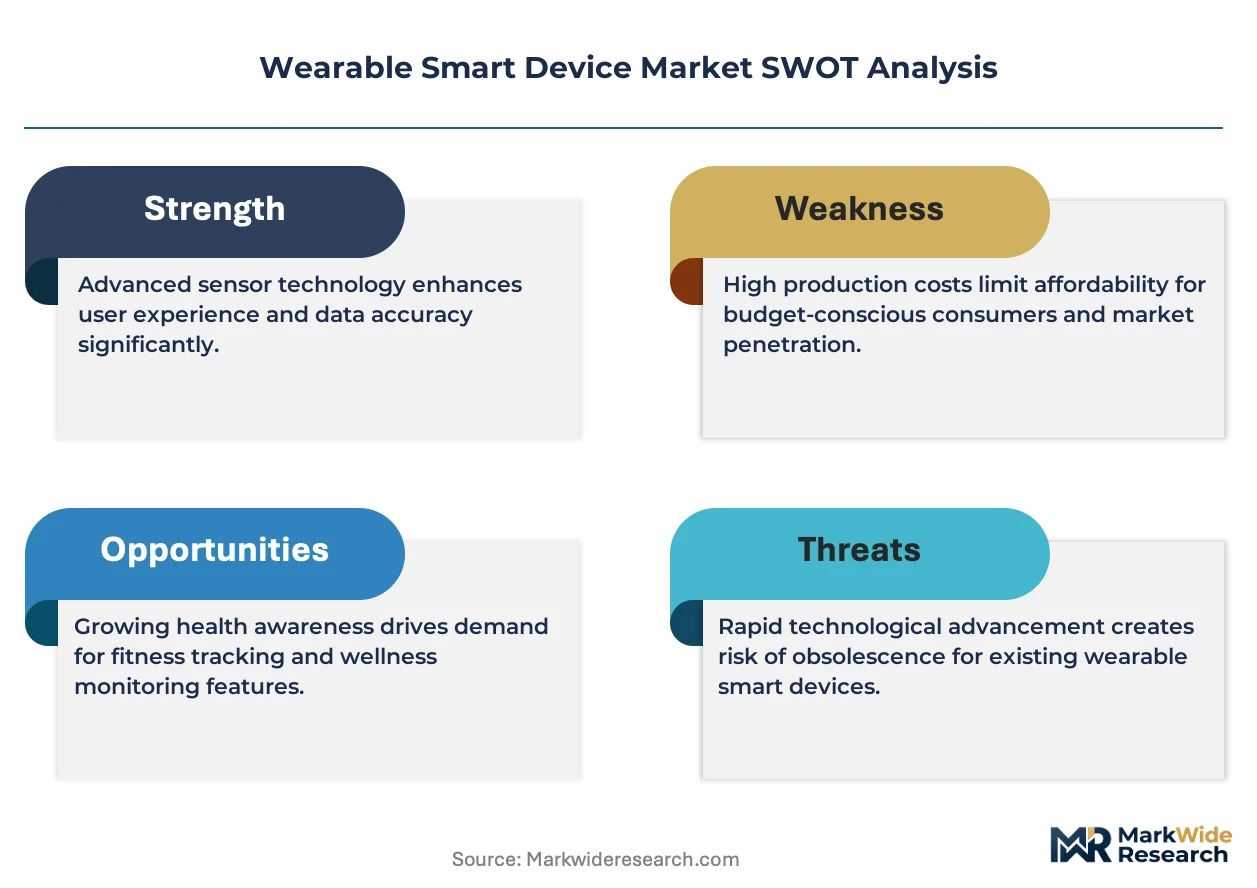
Healthcare reimbursement codes for continuous physiological monitoring are redirecting wearable demand from consumer retail channels toward reimbursable clinical workflows, forcing manufacturers to revalidate sensor accuracy against medical-grade standards.
Growth Catalysts
- Remote Patient Monitoring Mandates:Medicare reimbursement expansion for ambulatory cardiac monitoring drives hospital procurement of FDA-cleared wearables.
- China:NMPA fast-track pathways for AI-enabled diagnostic wearables accelerate domestic market authorization timelines.
- Textile-Embedded Electrodes:Advances in conductive yarn manufacturing enable clinical-grade ECG acquisition through machine-washable smart garments.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell production clusters in South Korea and Japan create single-source vulnerability for thin-form-factor power modules.
- GDPR Data Residency Requirements:EU cloud processing restrictions force wearable vendors to establish European edge-computing infrastructure.
- Smartphone Tethering Dependency:Bluetooth Low Energy range limitations constrain standalone functionality in rural connectivity gaps.
Strategic Opportunities
- Preventive Cardiology Programs:Employer-sponsored wellness budgets in Germany and France fund subsidized wearables for hypertension screening.
- AI Act Conformity:EU high-risk system classification creates first-mover advantage for biometric AI vendors achieving notified body certification.
- Pharmacy Distribution:CVS and Walgreens shelf placement for over-the-counter glucose monitors builds habit formation for wearable adoption.
Industry Challenges
- Biomedical Signal Processing Talent:Scarcity of engineers with combined expertise in MEMS sensor physics and machine learning model compression.
- ISO 14155 Clinical Trial Costs:Medical device validation studies for arrhythmia detection algorithms require multi-thousand-patient cohorts.
- Legacy Hospital IT Integration:HL7 FHIR interoperability gaps delay EHR connectivity for wearable data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Smart Device Market |
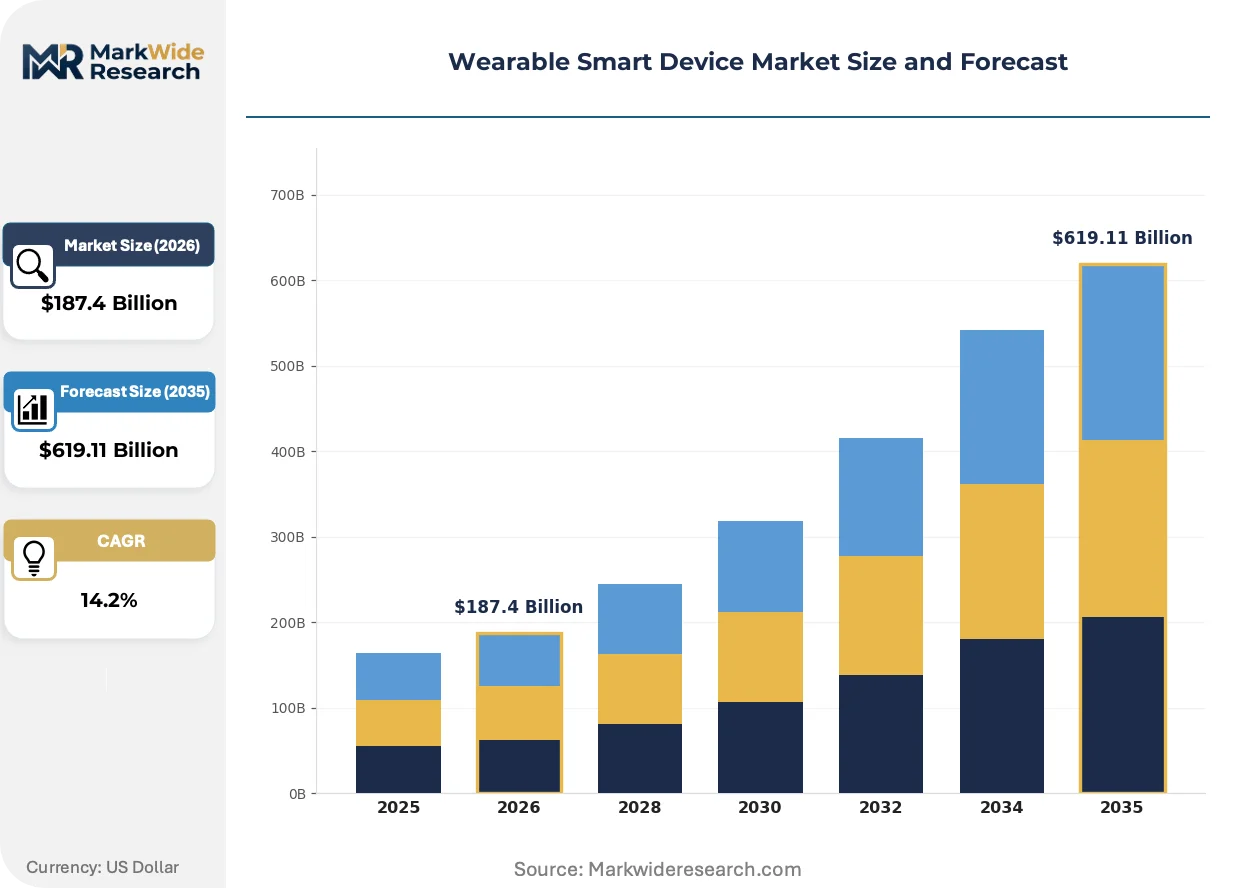
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Smart Clothing Technology: Bluetooth, RFID, NFC, Wi-Fi End User: Fitness Enthusiasts, Healthcare Providers, Consumers, Industrial Workers Application: Health Monitoring, Fitness Tracking, Remote Patient Monitoring, Personal Safety |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Alphabet Inc., Huawei Technologies, Xiaomi Corporation, Fossil Group Inc., Fitbit (Google LLC), Withings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Smart Device Market Trends and Innovations
Edge AI inference on wearable SoCs is eliminating cloud dependency for real-time health alerts, while regulatory frameworks coalesce around biometric data governance.
On-device neural processing units with sub-milliwatt power budgets are decentralizing machine learning execution from smartphone hosts to wrist-worn form factors. Cardiology departments in US health systems now specify local inference as a procurement requirement for patient data sovereignty. This architecture shift compresses alert latency from seconds to milliseconds for fall detection and atrial fibrillation classification.
The EU AI Act's high-risk system obligations for biometric identification impose conformity assessment burdens on heart-rate-variability algorithms used for stress scoring. Wearable OEMs must maintain technical documentation and human oversight protocols equivalent to Class IIa medical devices. Smartwatch vendors with European market exposure are restructuring quality management systems to accommodate notified body audits.
Direct-to-employer contracting is displacing retail channel dependence for workforce wellness deployments. Large self-insured employers in Texas and California negotiate volume pricing for continuous glucose monitoring patches as diabetes prevention benefits. This procurement model bypasses traditional consumer electronics margins and locks in multi-year sensor replacement cycles.
Wearable Smart Device Market Segmentation
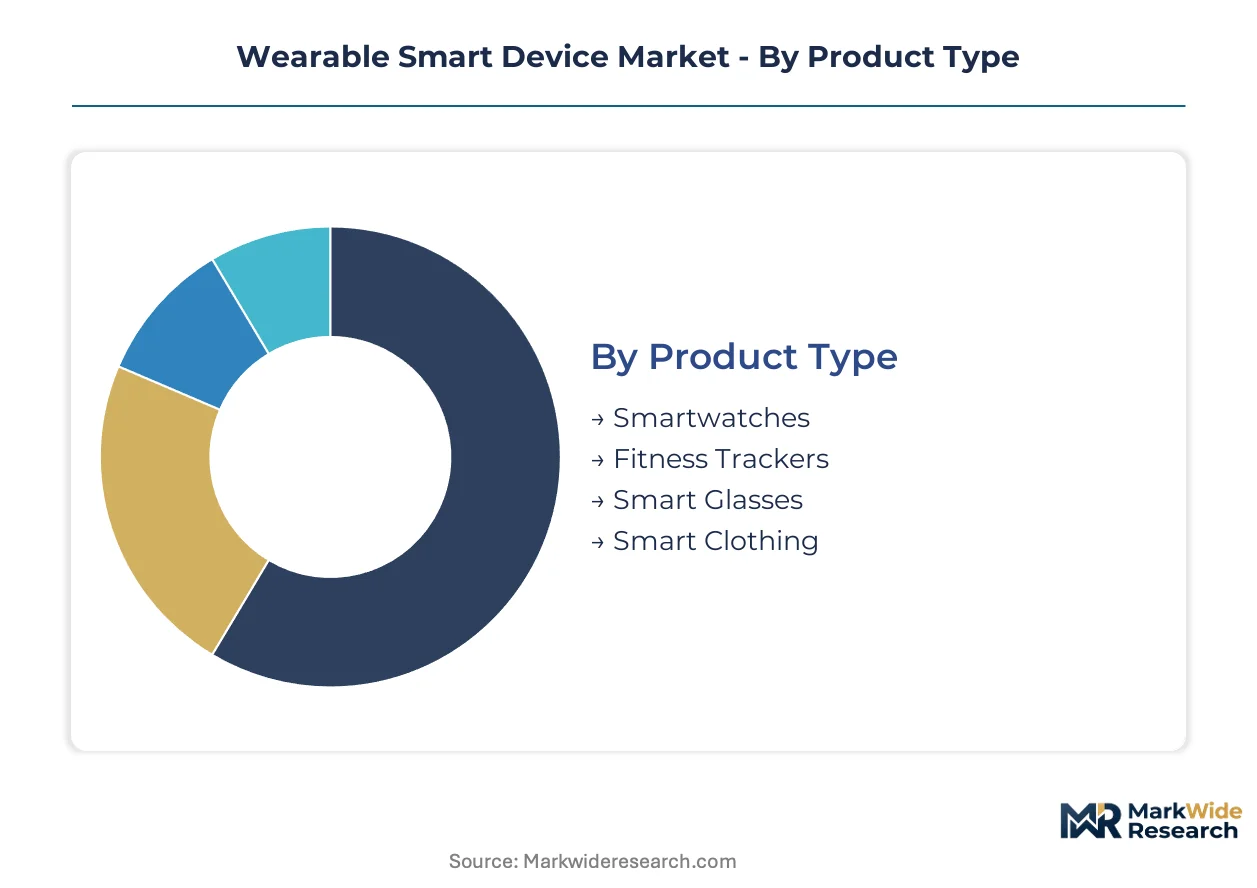
Segmentation reveals how wearable smart device manufacturers allocate R&D and manufacturing capacity across divergent technical requirements and reimbursement pathways. Product form factors, wireless protocols, end-user specifications, and application workflows each impose distinct sensor calibration, regulatory clearance, and channel strategies.
Product Type:
Supply concentration for MEMS sensors and flexible displays clusters around Shenzhen, Dongguan, and Seoul, shaping which form factors achieve cost-competitive scale.
- Smartwatches:Dominant value capture through premium pricing and ecosystem lock-in. Hospital procurement in the United States and Germany specifies FDA-cleared and MDR-compliant models for reimbursable cardiac monitoring workflows.
- Smart Clothing:Textile-integrated electrodes enable clinical-grade ECG acquisition through machine-washable garments. Demand concentrates in preventive cardiology programs across France and employer wellness budgets in California and Texas.
- Fitness Trackers:Cost-engineered units for emerging market volume.
- Smart Glasses:Industrial AR applications drive enterprise procurement.
Today's leader: Smartwatches. Tomorrow's challenger: Smart Clothing.
Technology:
Component sourcing for wireless transceivers traces to semiconductor foundries in Taiwan and South Korea, with protocol selection determining power budget and interoperability certification costs.
- Bluetooth:Bluetooth Low Energy dominates continuous heart rate sampling at 100 Hz with sub-milliwatt power budgets. Medicare reimbursement expansion for ambulatory cardiac monitoring in the United States mandates BLE connectivity for hospital-issued devices.
- Wi-Fi:Enables standalone cloud upload without smartphone tethering, critical for rural connectivity gaps. NMPA cybersecurity review requirements in China favor Wi-Fi implementations with local edge-processing architectures.
- RFID:Asset tracking and access control in industrial deployments.
- NFC:Payment authentication and medical record tap-to-transfer.
Bluetooth anchors installed base. Wi-Fi is climbing the fastest for clinical independence.
End User:
Pricing power and margin structure diverge sharply between consumer retail channels and reimbursable healthcare procurement, with regulatory clearance requirements acting as the sorting mechanism.
- Healthcare Providers:FDA Class II medical device clearances and EU MDR clinical evidence requirements create competitive barriers. Hospital systems in the United States now specify local AI inference for patient data sovereignty.
- Industrial Workers:OSHA-aligned safety alerting for fall detection and environmental hazard exposure. Demand concentrates in oilfield services across Texas and construction consortia in Germany.
- Fitness Enthusiasts:Consumer retail volume with minimal regulatory burden.
- Consumers:General-purpose lifestyle tracking through electronics retail.
Healthcare Providers command premium pricing. Industrial Workers show steepest expansion trajectory as safety mandates tighten.
Application:
Reimbursement code availability determines whether application workflows flow through consumer electronics margins or clinical procurement budgets with multi-year replacement cycles.
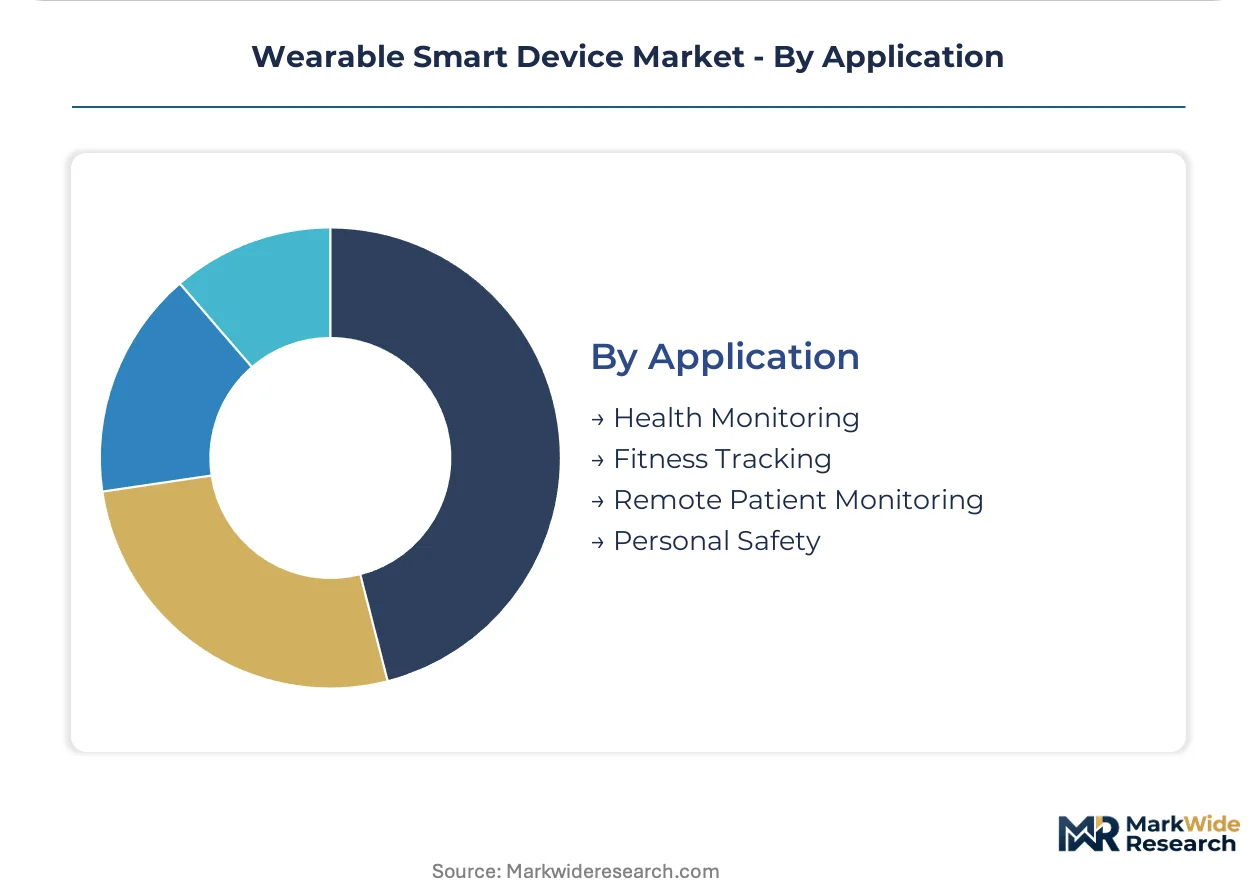
- Remote Patient Monitoring:Medicare reimbursement codes for continuous physiological monitoring redirect demand from retail toward reimbursable clinical workflows. FDA-cleared arrhythmia detection algorithms require ISO 14155 validation studies with multi-thousand-patient cohorts.
- Health Monitoring:Continuous glucose monitoring and blood pressure wearables seek expansion beyond diabetic populations into preventive care budgets in Germany and France.
- Fitness Tracking:Largest installed base though revenue concentration shifts toward healthcare channels.
- Personal Safety:Fall detection and emergency alerting for aging populations.
Remote Patient Monitoring is gaining share fastest. Health Monitoring holds largest addressable expansion pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns in Germany diverge sharply from consumer retail dominance in the United States, reflecting how reimbursement infrastructure shapes wearable demand curves.
United States
Medicare reimbursement expansion for ambulatory cardiac monitoring drives hospital procurement of FDA-cleared wearables. The FDA governs Class II medical device clearances for arrhythmia-detection algorithms with multi-thousand-patient validation requirements. Texas and California anchor employer-sponsored wellness budgets for continuous glucose monitoring patches.
Germany
Preventive cardiology programs across Bavaria and North Rhine-Westphalia fund subsidized wearables for hypertension screening through statutory health insurance. The EU MDR imposes clinical evidence and data residency requirements that lengthen approval timelines. Berlin hosts edge-computing infrastructure investments forced by GDPR cloud processing restrictions.
China
NMPA fast-track pathways for AI-enabled diagnostic wearables accelerate domestic market authorization timelines. GB standards mandate electromagnetic compatibility testing and cybersecurity review for networked health devices. Shenzhen and Dongguan manufacturing clusters concentrate MEMS sensor and flexible display supply.
France
Employer wellness budgets in Île-de-France and Auvergne-Rhône-Alpes expand preventive care allocations for wearable-based health screening. The EU AI Act's high-risk system obligations impose conformity assessment burdens on biometric identification algorithms. Paris anchors notified body audit preparation for heart-rate-variability stress scoring systems.
South Korea
MFDS medical device clearance pathways support domestic wearable OEMs targeting export markets. Lithium-polymer battery cell production clusters create single-source vulnerability for thin-form-factor power modules. Seoul anchors display innovation in foldable and curved-screen form factors for next-generation smartwatches.
Wearable Smart Device Market Competitive Landscape
East Asian producers anchor scale-driven supply tiers; North American and European specialists hold premium positioning through medical-grade certification stacks. Market structure consolidates around three archetypes: silicon-integrated ecosystem players, display-forward hardware specialists, and cost-engineered volume manufacturers. Competitive moves concentrate on M&A for sensor technology access and capacity expansion for medical-grade assembly lines.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics Co., Ltd. exemplify premium positioning through captive silicon and display supply chains. Xiaomi Corporation occupies a cost-engineered volume position targeting emerging market fitness tracker deployment. Garmin Ltd. anchors specialized positioning in GPS-integrated outdoor performance wearables. Each represents distinct margin architecture: premium ecosystem lock-in, component verticalization, and cost-optimized scale respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Alphabet Inc. |
| Huawei Technologies |
| Xiaomi Corporation |
| Fossil Group Inc. |
| Fitbit (Google LLC) |
| Withings |
| Others |
Pricing and Supply Chain Analysis
Textile-embedded electrode manufacturing is migrating from specialty batch production to roll-to-roll conductive yarn processing, collapsing unit costs for clinical-grade ECG garments while concentrating capacity among Korean and Japanese chemical fiber producers. This process shift simultaneously enables price accessibility for preventive cardiology programs and tightens supply control over conductive polymer formulations.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for lithium-polymer battery cells that power thin-form-factor wearables. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical devices from consumer-grade fitness trackers and white-label OEM units. Cost compression in the economy tier is intensifying because Chinese contract manufacturers are absorbing margin erosion to maintain Shenzhen assembly line utilization. Employer wellness procurement committees show lowest price sensitivity due to multi-year sensor replacement contracts, while emerging market retail consumers drive hardest bargain hunting.
Supply Chain Analysis
Returns and refurbishment flows for smartwatch trade-in programs are creating secondary component markets that compete with virgin MEMS sensor procurement. Component sourcing draws from Taiwan for semiconductor foundry output, South Korea for OLED flexible displays, and China for final assembly integration. Raw material dependencies include lithium carbonate for power modules, rare earth elements for micro motor actuators, and conductive silver inks for textile electrodes. Single-source vulnerability concentrates in South Korean battery cell production. Distribution runs through hospital procurement committees for reimbursable devices and electronics retail chains for consumer units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because Medicare reimbursement expansion for ambulatory cardiac monitoring locks in recurring hospital procurement cycles with multi-year replacement guarantees.
For Market Incumbents: Anticipate margin compression from Chinese cost-engineered fitness trackers by deepening backward integration into captive silicon design ecosystems. Defend hospital procurement relationships through ISO 14155 clinical trial investments that erect regulatory barriers against unvalidated sensor competitors. Prioritize edge-AI inference capabilities as Texas and California health systems now specify local processing for patient data sovereignty. For New Entrants and Emerging Players: Enter via employer-sponsored wellness channels in Germany and France where statutory health insurance funds subsidized hypertension screening programs with limited incumbent penetration. Target textile-embedded ECG garments for preventive cardiology applications as the fastest-expanding margin pool with nascent competitive density. Pursue pharmacy distribution partnerships with CVS and Walgreens for over-the-counter glucose monitor shelf placement that builds wearable adoption habit formation. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with medical-grade assembly certifications but lacking branded device portfolios. Long-term viability hinges on regulatory clearance moats rather than consumer electronics margin cycles. Acquisition targets should display combined MEMS sensor physics and machine learning model compression talent scarcity. Monitor NMPA fast-track pathway expansion for AI-enabled diagnostic wearables as inflection signal for Chinese domestic market authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Medical Device Clearance Investment | FDA Class II and EU MDR certifications unlock reimbursable hospital procurement workflows in Texas and Bavaria. |
| Conductive Yarn Manufacturing Scale-Up | Roll-to-roll textile electrode production enables machine-washable smart garment cost parity with conventional monitors. |
| Edge Computing Infrastructure Deployment | GDPR-mandated European data residency forces localized processing investments in Berlin and Paris. |
| Hospital System Partnership | Direct procurement relationships with US health systems bypass retail margin erosion and secure multi-year replacement cycles. |
| AI Algorithm Validation Study | ISO 14155 multi-thousand-patient cohorts satisfy Medicare reimbursement requirements for arrhythmia detection accuracy. |
Research Methodology
Multiple input streams — hospital procurement database analysis, contract manufacturer capacity surveys, and regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and wearable OEM supply chain directors informed demand-side validation. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body certifications, NMPA fast-track pathway disclosures, and CMS Medicare reimbursement code updates. Cross-referencing against customs records for MEMS sensor and lithium-polymer battery trade flows verified supply-side assumptions.
Data-stream reconciliation across product form factor, wireless protocol, end-user specification, and application workflow dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume build-ups validated against macro healthcare expenditure trajectories. Industry-specific forecast inputs incorporated reimbursement code expansion timelines for continuous glucose monitoring and blood pressure wearables, plus NMPA cybersecurity review processing rates for networked health devices.
Inputs from FDA and NMPA regulatory databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around quarterly demand estimates. Forecasts reflect documented assumptions regarding Medicare reimbursement continuity and EU AI Act implementation pacing. Practitioners should monitor employer wellness budget allocations in Germany and France plus NMPA fast-track pathway velocity for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Kids Watch Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Smart Band Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market