
 Wearable Camera Market | 2026-2036
Wearable Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Camera Market Intelligence
The EU Green Deal is expanding compliance obligations for electronics manufacturers serving European markets. GoPro leverages its direct-to-consumer channel strength and subscription ecosystem to sustain recurring revenue beyond hardware sales. Sony anchors premium image sensor supply across multiple wearable OEMs, while Axon Enterprise dominates public-sector procurement through integrated evidence-management software. Insta360 competes aggressively in 360-degree capture formats for content creators seeking immersive output.
A wearable camera integrates compact optical sensors, stabilized imaging processors, and wireless connectivity into body-worn or mountable form factors, typically weighing under 250 grams and capturing video at resolutions from 1080p to 5.7K for evidence documentation, athletic performance analysis, or broadcast content generation. Body cameras for law enforcement represent the most structurally concentrated revenue pool due to multi-year municipal contracts and mandatory deployment policies across US police departments. Action cameras targeting sports enthusiasts retain the highest consumer brand recognition and accessory attach rates. Smart glasses with embedded cameras are attracting renewed development investment from enterprise logistics and remote-assistance applications despite earlier consumer failures.
FCC certification governs radio-frequency emissions for all wearable cameras sold in the United States, while the EU's RoHS and REACH frameworks restrict hazardous substances in batteries and circuit assemblies. The EU AI Act introduces additional scrutiny for devices with facial recognition or biometric processing capabilities, directly impacting product roadmaps. Stakeholders must monitor evolving battery transport regulations and right-to-repair mandates that threaten sealed-unit designs and proprietary firmware lockdowns.
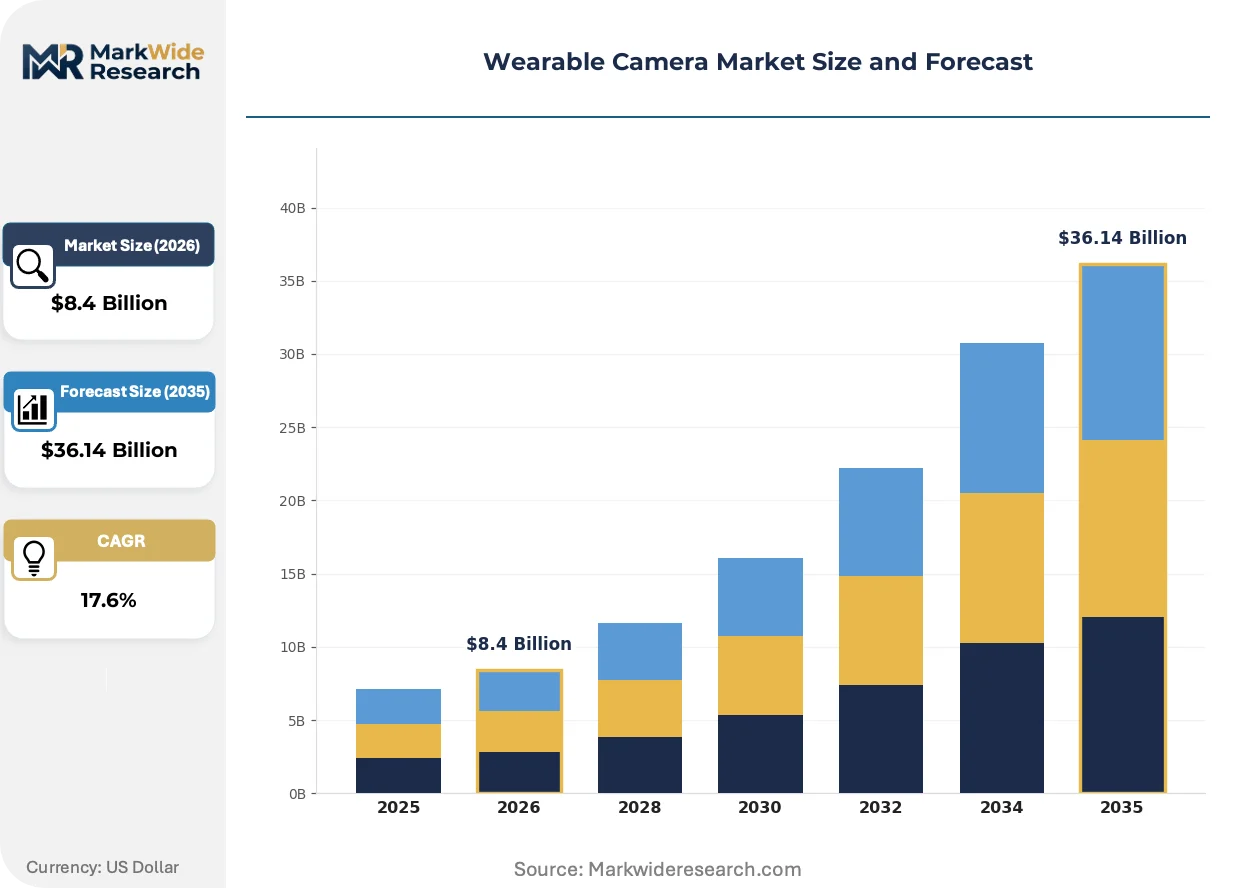
Market Dynamics
Law enforcement procurement mandates and EU sustainability regulations are forcing simultaneous hardware upgrades and supply chain reconfigurations across wearable camera manufacturers.
Growth Catalysts
- Police Department Mandates:Municipal body-worn camera deployment policies across United States police departments are generating multi-year procurement contracts with predictable replacement cycles.
- Ecodesign for Sustainable Products Regulation:The EU framework is pressuring manufacturers to redesign devices for repairability and recycled content integration, creating upgrade demand from compliance-driven replacements.
- Image Sensor Advancement:Compact optical sensors capable of 5.7K resolution capture are expanding evidence documentation quality standards in forensic applications.
Market Restraints
- Lithium-Ion Supply Concentration:China's dominance over compact lithium-ion power system manufacturing creates geopolitical exposure for battery-dependent form factors.
- AI Act Compliance Friction:The EU's biometric processing restrictions are extending product development timelines for facial recognition capabilities.
- Sealed-Unit Design Limitations:Right-to-repair mandates threaten proprietary firmware lockdowns and integrated battery architectures that manufacturers rely on for water resistance ratings.
Strategic Opportunities
- Enterprise Logistics Smart Glasses:Remote-assistance applications in warehouse operations and field service are attracting renewed development investment despite earlier consumer failures.
- Subscription Ecosystem Expansion:Cloud-based evidence management and content storage services offer recurring revenue streams beyond hardware replacement cycles.
- 360-Degree Content Creation:Immersive capture formats for athletic performance analysis and broadcast content generation represent underpenetrated professional segments.
Industry Challenges
- FCC Certification Timelines:Radio-frequency emissions testing for wireless connectivity features creates bottlenecks for product launches in United States markets.
- Stabilized Imaging Processor Integration:Miniaturization of gimbal mechanisms and electronic image stabilization into sub-250 gram form factors demands specialized mechanical engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Camera Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Camera, Action Camera, Smart Glasses, Helmet Camera Technology: Bluetooth, Wi-Fi, 4G, GPS End User: Law Enforcement, Sports Enthusiasts, Filmmakers, Travelers Application: Security, Adventure Sports, Content Creation, Documenting |
| Companies Covered | GoPro, Sony, Garmin, DJI, Insta360, Axon Enterprise, Panasonic, Digital Ally, Narrative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Camera Market Strategic Shifts & Innovations
Component miniaturization and regulatory fragmentation are simultaneously compressing device footprints while expanding compliance scope across wearable camera architectures.
Edge AI inference engines are modularizing across body-worn camera platforms, enabling real-time object recognition and threat detection without cloud dependency. Law enforcement agencies in Germany and France are piloting these capabilities for officer safety applications. This architecture is modularizing hardware-software boundaries, allowing sensor modules to swap between vendors while retaining proprietary analytics layers.
The EU AI Act's biometric processing restrictions are forcing facial recognition features into separate hardware modules that can be deactivated for European market variants. Manufacturers must maintain dual firmware branches and certification documentation, increasing quality assurance overhead. Public-sector procurement in Spain and Italy now explicitly excludes non-compliant devices from tender eligibility.
Municipal evidence-management platforms are consolidating vendor selection around integrated software-hardware bundles rather than standalone hardware procurement. Police departments in Texas and California are mandating API compatibility with existing digital evidence systems as a precondition for contract award. This specification tightening favors incumbent platform providers with established certification relationships.
Wearable Camera Market Segmentation
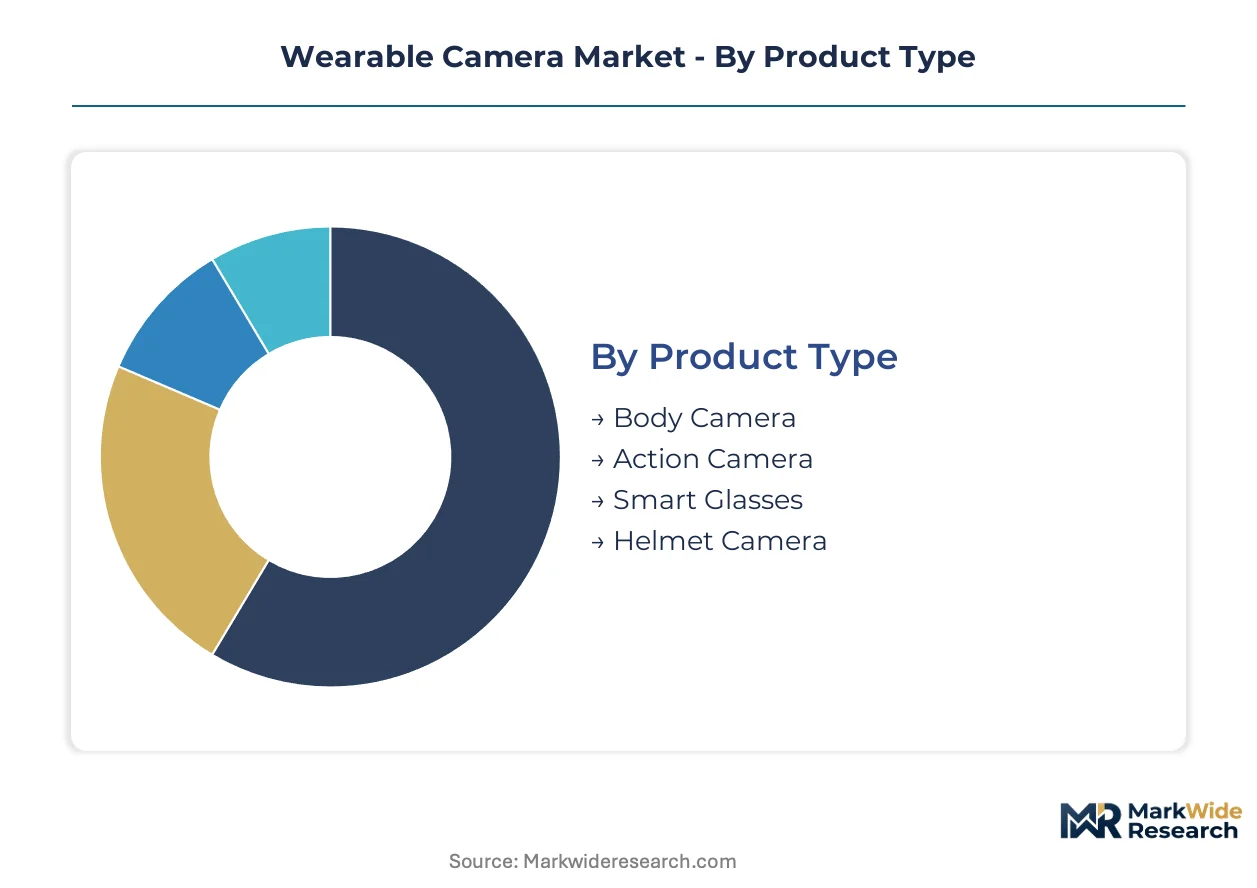
Wearable camera architectures diverge sharply across use cases, with body-worn evidence systems demanding ruggedized durability while action cameras prioritize stabilization and mounting flexibility. Segmentation reveals how procurement channels, connectivity requirements, and content workflows reshape competitive positioning across hardware categories.
Product Type:
Volume concentrates in law enforcement body cameras with municipal contract scale, while premium pricing attaches to professional filmmaking configurations and enterprise smart glasses.
- Body Camera:Ruggedized units weighing 150-200 grams integrate tamper-evident encryption and pre-event buffering for evidence integrity. Procurement concentrates in United States municipal police departments with multi-year replacement mandates under federal grant programs. Axon Enterprise dominates through integrated evidence-management software lock-in.
- Action Camera:Sub-100 gram waterproof housings with hyper-smooth electronic stabilization target sports enthusiasts and content creators. Demand clusters in North American and Australian outdoor recreation markets where accessory ecosystems drive attach rates.
- Smart Glasses:Enterprise variants with embedded cameras enable hands-free remote assistance for logistics and field service operations. Pilot deployments in German automotive manufacturing and Japanese warehouse operations signal renewed viability after consumer segment failures.
- Helmet Camera:Impact-resistant mounts serve military training documentation and industrial safety compliance in mining and construction sectors. Regulatory pressure from OSHA-equivalent bodies in Australia and Canada drives specification tightening.
Today's leader: Body Camera. Tomorrow's challenger: Smart Glasses.
Technology:
Connectivity architecture determines real-time capability versus battery endurance tradeoffs, with cellular integration commanding premium positioning in public safety applications.
- Bluetooth:Low-energy pairing enables smartphone tethering for configuration and media offload in consumer action cameras. Ubiquity in entry-tier devices limits differentiation potential.
- Wi-Fi:Local streaming supports live viewfinder functionality and rapid content upload for travel bloggers and sports filmmakers. FCC certification timelines create launch bottlenecks for United States market entry.
- 4G:Cellular connectivity enables real-time evidence streaming and officer safety alerts in law enforcement deployments. Procurement specifications in Texas and California increasingly mandate LTE capability as contract precondition.
- GPS:Geolocation tagging provides chain-of-custody verification for forensic evidence and route tracking for athletic performance analysis. Integration with Galileo and GLONASS systems expands precision in European and Russian markets.
4G-equipped units capture the steepest expansion trajectory as real-time evidence workflows displace dock-and-upload architectures.
End User:
Customer type segmentation maps directly to channel structure, with public-sector procurement favoring integrated platform vendors while consumer segments reward brand marketing and retail distribution.
- Law Enforcement:Municipal agencies with mandatory deployment policies generate predictable replacement cycles and evidence-management software subscriptions. United States federal grant funding accelerates procurement velocity.
- Sports Enthusiasts:Weekend athletes and outdoor adventurers drive seasonal demand peaks with high accessory attach rates for mounts and protective housings. Brand loyalty concentrates around content creator influencer ecosystems.
- Filmmakers:Professional content producers demand 5.7K resolution, log color profiles, and multi-camera synchronization for broadcast and streaming production. 360-degree capture formats attract immersive content specialists.
- Travelers:Compact form factors prioritize portability and quick-capture convenience for social media documentation. Price sensitivity runs highest in this segment with heavy cross-shopping against smartphone camera capabilities.
Law Enforcement anchors current revenue concentration. Filmmakers represent the fastest-climbing premium tier as resolution and workflow integration demands escalate.
Application:
Use case segmentation reveals diverging durability, connectivity, and software requirements, with security applications demanding encryption while adventure sports prioritize environmental sealing.
- Security:Evidence-grade capture with tamper detection and audit trails serves law enforcement, private security, and critical infrastructure monitoring. EU AI Act biometric restrictions are forcing facial recognition features into modular hardware deactivatable for European variants.
- Adventure Sports:Waterproofing, shock resistance, and stabilization dominate specification priorities for surfing, skiing, and mountain biking documentation. Australian and New Zealand markets show particular density of enthusiast penetration.
- Content Creation:YouTube, TikTok, and streaming platform creators drive demand for cinematic color science and vertical-format native capture. Subscription cloud storage services attach to hardware purchases for recurring revenue.
- Documenting:Personal memory capture and travel journaling favor simplicity and automatic backup integration. Smartphone convergence threatens standalone device relevance in this casual-use segment.
Security applications command the highest average selling prices. Content Creation exhibits the most rapid feature cycle turnover as platform algorithm changes reshape capture priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Shenzhen, San Francisco, and Tokyo anchor wearable camera development pipelines. Manufacturing workforce concentration in Guangdong Province and Bavaria shapes component sourcing decisions. Regulatory compliance specialists concentrate in Brussels and Washington DC.
United States
Municipal police departments in Texas and California drive body-worn camera procurement through federal grant programs. FCC certification timelines create bottlenecks for wireless-enabled device launches. Austin and Los Angeles host evidence-management software integration hubs serving multi-agency deployments.
Germany
Automotive manufacturers in Stuttgart and Munich pilot smart glasses for assembly-line remote assistance. EU AI Act biometric restrictions force facial recognition features into modular hardware deactivatable for European variants. Bavaria hosts industrial safety compliance testing facilities for helmet-mounted documentation systems.
China
Shenzhen and Dongguan concentrate image sensor fabrication and compact lithium-ion battery assembly capacity. MIIT standards govern wireless transmission protocols for domestic market devices. Guangdong Province suppliers feed component pipelines for action camera OEMs worldwide.
Japan
Content creator demand in Tokyo and Osaka sustains premium action camera accessory ecosystems. METI guidelines influence imaging processor efficiency standards. Nagoya engineering clusters specialize in stabilized gimbal miniaturization for sub-100 gram form factors.
Australia
Adventure sports enthusiasts in Queensland and New South Wales drive seasonal demand peaks for waterproof housings. TGA-equivalent workplace safety regulations mandate impact-resistant documentation in mining operations. Perth hosts industrial safety compliance certification bodies for resource sector deployments.
Wearable Camera Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the wearable camera value chain. Image sensor foundries and battery cell manufacturers anchor the supply base, while brand marketers and software integrators capture downstream margin pools. Three archetypes dominate: integrated platform vendors bundling hardware with evidence-management subscriptions, component specialists supplying optical modules across multiple OEMs, and direct-to-consumer brands building content creator ecosystems. Competitive moves concentrate on cloud service attach rates and API certification relationships with municipal procurement systems.
Within the integrated platform tier, Axon Enterprise exemplifies the evidence-management software lock-in model. Among diversified electronics conglomerates, Sony and Panasonic occupy positions anchoring premium image sensor supply across wearable OEM portfolios. GoPro represents the direct-to-consumer archetype leveraging subscription ecosystems for recurring revenue beyond hardware replacement cycles.
| Leading Market Players |
|---|
| GoPro |
| Sony |
| Garmin |
| DJI |
| Insta360 |
| Axon Enterprise |
| Panasonic |
| Digital Ally |
| Narrative |
| Others |
Cost & Logistics Intelligence
Municipal police procurement programs in the United States concentrate buying power into multi-year evidence-management contracts, anchoring premium pricing for integrated hardware-software bundles while consumer action camera tiers compete on accessory attach rates and subscription conversion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates law enforcement body cameras with encrypted evidence chains from action cameras targeting content creators and entry-level travelers. Price differentiation hinges on certification grade for FCC and EU AI Act compliance plus volume scale in municipal tenders. Cost compression in the consumer tier is intensifying because smartphone camera convergence erodes standalone device value. Travelers exhibit the highest price sensitivity, while public safety agencies prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Image sensor fabrication rests on Japanese and South Korean specialty foundries, while compact lithium-ion cell assembly concentrates in China's Guangdong Province. Raw material dependencies span cobalt and lithium feedstocks, optical glass substrates, and stabilized gimbal motors. Single-source vulnerability in battery cell supply creates tariff exposure and logistics chokepoint risk as geopolitical friction disrupts component flows. Distribution runs through direct-to-consumer channels for action cameras and authorized reseller networks for law enforcement procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance costs in Europe run substantially higher than FCC certification burdens in the United States, creating arbitrage opportunities for manufacturers optimizing regional product variants.
For Market Incumbents: Hedge against right-to-repair mandate proliferation by modularizing battery and sensor architectures before sealed-unit designs face regulatory obsolescence. Deepen backward integration into image sensor supply through captive partnerships with Sony or Panasonic foundries. Prioritize API certification investments with Texas and California evidence-management platforms to lock in municipal contract renewals.
For New Entrants and Emerging Players: Enterprise logistics integrators represent the most accessible channel partner type for smart glasses pilots in German automotive and Japanese warehouse deployments. White-space targets include 360-degree filmmaking workflows for immersive content creators and helmet-mounted safety documentation for Australian mining operations. A software-first go-to-market angle emphasizing cloud evidence storage subscriptions bypasses hardware margin compression.
For Investors and Strategic Acquirers: Cloud software vendors serving law enforcement evidence management are the most active acquirer in this space, seeking hardware attach points for platform expansion. Long-term viability favors integrated platform providers with sticky municipal relationships over pure-play component suppliers. Watch EU Ecodesign enforcement intensity as the inflection indicator for compliance-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Ecosystem Expansion | Recurring revenue from Axon Evidence cloud storage reduces hardware replacement cycle dependency. |
| EU AI Act Modularization | Separable facial recognition hardware enables European market compliance without global product redesign. |
| Enterprise Smart Glasses Pilot | Remote-assistance deployments in Stuttgart automotive plants validate logistics use case viability. |
| Image Sensor Backward Integration | Captive supply agreements with Sony foundries secure 5.7K resolution pipeline for forensic applications. |
| Right-to-Repair Pre-Compliance | Modular battery architectures anticipate EU Ecodesign mandates threatening sealed-unit waterproof designs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with police procurement officers, evidence-management software architects, action camera product managers, and optical sensor R&D directors with secondary validation against FCC certification databases, EU AI Act regulatory filings, and municipal contract award records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting approaches modeled product type, connectivity technology, end user vertical, and application use case dimensions across the projection horizon. CAGRs derived from logistic growth curve fitting adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated federal grant funding velocity for US law enforcement and EU Green Deal compliance timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply chain disruption and biometric processing regulatory expansion. Forecasts reflect documented assumptions about municipal replacement cycle regularity and smartphone convergence pressure. A small set of named triggers—EU Ecodesign enforcement rulings, China export control escalations, and major platform algorithm shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Global Smart Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Kids Watch Market
Wearable Technology
Pet Wearable Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Women's Watch Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Smart Band Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Consumer Grade Smart Wearable Device Market