
 Kids Smart Watch Market | 2026-2036
Kids Smart Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Smart Watch Market Insights
Platform licensing revenue from third-party app ecosystems is fragmenting as hardware makers build captive software environments. Apple sustains premium positioning through tight integration of its wearable operating system with family-sharing controls. Xiaomi competes on manufacturing scale, leveraging Shenzhen-based component sourcing to undercut rivals on bill-of-materials costs. VTech Holdings Limited anchors the preschool demographic with simplified interfaces that sidestep cellular subscription requirements.
A kids smart watch is a wrist-worn computing device engineered for children typically aged four to twelve, incorporating GPS positioning modules, two-way voice communication, and biometric sensors within IP67-rated or higher enclosures. Its primary commercial purpose is to provide guardians with real-time location telemetry and direct communication channels while restricting access to unvetted digital content. Communication watches command the deepest margin pools because recurring cellular service agreements generate annuity revenue streams alongside hardware sales. Fitness monitors represent the fastest-growing product type as schools in multiple countries integrate step-counting and sleep-tracking into physical education curricula. Bluetooth-enabled devices still dominate unit shipments, though cellular SKUs capture disproportionate value due to monthly data plan attachments.
FCC certification mandates in the United States govern specific absorption rate limits and emergency communication protocols for wearable devices with cellular radios. GDPR-K and COPPA frameworks impose strict boundaries on geolocation data retention and require verifiable parental consent before any personal information collection begins. China's SAMR enforces GB standard compliance for lithium-ion battery safety in devices marketed to minors. Stakeholders must monitor evolving interoperability requirements between proprietary parental-control applications and third-party emergency services platforms.
Market Dynamics
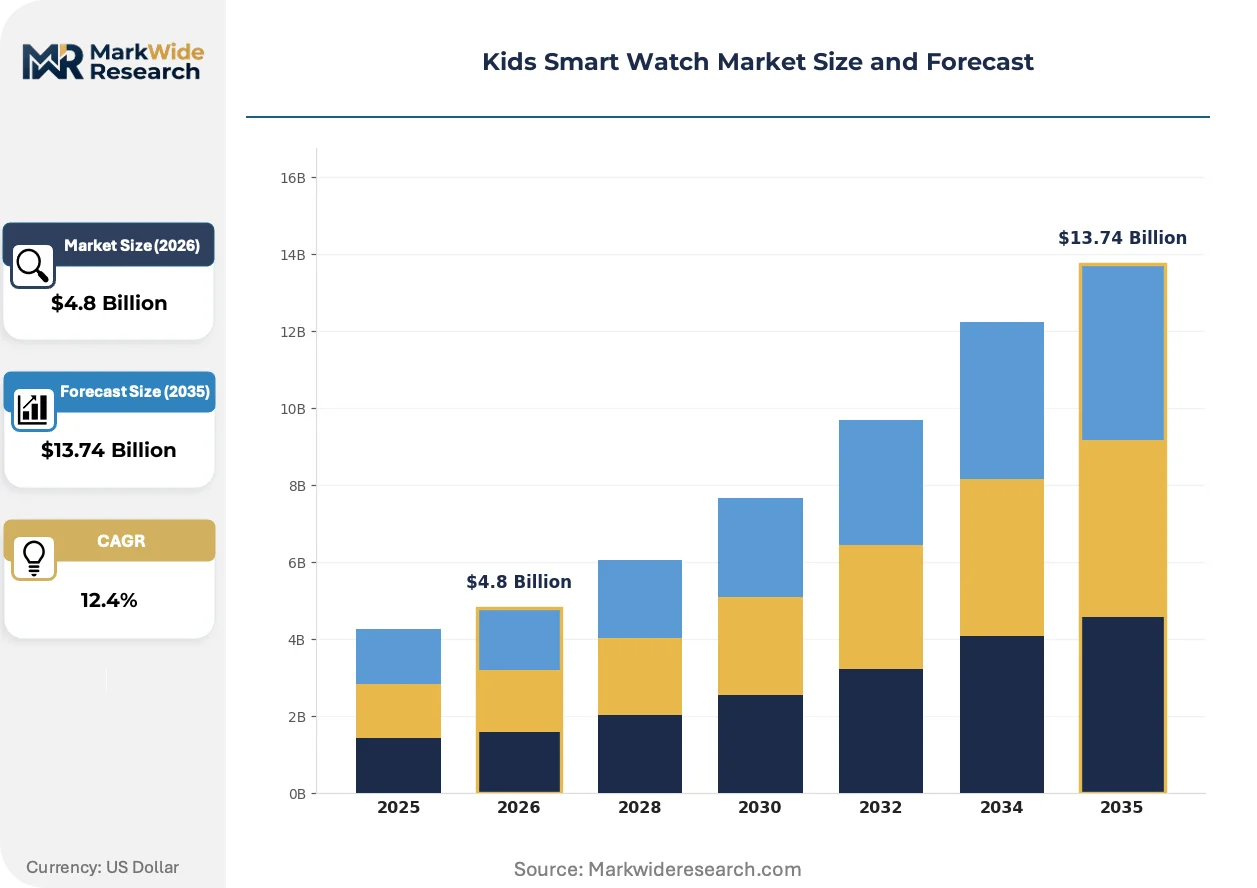
Cellular subscription bundling is restructuring profit pools away from hardware margins toward recurring service revenue, forcing OEMs to rearchitect go-to-market strategies around carrier partnerships rather than retail channel dominance.
Growth Catalysts
- COPPA-compliant parental consent architectures:US vendors embedding verifiable consent workflows unlock school district procurement channels previously closed to connected devices.
- Physical education curriculum mandates:School systems in South Korea and Japan now require biometric activity tracking, converting fitness monitors from consumer discretionary to institutional required purchases.
- Shenzhen component clustering:Concentrated battery and GPS module manufacturing compresses bill-of-materials costs for cellular-enabled SKUs.
Market Restraints
- Lithium-ion cell supply concentration:GB standard certification through China's SAMR creates 8-14 week approval bottlenecks for non-domestic vendors.
- GDPR-K data localization requirements:European geolocation telemetry must reside on EU servers, fragmenting cloud infrastructure economics.
- Smartphone substitution pressure:Hand-me-down iOS and Android devices from parents displace standalone watch purchases for children over age ten.
Strategic Opportunities
- Rural India connectivity gaps:Offline-first GPS tracking with delayed sync protocols addresses areas lacking consistent cellular coverage.
- EMA-connected health monitoring:EU medical device regulation pathways open reimbursement channels for pediatric sleep and activity tracking.
- Telecom carrier white-label programs:Mobile network operators seek differentiated family plan attachments through exclusive hardware partnerships.
Industry Challenges
- FCC SAR certification timelines:Specific absorption rate testing for wrist-worn cellular radios extends product launch windows by 90-120 days.
- Parental control app fragmentation:Proprietary supervision software lacks interoperability with third-party emergency services platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Smart Watch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.74 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, Fitness Monitors, Gaming Watches, Communication Watches Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Parents, Schools, Childcare Centers, Retailers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Garmin Ltd., Xplora Technologies, Apple Inc., Koninklijke Philips N.V., LG Electronics, Xiaomi Corporation, VTech Holdings Limited, Fitbit Inc., Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Smart Watch Market Trends and Innovations
Edge computing architectures are displacing cloud-dependent processing, enabling real-time biometric analysis without persistent connectivity and reducing latency-critical safety alert failures.
eSIM technology is migrating from premium-tier cellular watches toward mid-market SKUs, eliminating physical SIM tray engineering and enabling over-the-air carrier provisioning. Chinese OEMs led by manufacturing clusters in Shenzhen adopted embedded subscriber identity modules at scale during 2023-2024. This migration from removable to integrated connectivity is compressing distribution margins previously captured by carrier retail stores.
GDPR-K enforcement through France's CNIL and Germany's state data protection authorities is tightening geolocation retention limits to 30-day maximums. Vendors must now deploy automated data purging workflows or face per-violation penalties. Preschool-focused devices with simplified consent mechanisms face disproportionate compliance burden relative to teen-oriented products with explicit user interfaces.
School district procurement consolidation is displacing individual parent purchases as the dominant volume channel. District technology coordinators now issue RFPs for district-wide fitness monitoring programs with centralized dashboard administration. This behavioral shift is most visible in Japan's municipal education boards and Texas independent school districts, where bulk purchasing agreements override retail preference.
Kids Smart Watch Market Segmentation
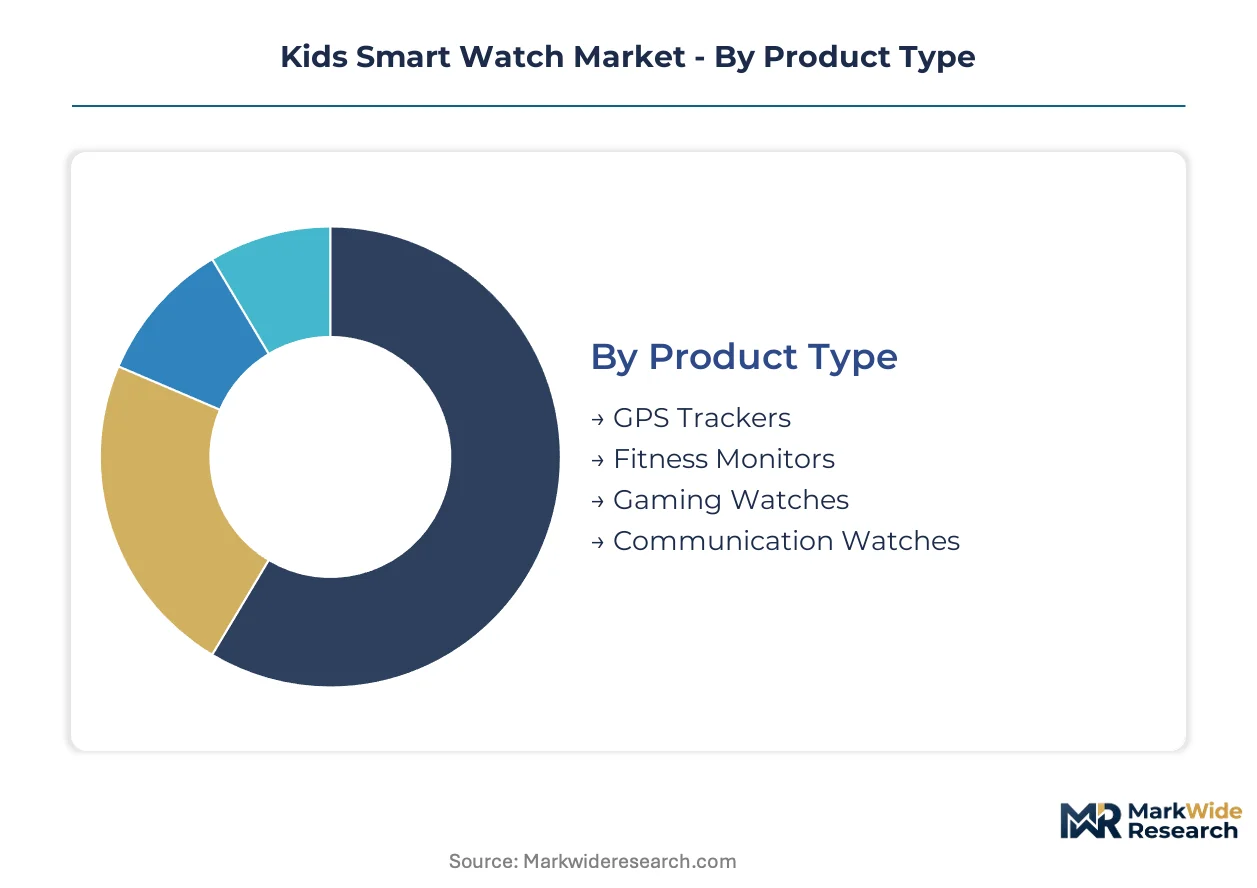
Segmentation in the kids smart watch market reveals distinct profit pools and regulatory exposure profiles. Product architecture choices determine COPPA compliance burden, while connectivity technology shapes carrier partnership viability and recurring revenue potential.
Product Type:
Application focus differentiates hardware specifications, content restrictions, and parental control complexity across this dimension.
- Communication Watches:Two-way voice and messaging capabilities with embedded cellular radios require FCC SAR certification. School district procurement in Texas and Japan favors these units for emergency contact protocols.
- Fitness Monitors:Biometric sensors track step counts, sleep patterns, and heart rate variability without cellular subscription requirements. South Korean and Japanese physical education mandates are converting these from discretionary purchases to institutional requirements.
- Gaming Watches:Gamified activity tracking with simplified touch interfaces targets the four-to-seven age bracket.
- GPS Trackers:Location-only devices with geofencing alerts serve as entry-tier safety tools for budget-conscious guardians.
Communication watches command the established base. The steepest expansion runs through fitness monitors.
Technology:
Connectivity tier determines cloud infrastructure requirements, data localization obligations, and hardware bill-of-materials structure.
- Cellular:eSIM-enabled devices with over-the-air provisioning capture recurring carrier revenue alongside hardware margins. Shenzhen component clustering compresses manufacturing costs for these SKUs.
- Bluetooth:Tethered connectivity to parental smartphones dominates unit shipments but lacks standalone emergency communication capability.
- Wi-Fi:Campus and home-bound devices reduce cellular data costs while enabling richer content synchronization.
- NFC:Contactless payment and access control integration targets the upper elementary demographic in urban China.
Cellular-enabled units anchor premium positioning. Bluetooth SKUs are gaining share fastest in price-sensitive emerging markets.
End User:
Customer type shapes purchasing authority, volume scale, and post-sale support expectations.
- Schools:District technology coordinators issue RFPs for centralized dashboard administration and bulk device management. Municipal education boards in Japan and independent school districts in Texas are consolidating procurement away from individual parent purchases.
- Parents:Individual guardians prioritize geofencing reliability and simplified consent workflows for COPPA compliance.
- Childcare Centers:Supervised environment deployments emphasize durable enclosures and shared charging infrastructure.
- Retailers:Carrier stores and electronics chains demand margin structures that accommodate promotional discounting cycles.
Parental purchasers command the established base. Institutional buyers are climbing the fastest as procurement channels shift.
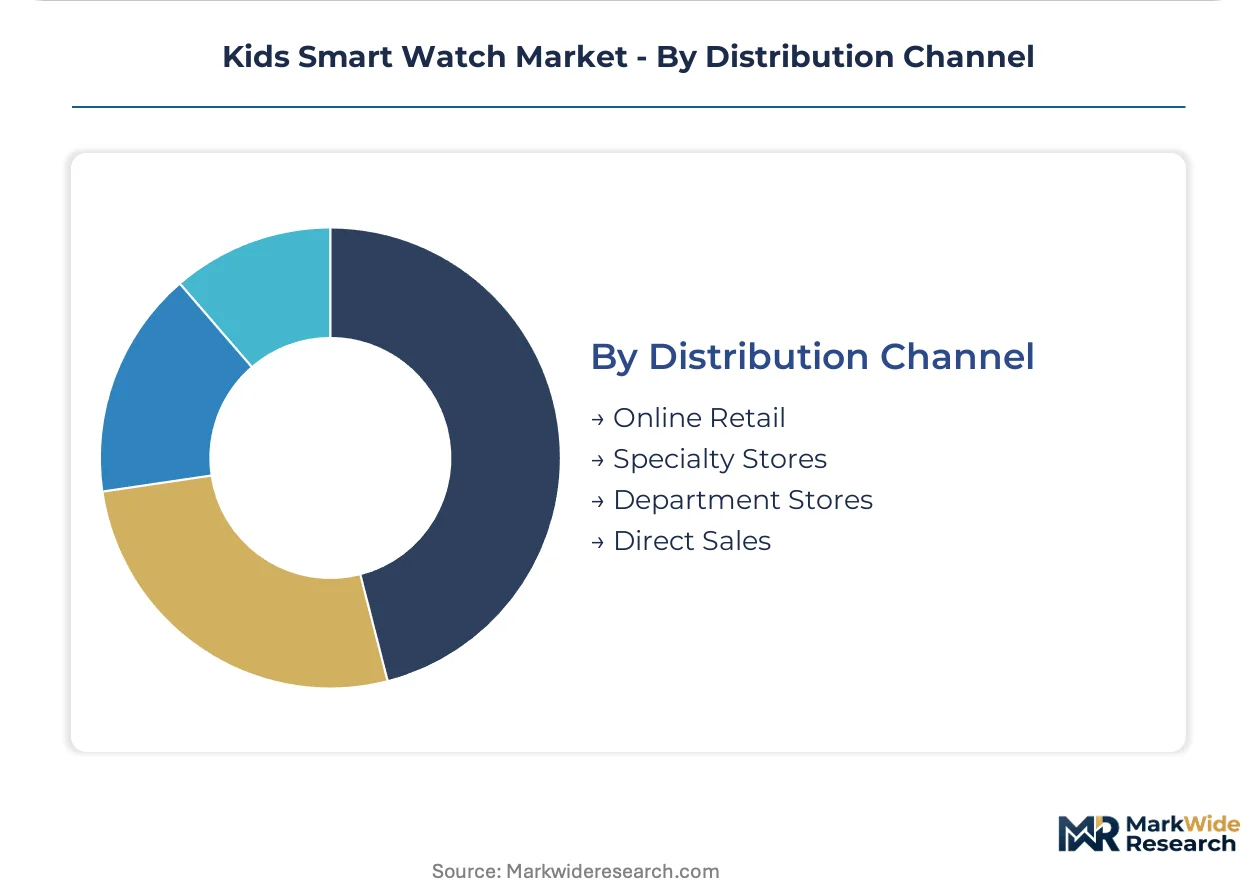
Distribution Channel:
Channel selection determines margin capture, customer education burden, and carrier partnership integration depth.
- Online Retail:Direct-to-consumer platforms enable subscription bundling and over-the-air eSIM provisioning without physical retail presence.
- Specialty Stores:Electronics retailers provide hands-on demonstration and technical support for first-time buyers.
- Department Stores:Mass merchandisers reach gift purchasers and seasonal demand spikes with limited sales assistance.
- Direct Sales:Carrier-owned channels capture service plan attachments through exclusive hardware partnerships.
Online retail commands the established base. Direct carrier sales are expanding most quickly through white-label partnership programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Chinese buyers prioritize sub-$50 cellular units with bundled educational content. German and French purchasers absorb 3-4x hardware premiums for GDPR-K compliance and data sovereignty guarantees.
China
Shenzhen manufacturing clusters compress cellular-enabled bill-of-materials costs below Western rivals' entry tiers. SAMR enforces GB standard certification for lithium-ion battery safety in devices marketed to minors, creating 8-14 week approval bottlenecks for non-domestic vendors. Domestic OEMs in Guangdong Province bundle safety features with educational content at price points inaccessible to foreign competitors.
United States
School district procurement channels in Texas and California now require COPPA-compliant parental consent architectures for connected device purchases. FCC mandates govern specific absorption rate limits and emergency communication protocols for cellular radios in wrist-worn form factors. Cupertino-based platform licensing sustains premium positioning through tight wearable OS integration with family-sharing controls.
Germany
Municipal education boards issue RFPs for district-wide fitness monitoring with centralized dashboard administration, converting biometric tracking from discretionary to institutional purchases. State data protection authorities enforce 30-day maximum geolocation retention limits under GDPR-K, forcing automated data purging workflows. Bavaria-based technology coordinators prioritize interoperability between proprietary parental-control applications and third-party emergency services platforms.
Japan
Physical education curriculum mandates from METI require biometric activity tracking in municipal schools, institutionalizing fitness monitor purchases. Kansai and Tokyo metropolitan education boards consolidate procurement away from individual parent purchases through bulk purchasing agreements. Osaka-based component sourcing supports domestic OEMs competing on manufacturing scale against Shenzhen rivals.
India
Rural connectivity gaps drive demand for offline-first GPS tracking with delayed sync protocols addressing areas lacking consistent cellular coverage. TRAI regulations shape data localization requirements for geolocation telemetry from devices marketed to minors. Maharashtra and Karnataka technology hubs host emerging domestic assembly operations targeting sub-$25 price tiers for mass-market penetration.
Kids Smart Watch Market Competitive Landscape
Platform licensors and manufacturing-scale specialists split the market along recurring-revenue versus hardware-margin fault lines. Consolidation pressure concentrates among cellular-enabled SKU producers seeking carrier partnership exclusivity. Three archetypes dominate: ecosystem-integrated technology platforms, Shenzhen-based component assemblers, and preschool-focused simplified-interface specialists. Competitive moves center on eSIM over-the-air provisioning capabilities and school district procurement channel capture.
Within the ecosystem-integrated tier, Apple Inc. and Xiaomi Corporation exemplify divergent positioning strategies. Garmin Ltd. occupies a position among precision-navigation specialists extending wearable expertise into juvenile safety applications. Huawei Technologies Co. Ltd. represents the state-affiliated technology platform archetype navigating export control complexities through domestic market concentration. VTech Holdings Limited anchors the preschool demographic with simplified interfaces that sidestep cellular subscription requirements entirely.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Xplora Technologies |
| Apple Inc. |
| Koninklijke Philips N.V. |
| LG Electronics |
| Xiaomi Corporation |
| VTech Holdings Limited |
| Fitbit Inc. |
| Huawei Technologies Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen component clustering compresses bill-of-materials costs for cellular-enabled kids smart watches while enabling domestic Chinese OEMs to undercut Western rivals on entry-tier pricing. This manufacturing concentration grants Guangdong Province suppliers asymmetric pricing power over non-domestic vendors facing GB standard certification delays.
Pricing Analysis
Cellular subscription bundling drives lifetime value more than hardware margins for tier-one OEMs. Three-tier pricing structure across premium, standard, and economy levels separates eSIM-enabled communication watches with carrier partnerships from Bluetooth-tethered fitness monitors and entry GPS trackers. Price differentiation hinges on COPPA compliance certification tier and after-sales service bundling with educational content platforms. Cost compression in the sub-$50 economy tier is intensifying because Shenzhen manufacturers integrate captive battery and GPS module production. School district procurement coordinators demonstrate lowest price sensitivity; rural Indian parents through direct-to-consumer channels exhibit highest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for cellular radio modules and lithium-ion cells. Component sourcing concentrates in China, South Korea, and Japan for GPS receivers, biometric sensors, and display assemblies. Raw material dependencies span rare earth elements for magnetometers, cobalt compounds for battery cathodes, and specialized polymers for IP67-rated enclosures. Single-source vulnerability persists for eSIM provisioning platforms controlled by limited semiconductor vendors. Distribution runs through carrier-owned retail channels for subscription-attached SKUs, while online direct-to-consumer platforms capture fitness monitor volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
School district procurement consolidation is shifting buyer power toward institutional technology coordinators and away from individual parental purchasers. Municipal education boards in Japan and Texas independent school districts now issue centralized RFPs that override fragmented retail demand.
For Market Incumbents: Insulate recurring revenue streams by deepening carrier partnership exclusivity for eSIM-enabled SKUs before white-label programs commoditize connectivity provisioning. Invest in COPPA-compliant consent workflow automation to defend school district procurement channels against emerging entrants lacking verifiable parental architecture. Prioritize backward integration into Shenzhen battery assembly to compress GB standard certification timelines that currently disadvantage non-domestic rivals.
For New Entrants and Emerging Players: Build out offline-first GPS tracking capabilities for rural India connectivity gaps where delayed sync protocols address inconsistent cellular coverage. Target childcare center deployments with shared charging infrastructure and durable enclosure specifications that sidestep complex cellular subscription requirements. Pursue direct-to-consumer online retail with fitness monitor SKUs positioned below institutional procurement minimum order thresholds.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component assemblers with captive eSIM provisioning capabilities and established SAMR certification pathways. Long-term viability across the projection horizon rests on carrier partnership exclusivity rather than hardware margin capture. Acquisition target archetype: Shenzhen-based OEMs with integrated battery manufacturing and educational content licensing. Signal to watch: district-wide RFP issuance velocity from municipal education boards converting fitness monitors from discretionary to institutional purchases.
| Strategic Initiative | Industry Significance |
|---|---|
| eSIM Over-the-Air Provisioning | Enables carrier partnership exclusivity without physical retail distribution infrastructure. |
| COPPA Compliance Certification | Unlocks Texas and California school district procurement channels previously closed to connected devices. |
| Shenzhen Battery Assembly Integration | Compresses SAMR GB standard approval timelines that currently block non-domestic market entry. |
| District-Wide Fitness Monitor RFP Capture | Converts biometric tracking from discretionary parent purchases to institutional required procurement. |
| Educational Content Platform Licensing | Differentiates hardware offerings through bundled safety-education integration at sub-$50 price tiers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hardware engineering directors, carrier partnership managers, school district technology coordinators, and parental control software developers; and secondary validation through FCC equipment authorization databases, SAMR GB standard filings, GDPR-K enforcement actions from CNIL and German state authorities, and carrier eSIM deployment disclosures. Bottom-up triangulation across component bill-of-materials estimates and top-down reconciliation against disclosed OEM shipment volumes anchored value projections.
Forecast inputs span cellular subscription attachment rates, school district procurement conversion timelines, and eSIM migration curves across premium and mid-market SKUs. Segmentation dimensions modeled include connectivity technology tier, application focus, end-user type, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for institutional procurement inflections. Industry-specific forecast inputs incorporate SAR certification timeline distributions and GDPR-K data retention compliance cost burdens.
Stress conditions across lithium-ion cell supply disruptions, carrier partnership exclusivity durations, and COPPA enforcement intensity variations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding eSIM technology migration pace and school district procurement centralization trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Wearable Computing Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Smart Bra Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Global Smart Watch Market