
 Europe Smart Watches Market | 2026-2036
Europe Smart Watches Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Watches Market Foresight
Multi-source component procurement is hardening across European smartwatch supply chains as brands reduce dependence on single Asian foundries. Apple Inc sustains in-house silicon design for its wearable ecosystem, locking performance differentiation at the chip level. Samsung Electronics Co Ltd leverages vertical manufacturing from display to battery, compressing lead times for European retail replenishment. Garmin Ltd anchors its position through specialized GPS and multi-sport firmware tuned to outdoor enthusiasts across the Alps and Nordic regions.
Europe smart watches are wrist-worn computing devices integrating biometric sensors, wireless connectivity modules, and rechargeable power systems within sealed enclosures rated for water and dust ingress. These devices primarily serve continuous health telemetry, notification relay, and activity quantification for consumer and clinical adjacency markets. Fitness trackers lead volume shipments across the continent, though luxury smartwatches command disproportionate margin pools through Swiss heritage branding and precious material integration. Cellular-enabled devices represent the fastest-expanding technology segment as eSIM standardization eliminates paired-phone dependency for outdoor athletes and elderly safety monitoring.
CE marking under the EU Medical Device Regulation governs health-claim substantiation for SpO2, ECG, and blood pressure features, while GDPR constrains biometric data processing architectures. ECHA REACH compliance adds material traceability burdens for lithium-polymer batteries and rare-earth magnet assemblies sourced into European assembly plants. Stakeholders must monitor impending CSRD disclosure requirements that will mandate supply-chain emissions reporting from component vendors through final distribution.
Market Dynamics
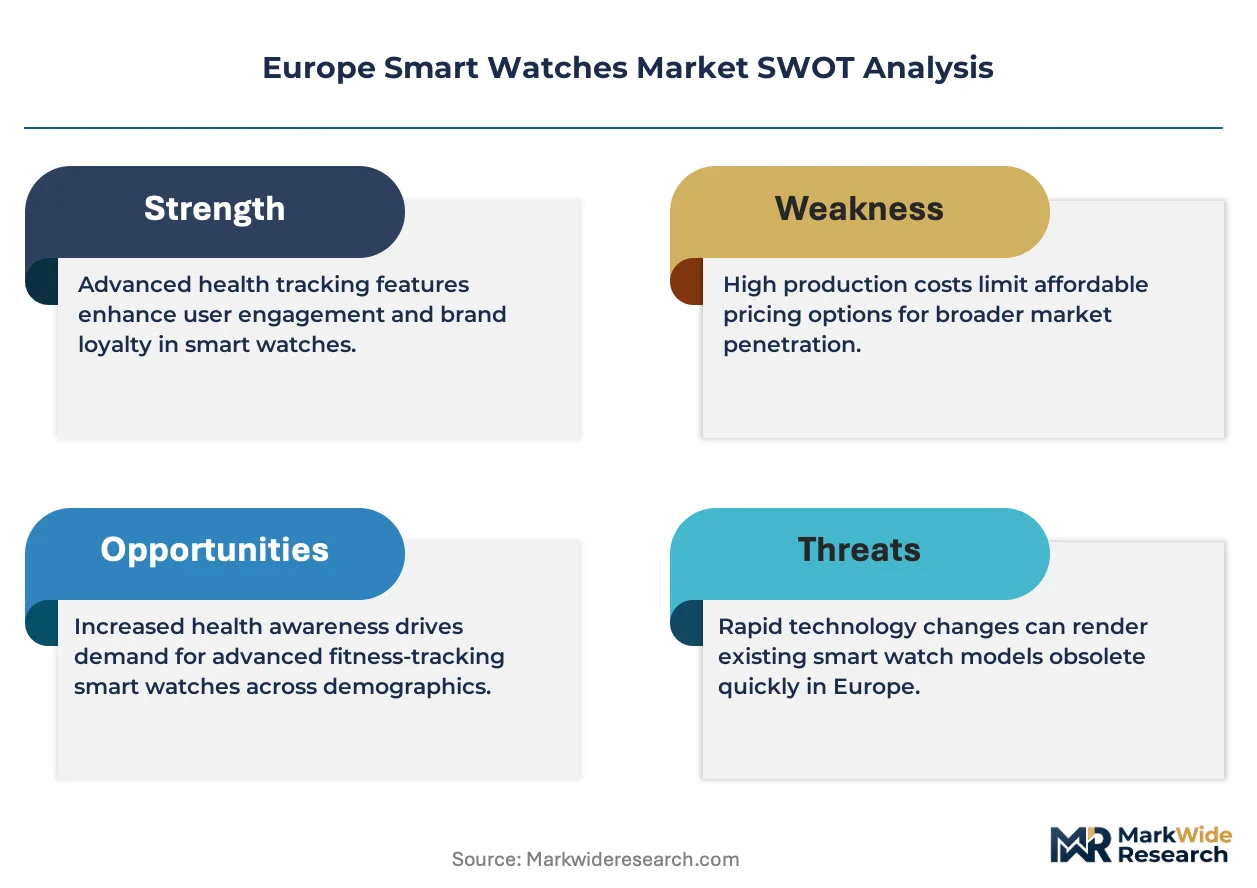
Cellular-enabled smartwatches are unifying health telemetry with independent connectivity, eliminating smartphone tethering for outdoor athletes and elderly safety monitoring across European metropolitan corridors.
Growth Catalysts
- EU Medical Device Regulation:CE marking pathways for SpO2 and ECG features legitimize clinical-grade health claims, accelerating hospital-adjacent procurement in Germany and France.
- Employer wellness mandates:Corporate programs in United Kingdom metropolitan clusters subsidize connected health devices, embedding smartwatches into occupational health infrastructure.
- eSIM standardization:Embedded subscriber identity modules eliminate paired-phone dependency, expanding addressable demand among Alpine outdoor enthusiasts and Nordic elderly populations.
Market Restraints
- Lithium-polymer supply concentration:Battery cell sourcing clusters in East Asian foundries expose European assemblers to geopolitical friction and freight cost volatility.
- GDPR biometric processing constraints:Continuous heart-rate and blood-pressure data flows require localized storage architectures, inflating cloud infrastructure expenditure.
- Swiss heritage substitution:Mechanical timepieces retain status-signaling preference among luxury buyers in Geneva and Zurich corridors, capping smartwatch penetration at the premium tier.
Strategic Opportunities
- CSRD disclosure preparation:Impending supply-chain emissions reporting mandates create first-mover advantage for vendors with traceable rare-earth magnet assemblies.
- French aging demographics:Underpenetrated rural districts outside Paris and Lyon offer expansion headroom for cellular-enabled elderly safety monitoring.
- Pharmacy channel integration:German and Italian retail pharmacy networks are piloting prescription-adjacent smartwatch dispensing, converging consumer electronics with reimbursed health devices.
Industry Challenges
- ECHA REACH material traceability:Compliance documentation for lithium-polymer and magnet assemblies consumes procurement bandwidth and extends supplier onboarding timelines.
- Firmware specialization talent scarcity:Multi-sport algorithm development for Alpine GPS applications competes for embedded systems engineers against automotive and aerospace sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Watches Market |
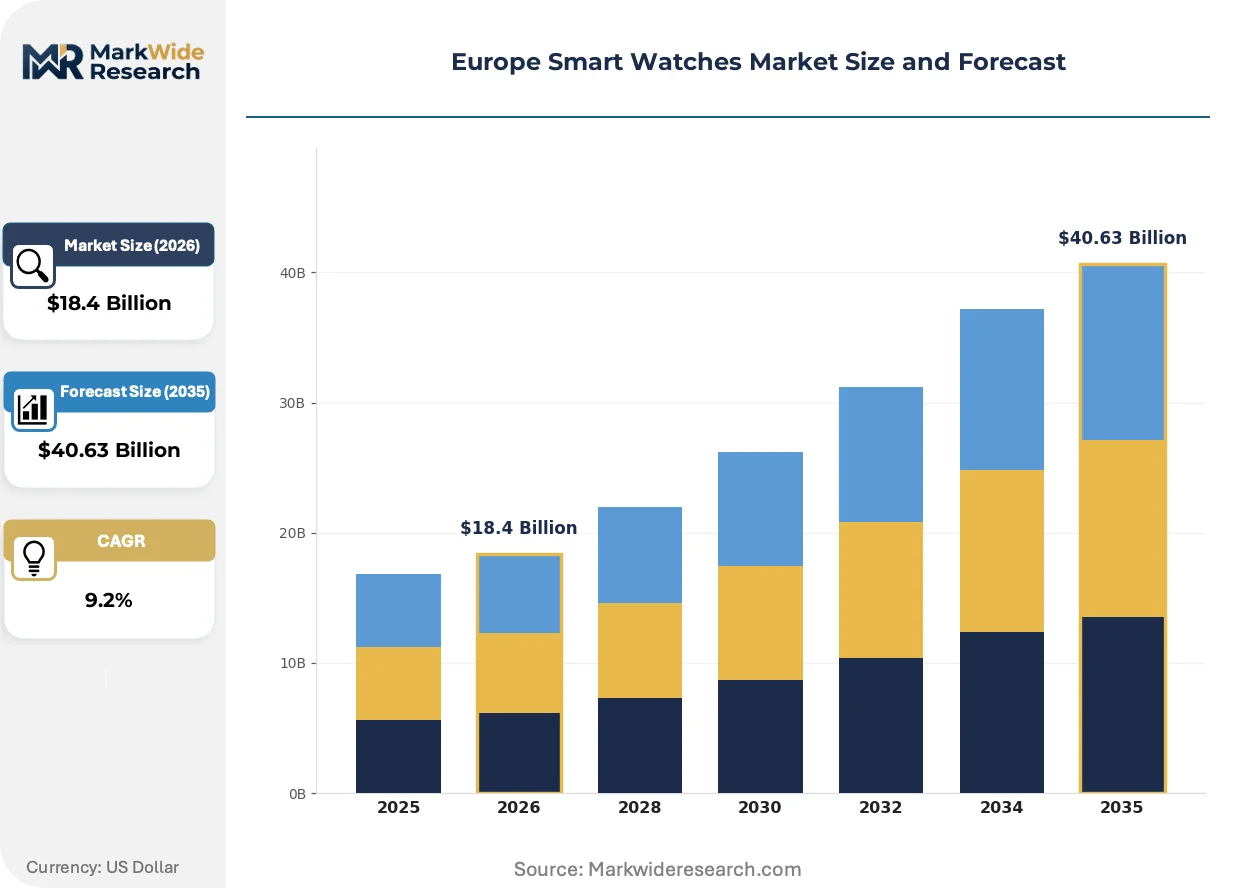
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $40.63 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Hybrid Smartwatches, Luxury Smartwatches, Standard Smartwatches Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Fitness Enthusiasts, Tech-Savvy Users, Professionals, Elderly Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Fitbit Inc, TAG Heuer SA, Apple Inc, Polar Electro OY, Fossil Group Inc, Samsung Electronics Co Ltd, Huawei Technologies Co Ltd, Google LLC, Garmin Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Watches Market Shifts & Advancements
Sensor fusion architectures and regulatory recalibration are compressing development cycles while cellular independence redefines usage contexts across European consumer and clinical adjacency markets.
Photoplethysmography arrays are unifying optical heart-rate, SpO2, and blood-pressure estimation within single sensor modules. Fitness enthusiasts across Germany's Ruhr corridor and France's Île-de-France region are adopting these consolidated biometric stacks at accelerating replacement cycles. This convergence is compressing component count and assembly cost structures while elevating performance differentiation thresholds for mid-tier vendors.
CE marking under the EU Medical Device Regulation is hardening substantiation requirements for health-claim marketing. SpO2 and ECG feature deployments now require notified body intervention and clinical validation dossiers, extending time-to-market by twelve to eighteen months for new entrants. German and United Kingdom distributors are prioritizing pre-certified device portfolios, concentrating shelf access around established compliance infrastructures.
Cellular-enabled procurement is displacing Bluetooth-tethered purchasing patterns among Alpine rescue services and Nordic municipal elderly care programs. French and Italian outdoor retailers are reallocating floor space toward standalone LTE models, while paired-phone dependent inventory accumulates in secondary channels. This rotation is most visible in Bavarian and Tyrolean mountain sports clusters where emergency connectivity commands premium positioning.
Europe Smart Watches Market Segmentation
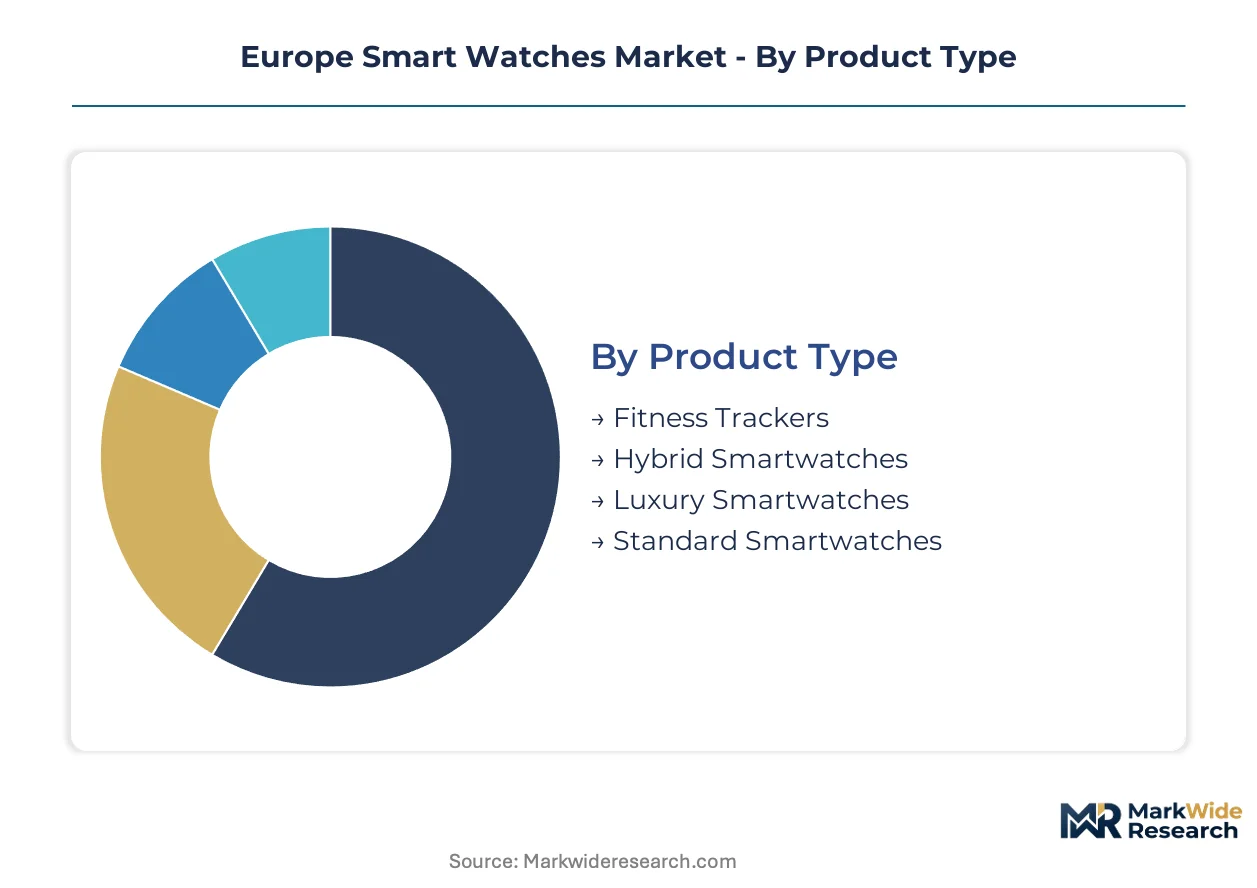
Segmentation in the Europe Smart Watches Market reveals divergent margin architectures across hardware tiers and connectivity modalities. Vendors calibrate sensor density, material selection, and cellular integration to match discrete buyer willingness-to-pay across German fitness clusters, French elderly care networks, and UK corporate wellness programs.
Product Type:
Standardization dominates the low end with commoditized fitness bands, while customization intensity escalates through Swiss-heritage luxury assemblies requiring precious metal sourcing and bespoke firmware tuning.
- Fitness Trackers:Stripped-down biometric sensors and polymer enclosures deliver continuous heart-rate and step-count telemetry at minimal bill-of-materials cost. Ruhr corridor gym chains and Île-de-France corporate wellness programs procure these in volume for employee health monitoring subsidies.
- Standard Smartwatches:Full-color OLED displays, GPS modules, and notification relay architectures serve the mass-market connectivity segment. German metropolitan electronics retailers move the highest inventory velocity here, though replacement cycles compress as photoplethysmography arrays migrate downstream.
- Hybrid Smartwatches:Mechanical watch hands overlay digital notification sub-displays, preserving analog aesthetics for status-conscious buyers. Swiss assembly plants in Neuchâtel and Solothurn specialize in these bridge products.
- Luxury Smartwatches:Titanium casings, sapphire crystals, and concierge service integrations command Geneva and Zurich corridor premiums. CE marking under EU MDR adds clinical-validation overhead that filters smaller entrants from this tier.
Most installed capacity flows through Standard Smartwatches. Expansion is steepest in Luxury Smartwatches.
Technology:
Cost tier stratification separates tethered connectivity from standalone cellular architectures, with premium positioning attaching to emergency-ready independence.
- Bluetooth:Tethered radio protocols drain minimal power from compact lithium-polymer cells. French and Italian secondary channels accumulate excess inventory as eSIM standardization accelerates cellular substitution.
- Cellular:Embedded LTE modems with eSIM provisioning eliminate smartphone dependency for Alpine rescue services and Nordic municipal elderly safety programs. Bavarian mountain sports retailers command floor-space premiums for these standalone models.
- Wi-Fi:Higher-throughput connectivity enables music streaming and software updates without phone proximity. Home-bound users in UK suburban clusters favor this intermediate specification.
- NFC:Near-field payment authentication and transit pass integration concentrate demand in London and Stockholm contactless-transit corridors.
Bluetooth retains the largest installed base. Cellular is climbing the fastest.
End User:
Application intensity varies from casual notification consumers to clinical-grade telemetry dependents, with firmware specialization scaling accordingly.
- Fitness Enthusiasts:Multi-sport algorithm demands for Alpine GPS tracking and Nordic ski metrics drive Garmin and Polar firmware development. These users replace devices at accelerated cycles as sensor fusion improves.
- Elderly:Fall detection, geofencing alerts, and medication reminders concentrate procurement through French rural pharmacy pilots and German municipal care programs. Cellular independence matters most in this cohort.
- Professionals:Calendar integration, email triage, and discreet notification filtering dominate London and Frankfurt financial district purchasing patterns.
- Tech-Savvy Users:Early-adopter appetite for beta health features and third-party app ecosystems sustains developer community engagement across Berlin and Amsterdam startup clusters.
Fitness Enthusiasts anchor current volume. Elderly applications show the steepest expansion trajectory.
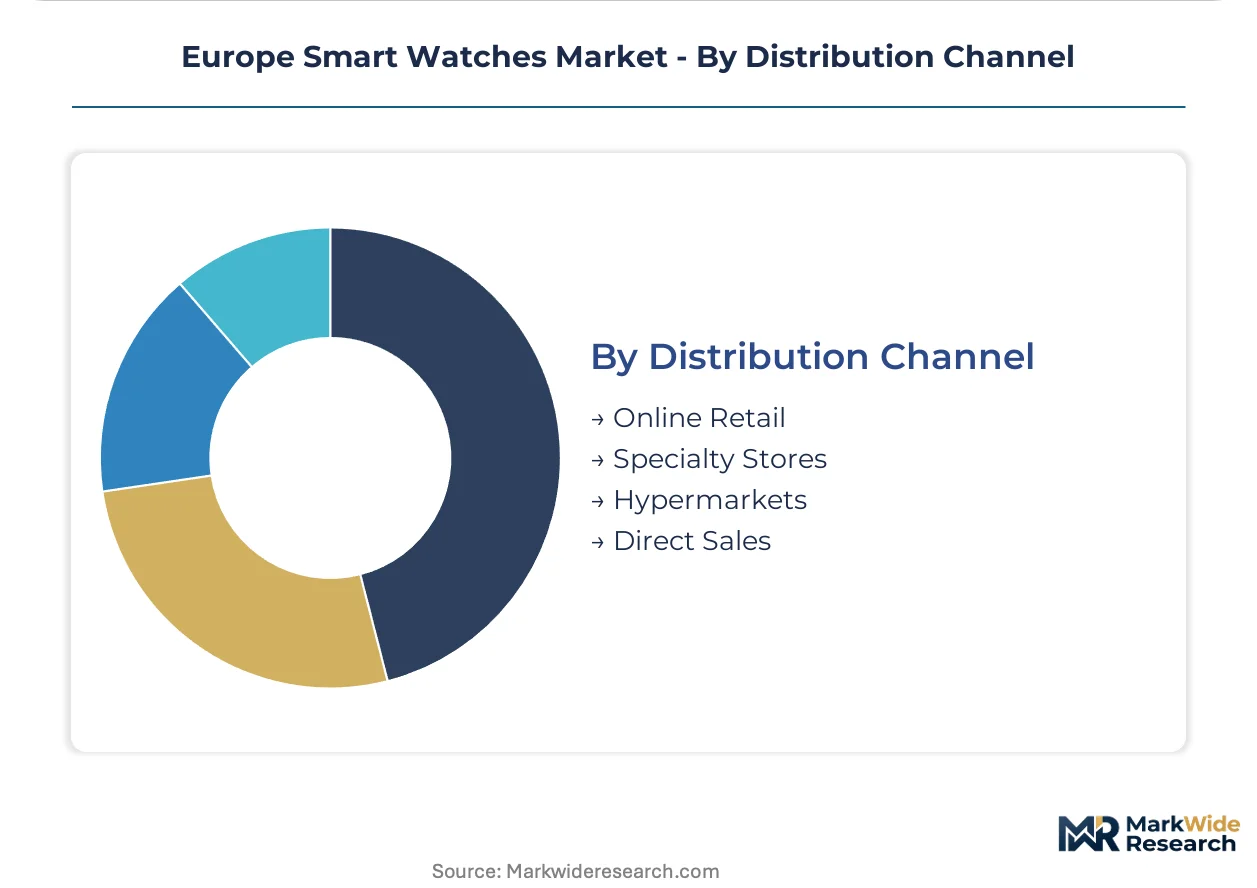
Distribution Channel:
Margin capture concentrates in direct-to-consumer and specialty retail, while hypermarkets sacrifice service attachment for turnover velocity.
- Online Retail:Amazon.de and native brand storefronts aggregate comparison shoppers across German-speaking markets. Return logistics infrastructure filters out sizing-sensitive luxury purchases.
- Specialty Stores:Curated Alpine outdoor retailers in Tyrol and Bavaria provide GPS firmware guidance and emergency-connectivity demonstrations. Staff expertise justifies premium pricing.
- Hypermarkets:Carrefour and MediaMarktSaturn outlets in France and Germany move fitness tracker volume at compressed margins. Impulse placement near checkout drives unplanned purchases.
- Direct Sales:Apple and Samsung flagship experiences in London, Paris, and Milan control brand presentation and trade-in program execution. Service attachment rates peak here.
Online Retail processes the largest transaction volume. Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr corridor and Bavarian clusters anchor European smartwatch procurement through employer wellness mandates and Alpine outdoor retail networks. Metropolitan electronics distribution concentrates in Frankfurt and Munich, while regulatory compliance infrastructure under EU MDR shapes cross-border certification pathways.
Germany
Employer wellness subsidies and aging demographics in North Rhine-Westphalia drive enterprise procurement of cellular-enabled safety devices. CE marking under EU MDR governs SpO2 and ECG feature deployments, extending validation timelines for new entrants. Munich specialty retailers command premium positioning for GPS-equipped outdoor models targeting Alpine rescue services.
United Kingdom
London financial district professionals prioritize calendar integration and discreet notification filtering in wearable procurement. GDPR biometric processing constraints force localized data storage architectures, inflating cloud infrastructure costs for vendors. Midlands distribution hubs process bulk fitness tracker shipments for corporate wellness programs.
France
Underpenetrated rural districts outside Paris and Lyon present expansion headroom for elderly safety monitoring with cellular independence. ANSM clinical validation requirements add regulatory overhead for blood pressure estimation features. Île-de-France pharmacy networks pilot prescription-adjacent smartwatch dispensing, converging consumer electronics with reimbursed health devices.
Italy
Lombardy and Veneto retail pharmacy chains integrate connected health devices into chronic disease management programs. ECHA REACH compliance documentation consumes procurement bandwidth for lithium-polymer battery sourcing. Milan flagship experiences control brand presentation and trade-in program execution for premium-tier vendors.
Switzerland
Geneva and Zurich corridors sustain mechanical timepiece preference among luxury buyers, capping smartwatch penetration at the premium tier. Swissmedic medical device oversight applies to clinical-grade health claims in Neuchâtel assembly operations. Solothurn hybrid manufacturing preserves analog aesthetics through mechanical watch hand overlays on digital sub-displays.
Europe Smart Watches Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized firmware and cellular independence vectors. Market structure consolidates around three capability clusters: in-house silicon design, vertical manufacturing integration, and GPS-specialized outdoor positioning. Strategic archetypes include ecosystem-locked premium vendors, component-integrated Asian conglomerates, and Alpine-focused outdoor specialists. Dominant competitive moves center on supply-chain diversification away from single Asian foundries and pre-certification portfolios that accelerate EU MDR market access.
Within the ecosystem-locked tier, Apple Inc and Samsung Electronics Co Ltd exemplify divergent integration strategies. Cupertino-based design houses anchor performance differentiation through captive silicon architectures, while Seoul-anchored conglomerates compress European replenishment lead times through display-to-battery manufacturing control. Garmin Ltd occupies a position among GPS-specialized outdoor specialists, with firmware tuned to Alpine and Nordic multi-sport applications representing a defensible niche against generalized competitors.
| Leading Market Players |
|---|
| Fitbit Inc |
| TAG Heuer SA |
| Apple Inc |
| Polar Electro OY |
| Fossil Group Inc |
| Samsung Electronics Co Ltd |
| Huawei Technologies Co Ltd |
| Google LLC |
| Garmin Ltd |
| Others |
Supply & Pricing Matrix
Lithium-polymer cell costs cascade through three-tier pricing structures across premium, standard, and economy levels, with German metropolitan buyers absorbing battery freight volatility more readily than French pharmacy channel purchasers. ECHA REACH compliance documentation inflates landed costs for rare-earth magnet assemblies before Swiss-heritage branding premiums attach at Geneva and Zurich retail endpoints.
Pricing Analysis
Input-cost pass-through from East Asian battery foundries compresses margins at the standard tier while CE marking under EU MDR elevates certification-grade premiums for SpO2 and ECG features. Price differentiation hinges on clinical validation dossiers and cellular independence specifications, with fitness enthusiasts in the Ruhr corridor showing least price sensitivity for GPS-equipped outdoor models. Cost compression in Bluetooth-tethered inventory intensifies as eSIM standardization accelerates cellular substitution, forcing paired-phone dependent SKUs into secondary channels at eroded price points.
Supply Chain Analysis
Photoplethysmography sensor modules rest on Taiwanese optical component specialists and South Korean display foundries, with final assembly concentrating in Chinese coastal plants serving European distributors. Rare-earth magnet assemblies for haptic feedback and lithium-polymer cells draw from concentrated East Asian supply bases, exposing vendors to geopolitical friction and freight cost volatility. Single-source vulnerability in cellular modem silicon constrains eSIM-enabled production ramps. Distribution runs through Frankfurt and Munich electronics hubs before pharmacy channel pilots in Germany and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by employer wellness mandates in United Kingdom metropolitan clusters shifting procurement toward clinical-grade specifications with attached service premiums.
For Market Incumbents: To counter firmware specialization talent scarcity, anchor defensive positioning through captive GPS algorithm development for Alpine applications and backward integration into photoplethysmography sensor module sourcing. Pre-certification portfolios under EU MDR accelerate shelf access against emerging entrants facing eighteen-month validation timelines. For New Entrants and Emerging Players: Capture underpenetrated French rural districts outside Paris and Lyon through cellular-enabled elderly safety monitoring with pharmacy channel integration. Target German municipal care programs with standalone LTE models eliminating smartphone dependency, leveraging ANSM clinical validation partnerships as go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for GPS-specialized outdoor firmware developers because Alpine and Nordic multi-sport algorithm talent competes against automotive and aerospace sectors for embedded systems engineers. Long-term viability favors vendors with traceable rare-earth magnet assemblies ahead of CSRD disclosure mandates. Watch eSIM standardization penetration rates as inflection indicator for cellular substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR pre-certification accelerates German and French distributor shelf access against validation-delayed competitors. |
| Cellular Modem Supply Agreement | eSIM-enabled silicon procurement secures standalone LTE production capacity for Alpine rescue service contracts. |
| Pharmacy Channel Partnership | Italian and German retail pharmacy pilots converge consumer electronics with reimbursed health device dispensing. |
| Rare-Earth Magnet Traceability Program | ECHA REACH documentation infrastructure creates first-mover advantage ahead of CSRD supply-chain emissions mandates. |
| GPS Firmware Specialist Acquisition | Multi-sport algorithm talent pools in Neuchâtel and Solothurn defend Alpine positioning against generalized competitors. |
Research Methodology
Coverage spans Western Europe and Nordic corridors, with primary inputs from each combining interviews with connected health device procurement managers, retail pharmacy category buyers, Alpine outdoor retail specialists, and EU regulatory affairs consultants. Secondary validation draws from ECHA REACH filings, CE marking notification body records, German employer wellness program disclosures, and French ANSM clinical validation databases. Bottom-up shipment estimates triangulate against top-down expenditure models across the analysis window.
Rate-of-change decomposition separates volume expansion from value migration across product type, connectivity technology, end-user application, and distribution channel dimensions. CAGRs derive from segmented adoption curve modeling incorporating cellular independence demand, employer wellness subsidy trajectories, and EU MDR compliance timeline impacts. Forecast inputs include eSIM carrier provisioning rates and photoplethysmography sensor fusion adoption patterns.
Geopolitical friction in East Asian battery sourcing, regulatory recalibration under impending CSRD disclosure mandates, and Swiss heritage substitution resistance are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on subsidy continuity and certification pathway stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Women's Watch Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Smart Band Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Smart Bra Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Consumer Grade Smart Wearable Device Market