
 Android Smartwatch Market | 2026-2036
Android Smartwatch Market Size, Share, and Industry Trends Forecast 2026-2036
Android Smartwatch Market Insights
The R&D-to-manufacturing capability gap between vertically integrated electronics conglomerates and design-focused wearables specialists is unwinding competitive stability in the Android smartwatch space. Samsung Electronics Co., Ltd leverages in-house semiconductor and display production to control component costs across Galaxy Watch lineups. Xiaomi Corp. anchors its position through aggressive pricing in emerging markets while extending Mi Band ecosystem loyalty upward into smartwatch tiers. Huawei Technologies Co., Ltd navigates geopolitical constraints by deepening its proprietary HarmonyOS integration with wearable sensors.
An Android smartwatch constitutes a wrist-worn computing device running Google's Wear OS or compatible open-source Android derivatives, integrating ARM-based processors, AMOLED or LCD touch displays, and multi-sensor arrays for biometrics, motion, and environmental data capture. These devices serve continuous health telemetry, notification relay, contactless payment, and voice-activated digital assistance in consumer and clinical-adjacent contexts. Fitness Monitoring functionality captures the largest addressable user base among product type segments, while Payment-enabled models concentrate margin pools through NFC transaction fee structures and banking partnerships. Wearable Sensors technology leads hardware differentiation as photoplethysmography and accelerometer fusion enable sleep apnea detection and fall alerting without companion devices.
FDA 510(k) clearance requirements for blood oxygen and electrocardiogram features shape product development timelines and clinical marketing claims in the United States. China's NMPA regulates medical-grade health monitoring classifications through GB standard compliance, while the EU MDR and GDPR constrain biometric data processing and cross-border cloud storage architectures in European markets. Stakeholders must monitor whether regulatory divergence between medical device and consumer electronics frameworks forces platform fragmentation or drives consolidation around compliant reference designs.
Market Dynamics
Google's Wear OS platform consolidation and Samsung's proprietary silicon integration are compressing margins for design-only wearables specialists while elevating hardware-software coherence as the decisive competitive variable.
Growth Catalysts
- FDA 510(k) Pathway Expansion:Accelerated clearance timelines for photoplethysmography-based arrhythmia detection are enabling clinical-grade marketing claims in the United States.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are attracting component assembly investments from global brand licensees.
- Accelerometer-Gyroscope Fusion:Advanced motion-sensor algorithms for fall detection are expanding reimbursable use cases in senior care facilities.
Market Restraints
- AMOLED Display Supply Concentration:Korean and Chinese panel manufacturers control over ninety percent of wearable-grade flexible display output, creating input cost volatility.
- EU MDR Compliance Burden:Extended clinical evaluation requirements for blood oxygen monitoring features are delaying European launches by twelve to eighteen months.
- Smartphone-Tethered Dependency:Persistent requirement for companion device pairing limits addressable market among non-smartphone users.
Strategic Opportunities
- Indonesia and Vietnam Penetration:Sub-$100 price points and local distributor partnerships are unlocking first-time wearable adoption in Southeast Asian urban centers.
- Enterprise Wellness Programs:B2B bulk procurement for workforce health monitoring is bypassing retail channel constraints and generating recurring platform revenue.
- ISO 13485 Certification:Medical device quality management alignment is creating differentiation for vendors targeting hospital-adjacent remote patient monitoring contracts.
Industry Challenges
- Biomedical Algorithm Validation:Recruiting sufficient clinical data scientists to train FDA-submittable health monitoring models exceeds current talent pipeline capacity.
- Multi-Regulatory Parallel Certification:Simultaneous pursuit of FDA 510(k), NMPA Class II, and EU MDR approvals fragments engineering resources and extends development cycles.
- Legacy Fitness Tracker Displacement:Mi Band and similar low-cost band users resist upgrade conversion due to battery life and price anchoring effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android Smartwatch Market |
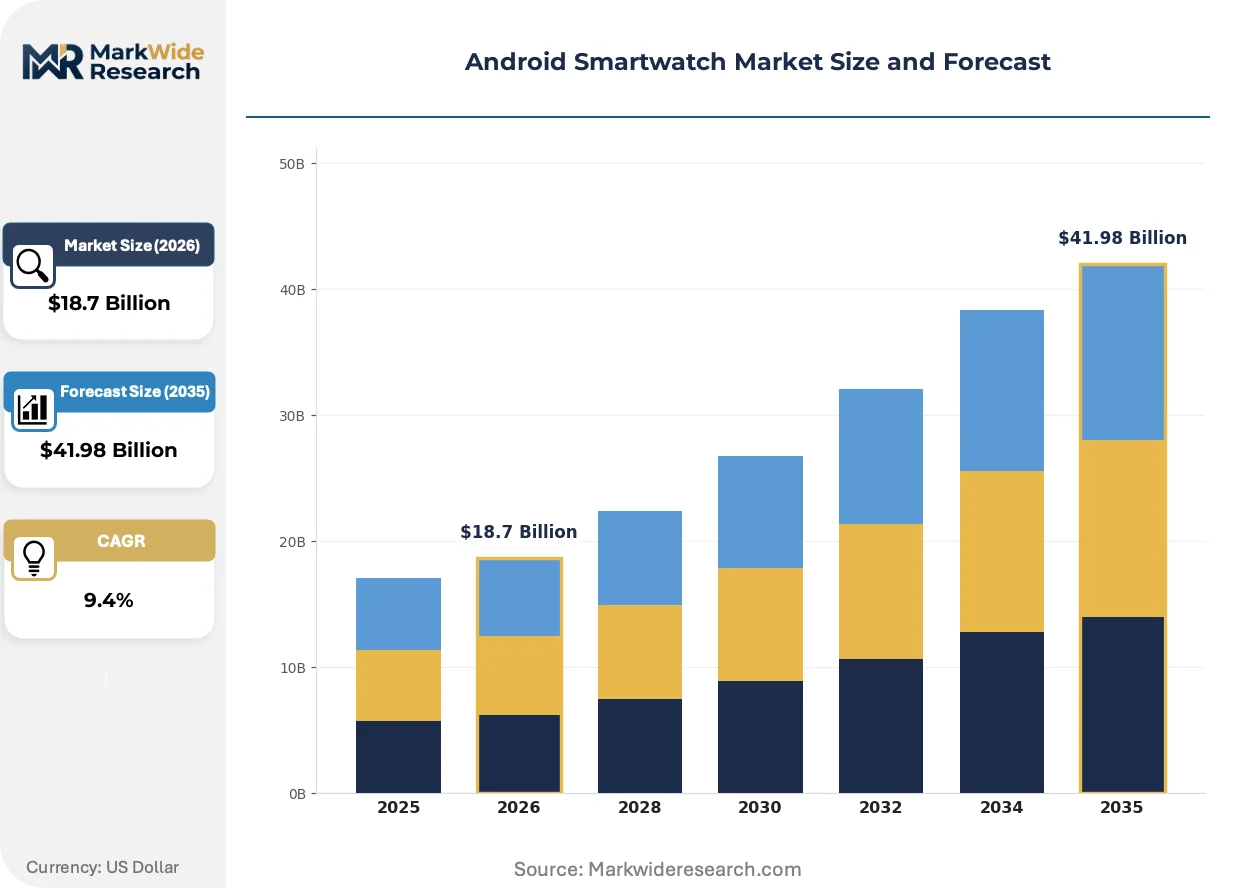
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Tracking, Fitness Monitoring, Messaging, Payment Technology: Wearable Sensors, Bluetooth, Wi-Fi, NFC End User: Fitness Enthusiasts, Tech Savvy Consumers, Professionals, Casual Users Distribution Channel: Online Retail, Electronics Stores, Supermarkets, Specialty Stores |
| Companies Covered | Samsung Electronics Co., Ltd, Google, Garmin Ltd, Fitbit, OnePlus, Huawei Technologies Co., Ltd, Xiaomi Corp., Mobvoi Inc., Fossil Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android Smartwatch Market Trends and Innovations
Sensor fusion architectures and platform consolidation are redefining hardware differentiation while regulatory clarity around clinical claims is separating reimbursable medical-grade devices from consumer wellness accessories.
Photoplethysmography sensor arrays are achieving continuous blood pressure estimation without cuff inflation. Samsung and Huawei are integrating multi-LED configurations into flagship Galaxy Watch and Watch GT lineups. This capability is miniaturizing the gap between consumer wearables and ambulatory blood pressure monitors, compressing addressable market boundaries for dedicated medical device manufacturers.
China's NMPA issued technical review guidelines for wearable electrocardiogram devices in 2023, establishing clinical trial benchmarks previously absent from the regulatory framework. Domestic manufacturers now face substantiation requirements comparable to FDA 510(k) pathways. Huawei and Xiaomi are responding by funding multi-center validation studies at Beijing Anzhen Hospital and Fuwai Hospital to secure Class II medical device registrations.
Employer-sponsored wellness programs are displacing individual retail purchase as the primary volume channel for mid-tier Android smartwatches. Human resources departments at technology and financial services firms in the United States are negotiating three-year platform subscriptions bundled with device deployment. This procurement concentration is visible most acutely in California and New York metropolitan corridors where self-insured employers seek claims reduction through preventive monitoring incentives.
Android Smartwatch Market Segmentation
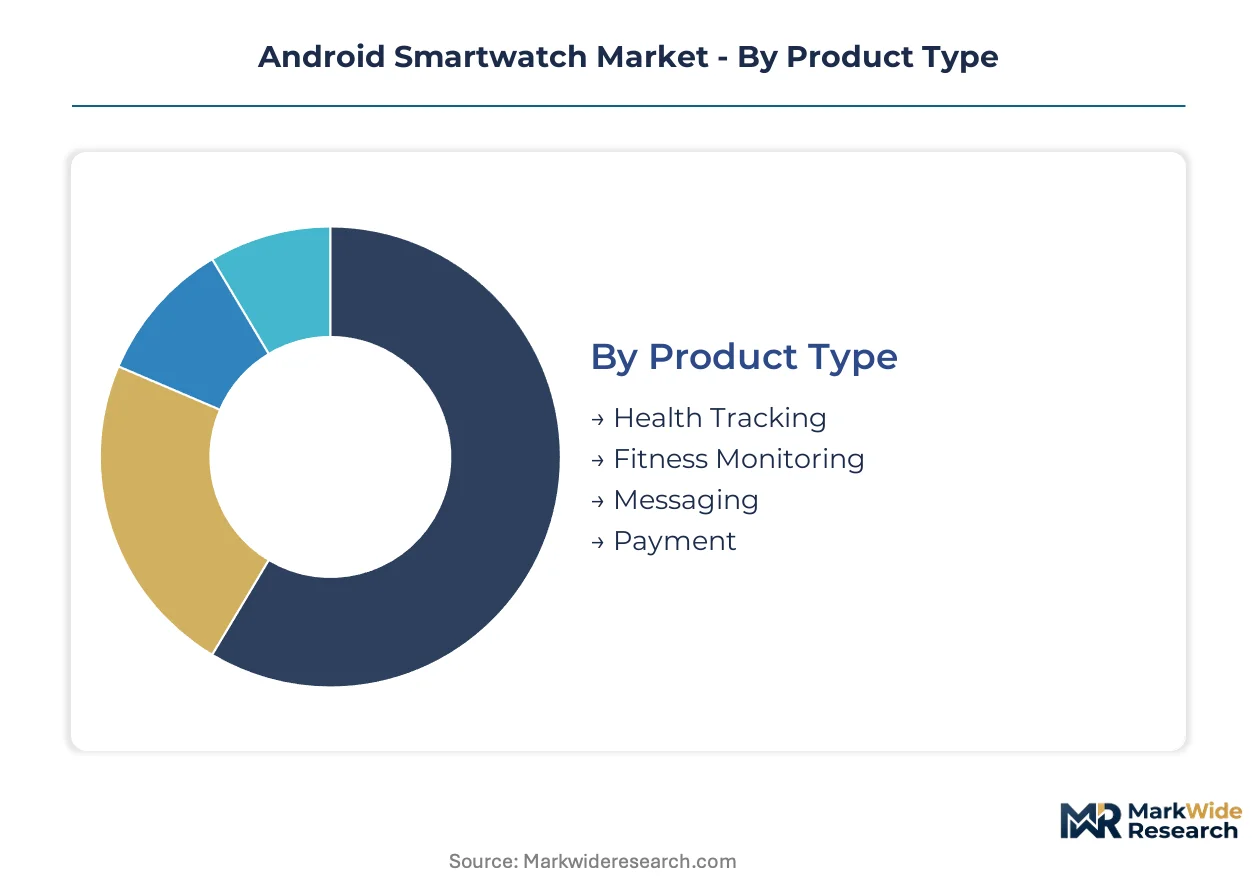
Segmentation in the Android smartwatch market reveals how hardware specifications, connectivity protocols, and buyer profiles determine pricing power and channel strategy. Understanding these divides helps vendors allocate R&D resources and distribution investments.
Product Type:
Domestic demand in India and China concentrates on affordable health tracking variants, while export-led premium volumes flow from South Korean and Taiwanese assembly hubs toward North American and European markets.
- Fitness Monitoring:Continuous heart rate, SpO2, and accelerometer fusion for workout analytics dominate consumer purchasing decisions. Demand clusters among gym members and amateur athletes in the United States and Germany where employer wellness subsidies offset retail prices.
- Health Tracking:Medical-grade ECG and blood pressure estimation features require FDA or NMPA clearance, constraining availability to flagship tiers. Clinical validation investments by Samsung and Huawei target hospital-adjacent remote monitoring contracts in California and Beijing.
- Messaging:Voice-to-text and quick-reply interfaces serve notification-heavy professionals who prioritize glanceable communication over fitness metrics.
- Payment:NFC-enabled contactless transaction capability concentrates margin extraction through banking partnership fees and tokenization service revenues.
Fitness Monitoring holds the largest share; momentum sits with Health Tracking as regulatory pathways mature.
Technology:
Component cost tiers separate flagship sensor arrays from basic connectivity modules, with photoplethysmography and multi-band GNSS commanding premium bill-of-materials positions.
- Wearable Sensors:Photoplethysmography, accelerometer, gyroscope, and temperature sensor fusion enables sleep apnea detection and fall alerting without companion devices. Samsung's BioActive Sensor integrates three wavelengths for improved melanin-compensated readings across diverse skin tones.
- Bluetooth:Low-energy 5.3 protocols sustain week-long battery life in mid-tier devices, making this the default tethering standard for smartphone-dependent architectures.
- Wi-Fi:Standalone connectivity for music streaming and emergency calling when smartphones are absent, adding $8-12 to manufacturing costs.
- NFC:Secure element integration for transit and payment credential storage, requiring additional hardware certification by payment networks.
Wearable Sensors absorb the highest R&D allocation; NFC deployment is climbing fastest as transit authority partnerships proliferate.
End User:
Volume concentration among fitness enthusiasts and tech-savvy consumers creates a dual-peak demand structure that casual users and professionals fill at lower price points.
- Fitness Enthusiasts:Training load balance, recovery metrics, and VO2 max estimation drive replacement cycles every 18-24 months. Garmin and Polar migration toward Wear OS is capturing this segment from proprietary platforms.
- Tech Savvy Consumers:Early adopters prioritize API access, third-party watch face ecosystems, and smart home integration, sustaining Google's developer investment in Wear OS.
- Professionals:Calendar notifications, silent alarms, and discreet communication tools dominate purchasing criteria over health metrics.
- Casual Users:Basic step counting and sleep duration tracking at sub-$75 price points, with Mi Band ecosystem loyalty resisting upgrade conversion.
Fitness Enthusiasts generate the highest per-unit margins; Tech Savvy Consumers show the steepest expansion trajectory as smart home integration deepens.
Distribution Channel:
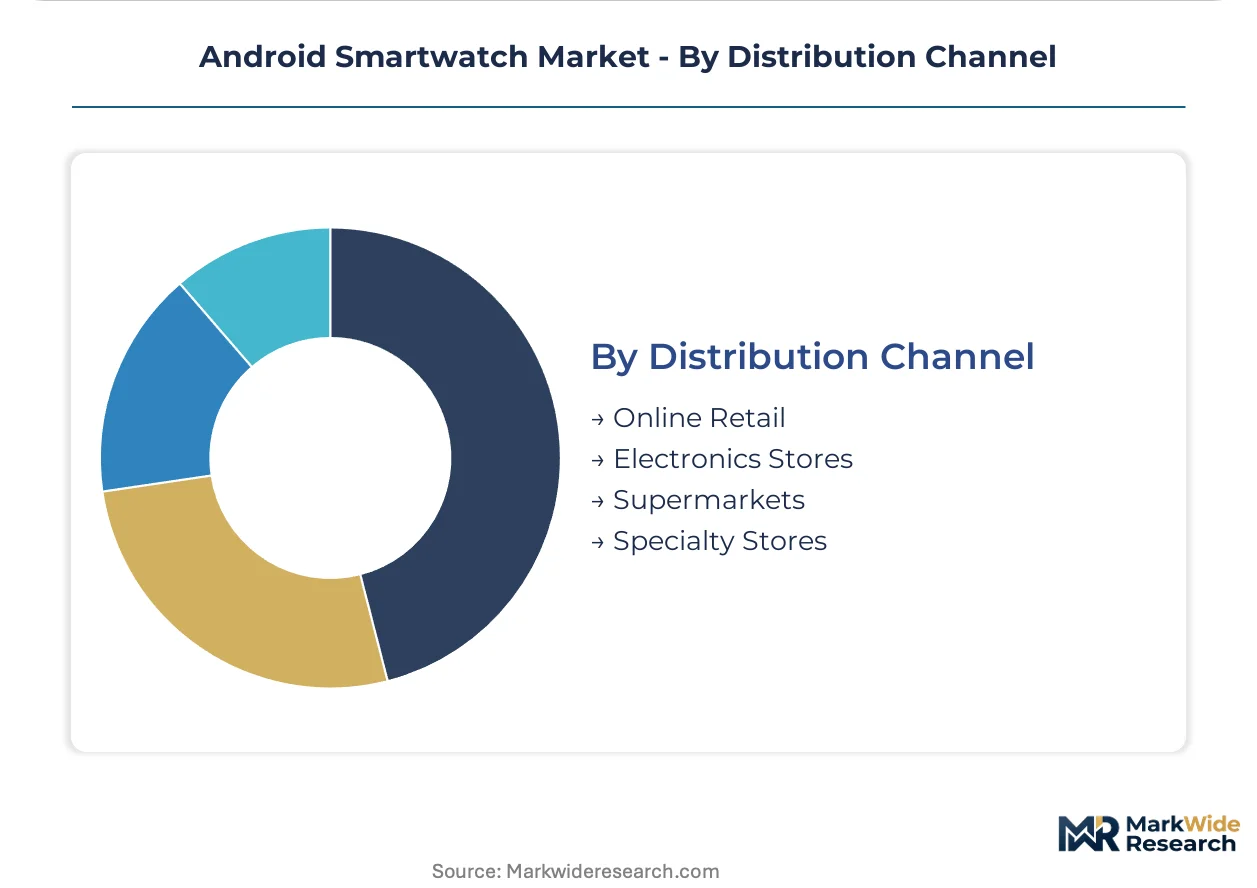
Online retail captures first-time buyers through algorithmic recommendation engines, while electronics stores and specialty retailers secure premium-tier purchasers seeking hands-on evaluation.
- Online Retail:Amazon, Flipkart, and JD.com algorithmic placement determines discovery for price-sensitive first-time buyers. Flash sales and bundled accessory promotions compress margins but accelerate inventory velocity.
- Electronics Stores:Best Buy, MediaMarkt, and Suning provide tactile evaluation for AMOLED display quality and haptic feedback, defending premium pricing against online discounting.
- Supermarkets:Impulse placement near checkout zones moves entry-level fitness bands with minimal sales assistance.
- Specialty Stores:Running and cycling retailers provide gait analysis and sport-specific fitting services that justify 15-20% price premiums over mass channels.
Online Retail commands volume leadership; Specialty Stores are gaining share fastest as sport-specific positioning differentiates against commoditized electronics retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian and Indonesian buyers prioritize sub-$75 fitness bands, while German and American consumers absorb 3-4x premiums for FDA-cleared health monitoring. This price-response divergence shapes regional product mix and margin architecture.
United States
Employer wellness subsidies and self-insured healthcare cost reduction drive B2B procurement concentration in California and New York metros. FDA 510(k) clearance for ECG and blood oxygen features enables clinical-grade marketing claims that justify $400+ price tiers. Samsung Electronics and Google anchor device distribution through carrier partnerships and direct-to-enterprise sales channels.
China
Domestic volume concentrates in affordable health tracking variants while export-oriented premium assembly flows from Shenzhen and Dongguan hubs toward North American markets. NMPA Class II medical device registrations now require multi-center validation studies comparable to FDA pathways. Huawei Technologies and Xiaomi fund clinical trials at Beijing Anzhen Hospital and Fuwai Hospital to secure regulatory approvals.
Germany
EU MDR compliance burdens delay product launches by twelve to eighteen months, compressing addressable market for blood oxygen monitoring features. GDPR constraints on biometric data processing force localized cloud storage architectures. Berlin and Munich host enterprise wellness program procurement decisions that bypass retail channel constraints for mid-tier device volumes.
India
PLI scheme production-linked incentives attract component assembly investments from global brand licensees. Sub-$100 price points unlock first-time wearable adoption in Mumbai, Delhi-NCR, and Bangalore urban centers. Xiaomi Corp. anchors position through aggressive pricing while extending Mi Band ecosystem loyalty upward into smartwatch tiers.
South Korea
In-house semiconductor and display production capabilities control component costs across flagship lineups. Seoul metropolitan area concentrates R&D talent for photoplethysmography sensor fusion and multi-LED configurations. Samsung Electronics leverages backward integration into AMOLED panel manufacturing to defend margin position against design-only competitors.
Android Smartwatch Market Competitive Landscape
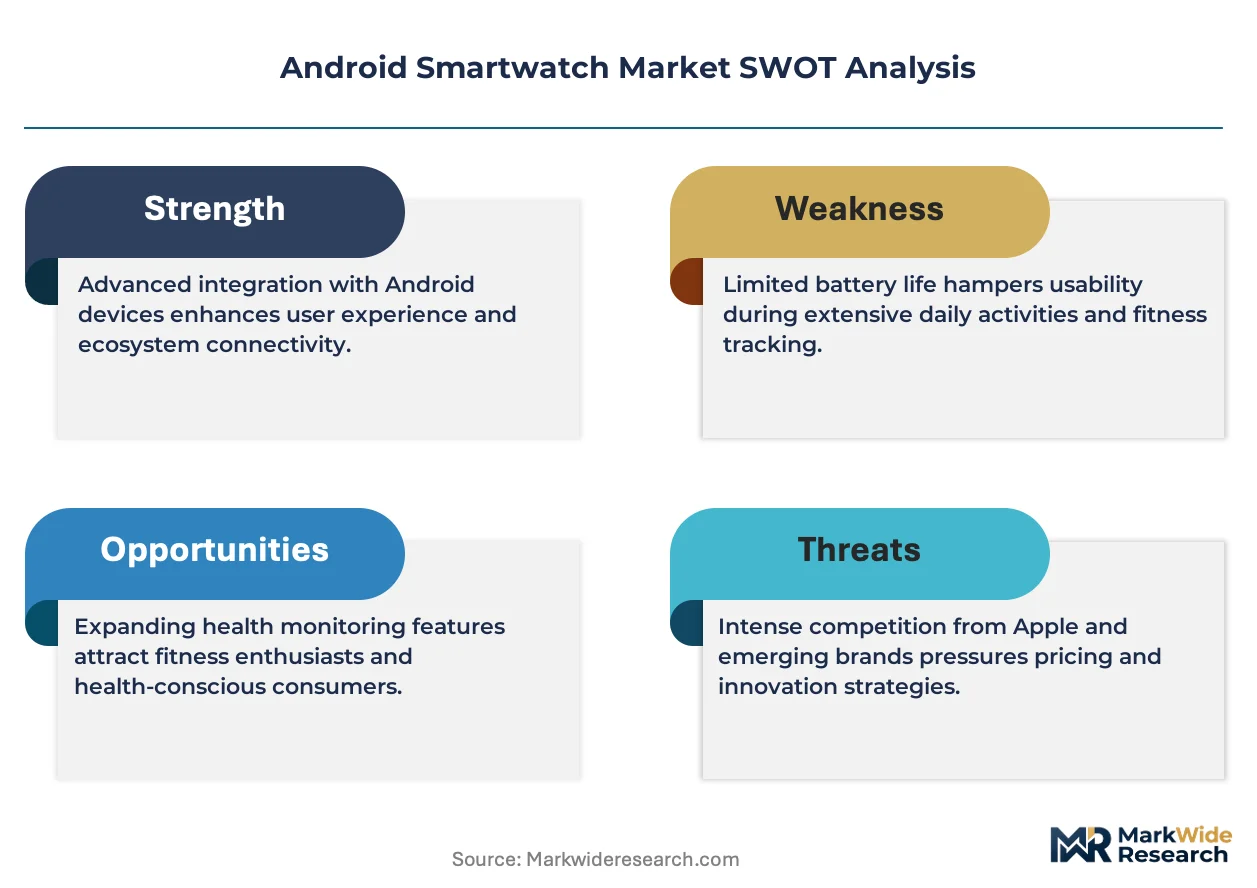
A small set of integrated leaders sits above a broader specialist tier in the Android smartwatch competitive structure. Samsung Electronics and Huawei Technologies occupy the vertically integrated apex through captive semiconductor and display supply chains. Design-focused wearables specialists compete on software differentiation and ecosystem integration rather than hardware cost control. Strategic moves concentrate on platform consolidation partnerships and clinical validation investments for regulatory clearance.
Among Asia-Pacific-based conglomerates, Samsung Electronics Co., Ltd and Huawei Technologies Co., Ltd exemplify the integrated archetype through upstream control over component manufacturing. Xiaomi Corp. occupies a position within the ecosystem-loyalty tier, leveraging existing user bases from adjacent product categories. Google represents the platform-layer anchor, consolidating Wear OS distribution across hardware partners rather than competing directly on device margins.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd |
| Garmin Ltd |
| Fitbit |
| OnePlus |
| Huawei Technologies Co., Ltd |
| Xiaomi Corp. |
| Mobvoi Inc. |
| Fossil Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance pathways gate both component supplier qualification and price tier separation in the Android smartwatch market, compressing margin architecture for uncertified vendors while elevating medical-grade premiums. This regulatory threshold simultaneously constrains supply base access and enables banking partnership fees that sustain NFC-enabled pricing power.
Pricing Analysis
Platform subscription revenue and extended warranty contracts now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared health monitoring flagships from fitness-focused mid-tiers and Mi Band-anchored entry bands. Cost compression in the sub-$100 tier intensifies because Indian and Indonesian buyers resist upgrade conversion from legacy fitness bands. Casual users exhibit highest price sensitivity; enterprise wellness procurement managers absorb 3-4x premiums for clinical-grade telemetry.
Supply Chain Analysis
Strategic stockpiling of AMOLED display panels and MEMS sensors dominates inventory strategy as Korean and Chinese panel manufacturers control over ninety percent of wearable-grade flexible output. Component sourcing concentrates in South Korea, China, and Taiwan, with photoplethysmography sensors, ARM-based processors, and multi-band GNSS modules anchoring bill-of-materials positions. Single-source vulnerability in flexible display supply creates input cost volatility during fab allocation cycles. Distribution runs through carrier partnerships and direct-to-enterprise sales channels that bypass retail margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Android smartwatch market is entering a cyclical recovery phase as employer wellness program procurement accelerates replacement cycles beyond individual retail purchase patterns. This B2B volume concentration in California and New York metropolitan corridors stabilizes revenue visibility against consumer discretionary softness.
For Market Incumbents: Secure ISO 13485 certification alignment to defend hospital-adjacent remote patient monitoring contracts against emerging design-focused specialists. Deepen backward integration into photoplethysmography sensor production to control component costs during AMOLED supply volatility. Channel control through carrier partnerships remains essential as retail discounting erodes brand premiums.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for accelerometer-gyroscope fall detection algorithms open reimbursable senior care facility contracts underserved by current flagships. Target Indonesia and Vietnam urban centers where sub-$100 price points unlock first-time wearable adoption ahead of ecosystem-locked incumbents. Local distributor partnerships provide the essential go-to-market angle for navigating fragmented retail landscapes.
For Investors and Strategic Acquirers: Carve-out targets emerge from electronics conglomerates spinning off non-core wearables divisions amid platform consolidation pressure. Five-to-ten year viability hinges on clinical validation capabilities rather than hardware volume scale. Watch FDA 510(k) clearance velocity for photoplethysmography-based arrhythmia detection as the inflection indicator separating medical-grade margin pools from commoditized fitness accessories.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Consolidation Partnership | Google's Wear OS distribution agreements with Samsung and Garmin unify developer investment against proprietary alternatives. |
| Clinical Validation Investment | Multi-center trials at Beijing Anzhen Hospital and Fuwai Hospital secure NMPA Class II registrations for Huawei and Xiaomi. |
| Enterprise Wellness Program Deployment | Self-insured employers in California negotiate three-year subscriptions that bypass retail channel constraints. |
| Backward Integration into Sensor Production | Samsung's BioActive Sensor in-house manufacturing defends margin position against design-only competitors. |
| Transit Authority NFC Partnership | Secure element certification by payment networks accelerates contactless credential deployment in urban mobility corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, FDA 510(k) submission databases, and NMPA registration records to establish market size and competitive positioning. Interviews with wearable product managers, regulatory affairs leads at medical device divisions, carrier partnership directors, and enterprise wellness procurement officers provided demand-side validation. Bottom-up shipment estimates by price tier and top-down platform revenue analysis were cross-checked against customs records from Shenzhen and Dongguan export hubs.
Segmentation dimensions modeled include product type tier, connectivity protocol, end user archetype, and distribution channel across the projection horizon. CAGRs were derived from regression analysis of historical shipment data against smartphone ecosystem penetration rates and employer wellness subsidy expansion curves. Pricing trajectories incorporated bill-of-materials cost curves for AMOLED panels and photoplethysmography sensor arrays.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance timelines or NMPA registration velocity would require recalibration. Forecasts assume continued Wear OS platform consolidation and stable employer wellness program adoption. Revision becomes warranted when AMOLED display supply concentration crosses critical allocation thresholds or EU MDR compliance burdens extend European launch delays beyond current twelve-to-eighteen month baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Smart Band Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Women's Watch Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Global Smartwatch Battery Market