
 3D Printed Wearables Market | 2026-2036
3D Printed Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Wearables Market Intelligence
Healthcare providers is bifurcating from fitness enthusiasts as the dominant buyer archetype in 3D printed wearables. Stratasys anchors its position through hospital-centric R&D partnerships for custom-fit medical devices. Materialise NV specializes in patient-specific surgical guides and orthopedic implants that command premium positioning. Formlabs competes by extending accessible desktop stereolithography into dental and audiology clinics worldwide.
3D printed wearables encompass body-worn devices fabricated through additive manufacturing, typically utilizing biocompatible photopolymers, selective laser-sintered nylon, or direct metal laser sintering to achieve sub-millimeter geometric precision for skin-contact applications. These devices serve medical monitoring, prosthetic integration, athletic performance tracking, and personalized fashion functions through digitally customized form factors impossible with injection molding. Medical sensors lead value capture due to regulatory barriers and reimbursement pathways that protect margin pools, while fitness bands represent the fastest-growing application as consumers seek biomechanically optimized designs. FDM technology dominates unit volume for basic prototypes and fitness accessories, yet SLA and SLS command structural priority in finished medical-grade production where surface finish and isotropic strength determine clinical acceptance.
FDA 510(k) clearance requirements govern patient-contact 3D printed devices in the United States, while EU MDR and CE marking obligations enforce biocompatibility documentation and clinical validation across European markets. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further constrain market entry for non-specialized manufacturers. Stakeholders must monitor evolving reimbursement codes for personalized medical devices and anticipate how national health technology assessment bodies will classify digitally manufactured wearables against conventionally produced alternatives.
Market Dynamics
Patient-specific manufacturing workflows are compressing traditional medical device development cycles from months to weeks, forcing established orthotics suppliers to retool quality systems around digital file-to-fabrication pipelines rather than mold-based production.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's additive manufacturing guidance for medical devices accelerates market entry for patient-matched prosthetics in the United States, reducing premarket notification review timelines for biocompatible photopolymer applications.
- Selective laser sintering maturation:Nylon 12 powder bed fusion now delivers isotropic mechanical properties matching injection-molded equivalents, enabling load-bearing orthopedic braces without tooling investment.
- Germany's hospital network consolidation:University medical centers in Berlin, Munich, and Hamburg maintain captive additive manufacturing labs, creating built-in demand channels for certified production partners.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock for direct metal laser sintering concentrates among a handful of plasma atomization specialists, exposing implant manufacturers to input cost volatility and allocation risk.
- EU MDR clinical validation burdens:The Medical Device Regulation's requirements for patient-specific implant biocompatibility documentation extend product development timelines and inflate regulatory compliance costs for European market entry.
- Injection molding cost floor:Conventional thermoforming retains substantial unit cost advantages above ten-thousand-unit production runs, capping addressable market size for mass-market fitness wearables.
Strategic Opportunities
- China's tier-two hospital penetration:Provincial medical centers in Chengdu, Wuhan, and Xi'an lack established orthotics fabrication partnerships, representing white space for certified 3D printing service bureaus with NMPA registration pathways.
- Remote patient monitoring integration:Convergence of embedded flexible electronics with photopolymer lattice structures enables continuous biomechanical sensing in custom-fit wearable form factors.
- India's PLI scheme for medical devices:The Production Linked Incentive program subsidizes domestic manufacturing of high-value implants, attracting foreign additive technology providers to establish CDSCO-compliant production nodes.
Industry Challenges
- Biomedical design engineering scarcity:The intersection of computational topology optimization, anatomical imaging segmentation, and ISO 13485 quality documentation requires hybrid skill sets rarely available in single candidates.
- Post-processing certification bottlenecks:Surface finishing, sterilization validation, and packaging integrity testing for patient-contact devices extend time-to-revenue beyond hardware depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Wearables Market |
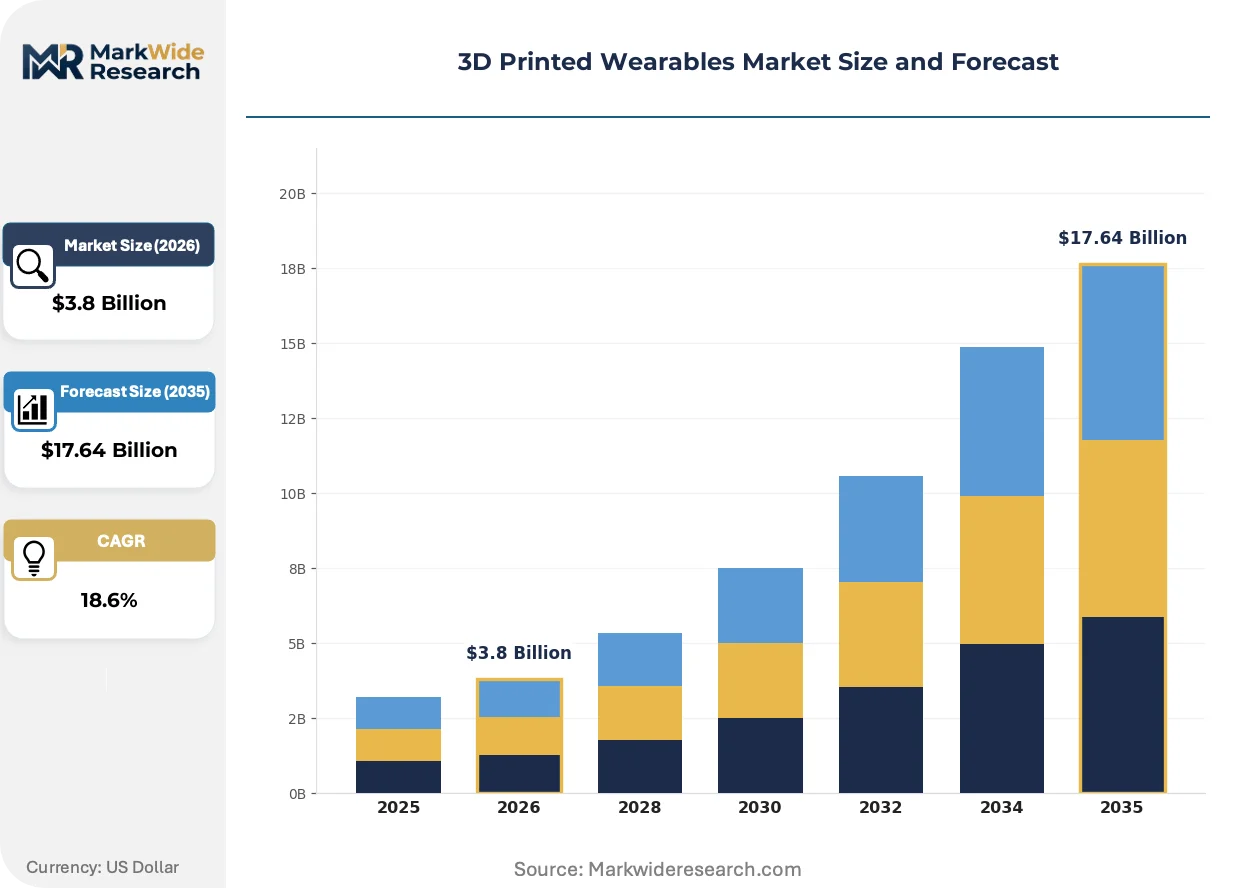
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Bands, Medical Sensors, Fashion Accessories End User: Healthcare Providers, Fitness Enthusiasts, Fashion Designers, Technologists Material: Thermoplastics, Metals, Polyurethanes, Bio-compatible Materials Technology: FDM, SLA, SLS, Binder Jetting |
| Companies Covered | 3D Systems, Inc, Stratasys, ENVISIONTEC US LLC, General Electric, Cyfuse Biomedical K.K., Koninklijke Philips N.V., Omron Corporation, Materialise NV, Formlabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Wearables Market Strategic Shifts & Innovations
Digital anatomy capture and generative design algorithms are collapsing the traditional hand-sculpted mold workflow, enabling same-day fitting appointments that reshape competitive dynamics in prosthetics and orthotics.
Multi-material extrusion systems incorporating conductive silver inks alongside structural polymers are miniaturizing integrated sensor architectures. Audiologists in the Netherlands and Denmark deploy these hybrid printers for hearing aids with embedded real-time feedback circuits. The technology is miniaturizing electronic packaging constraints that previously forced compromises between acoustic performance and wearer comfort.
Japan's PMDA issued supplemental guidance in 2023 clarifying quality management expectations for point-of-care 3D printed devices, prompting Tokyo and Osaka hospital networks to formalize in-house production protocols. Orthopedic departments now maintain validated file repositories for recurring patient-matched implant designs. The regulatory clarity accelerates same-day surgical guide fabrication, compressing preoperative planning cycles for complex joint reconstruction cases.
Hospital procurement departments increasingly specify digital manufacturing capabilities in orthopedic brace tenders, displacing traditional durable medical equipment distributors from specification influence. Large integrated delivery networks in Texas, California, and Florida consolidate vendor pools around additive-certified suppliers with direct-to-facility file transfer protocols. This concentration is most visible in pediatric orthotics, where rapid growth-adjusted refitting cycles favor on-demand production over inventory-heavy distribution models.
3D Printed Wearables Market Segmentation
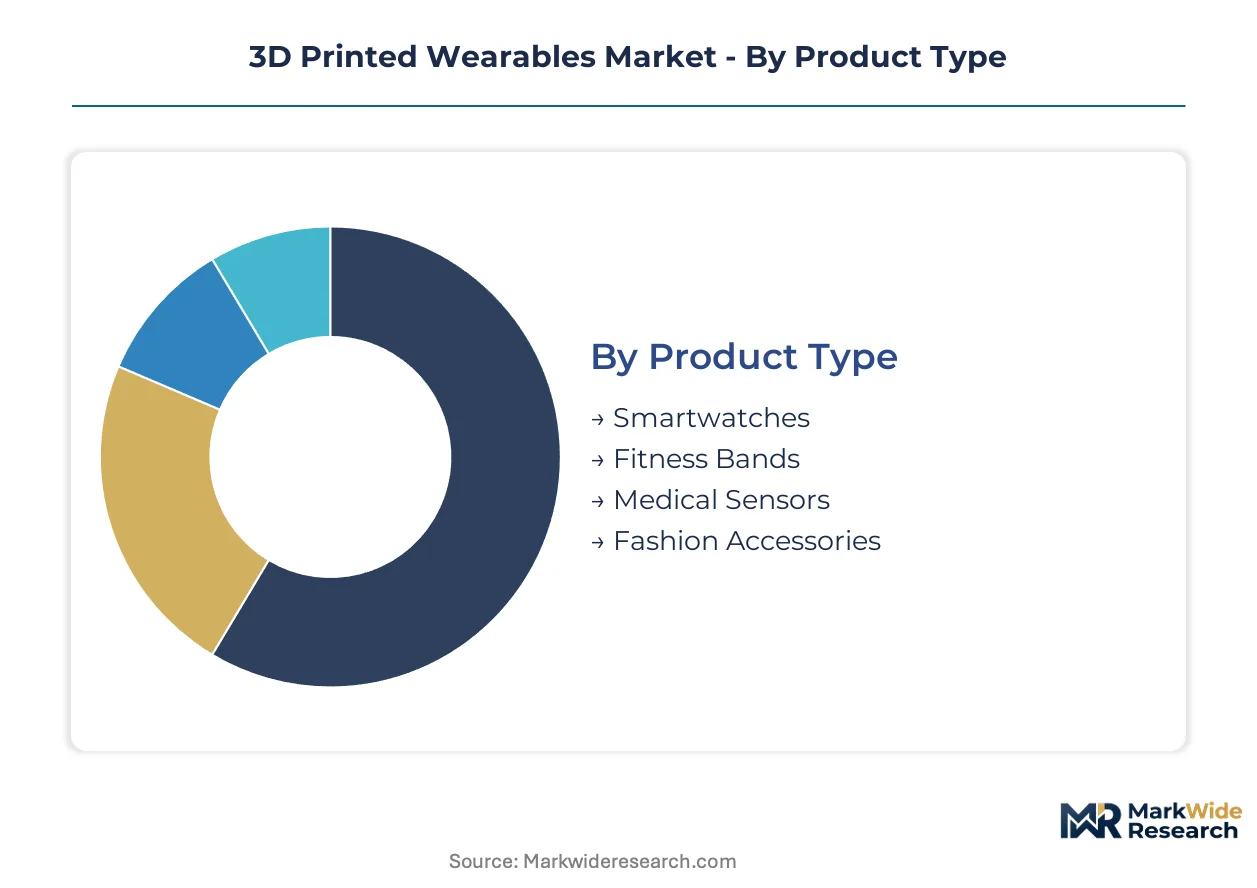
Segmentation in 3D printed wearables separates regulated medical applications from consumer discretionary purchases, with material biocompatibility and manufacturing precision determining margin structures and certification pathways across each category.
Product Type:
FDA 510(k) clearance requirements and EU MDR biocompatibility documentation create divergent commercialization timelines across wearable categories, with patient-contact devices facing extended validation cycles.
- Medical Sensors:Photopolymer housings with embedded conductive traces monitor glucose, cardiac rhythm, and respiratory biomarkers. Demand concentrates in United States hospital networks where reimbursement codes for continuous monitoring protect premium pricing. FDA clearance pathways and ISO 13485 quality systems constrain supplier pools.
- Fitness Bands:Nylon 12 selective laser sintering enables lattice structures that optimize sweat wicking and biomechanical fit. Germany's university medical centers and China's tier-two hospitals drive procurement as institutional wellness programs expand. Customization commands price premiums over injection-molded equivalents.
- Smartwatches:Titanium direct metal laser sintering produces durable, lightweight casings for high-performance athletic applications.
- Fashion Accessories:Thermoplastic polyurethane FDM prints enable rapid style iteration for limited-edition designer collaborations.
Established volume favors Medical Sensors; emerging adoption favors Fitness Bands.
End User:
Customer procurement sophistication varies from institutional tender processes with validated supplier lists to individual consumers prioritizing aesthetic customization and delivery speed.
- Healthcare Providers:Hospital orthopedic departments and audiology clinics specify ISO 13485-certified production with direct digital file transfer protocols. United States integrated delivery networks in Texas and Florida consolidate vendor pools around additive-certified partners. Reimbursement pathways for patient-matched devices protect margin pools.
- Technologists:Early adopters in Netherlands and Denmark deploy hybrid multi-material systems for hearing aids with real-time feedback circuits. Embedded electronics miniaturization drives specification requirements beyond structural performance alone.
- Fitness Enthusiasts:Biomechanical optimization and rapid refitting cycles attract consumers seeking performance differentiation.
- Fashion Designers:Digital customization enables micro-batch production without tooling investment for runway and capsule collections.
Procurement consolidation favors Healthcare Providers; customization premium favors Technologists.
Material:
Feedstock selection determines mechanical properties, sterilization compatibility, and regulatory classification for skin-contact applications.
- Bio-compatible Materials:ISO 10993-tested photopolymers and USP Class VI silicones serve implantable and long-term wear applications. FDA and EU MRA documentation requirements extend development timelines but protect qualified supplier margins. Germany's hospital networks specify certified bio-compatible grades for pediatric orthotics.
- Thermoplastics:ABS and PLA filament deposition dominates fitness accessory prototyping and low-load applications. Cost efficiency and desktop printer accessibility drive adoption in China's provincial medical centers without captive additive labs.
- Metals:Ti-6Al-4V powder bed fusion produces load-bearing orthopedic braces and surgical guides.
- Polyurethanes:Flexible resin formulations enable soft-tissue interfaces and vibration-damping properties.
Regulatory protection favors Bio-compatible Materials; volume accessibility favors Thermoplastics.
Technology:
Process selection trades build speed against surface finish, isotropic strength, and geometric complexity for finished part requirements.
- SLS:Nylon 12 powder bed fusion delivers isotropic mechanical properties matching injection-molded equivalents without tooling investment. Germany's Berlin and Munich university centers deploy SLS for load-bearing orthopedic braces. Surface finish quality supports direct patient contact without extensive post-processing.
- SLA:Stereolithography achieves sub-millimeter precision for dental aligners and audiology shells. Formlabs and comparable desktop systems extend access to India's CDSCO-registered clinics and China's tier-two hospitals. Biocompatible resin formulations command material premiums.
- FDM:Filament deposition dominates prototype iteration and fitness accessory production for cost-sensitive applications.
- Binder Jetting:Metal powder binding enables medium-volume titanium production without laser system capital intensity.
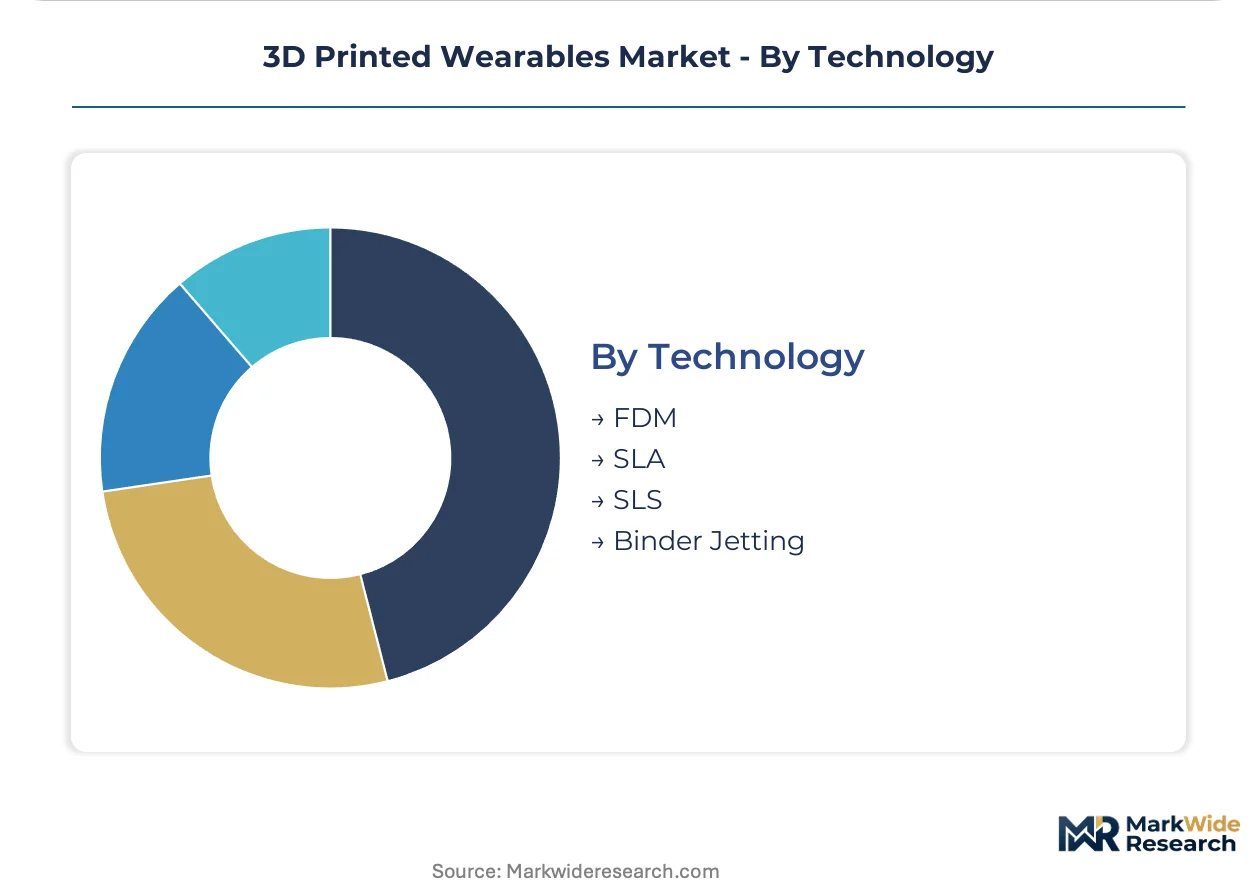
Clinical acceptance favors SLS; accessibility expansion favors SLA.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites Europe's distribution centrality for 3D printed wearables, connecting German additive manufacturing clusters to Atlantic shipping lanes.
United States
Integrated delivery networks in Texas, California, and Florida consolidate procurement around additive-certified suppliers with direct digital file transfer protocols. FDA 510(k) clearance pathways for patient-matched prosthetics compress premarket review timelines for biocompatible photopolymer applications. Hospital networks in Houston and the Research Triangle maintain captive additive manufacturing labs with validated production workflows.
Germany
University medical centers in Berlin, Munich, and Hamburg sustain built-in demand channels for certified production partners through captive additive manufacturing facilities. EU MDR biocompatibility documentation requirements enforce clinical validation standards across European markets. The Eindhoven-to-Munich medical technology corridor concentrates precision polymer processing expertise for orthopedic brace fabrication.
China
Provincial medical centers in Chengdu, Wuhan, and Xi'an lack established orthotics fabrication partnerships, creating white space for certified 3D printing service bureaus. NMPA registration pathways govern patient-contact device market entry with quality management documentation requirements. Yangtze River Delta hospital networks in Shanghai and Suzhou pioneer point-of-care production protocols for surgical guides.
Japan
PMDA supplemental guidance issued in 2023 clarified quality management expectations for point-of-care 3D printed devices, prompting hospital network formalization of in-house production. Tokyo and Osaka orthopedic departments now maintain validated file repositories for recurring patient-matched implant designs. Same-day surgical guide fabrication compresses preoperative planning cycles for complex joint reconstruction cases.
India
The Production Linked Incentive program subsidizes domestic manufacturing of high-value implants, attracting foreign additive technology providers to establish CDSCO-compliant production nodes. Tier-two hospital penetration in Bengaluru and Hyderabad drives demand for desktop stereolithography systems in dental and audiology clinics. Maharashtra's medical device manufacturing zones concentrate polymer powder bed fusion capacity for orthopedic applications.
3D Printed Wearables Market Key Industry Players
Concentration sits with diversified additive manufacturing incumbents and specialized medical device fabricators. Hospital-centric R&D partnerships and regulatory certification capabilities determine competitive positioning across procurement consolidation waves. Three archetypes dominate: capital equipment suppliers with medical-grade system portfolios, software-integrated service bureaus with ISO 13485 quality systems, and point-of-care solution providers with desktop accessibility. Capacity expansion into certified production facilities and strategic partnerships with integrated delivery networks represent the dominant competitive moves reshaping vendor selection criteria.
Among diversified capital equipment providers, 3D Systems, Inc. and Stratasys occupy positions anchoring hospital network procurement specifications. Materialise NV exemplifies the software-integrated service bureau archetype with regulatory documentation capabilities. Formlabs represents the desktop accessibility vector extending stereolithography into clinic-scale deployments. These three companies collectively span the technology-to-service spectrum that procurement departments evaluate against validated supplier criteria.
| Leading Market Players |
|---|
| 3D Systems, Inc |
| Stratasys |
| ENVISIONTEC US LLC |
| General Electric |
| Cyfuse Biomedical K.K. |
| Koninklijke Philips N.V. |
| Omron Corporation |
| Materialise NV |
| Formlabs |
| Others |
Cost & Logistics Intelligence
Capacity utilization at powder atomization facilities in Germany and the United States shapes both titanium feedstock availability and orthopedic implant price floors, compressing margins for manufacturers without captive supply agreements or NMPA-registered alternatives in China.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical sensors from CE-marked fitness bands and uncertified prototype-grade accessories. Price differentiation hinges on ISO 13485 certification status and biocompatible resin grade, with hospital procurement committees least sensitive and individual fitness consumers most responsive to unit cost. Pricing pressure stems from selective laser sintering equipment depreciation schedules as service bureaus compete for orthopedic brace contracts. Healthcare providers absorb premium positioning through reimbursement-protected channels, while fashion designers and fitness enthusiasts drive commoditization in unregulated segments.
Supply Chain Analysis
Inventory lead times for spherical Ti-6Al-4V powder extend beyond hardware depreciation cycles, forcing implant manufacturers to pre-position feedstock at production nodes. Supply concentrates in Germany, China, and the United States for selective laser sintering systems, with photopolymer resin formulation expertise clustering in the Netherlands and Japan. Raw material dependencies span titanium powder, nylon 12 granules, and biocompatible photopolymers. Single-source vulnerability in plasma atomization capacity exposes orthopedic brace manufacturers to allocation risk during demand surges. Distribution runs through hospital GPO contracts in the United States and direct digital file transfer protocols in German university medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement consolidation in Texas, California, and Florida, fragmenting specification influence among traditional durable medical equipment distributors.
For Market Incumbents: Secure ISO 13485-certified production capacity in China's Yangtze River Delta before NMPA registration pathways tighten, and deepen backward integration into photopolymer resin formulation to defend margin position against desktop SLA entrants. Threat substitution from Formlabs-style clinic-scale deployments demands channel control through validated file transfer protocols with hospital networks. For New Entrants and Emerging Players: Lead with tier-two hospital penetration in Chengdu, Wuhan, and Xi'an where orthotics fabrication partnerships remain unestablished, and target India's CDSCO-registered dental and audiology clinics via Maharashtra's medical device manufacturing zones. White space sits with remote patient monitoring integration, where embedded flexible electronics convergence enables premium positioning beyond structural performance alone. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-integrated service bureaus with regulatory documentation capabilities, suggesting long-term viability accrues to platforms combining computational topology optimization with ISO 13485 quality systems. Acquisition target archetype: hybrid skill-set organizations bridging anatomical imaging segmentation and biomedical design engineering. Signal to watch: NMPA registration pathway acceleration for foreign additive technology providers establishing domestic production nodes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for patient-matched prosthetics in United States hospital networks. |
| Hospital System Partnership | Consolidates vendor pools around additive-certified suppliers with direct file transfer protocols. |
| Backward Integration into Feedstock | Secures spherical Ti-6Al-4V supply against powder atomization allocation risk. |
| Software Companion Development | Enables generative design algorithms for same-day fitting appointments in orthotics. |
| Reimbursement Strategy | Protects premium pricing for continuous monitoring applications through CMS code alignment. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and additive manufacturing service bureau operators anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR submission databases, NMPA registration records, and hospital procurement contract repositories. Bottom-up patient-volume modeling and top-down equipment installation tracking triangulated market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against titanium powder price volatility and regulatory timeline compression scenarios. Segmentation dimensions spanned product type, end user archetype, material biocompatibility grade, and technology process selection. CAGRs derived from equipment shipment trajectories, hospital lab expansion announcements, and reimbursement code adoption curves. Industry-specific inputs included ISO 13485 certification velocity and point-of-care production protocol formalization rates.
Forecasts assume regulatory continuity in FDA, EU MDR, and NMPA regimes; material policy shifts would require re-modeling. Specific risks include PMDA guidance evolution in Japan, India's PLI scheme modification, and EU MDR clinical validation burden inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Smart Necklace Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Smart Bra Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Children Digital Watch Market