
 Asia Pacific Smartwatch Market | 2026-2036
Asia Pacific Smartwatch Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smartwatch Market Insights
Premium-tier health monitoring specifications is rotating the Asia Pacific smartwatch market toward higher-margin configurations. Samsung Electronics leverages its in-house semiconductor capabilities to control sensor integration costs. Xiaomi Corporation anchors its position through aggressive pricing across India's online retail channels. Garmin Ltd. differentiates through specialized GPS accuracy for outdoor fitness tracking.
A smartwatch integrates a wearable computer with biometric sensors, wireless connectivity modules, and rechargeable power systems typically rated for multi-day operation between charges. The device serves commercial purposes spanning health telemetry, mobile payment authentication, and real-time navigation assistance. Fitness trackers dominate volume shipments across the region's online retail channels, while luxury smartwatches capture concentrated margin pools through limited distribution in specialty stores. NFC-enabled models are gaining structural prominence as contactless payment infrastructure expands across South Korean and Japanese urban transit networks.
India's BIS mandates electromagnetic compatibility certification for all wearable devices, directly shaping product design cycles for manufacturers targeting the subcontinent. Japan's METI enforces radio equipment compliance standards that constrain transmitter configurations in devices sold domestically. South Korea's MFDS maintains medical-device-adjacent guidelines for continuous heart-rate and blood-oxygen monitoring claims. Stakeholders must monitor evolving biometric data privacy frameworks across Australia, Singapore, and Thailand as these jurisdictions develop wearable-specific consumer protection rules.
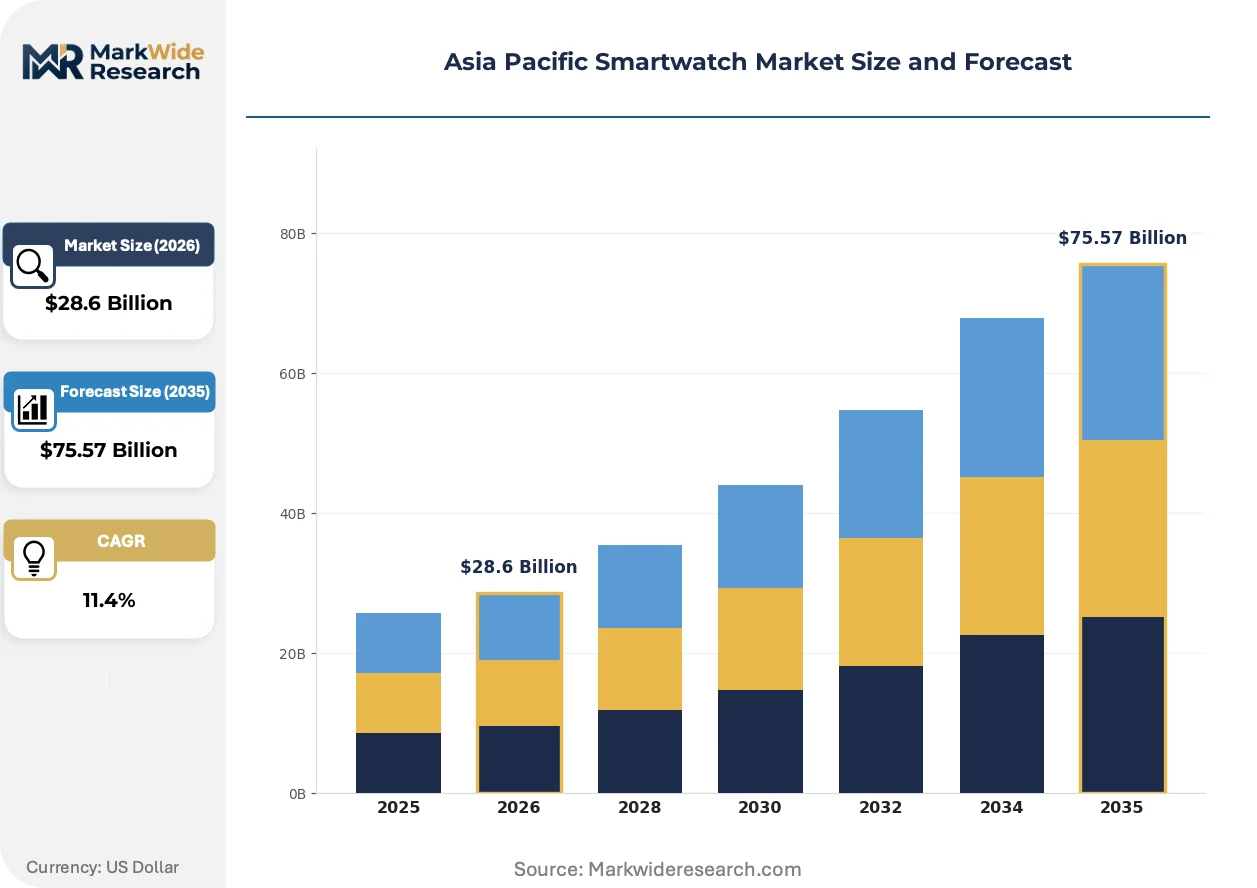
Market Dynamics
India's BIS electromagnetic compatibility certification mandates are compressing product development timelines and forcing hardware redesigns for manufacturers targeting the subcontinent's metropolitan consumer bases.
Growth Catalysts
- Fitness telemetry adoption:Health-conscious consumers across South Korea and Japan are demanding continuous heart-rate and blood-oxygen monitoring capabilities, expanding the addressable base for medical-grade sensor configurations.
- BIS certification harmonization:India's tightening electromagnetic compatibility standards are accelerating quality upgrades across the supply chain, filtering out substandard imports and elevating average selling prices for compliant devices.
- NFC transit integration:Contactless payment infrastructure expansion across Japanese and South Korean urban rail networks is structurally elevating demand for payment-enabled wearable form factors.
Market Restraints
- Display panel cost volatility:AMOLED and LTPO screen supply concentration in Korean and Chinese manufacturing clusters creates margin pressure during component allocation cycles.
- Biometric sensor supply concentration:Photoplethysmography and SpO2 module sourcing relies heavily on Taiwanese and Japanese component specialists, exposing brands to single-source vulnerability.
- Medical-claim regulatory friction:South Korea's MFDS guidelines constrain how manufacturers market continuous monitoring features, limiting differentiation for health-focused positioning.
Strategic Opportunities
- Tier-two Indian urban penetration:Smartwatch adoption remains underdeveloped in cities like Pune, Hyderabad, and Ahmedabad relative to Mumbai and Delhi, creating whitespace for localized distribution models.
- Enterprise wellness programs:Corporate health initiatives across Australian and Singaporean employers are opening bulk procurement channels for standardized wearable fleets with centralized data dashboards.
- Cross-border e-commerce channels:Direct-to-consumer platforms are enabling Southeast Asian brands to bypass traditional retail markups and establish presence in Vietnamese and Indonesian markets.
Industry Challenges
- Firmware-aerospace engineering talent scarcity:The intersection of low-power embedded systems and clinical-grade algorithm development remains critically understaffed across the region's engineering labor pools.
- Multi-jurisdiction certification sequencing:Brands must stagger BIS, METI, and MFDS approval timelines, creating launch delays and inventory fragmentation across country-specific SKUs.
- Legacy smartphone ecosystem lock-in:Platform-specific health data silos complicate user migration between Android and iOS companion environments, elevating customer acquisition costs for cross-platform entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smartwatch Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Watches, Fitness Trackers, Hybrid Smartwatches, Luxury Smartwatches Technology: Bluetooth, Wi-Fi, NFC, GPS End User: Adults, Teenagers, Fitness Enthusiasts, Seniors Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Xiaomi Corporation, Amazfit, Apple Inc., Motorola, OPPO, Samsung Electronics, Garmin Ltd., Noise, Huawei Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smartwatch Market Trends and Innovations
Sensor fusion architectures and regulatory harmonization efforts are compressing development cycles while elevating clinical credibility thresholds across the Asia Pacific wearable ecosystem.
MicroLED display technology is supplanting traditional AMOLED configurations in premium-tier devices. Japanese and South Korean early adopters are driving initial volume for this transition. The shift is enabling daylight-visible always-on interfaces while reducing power draw for multi-day battery life claims.
Australia's evolving biometric data privacy framework is forcing explicit consent mechanisms for health telemetry storage and third-party sharing. Device manufacturers must now embed granular permission architectures directly into companion application workflows. Fitness-focused brands targeting Australian enterprise wellness contracts are restructuring data governance policies to maintain procurement eligibility.
Specialty retail channels in Indian metropolitan markets are ceding volume to quick-commerce platforms promising sub-two-hour delivery windows. Urban consumers in Bangalore and Chennai increasingly finalize purchase decisions through app-based comparison tools rather than in-store demonstration. This behavioral pivot is compressing brand marketing spend toward performance-based digital acquisition and away from mall-based flagship investments.
Asia Pacific Smartwatch Market Segmentation
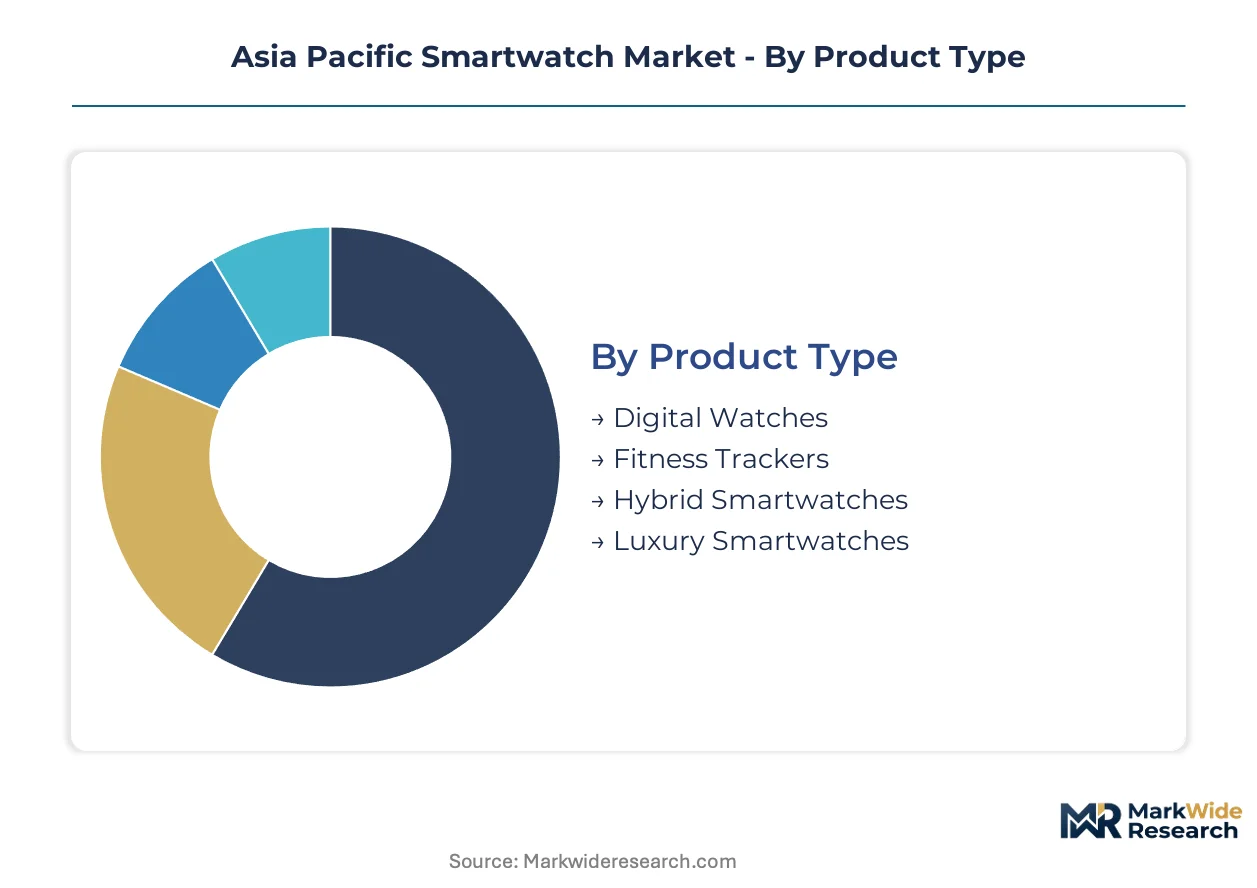
Smartwatch purchasing patterns across the Asia Pacific diverge sharply by use case and technical sophistication. Manufacturers must align sensor configurations and connectivity modules to distinct buyer profiles rather than pursuing universal feature sets.
Product Type:
Fitness trackers face intensifying substitution pressure from dedicated health wearables and smartphone-integrated motion sensors, forcing vendors to differentiate through clinical-grade biometrics.
- Digital Watches:These devices prioritize timekeeping functions with basic notification mirroring and limited sensor arrays. Demand concentrates among price-sensitive consumers in Indian tier-two cities where BIS-compliant entry-level models dominate quick-commerce channels.
- Fitness Trackers:Continuous heart-rate and SpO2 monitoring anchor these lightweight form factors. South Korean and Japanese health-conscious buyers drive specification upgrades toward medical-device-adjacent accuracy claims under MFDS guidelines.
- Hybrid Smartwatches:Analog-dial aesthetics conceal Bluetooth connectivity and step-counting capabilities. Japanese metropolitan professionals favor these configurations for workplace-appropriate styling without full digital distraction.
- Luxury Smartwatches:Premium materials and exclusive distribution through specialty stores define this tier. Limited production runs target concentrated margin pools in Singapore and Hong Kong luxury retail corridors.
Fitness trackers retain volume leadership; luxury smartwatches hold the steepest expansion curve.
Technology:
Cost tier stratification determines which connectivity modules manufacturers integrate, with premium devices absorbing multi-protocol stacks while economy SKUs minimize component count.
- Bluetooth:Low-energy protocols enable smartphone tethering for notification relay and firmware updates. This baseline configuration saturates Indian online retail channels where price elasticity shapes procurement decisions.
- Wi-Fi:Direct cloud synchronization bypasses smartphone intermediaries for music streaming and standalone app functionality. Australian enterprise wellness deployments specify Wi-Fi capability for centralized fleet management dashboards.
- NFC:Contactless payment and transit authentication modules are gaining structural prominence. Japanese and South Korean urban rail network integration elevates demand for FeliCa and EMV-compatible wearable form factors.
- GPS:Multi-band satellite positioning enables route tracking without smartphone tethering. Outdoor fitness enthusiasts across Australian trail networks and Japanese mountain regions drive accuracy requirements for specialized vendors.
Bluetooth-enabled devices command shipment volume; NFC configurations are climbing the fastest.
End User:
Application-specific use cases segment the addressable base, with health telemetry and payment authentication creating divergent hardware requirements.
- Adults:General-purpose productivity and health monitoring define this broad category. Metropolitan Indian consumers in Mumbai and Bangalore prioritize notification management and multi-day battery endurance.
- Teenagers:Social connectivity features and customizable watch faces dominate purchasing criteria. Parental control integrations and durable chassis designs shape product development for this demographic.
- Fitness Enthusiasts:This rapidly expanding segment demands continuous biometric monitoring and specialized workout modes. South Korean MFDS guidelines constrain how manufacturers market clinical-grade accuracy claims to this audience.
- Seniors:Fall detection, medication reminders, and simplified interfaces address aging-population needs. Japanese METI radio equipment compliance standards affect transmitter configurations in devices targeting this safety-critical segment.
Adult-oriented SKUs retain volume leadership; fitness enthusiast configurations gain share fastest.
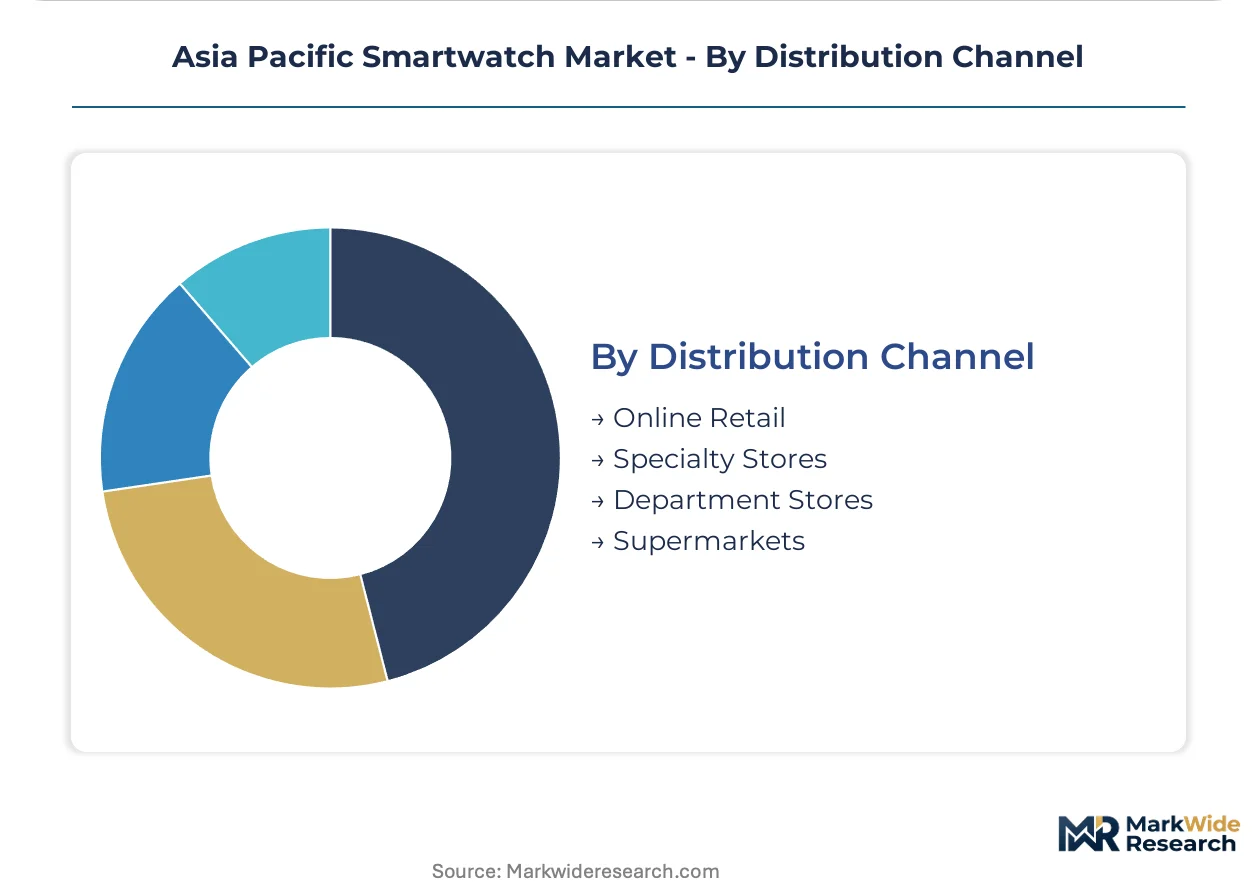
Distribution Channel:
Customer type and purchase urgency determine channel selection, with urban convenience expectations reshaping traditional retail economics.
- Online Retail:Aggressive pricing and comparison tools dominate volume shipments. Xiaomi Corporation anchors position through flash sales and exclusive launches across Indian e-commerce platforms.
- Specialty Stores:In-person demonstration and technical consultation support premium-tier purchases. Japanese electronics retailers and Singaporean luxury malls concentrate high-margin transactions.
- Department Stores:Mid-range gifting occasions and seasonal promotions drive this channel. Australian and South Korean department store networks maintain curated wearable selections.
- Supermarkets:Impulse purchases and entry-level stocking characterize this emerging channel. Indian quick-commerce platforms are compressing delivery windows below two hours, eroding traditional supermarket foot traffic.
Online retail retains volume leadership; specialty stores hold the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific smartwatch trade flows reveal a pronounced import dependency in India against export-oriented manufacturing bases in China and Vietnam. Component sourcing networks concentrate in Taiwanese and South Korean semiconductor clusters. Finished goods distribution radiates from Shenzhen and Ho Chi Minh City logistics hubs into Southeast Asian and Oceania consumer markets.
India
Metropolitan demand in Mumbai, Delhi, and Bangalore drives volume procurement through quick-commerce channels. BIS electromagnetic compatibility certification mandates compress development timelines for entrants targeting the subcontinent. Domestic assembly operations in Noida and Sri City industrial corridors are expanding to reduce import duty exposure.
China
Shenzhen and Dongguan manufacturing ecosystems anchor global smartwatch production capacity with vertically integrated display and battery supply chains. MIIT radio transmission standards govern wearable device certification protocols. Yangtze River Delta component suppliers dominate photoplethysmography sensor module output for regional brand procurement.
Japan
Tokyo and Osaka metropolitan professionals favor hybrid analog-digital form factors for workplace-appropriate styling. METI radio equipment compliance standards constrain transmitter configurations in devices sold domestically. Kanto region specialty electronics retailers concentrate high-margin transactions through in-person technical consultation.
South Korea
Seoul Capital Area consumers demand medical-grade biometric accuracy for continuous heart-rate monitoring. MFDS guidelines constrain how manufacturers market clinical-grade health claims to fitness enthusiasts. Busan-Ulsan logistics corridors facilitate component import from Japanese and Taiwanese specialist suppliers.
Australia
Sydney and Melbourne enterprise wellness programs are opening bulk procurement channels for standardized wearable fleets. Evolving biometric data privacy frameworks force explicit consent mechanisms for health telemetry storage. New South Wales and Victoria corporate health initiatives are restructuring data governance policies to maintain procurement eligibility.
Asia Pacific Smartwatch Market Competitive Landscape
Concentration sits with diversified consumer electronics conglomerates controlling semiconductor and display supply chains. Market structure exhibits tiered competition across premium health-monitoring configurations, mid-range fitness-oriented devices, and entry-level notification wearables. Three strategic archetypes dominate: integrated technology conglomerates with captive component production, specialized fitness-tracking vendors with GPS accuracy differentiation, and value-oriented brands leveraging flash-sale e-commerce velocity. Dominant competitive moves include backward integration into sensor module sourcing and geographic expansion through direct-to-consumer platform establishment.
Among Asia Pacific headquartered conglomerates, Samsung Electronics and Xiaomi Corporation exemplify divergent positioning archetypes. Samsung Electronics occupies a position representing integrated semiconductor capability leveraged for sensor cost control. Xiaomi Corporation anchors the aggressive online retail penetration archetype through exclusive e-commerce launch strategies. Garmin Ltd., originating from a specialized outdoor equipment tradition, sits within the precision-navigation differentiation tier. These three entities collectively represent the competitive spectrum spanning premium health telemetry, mass-market volume, and specialized fitness accuracy.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Amazfit |
| Apple Inc. |
| Motorola |
| OPPO |
| Samsung Electronics |
| Garmin Ltd. |
| Noise |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with Taiwanese photoplethysmography sensor suppliers lock in both component access and unit cost visibility for brands navigating India's BIS electromagnetic compatibility mandates. These arrangements insulate procurement teams from spot-market volatility while compressing margin buffers for entrants lacking scale.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in enterprise wellness deployments. Certification grade under BIS and MFDS guidelines separates compliant from non-compliant tiers, while volume scale drives negotiation leverage for Australian corporate fleet procurement. Cost compression in economy SKUs is intensifying because AMOLED panel allocation cycles favor premium-tier orders. Quick-commerce channel buyers in Indian metropolitan markets exhibit highest price sensitivity; Japanese specialty retail customers demonstrate lowest elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor photoplethysmography and SpO2 module fabrication for regional smartwatch brands. Component sourcing draws from Yangtze River Delta display clusters and Shenzhen battery assembly ecosystems. Single-source vulnerability in Taiwanese sensor specialists exposes brands to allocation disruptions during demand spikes. Distribution runs through Ho Chi Minh City logistics hubs into Southeast Asian markets and quick-commerce platforms across Indian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on health data interoperability between Android and iOS companion environments, forcing ecosystem choices that lock in user migration costs.
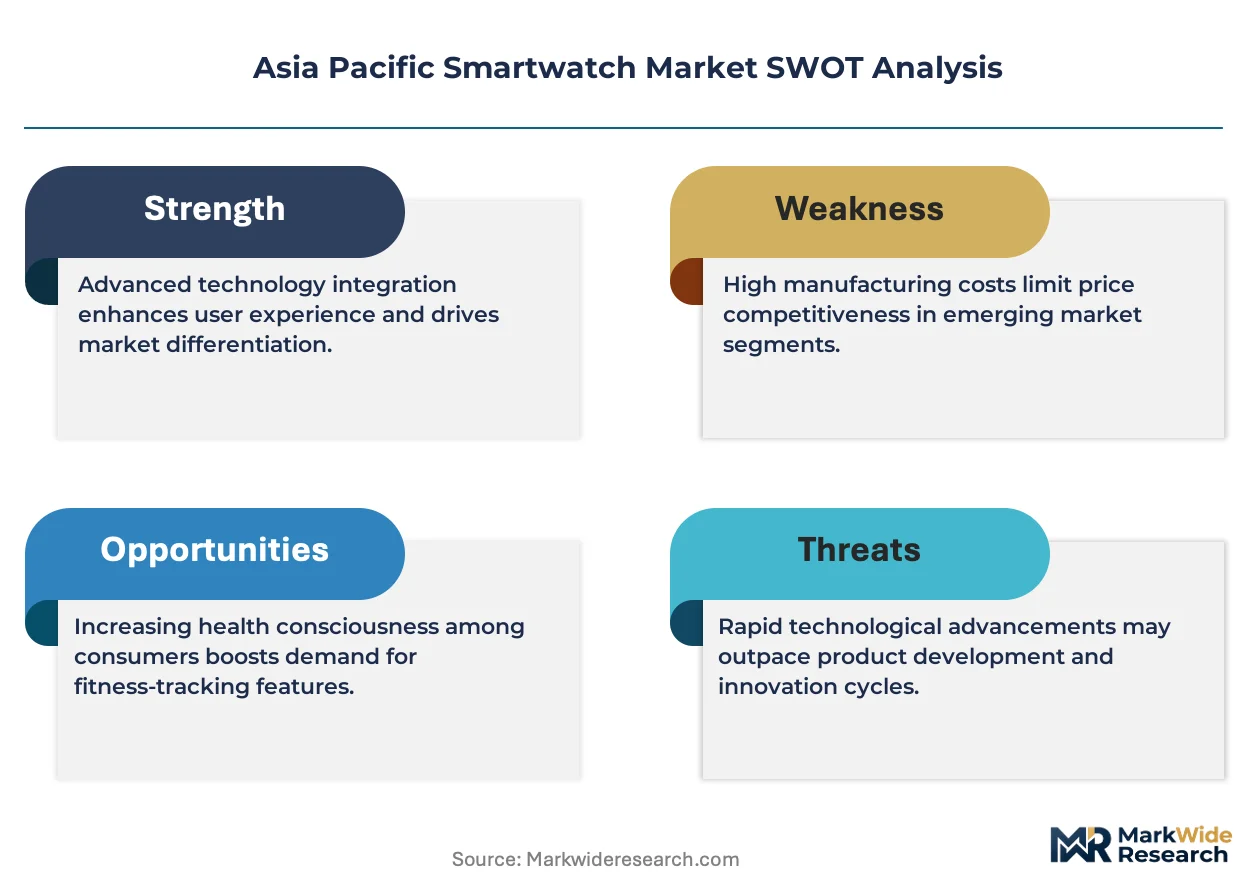
For Market Incumbents: Compound captive sensor integration through backward integration into photoplethysmography module sourcing. Expand Noida and Sri City assembly capacity to deflect Indian import duty exposure. Counter emerging Southeast Asian direct-to-consumer entrants by tightening quick-commerce exclusivity arrangements with Indian platform partners. For New Entrants and Emerging Players: Enterprise wellness data governance gaps in Australian corporate procurement specifications offer service-layer differentiation through explicit consent architectures. Target Sydney and Melbourne bulk fleet channels where standardized wearable deployments lack centralized dashboard integration. Pursue white-label partnerships with Australian employers restructuring health telemetry policies. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors component-integrated mid-caps with BIS and MFDS approval pipelines. Long-term viability hinges on regulatory compliance velocity rather than pure hardware innovation. Watch MFDS guideline expansions constraining clinical-grade marketing claims as inflection signal for health-focused positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Backward Integration | Captive photoplethysmography sourcing reduces allocation vulnerability to Taiwanese specialist suppliers. |
| BIS Certification Fast-Track Investment | Accelerated electromagnetic compatibility approval unlocks Indian metropolitan quick-commerce channel access. |
| Enterprise Wellness Platform Partnership | Australian employer fleet procurement contracts require centralized data dashboard compatibility. |
| MicroLED Display Technology Transition | Japanese and South Korean early adopter demand enables daylight-visible always-on interface differentiation. |
| Cross-Border E-Commerce Channel Establishment | Direct-to-consumer platforms bypass traditional retail markups in Vietnamese and Indonesian markets. |
Research Methodology
Desk research of customs import records, BIS certification filings, and MFDS device registration databases preceded structured interviews with smartwatch product managers, component procurement leads at regional OEMs, quick-commerce platform category heads, and Australian corporate wellness program directors. Primary fieldwork with supply chain planners and regulatory affairs specialists cross-checked secondary data on certification timelines and sensor module sourcing patterns. Bottom-up shipment estimates triangulated against top-down consumer expenditure models.
Variance decomposition across product type, connectivity protocol, end-user demographic, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Modeled inputs incorporated BIS electromagnetic compatibility approval velocity, AMOLED panel allocation cycles, and NFC transit infrastructure deployment timelines across Japanese and South Korean urban networks.
Underlying assumptions cover sustained Indian quick-commerce penetration, stable Taiwanese sensor specialist capacity, and Australian biometric data privacy framework evolution, with deviation risk concentrated in multi-jurisdiction certification sequencing delays. Recalibration cycles align with material shifts in BIS mandate scope, MFDS guideline expansion, and MicroLED display cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
US Pet Wearable Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Kids Watch Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market