
 Europe Watch Market | 2026-2036
Europe Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Watch Market Foresight
Asset-light licensing and consignment-based retail partnerships is tilting competitive dynamics toward brands that minimize fixed-capital exposure. Rolex leverages vertical integration across movement manufacturing to sustain margin control. Audemars Piguet anchors its position through limited-production complications and in-house calibers. Omega differentiates via co-axial escapement technology and deep sports sponsorship equity.
A watch is a portable timekeeping instrument comprising a mainspring or quartz oscillator, gear train, escapement, and balance wheel or tuning fork, housed in a case with crystal, dial, and hands or digital display, designed for personal wear and precise time measurement. Europe watch production emphasizes mechanical calibers with COSC chronometer certification tolerances of minus four to plus six seconds daily. Luxury analog segment commands the dominant margin pool, while smartwatches represent the fastest-expanding category as health-monitoring functionality penetrates mid-tier price bands. Stainless steel cases lead volume, though ceramic and precious metals capture premium positioning.
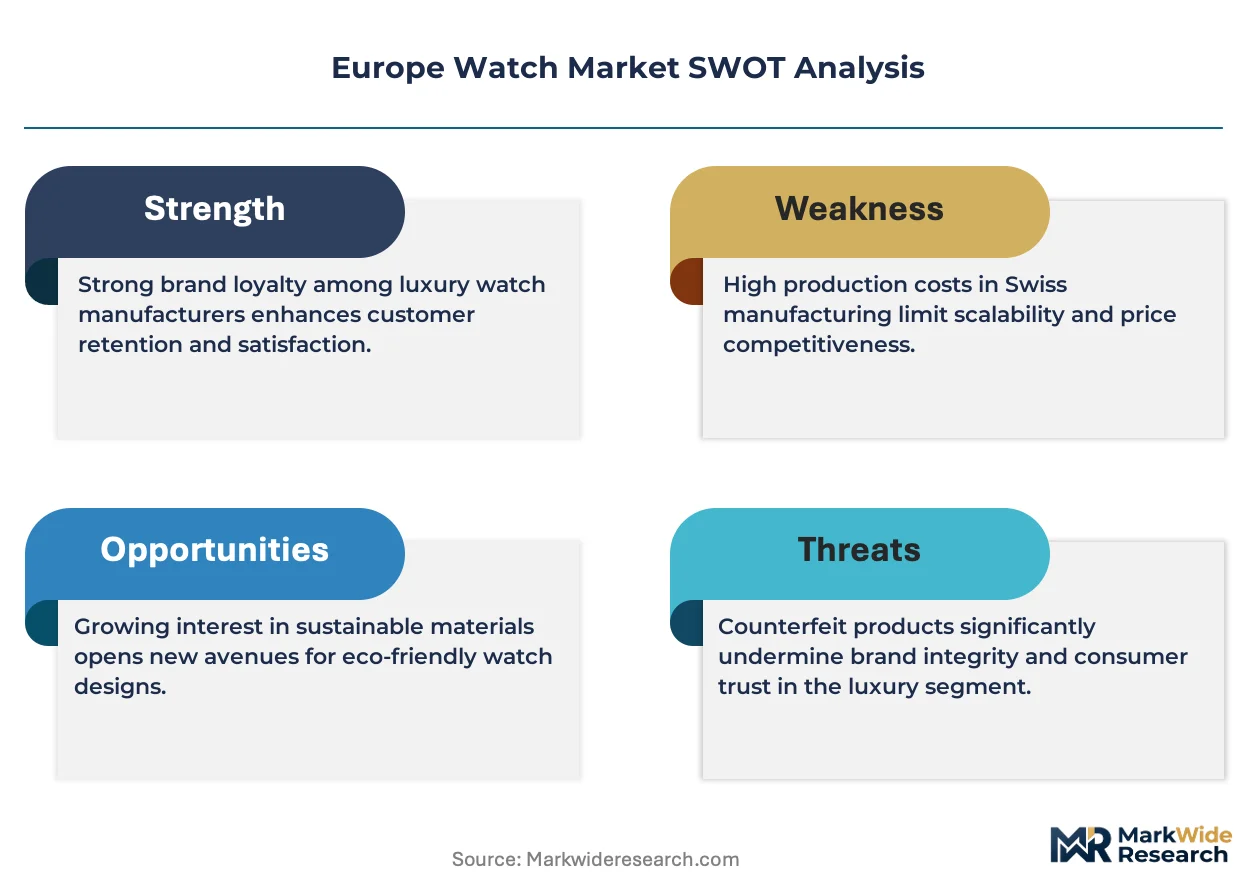
REACH restricts nickel release and chromium VI in watch cases and bracelets, compelling reformulation of stainless steel alloys and plating chemistries. CE marking under EU machinery directives governs smartwatch electrical safety and electromagnetic compatibility. ECHA substance evaluations increasingly target perfluorinated compounds in water-resistant gaskets and lubricants. Stakeholders must monitor evolving chemical restriction proposals and calibrate material substitution timelines against inventory cycles and supplier qualification periods.
Market Dynamics
REACH compliance deadlines and the EU Green Deal are forcing Swiss manufacturers to reformulate stainless steel alloys and leather tanning processes, restructuring supplier relationships across the Jura Arc watchmaking cluster.
Growth Catalysts
- EU Green Deal carbon neutrality targets:Manufacturers investing in renewable energy for Jura Arc production facilities gain preferential access to EU public procurement channels and green financing instruments.
- Health-monitoring functionality integration:Biometric sensors in mid-tier smartwatches attract fitness-conscious professionals who previously avoided traditional timepieces.
- Heritage craftsmanship scarcity:COSC chronometer certification programs in Switzerland create artificial supply constraints that sustain price premiums for mechanical calibers.
Market Restraints
- Nickel release restrictions under REACH:Reformulation of 316L stainless steel alloys increases raw material costs and extends supplier qualification timelines by months.
- Movement component concentration in Vallee de Joux:Dependency on a single Swiss valley for high-complication calibers creates vulnerability to weather disruptions and labor disputes.
- Smartwatch battery chemistry limitations:Energy density constraints in lithium-polymer cells restrict always-on display functionality to premium price tiers.
Strategic Opportunities
- Secondary market authentication services:Blockchain-based provenance tracking addresses collector concerns about counterfeit vintage pieces in France and Germany.
- Ceramic case manufacturing scale-up:Injection-molding expertise from medical device suppliers enables cost-competitive zirconium oxide production.
- CSRD sustainability reporting mandates:Early adopters of supply chain carbon accounting capture ESG-focused institutional buyers before compliance deadlines.
Industry Challenges
- Geneva Seal and Poincon de Geneve certification backlogs:Independent testing laboratories face capacity constraints that delay product launches.
- Perfluorinated compound substitution in gaskets:ECHA substance evaluations force rapid reformulation of water-resistant seals without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Watch Market |
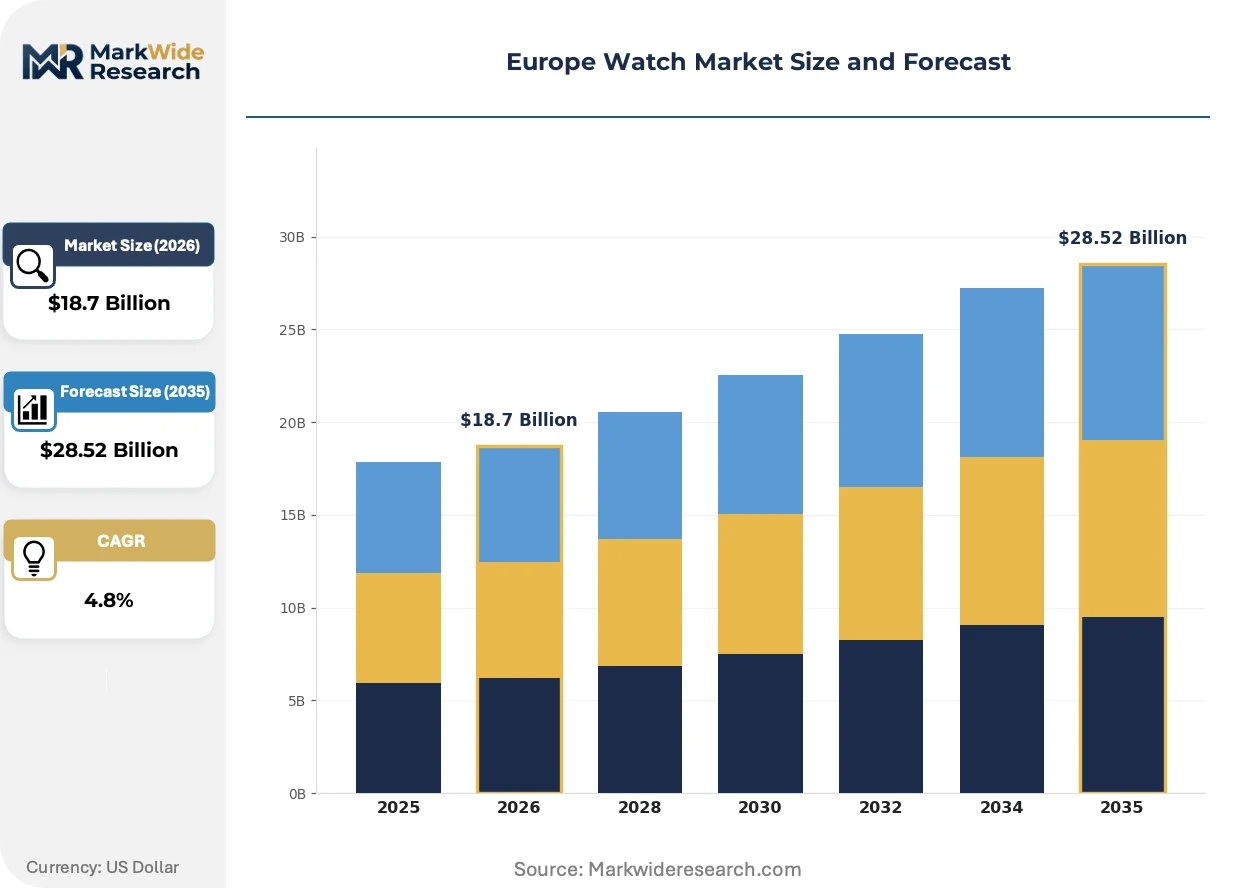
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smartwatches, Luxury Material: Stainless Steel, Leather, Ceramic, Plastic Distribution Channel: Online, Retail Stores, Boutiques, Distributors End User: Men, Women, Kids, Unisex |
| Companies Covered | Audemars Piguet, Breitling, Rolex, TAG Heuer, Vacheron Constantin, Cartier, Patek Philippe, IWC, Omega, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Watch Market Shifts & Advancements
Digital twin technology is virtualizing quality assurance workflows, compressing development cycles for new complications while regulatory pressure accelerates material substitution timelines.
Silicon escapement components are virtualizing the traditional balance wheel assembly, eliminating magnetic sensitivity and reducing service intervals. High-frequency mechanical movements from Grenchen and Le Locle manufacturers adopt silicon hairsprings at accelerating rates. This substitution is virtualizing the aftermarket service revenue model that sustained authorized dealers for decades.
REACH Annex XVII nickel release limits and chromium VI restrictions are compelling alloy reformulations across case and bracelet production. Swiss foundries must recertify 316L stainless steel variants under tighter ECHA substance evaluation protocols. Premium mechanical segments absorb compliance costs through price adjustments, while entry-level quartz lines face margin compression.
Collector preferences are fragmenting across authentication-dependent secondary channels, displacing traditional authorized dealer networks for vintage acquisitions. Online marketplaces with escrow verification services capture transaction volume from brick-and-mortar auction houses. This channel rotation concentrates in Germany and the United Kingdom where digital-native buyer demographics dominate.
Europe Watch Market Segmentation
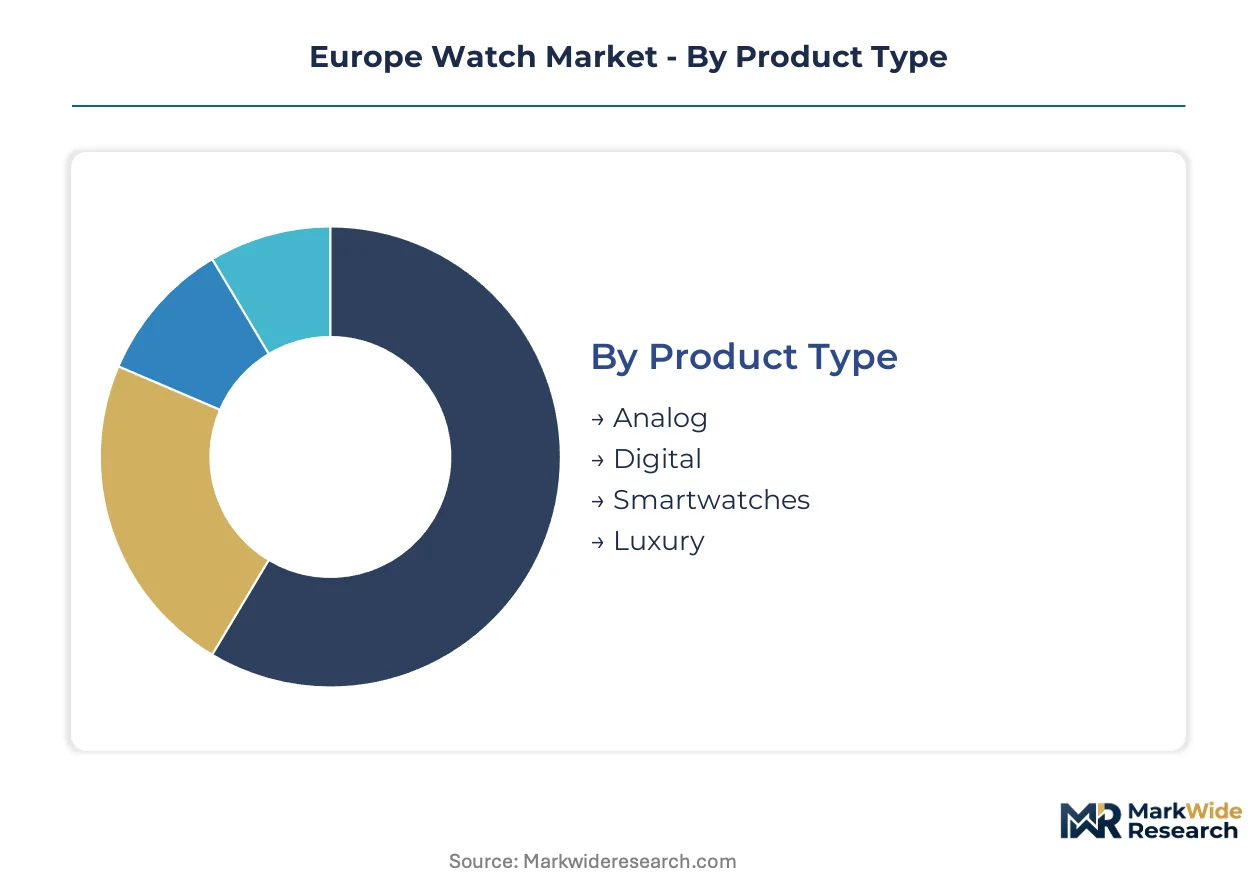
Segmentation in the Europe Watch Market reveals how COSC chronometer certification, REACH material compliance, and channel authentication requirements create divergent margin structures across product tiers. Understanding these fault lines helps manufacturers calibrate Jura Arc production capacity against shifting demand concentrations in Germany, France, and Switzerland.
Product Type:
Mature mechanical calibers coexist with emerging biometric sensor platforms across Swiss and German manufacturing bases.
- Analog:Mechanical movements with gear train, escapement, and balance wheel assemblies dominate Swiss Jura Arc output. Heritage collectors in France and Germany sustain demand for COSC-certified chronometers with minus four to plus six seconds daily tolerance, though silicon escapement components are displacing traditional hairsprings in Grenchen and Le Locle workshops.
- Smartwatches:Biometric sensor integration with lithium-polymer power management attracts fitness-conscious professionals who previously avoided traditional timepieces. Health-monitoring functionality penetration concentrates in mid-tier German and UK price bands where digital-native demographics dominate, constrained by battery chemistry limitations on always-on displays.
- Digital:Quartz oscillator and tuning fork architectures serve functional timekeeping needs with minimal service requirements.
- Luxury:Limited-production complications and in-house calibers command collector premiums through artificial supply constraints.
Analog retains volume leadership; smartwatches hold the steepest expansion curve.
Material:
Cost tier stratification separates REACH-compliant premium alloys from volume-oriented synthetic alternatives.
- Stainless Steel:316L alloy variants face REACH Annex XVII nickel release limits and chromium VI restrictions, forcing Swiss foundry recertification under ECHA protocols. Reformulation extends supplier qualification timelines by months, with premium mechanical segments absorbing compliance costs while entry-level quartz lines face margin compression.
- Ceramic:Zirconium oxide injection-molding enables scratch-resistant case production with medical device supplier expertise transfer. Cost-competitive scale-up potential concentrates in Swiss manufacturing clusters seeking differentiation from steel commoditization.
- Leather:Traditional tanning processes undergo EU Green Deal restructuring across Jura Arc strap suppliers.
- Plastic:Polymer cases serve children's and entry-tier segments with minimal regulatory exposure.
Stainless steel retains volume leadership; ceramic holds the steepest expansion curve.
Distribution Channel:
Customer authentication requirements are fragmenting transaction flows across digital and physical touchpoints.
- Online:Escrow verification services with blockchain-based provenance tracking capture vintage collector transactions from traditional auction houses. Channel rotation concentrates in Germany and the United Kingdom where digital-native buyer demographics dominate secondary market acquisitions.
- Boutiques:Authorized dealer networks sustain high-complication sales through in-person calibration and service relationships. Geneva Seal and Poincon de Geneve certification backlogs at independent testing laboratories create launch delays that reinforce boutique exclusivity.
- Retail Stores:Multi-brand physical presence serves mid-tier trial and gift purchase occasions.
- Distributors:Wholesale relationships penetrate price-sensitive Eastern European markets with reduced brand control.
Online channels gain share fastest; boutiques defend margin concentration.
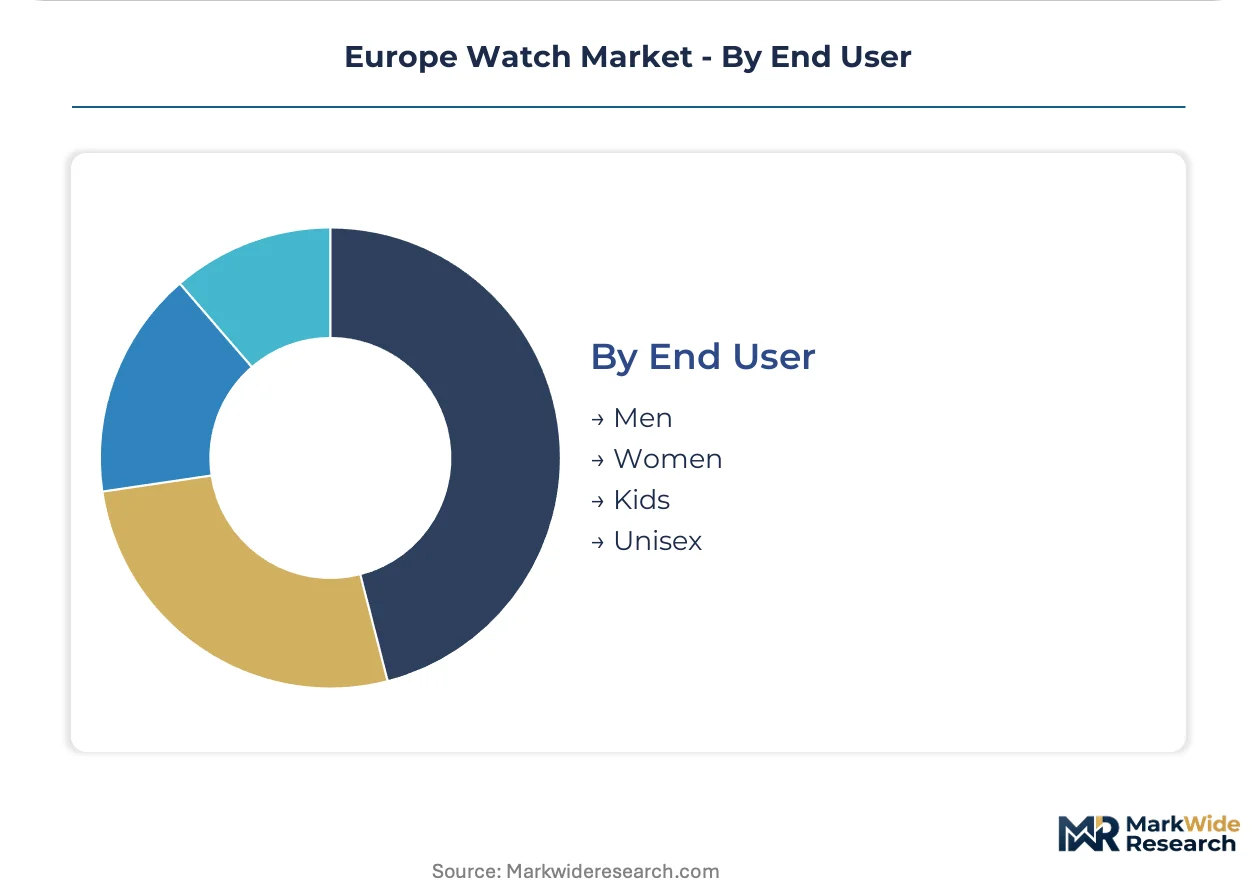
End User:
Application-driven design divergence separates professional tool-watch specifications from fashion-oriented aesthetics.
- Men:Sports sponsorship equity and complication density drive technical specification priorities. Swiss manufacturers target German and French professionals with co-axial escapement technology and deep athletic partnerships that signal engineering credibility.
- Women:Ceramic case adoption and smaller diameter mechanical movements expand beyond quartz-dominated historical positioning. CSRD sustainability reporting mandates attract ESG-focused institutional gifting programs in Northern European corporate procurement.
- Kids:Durability and educational positioning dominate plastic and digital segment targeting.
- Unisex:Neutral sizing and modular strap systems serve fragmented preference landscapes.
Men's segment retains volume leadership; women's holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across European watch markets reveal Switzerland's dominance in finished timepiece shipments, while Germany and France function as primary consumption hubs. Regulatory divergence around REACH compliance and EU Green Deal carbon accounting is reshaping cross-border supplier relationships.
Switzerland
Heritage collectors and institutional buyers drive demand for COSC-certified mechanical calibers. Swissmedic regulates medical-grade wearable interfaces, while ECHA substance evaluations target perfluorinated compounds in water-resistant gaskets. The Jura Arc watchmaking cluster concentrates precision engineering capacity, where silicon escapement adoption accelerates in Grenchen and Le Locle workshops.
Germany
Fitness-conscious professionals adopt biometric smartwatches with health-monitoring functionality. KBA compliance frameworks influence automotive-connected wearable specifications, while CE marking governs electromagnetic compatibility. Frankfurt and Munich anchor digital-native buyer demographics dominating secondary market authentication channels.
France
Fashion-conscious professionals sustain demand for ceramic case designs and smaller diameter mechanical movements. ANSM oversight extends to wearable health sensor data privacy, while EU AI Act provisions classify algorithmic fitness recommendations. Paris luxury retail corridors concentrate boutique exclusivity for high-complication acquisitions.
United Kingdom
Collector preferences fragment across blockchain-based provenance tracking platforms displacing traditional auction houses. Financial Conduct Authority guidelines intersect with wearable payment authentication standards. London digital marketplaces capture vintage transaction volume from brick-and-mortar channels.
Italy
ESG-focused institutional gifting programs drive ceramic and sustainably-tanned leather strap adoption. CSRD sustainability reporting mandates reshape corporate procurement criteria for Northern European buyers. Milan fashion-industry relationships influence unisex sizing and modular strap system development.
Europe Watch Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying movements, cases, and certified complications. The vendor base stratifies between vertically integrated heritage maisons and asset-light licensing operators minimizing fixed-capital exposure. Three archetypes dominate: chronometer-certified mechanical specialists, co-axial escapement technology holders, and biometric sensor platform integrators. Competitive moves concentrate on ceramic case manufacturing scale-up and blockchain-based secondary market authentication services.
Within the heritage manufacture tier, Audemars Piguet and Patek Philippe exemplify limited-production complication strategies anchored by in-house caliber development. Rolex occupies a position representing vertical integration across movement manufacturing and margin control architecture. Omega sits within the technology-differentiation vector, exemplifying co-axial escapement patent portfolios and sports sponsorship equity accumulation.
| Leading Market Players |
|---|
| Audemars Piguet |
| Breitling |
| Rolex |
| TAG Heuer |
| Vacheron Constantin |
| Cartier |
| Patek Philippe |
| IWC |
| Omega |
| Others |
Supply & Pricing Matrix
The Jura Arc watchmaking cluster concentrates precision engineering capacity that feeds downstream pricing power across European distribution channels. REACH compliance deadlines and EU Green Deal carbon accounting reshape alloy sourcing economics, forcing Swiss foundries to recertify 316L stainless steel variants under tighter ECHA protocols.
Pricing Analysis
Heritage collectors anchor a three-tier pricing structure across premium, standard, and economy levels, with COSC chronometer certification and silicon escapement adoption as primary differentiation drivers. Pricing pressure stems from nickel release restrictions compelling stainless steel reformulation, with entry-level quartz lines absorbing margin compression while premium mechanical segments pass compliance costs through price adjustments. Digital-native demographics in Germany and the United Kingdom exhibit lowest price sensitivity for blockchain-authenticated vintage acquisitions.
Supply Chain Analysis
Extended payment terms from Swiss movement manufacturers to Vallee de Joux component suppliers stabilize working capital across the Jura Arc production network. Geographic supply concentration centers on Switzerland for high-complication calibers, Germany for biometric sensor platforms, and France for ceramic case finishing. Raw material dependencies include lithium-polymer cells for smartwatch power management, zirconium oxide for ceramic injection-molding, and REACH-compliant leather tanning extracts. Single-source vulnerability in Vallee de Joux movement component concentration creates exposure to weather disruptions and labor disputes. Distribution runs through authorized dealer boutiques for high-complication sales, online escrow platforms for secondary market vintage transactions, and multi-brand retail for mid-tier trial purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical timepiece incumbents face substitution defense against biometric smartwatch platforms penetrating fitness-conscious professional segments. The report frames strategic positioning around material compliance, channel authentication, and silicon escapement adoption as differentiation levers.
For Market Incumbents: Harden supply chain resilience through backward integration into ceramic case manufacturing and captive silicon hairspring production in Grenchen workshops. Secure Geneva Seal certification capacity through independent laboratory partnerships to preempt launch delays. These moves counter smartwatch battery chemistry improvements threatening mid-tier mechanical volume.
For New Entrants and Emerging Players: Eastern European distributor relationships present white-space targeting for price-sensitive quartz segments underserved by heritage maisons. Blockchain-based provenance tracking platforms in the United Kingdom offer acquisition angles for vintage authentication services. Direct-to-collector online channels bypass boutique exclusivity constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a scarcity-premium play because COSC-certified mechanical caliber production capacity remains artificially constrained by heritage craftsmanship training pipelines. Acquisition targets include ceramic injection-molding specialists with medical device expertise transfer and secondary market authentication platforms with escrow verification infrastructure. The signal to watch is ECHA substance evaluation acceleration forcing perfluorinated compound substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Case Manufacturing Scale-Up | Zirconium oxide injection-molding from medical device suppliers enables scratch-resistant differentiation from steel commoditization. |
| Blockchain Provenance Tracking Launch | Escrow verification services capture vintage collector transactions displacing traditional auction house channels. |
| Silicon Escapement Component Integration | Grenchen and Le Locle workshops adopt silicon hairsprings eliminating magnetic sensitivity and reducing service intervals. |
| REACH-Compliant Alloy Reformulation | Swiss foundries recertify 316L stainless steel under ECHA protocols to maintain EU market access. |
| CSRD Sustainability Reporting Adoption | Early supply chain carbon accounting captures ESG-focused institutional buyers before compliance deadlines. |
Research Methodology
A spread of perspectives from heritage manufacture executives, Jura Arc component suppliers, boutique retail operators, and secondary market platform founders converged on the working assumptions. Primary fieldwork combined with secondary validation from Swiss customs export data, ECHA substance evaluation filings, COSC certification records, and EU Green Deal procurement disclosures. Bottom-up production capacity estimates triangulated against top-down consumption surveys across Germany, France, and Switzerland.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, material compliance tier, distribution channel, and end-user demographic. CAGRs derived from production volume trajectories, price elasticity estimates, and substitution rate assumptions for smartwatch platforms. Industry-specific forecast inputs incorporated REACH Annex XVII amendment timelines and CSRD reporting mandate phase-ins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology platform integrators or asset-light licensing operators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Global Smart Ring Market