
 Consumer Grade Smart Wearable Device Market | 2026-2036
Consumer Grade Smart Wearable Device Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Grade Smart Wearable Device Market Insights
Fitness enthusiasts is unwinding as the dominant buyer archetype while health-conscious consumers gain share in wearable purchasing decisions. Apple leverages vertical integration across silicon, software, and health sensors to sustain premium positioning. Samsung Electronics anchors its wearable lineup through deep Android ecosystem ties and multi-device interoperability. Xiaomi Corporation competes on manufacturing scale, driving cost-efficient fitness trackers into mass-market channels across Asia.
Consumer grade smart wearable devices encompass wrist-worn, head-mounted, and body-attached electronics incorporating accelerometers, photoplethysmography sensors, and low-power Bluetooth SoCs to capture biometric data and enable wireless connectivity. These devices serve commercial purposes spanning fitness quantification, chronic health monitoring, and contextual notification delivery. Smartwatches lead value generation through higher average selling prices and recurring subscription services, while fitness trackers dominate unit volumes in emerging economies. Health monitors represent the fastest-expanding category as regulatory clearances blur the boundary between wellness and medical-grade monitoring.
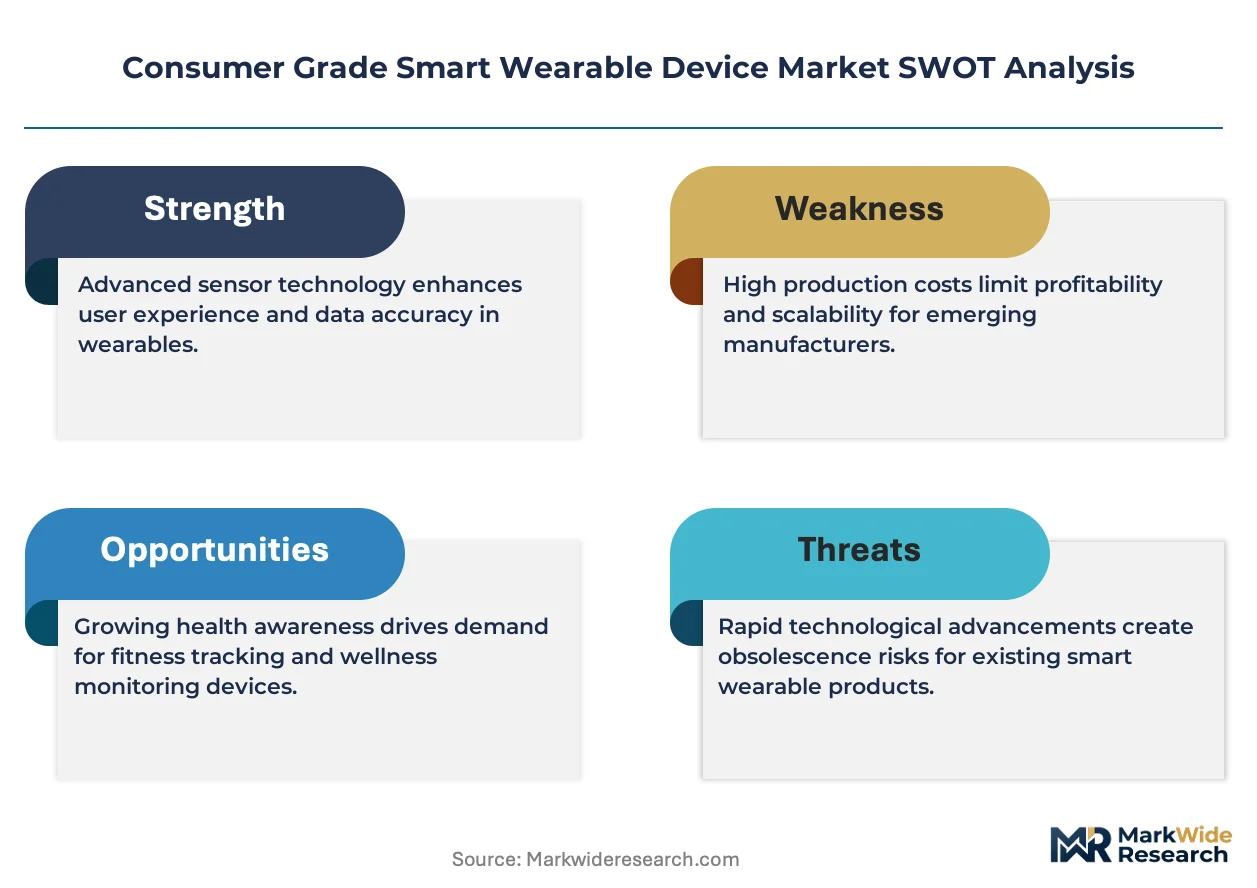
FDA 510(k) pathways and EU MDR classification rules determine whether wearable health features qualify as medical devices, directly shaping R&D investment and commercialization timelines. FCC radio equipment authorization and GDPR health data processing requirements impose additional compliance layers on connectivity architecture and cloud data handling. Stakeholders must monitor evolving regulatory boundaries between wellness and medical claims to anticipate which sensor modalities unlock reimbursement-accessible market segments.
Market Dynamics
FDA 510(k) clearance timelines for glucose-monitoring features are compressing product development cycles and forcing wearable OEMs to restructure clinical validation budgets. The convergence of wellness and medical-grade claims is redrawing competitive boundaries across the value chain.
Growth Catalysts
- EU MDR Class IIa Pathways:Regulatory clarity for continuous glucose monitoring wearables is unlocking reimbursement channels in Germany and accelerating hospital procurement pilots.
- Photoplethysmography Sensor Miniaturization:Blood oxygen and blood pressure estimation without cuff inflation is expanding addressable populations for hypertension management in aging demographics.
- China NMPA Green Channel:Expedited review for AI-enabled diagnostic features is attracting R&D investment toward algorithm-driven health alerts.
Market Restraints
- Lithium-Polymer Cell Volatility:Battery chemistry cost swings and cobalt supply concentration in the Democratic Republic of Congo squeeze margin predictability for mid-tier manufacturers.
- GDPR Health Data Processing:Cross-border cloud synchronization restrictions impose architectural complexity on wearable-to-smartphone data pipelines, lengthening time-to-market for European launches.
- Smartphone Tethering Dependency:Persistent requirement for companion apps limits standalone functionality in markets with low smartphone penetration, constraining rural addressability.
Strategic Opportunities
- India Preventive Health Stack:Integration with Ayushman Bharat digital health records creates a channel for subsidized chronic disease monitoring in tier-2 and tier-3 cities.
- Non-Invasive Glucose Optical Spectroscopy:Convergence of near-infrared sensing with machine learning inference is approaching clinical-grade accuracy without finger-prick calibration.
- Specialty Retail Clinics:CVS MinuteClinic and Walgreens Health Corner formats are creating assisted-sales environments where staff guide device selection and onboarding.
Industry Challenges
- Firmware-Validated Clinical Algorithms:Recruiting biomedical engineers capable of translating raw PPG signals into FDA-submittable efficacy data remains constrained against Big Tech compensation benchmarks.
- ISO 14155 Clinical Investigation Timelines:Prospective studies for arrhythmia detection features require 12-18 month enrollment periods that misalign with annual hardware refresh cycles.
- Interoperability with Hospital EMR Systems:HL7 FHIR integration demands bespoke engineering for each health network, fragmenting deployment economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Grade Smart Wearable Device Market |
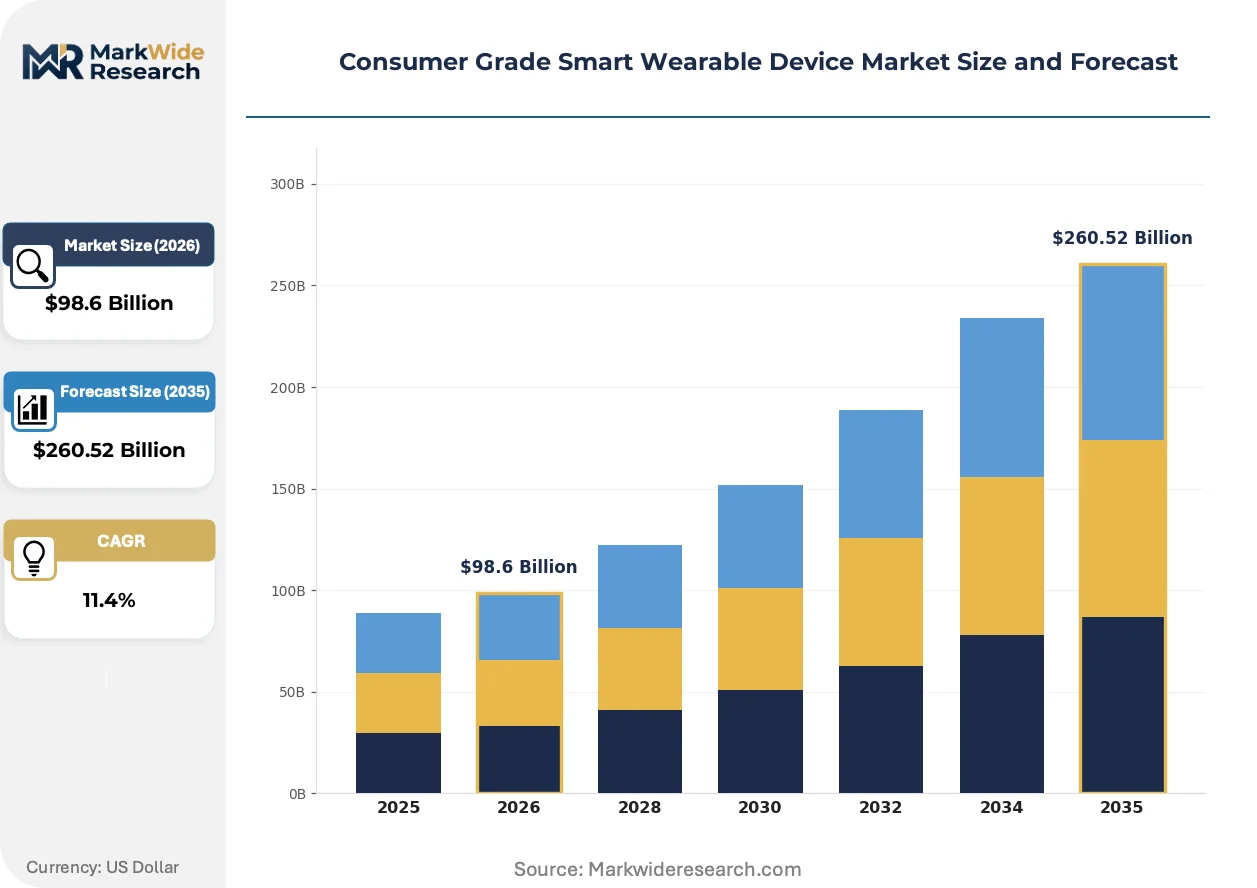
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $260.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Technology: Bluetooth, NFC, GPS, Wi-Fi End User: Fitness Enthusiasts, Health Conscious Consumers, Tech Savvy Individuals, Casual Users Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Mass Merchants |
| Companies Covered | Apple, Samsung Electronics, Garmin, Fitbit, Huawei Technologies, Xiaomi Corporation, Google, Amazfit, Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Grade Smart Wearable Device Market Trends and Innovations
Silicon architecture is fragmenting into specialized health-sensor subsystems that bypass general-purpose application processors. This decomposition is compressing power budgets and enabling multi-day battery life in compact form factors.
Photoplethysmography signal processing is decomposing from centralized smartphone apps into on-device neural accelerators. Apple and Samsung are migrating arrhythmia classification inference to wearable SoCs, reducing latency for critical alerts. This shift is compressing cloud dependency and enabling offline operation in connectivity-constrained environments.
EU MDR Article 120 transition deadlines are forcing wearable OEMs to reclassify borderline devices before 2028. Manufacturers with glucose-monitoring features face notified body queue congestion, compressing launch windows for second-generation sensors. Germany's BfArM early engagement pilot is attracting pre-submission activity from Asian suppliers seeking European market entry.
Employer-sponsored wellness programs are displacing direct-to-consumer channels for enterprise wearable deployments. Large self-insured employers in the United States are negotiating volume contracts with Fitbit and Garmin for metabolic health monitoring. This procurement consolidation is visible most acutely in the manufacturing and logistics verticals where shift workers represent concentrated risk pools.
Consumer Grade Smart Wearable Device Market Segmentation
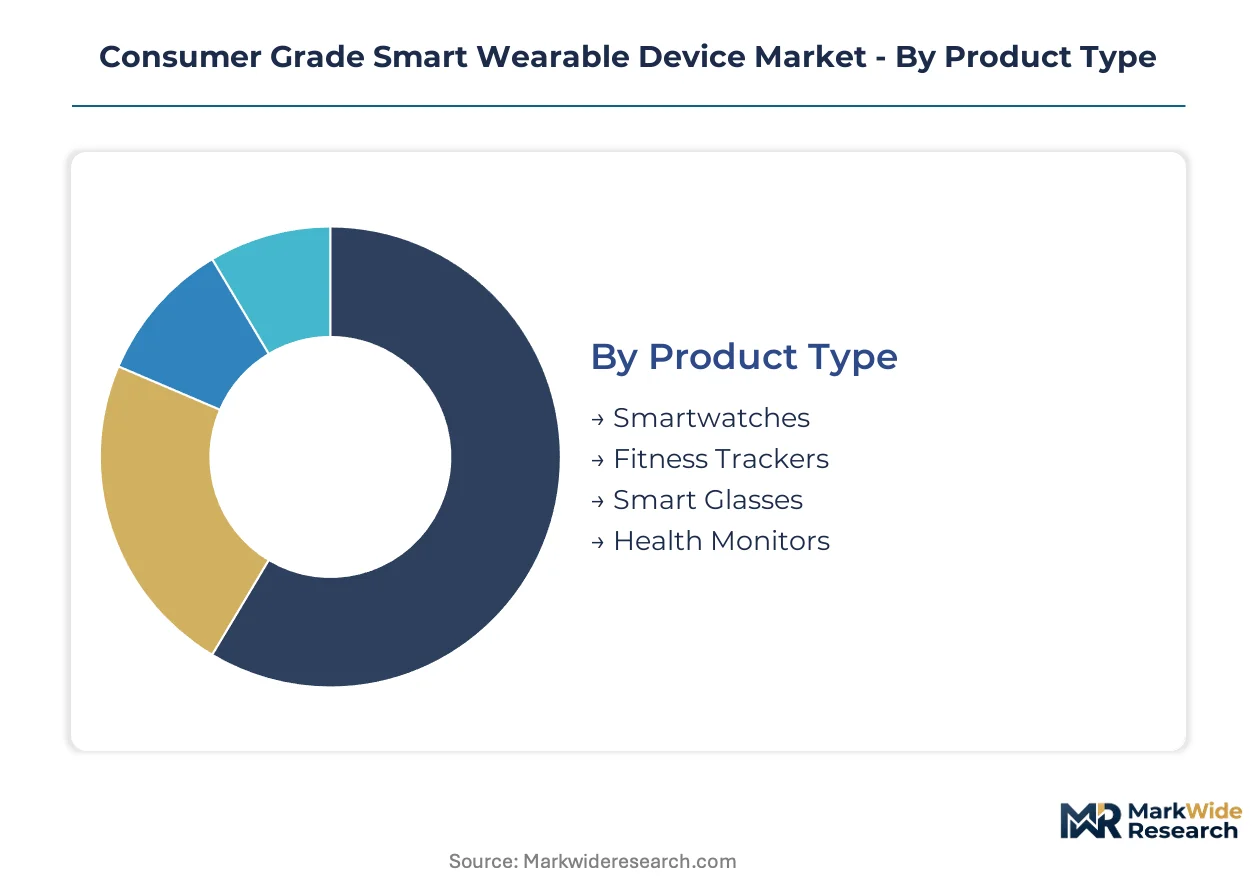
Segmentation in consumer wearables reveals how hardware specifications, connectivity protocols, and purchasing channels fragment addressable populations. Each dimension carries distinct margin profiles and regulatory exposure that reshape go-to-market economics.
Product Type:
Smartwatches and fitness trackers anchor domestic demand in the United States and China, while health monitors increasingly target export-led hospital procurement in Germany and reimbursement channels across Europe.
- Smartwatches:These wrist-worn devices integrate application processors, AMOLED displays, and multi-sensor arrays for notification management and biometric tracking. Demand concentrates among health-conscious consumers in the United States willing to pay premium prices for FDA-cleared ECG features. Apple's vertical control over silicon and software sustains margin leadership against Android competitors.
- Fitness Trackers:Stripped-down accelerometer and PPG sensor packages deliver step counting and sleep staging at sub-$50 price points. Volume demand clusters in China's tier-2 cities and India's mass-market channels where Xiaomi's manufacturing scale compresses unit economics. Battery life extending 10-14 days addresses rural connectivity gaps.
- Smart Glasses:Optical waveguide and micro-LED projection systems enable heads-up notification display and contextual AR overlays. Enterprise pilot programs in Germany's manufacturing sector are testing assisted-workflow applications before consumer scaling.
- Health Monitors:Dedicated continuous glucose monitoring patches and cuffless blood pressure wearables bypass smartphone tethering through embedded cellular modems. EU MDR Class IIa clearance pathways in Germany are unlocking prescription channels for aging populations with chronic conditions.
Smartwatches command the established base. The steepest expansion runs through health monitors.
Technology:
Connectivity protocol selection determines power budgets, data throughput, and interoperability with hospital IT infrastructure across deployment geographies.
- Bluetooth:Low-energy 5.3 specifications dominate wrist-worn device connectivity, enabling sub-10mW idle states that preserve multi-day battery life. FCC Part 15 certification requirements add 6-8 weeks to United States launch timelines.
- NFC:Near-field communication supports contactless payments and medical device pairing in European markets where EMVCo compliance is mandatory. Germany's transit authorities are integrating wearable transit credentials.
- GPS:Multi-constellation positioning (GPS, GLONASS, BeiDou) enables route tracking without smartphone tethering for outdoor fitness segments in the United States and China.
- Wi-Fi:802.11ax direct-to-cloud synchronization bypasses smartphone dependency for health data upload, critical for standalone health monitors targeting elderly users with limited mobile literacy.
Bluetooth anchors unit volumes across all product types. Wi-Fi is gaining share fastest in medical-adjacent segments requiring autonomous data pipelines.
End User:
Buyer archetypes fragment across motivation intensity, technical sophistication, and price sensitivity—each demanding differentiated feature packaging and channel strategy.
- Fitness Enthusiasts:Performance-oriented users demand VO2 max estimation, lactate threshold detection, and structured workout analytics. Garmin and Polar dominate this segment in Germany's endurance sports culture.
- Health Conscious Consumers:Preventive health motivation drives adoption of sleep apnea screening and atrial fibrillation detection. United States employer wellness programs are consolidating procurement for this segment in manufacturing and logistics verticals.
- Tech Savvy Individuals:Early adopters prioritize third-party application ecosystems and seamless multi-device interoperability within Apple or Samsung environments.
- Casual Users:Notification mirroring and basic activity tracking satisfy minimal engagement patterns. China's ODM manufacturers serve this price-sensitive population through white-label fitness bands.
Health conscious consumers are displacing fitness enthusiasts as the primary growth vector. Casual users represent the largest installed base but lowest lifetime value.
Distribution Channel:
Channel selection shapes customer acquisition costs, return rates, and onboarding support intensity—particularly critical for medical-featured devices requiring explanation.
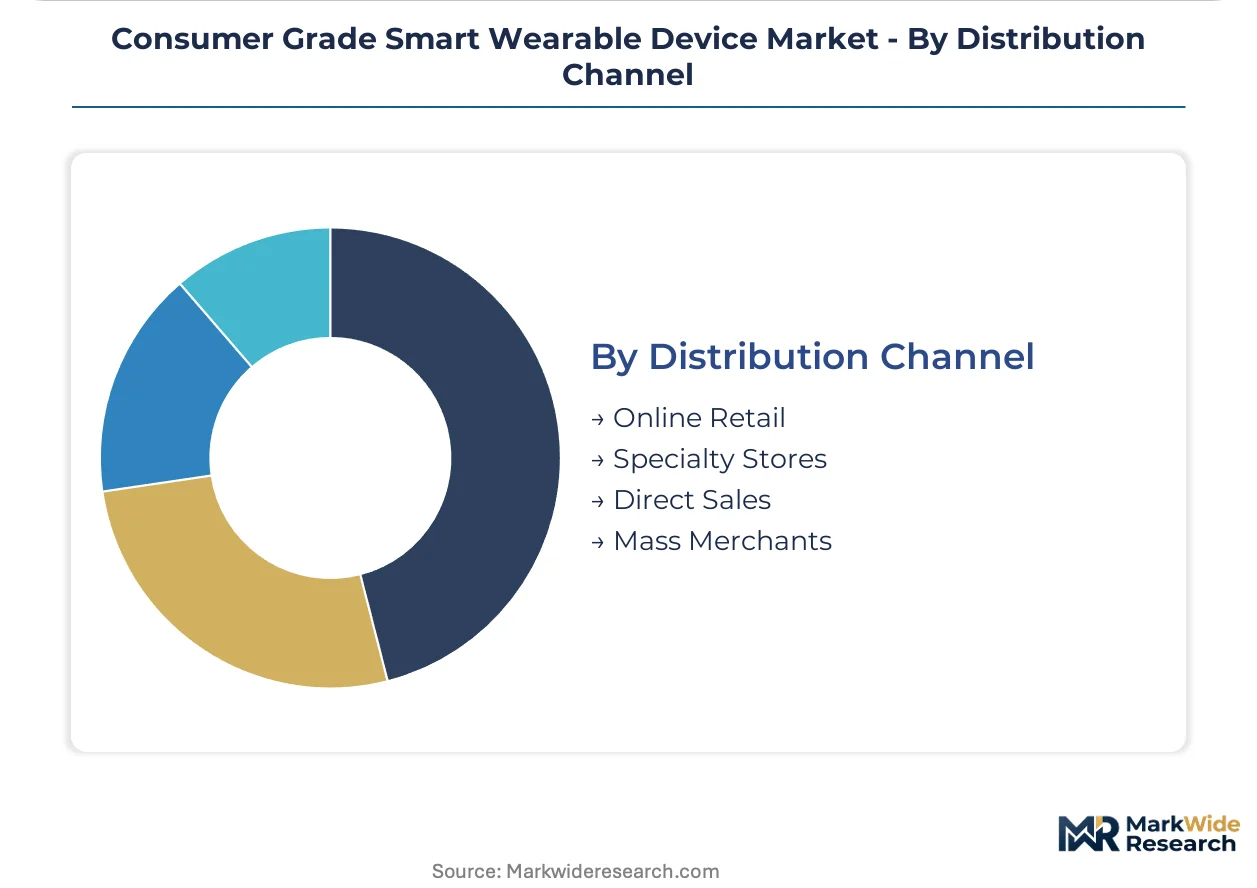
- Online Retail:Amazon and Tmall capture the majority of fitness tracker volumes in China and the United States, though return rates exceed 15% for health monitors due to sizing and skin irritation issues.
- Specialty Stores:Best Buy and Suning provide hands-on demonstration and technical support, commanding premium shelf placement fees that favor established brands with marketing development funds.
- Direct Sales:Apple's retail network and Samsung's experience stores enable controlled positioning and immediate technical support, justifying 30-40% gross margins.
- Mass Merchants:Walmart and Carrefour distribute entry-level fitness trackers in the United States and Europe, where impulse purchases and gift-giving drive seasonal volume spikes.
Online retail captures volume leadership in fitness trackers. Specialty stores are expanding fastest for health monitors requiring assisted onboarding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export wearable subassemblies to assembly plants in Vietnam and India, while finished devices from Shenzhen and Cupertino flow into German and United States retail channels. This trade architecture concentrates value capture in coastal manufacturing clusters and premium consumer markets.
United States
Employer-sponsored wellness programs drive bulk procurement of metabolic health monitors for manufacturing and logistics workforces. FDA 510(k) clearance timelines for glucose-monitoring features compress product development cycles for Silicon Valley hardware teams. Austin and Boston harbor medical-device startups navigating clinical validation partnerships with Texas Medical Center and Massachusetts General Hospital.
Germany
Aging demographics with chronic hypertension sustain demand for cuffless blood pressure wearables. EU MDR Class IIa pathways unlock prescription channels through BfArM early engagement pilots. Munich and Stuttgart anchor automotive supplier diversification into industrial-grade wearable sensors for factory-floor worker safety.
China
Mass-market fitness tracker volumes concentrate in tier-2 cities where Xiaomi's manufacturing scale dominates. NMPA Green Channel expedited review attracts algorithm-driven health alert R&D toward Shenzhen and Hangzhou. Yangtze River Delta assembly plants supply Bluetooth SoCs and PPG sensor modules to global OEMs.
India
Ayushman Bharat digital health record integration creates subsidized channels for chronic disease monitoring in tier-2 and tier-3 cities. BIS certification requirements for wireless devices extend launch timelines for imported wearables. Bangalore and Hyderabad host software development centers optimizing wearable firmware for low-bandwidth rural connectivity.
South Korea
Multi-device ecosystem loyalty sustains premium smartwatch replacement cycles in Seoul and Busan. MFDS medical device classification rules determine reimbursement eligibility for arrhythmia detection features. Pangyo Techno Valley clusters health-AI startups migrating inference workloads onto wearable neural accelerators.
Consumer Grade Smart Wearable Device Market Competitive Landscape
Player mix skews toward vertically integrated technology conglomerates with captive silicon and software stacks. Three tiers structure competitive positioning: premium ecosystem orchestrators commanding 30-40% gross margins, scale-driven mass-market suppliers competing on manufacturing efficiency, and specialized performance analytics vendors serving endurance sports niches. Dominant competitive moves include backward integration into custom sensor silicon and strategic partnerships with hospital networks for EMR interoperability.
Within the premium ecosystem tier, Apple and Samsung Electronics exemplify vertical control architectures that bind hardware, operating system, and health cloud into unified experiences. Xiaomi Corporation occupies a scale-driven position compressing unit economics for entry-level fitness bands across Asian mass-market channels. Garmin represents the specialized performance analytics archetype, anchoring endurance sports segments where VO2 max estimation and lactate threshold algorithms justify premium pricing.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Garmin |
| Fitbit |
| Huawei Technologies |
| Xiaomi Corporation |
| Amazfit |
| Polar Electro |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts for Bluetooth SoCs and PPG sensor modules lock in supply access for tier-1 OEMs while compressing price visibility for mid-tier manufacturers dependent on spot-market silicon. This contract-structure asymmetry concentrates margin protection among vertically integrated players with captive foundry relationships.
Pricing Analysis
Current-generation smartwatch SoCs with on-device neural accelerators command 40-60% premiums over prior-generation application processors, while next-generation non-invasive glucose optical spectroscopy modules carry pre-certification pricing premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared ECG features from wellness-grade heart rate monitoring and basic step-counting fitness bands. Cost compression in entry-level fitness trackers stems from Xiaomi's manufacturing scale and white-label ODM competition. Casual users in India's tier-3 cities exhibit highest price sensitivity, while health-conscious consumers in the United States demonstrate lowest elasticity for medical-adjacent features.
Supply Chain Analysis
Port congestion on Shenzhen-to-Long Beach trade lanes elevates inbound logistics costs for finished wearables, compressing margin buffers for brands without regional assembly footprints. Component manufacturing concentrates in China, South Korea, and Taiwan, with Yangtze River Delta facilities producing Bluetooth SoCs and PPG sensor modules. Raw material dependencies include lithium-polymer cells, cobalt cathode materials, and AMOLED display substrates. Single-source vulnerability in cobalt supply from the Democratic Republic of Congo exposes battery cost volatility. Distribution runs through direct-to-consumer online channels, specialty retail clinics, and enterprise wellness procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native health applications and hospital-issued medical devices present substitution threats that wearable incumbents must neutralize through clinical-grade feature differentiation and EMR interoperability.
For Market Incumbents: Compound ecosystem stickiness through backward integration into custom sensor silicon and exclusive partnerships with hospital networks for HL7 FHIR integration. FDA 510(k) clearance timelines compress competitive windows, making early clinical validation investment the critical defensive lever against emerging optical spectroscopy entrants. For New Entrants and Emerging Players: Anchor in India's Ayushman Bharat-integrated preventive health stack, where subsidized chronic disease monitoring in tier-2 cities offers lowest competitive density. Non-invasive glucose monitoring without finger-prick calibration represents the most penetrable white-space segment. Pursue assisted-sales partnerships with CVS MinuteClinic and Walgreens Health Corner formats to overcome onboarding friction. For Investors and Strategic Acquirers: Health-AI startups with on-device inference capabilities and notified body relationships for EU MDR Class IIa pathways represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory clearance moats rather than hardware refresh cycles. Watch for BfArM early engagement pilot participation as inflection signal for European market entry readiness.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks reimbursement channels and prescription-grade pricing premiums for glucose-monitoring features. |
| EU MDR Class IIa Certification | Enables hospital procurement pilots in Germany and accelerates notified body queue navigation. |
| Hospital EMR System Partnership | HL7 FHIR integration with Texas Medical Center and Massachusetts General Hospital creates switching costs. |
| Custom Sensor Silicon Development | Apple's vertical control over photoplethysmography subsystems sustains multi-day battery life advantages. |
| Employer Wellness Program Contract | Volume agreements with manufacturing and logistics verticals displace direct-to-consumer acquisition costs. |
Research Methodology
Cross-validation between primary interviews with wearable OEM product managers, biomedical engineers, and hospital GPO contracts managers and secondary validation through FDA 510(k) filings, EU MDR notified body databases, and NMPA Green Channel announcements anchors the qualitative findings. Bottom-up triangulation of component bill-of-materials and top-down reconciliation against employer wellness program procurement disclosures ensures methodological rigor.
Sensitivity analysis across the projection horizon tests demand elasticity for medical-adjacent features against smartphone tethering dependency and regulatory clearance timelines. Segmentation dimensions modeled include product type, connectivity protocol, buyer archetype motivation intensity, and regional reimbursement framework. CAGRs derive from hardware refresh cycle analysis and clinical validation pipeline progression. Forecast inputs incorporate lithium-polymer cell cost trajectories and cobalt supply concentration risk.
Material uncertainties — FDA enforcement discretion shifts, EU MDR Article 120 transition deadline extensions, and NMPA algorithm approval reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway velocity and clinical evidence standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Electronics Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Middle East and Africa Smartwatch Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Wearable AI Devices Market