
 Global Wearable Materials Market | 2026-2036
Global Wearable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Materials Market Foresight
Asian silicone elastomer producers is rebalancing supply chains after pandemic-era shortages disrupted component flows. BASF SE leverages its polymer research network to sustain leadership in thermoplastic polyurethane formulations for fitness trackers. DuPont de Nemours anchors North American supply through specialized fluoropolymer films that enable sweat-resistant device seals. Covestro AG competes on optical-grade polycarbonate for virtual reality headsets, where clarity and impact resistance prove critical.
Wearable materials encompass engineered polymers, conductive textiles, and elastomeric compounds formulated for skin-contact electronics and sensor-integrated garments. Thermoplastic polyurethane dominates flexible film production due to its Shore hardness range of 70A–85D and resistance to abrasion across repeated flex cycles. Silicone elastomers lead medical monitoring applications where ISO 10993 biocompatibility certification determines market access, while graphene sheets represent the fastest-expanding segment for next-generation conductive pathways in smart textiles. Fitness trackers and military gear applications split the volume base between consumer scale and premium performance specifications.
FDA biocompatibility standards and EU MDR compliance requirements shape material selection timelines for any skin-contact wearable sold in the United States or European Economic Area. China's NMPA and GB standards add a third certification layer for brands accessing domestic manufacturing or consumer markets. REACH substance restrictions and California Proposition 65 disclosure rules further constrain formulation choices for phthalates and residual monomers. Stakeholders must track evolving chemical disclosure mandates across multiple jurisdictions to avoid supply disqualification.
Market Dynamics
The wearable materials market contends with tightening biocompatibility certification timelines as FDA and EU MDR standards force reformulation cycles before products reach commercial scale.
Growth Catalysts
- ISO 10993 biocompatibility mandates:Medical-grade silicone elastomers command premium positioning as healthcare providers integrate continuous glucose monitors and cardiac wearables into standard care protocols.
- China's domestic electronics ecosystem:Shenzhen and Dongguan manufacturing clusters scale TPU film production for fitness tracker bands, compressing component lead times for global brands.
- Graphene conductive textiles:Next-generation sensor pathways enable washable smart garments with signal integrity matching rigid PCB alternatives.
Market Restraints
- Petrochemical input volatility:Polyether polyol and diisocyanate price swings destabilize TPU compound costing models for mid-volume converters.
- Asian silicone concentration:Over 70% of medical-grade elastomer supply originates from Jiangsu and Zhejiang provinces, creating single-source vulnerability for FDA-certified formulations.
- Fluoropolymer technical ceiling:PTFE and FEP films face thickness limitations below 25 microns for breathable yet liquid-tight device seals.
Strategic Opportunities
- India's PLI scheme for electronics:Component material suppliers can anchor local production for wearable assembly operations shifting from China.
- EU Green Deal chemical substitution:Bio-based polyol feedstocks gain regulatory preference for REACH-compliant TPU formulations targeting European consumer markets.
- Direct-to-consumer optical retail:VR headset manufacturers bypass traditional electronics distributors, creating specification partnerships with polycarbonate lens molders.
Industry Challenges
- Multi-jurisdiction certification sequencing:Brands must synchronize FDA 510(k), EU MDR technical documentation, and China NMPA registration without delaying unified product launches.
- Specialized polymer compounding talent:Formulation chemists with both medical biocompatibility and consumer electronics durability experience command scarcity premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Materials Market |
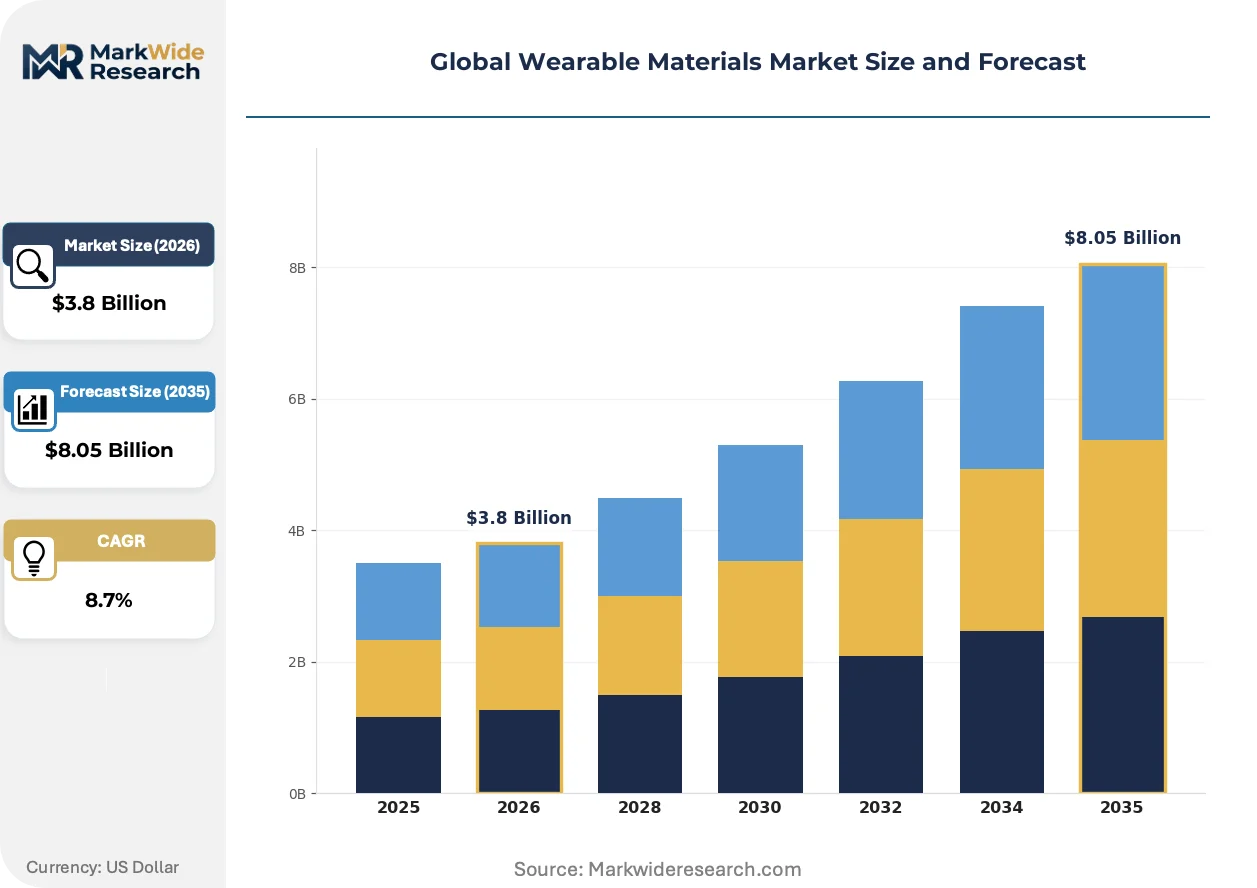
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Conductive Fibers, Thermoplastic Polyurethane, Silicone Elastomers, Shape Memory Polymers, Graphene Sheets Application: Fitness Trackers, Smart Textiles, Medical Monitoring, Virtual Reality Devices, Military Gear End User: Sports Enthusiasts, Healthcare Providers, Defense Agencies, Entertainment Companies, Research Institutes Form Factor: Flexible Films, Sheets, Coatings, Knit Fabrics, Composite Layers |
| Companies Covered | BASF SE, DuPont de Nemours, Wacker Chemie AG, Arkema S.A., Covestro AG, The Lubrizol Corporation, DSM, Momentive Performance Materials, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Materials Market Shifts & Advancements
Material science advances are compressing the performance gap between rigid electronics and conformable wearables, while regulatory chemistry mandates force substitution timelines faster than traditional reformulation cycles.
Printed graphene interconnects is decentralizing conductive pathway production away from copper-etch PCB fabrication. Sports apparel brands adopt screen-printed sensor grids for biometric jerseys at pilot scale. The shift enables regional textile converters to capture value previously concentrated in Asian rigid circuit board facilities.
EU MDR Annex I general safety and performance requirements now mandate clinical evidence for all skin-contact materials, not just implantables. Device manufacturers face 12-18 month documentation extensions for legacy silicone formulations. German notified bodies report 40% capacity expansion to manage backlog, compressing approval timelines for prepared submitters.
Hospital procurement coalitions now specify ISO 10993-5 cytotoxicity and ISO 10993-10 irritation testing as table stakes for wearable tenders, displacing supplier-declared biocompatibility. Materials vendors without certified third-party documentation exit consideration regardless of price position. The pattern concentrates contract awards among compounders with captive toxicology testing infrastructure, visible in US health system purchasing agreements.
Global Wearable Materials Market Segmentation
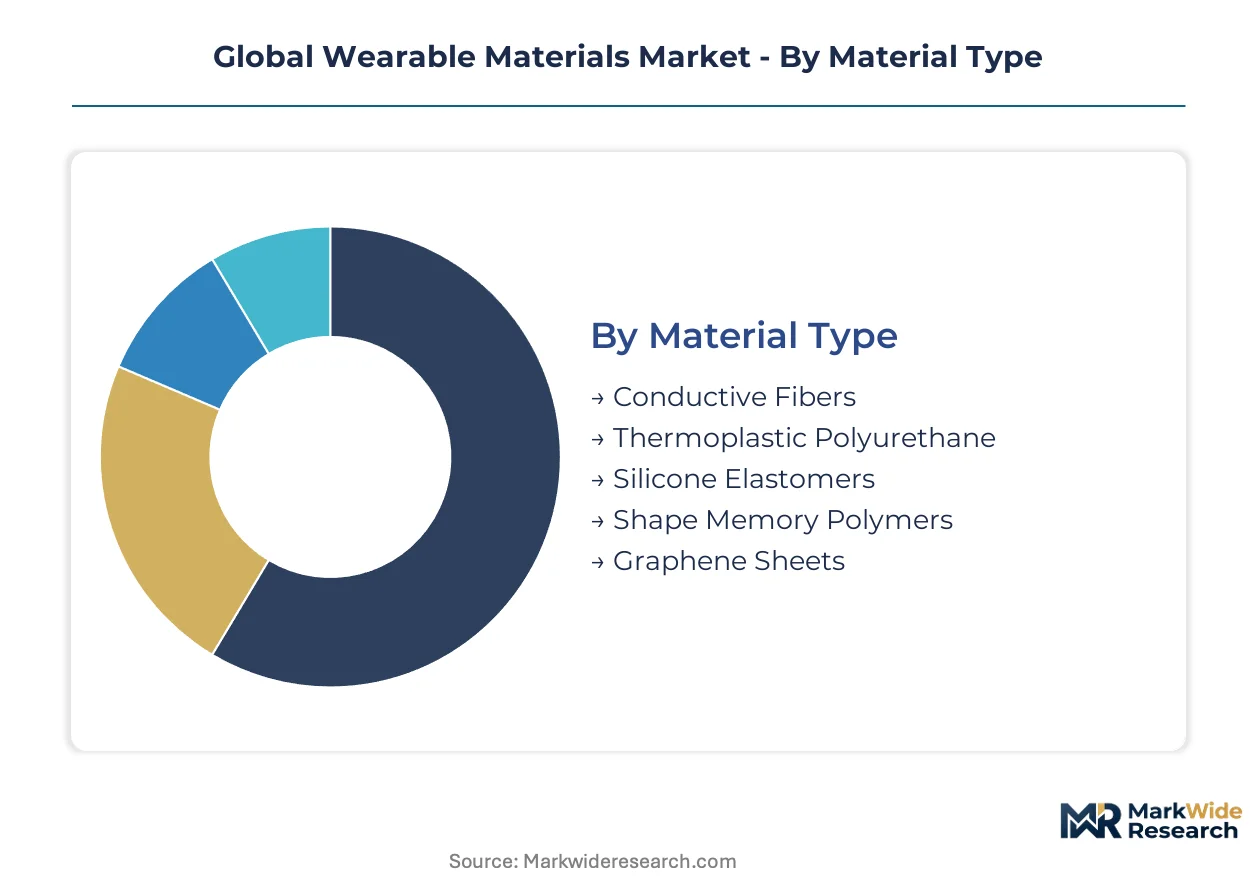
Material selection in wearable electronics hinges on skin-contact duration, mechanical stress cycles, and regulatory exposure. Each segmentation dimension reveals distinct procurement patterns between medical-grade certifiers and consumer-scale volume buyers.
Material Type:
Cost tiers separate commodity elastomers from certified medical compounds, with formulation chemistry dictating margin capture.
- Thermoplastic Polyurethane:Shore hardness tunability across 70A–85D enables abrasion-resistant films for fitness tracker bands. Demand concentrates in China's Dongguan manufacturing corridor, where TPU converters compress lead times for global electronics brands facing compressed product cycles.
- Silicone Elastomers:Platinum-cured formulations achieve ISO 10993 biocompatibility for continuous glucose monitor patches. Healthcare procurement in Germany and the United States now mandates third-party cytotoxicity documentation, disqualifying suppliers without captive toxicology infrastructure.
- Graphene Sheets:Screen-printed conductive pathways enable washable smart textile sensor grids at regional textile converters.
- Conductive Fibers:Silver-coated nylon and copper-core yarns integrate into military uniform grounding systems.
- Shape Memory Polymers:Temperature-activated actuation supports adaptive compression garments for post-surgical recovery.
Volume sits with thermoplastic polyurethane; growth tilts toward graphene sheets.
Application:
Application maturity determines whether specifications prioritize durability testing or rapid design iteration.
- Medical Monitoring:Continuous cardiac and glucose wearables require ISO 10993-5 and ISO 10993-10 certification as hospital procurement table stakes. FDA 510(k) and EU MDR documentation timelines extend 12-18 months, concentrating contract awards among compounders with established regulatory dossiers.
- Fitness Trackers:TPU band production scales through Shenzhen electronics clusters, with brands sourcing from certified converters to meet FCC and CE marking requirements for simultaneous US and European launches.
- Smart Textiles:Biometric jerseys with printed sensor grids gain pilot adoption at sports apparel brands.
- Virtual Reality Devices:Optical-grade polycarbonate lenses demand clarity and impact resistance specifications.
- Military Gear:Sweat-resistant fluoropolymer seals and conductive grounding fabrics face MIL-STD durability protocols.
Revenue concentrates in medical monitoring; expansion accelerates fastest in smart textiles.
End User:
Customer type dictates whether procurement emphasizes unit economics or performance guarantees under field conditions.
- Healthcare Providers:Hospital procurement coalitions in the United States and Germany specify certified biocompatibility documentation, displacing price-based supplier selection regardless of cost position.
- Sports Enthusiasts:Consumer brands source TPU films and silicone straps through Asian manufacturing clusters, prioritizing color consistency and batch-to-batch Shore hardness stability.
- Defense Agencies:Military specifications require electromagnetic shielding and chemical resistance under combat conditions.
- Entertainment Companies:VR headset manufacturers establish direct specification partnerships with polycarbonate molders, bypassing traditional electronics distributors.
- Research Institutes:Experimental graphene and shape memory polymer formulations support prototype development for next-generation conformable electronics.
Contract value peaks with healthcare providers; volume scales through sports enthusiasts.
Form Factor:
Manufacturing process constraints separate roll-to-roll film converters from specialized coating applicators.
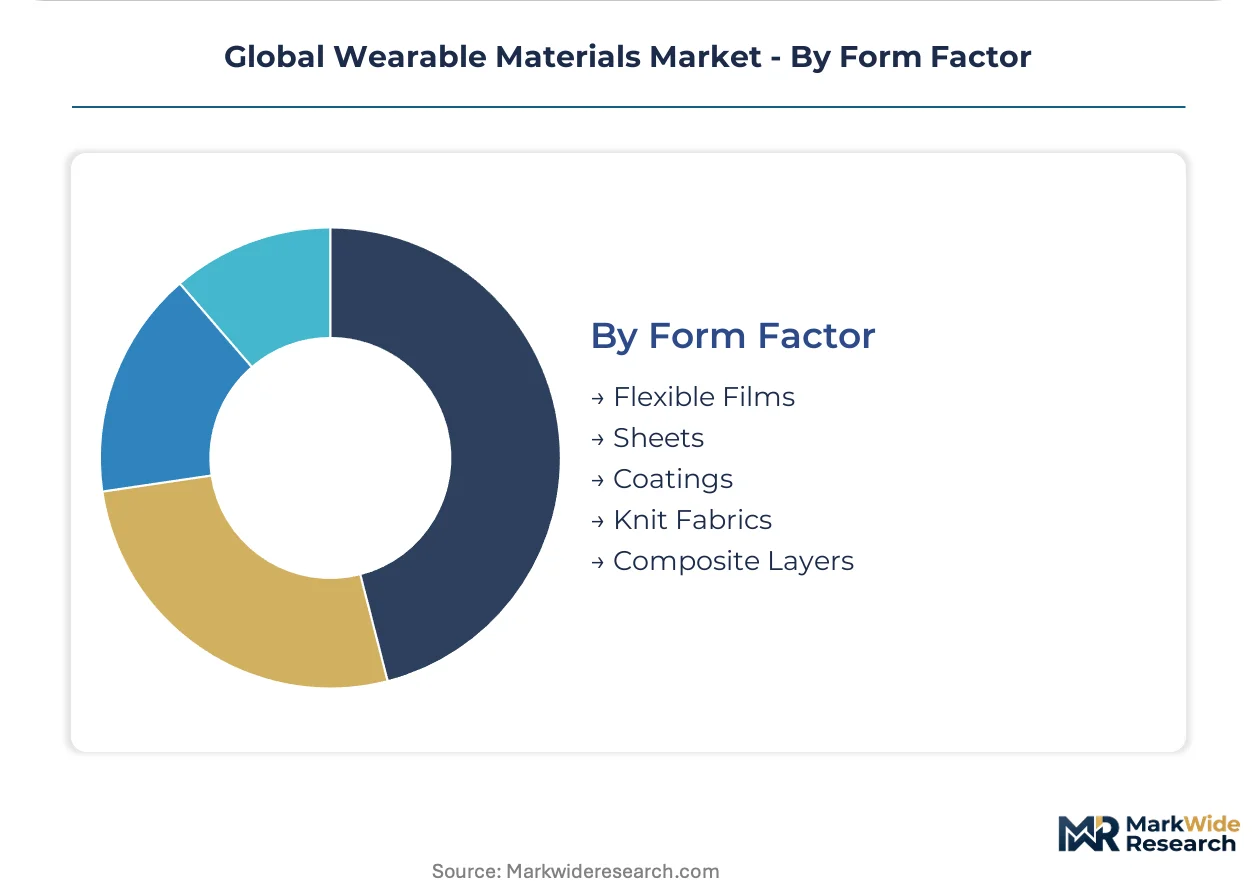
- Flexible Films:TPU and fluoropolymer films enable liquid-tight device seals at 25-micron thickness thresholds, with breathable variants supporting sweat management in fitness applications.
- Knit Fabrics:Conductive yarn integration at textile mills decentralizes sensor production from rigid PCB fabrication.
- Sheets:Silicone elastomer sheets serve as substrate layers for medical-grade adhesive patches.
- Coatings:Thin-film deposition protects sensor electrodes from corrosion in wearable environments.
- Composite Layers:Multi-material laminates combine thermal management with mechanical protection in military headsets.
Production throughput favors flexible films; technical differentiation concentrates in composite layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyether polyol feedstock concentration in the US Gulf Coast and diisocyanate production along Germany's Rhine corridor anchor regional supply architectures for wearable material converters.
United States
Hospital procurement coalitions in Texas and California mandate ISO 10993-5 cytotoxicity documentation for cardiac wearables. FDA 510(k) clearance timelines extend 12-18 months for new silicone formulations. Minneapolis medical device clusters source TPU films from domestic converters to compress regulatory submission cycles.
Germany
EU MDR Annex I requirements now demand clinical evidence for all skin-contact materials. Notified bodies in Berlin and Munich expanded capacity 40% to manage documentation backlogs. BASF SE anchors thermoplastic polyurethane supply from Ludwigshafen research networks.
China
Shenzhen and Dongguan electronics clusters scale TPU film production for fitness tracker bands. NMPA registration adds a third certification layer for brands accessing domestic manufacturing. Jiangsu and Zhejiang provinces concentrate over 70% of medical-grade silicone elastomer supply.
Japan
METI funding supports graphene conductive textile development for next-generation sensor pathways. PMDA biocompatibility standards align with ISO 10993 frameworks. Osaka polymer research institutes pilot shape memory polymer formulations for adaptive compression garments.
India
PLI scheme incentives attract component material suppliers for wearable assembly operations shifting from China. CDSCO medical device regulations tighten import documentation for skin-contact polymers. Karnataka electronics manufacturing zones host pilot TPU compounding facilities.
Global Wearable Materials Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based polyol feedstocks and printed graphene pathways. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive polymer research, specialized elastomer compounders with toxicology infrastructure, and regional converters serving single-application niches. Dominant competitive moves include backward integration into polyol feedstocks and specification partnerships with VR headset manufacturers bypassing traditional electronics distributors.
Among German chemical conglomerates, BASF SE and Covestro AG exemplify integrated producers with polymer research networks spanning thermoplastic polyurethane and optical-grade polycarbonate formulations. DuPont de Nemours anchors North American positioning through fluoropolymer specialization. Wacker Chemie AG represents the specialized silicone tier with platinum-cured elastomer capabilities for ISO 10993-certified medical applications.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours |
| Wacker Chemie AG |
| Arkema S.A. |
| Covestro AG |
| The Lubrizol Corporation |
| DSM |
| Momentive Performance Materials |
| Solvay |
| Others |
Supply & Pricing Matrix
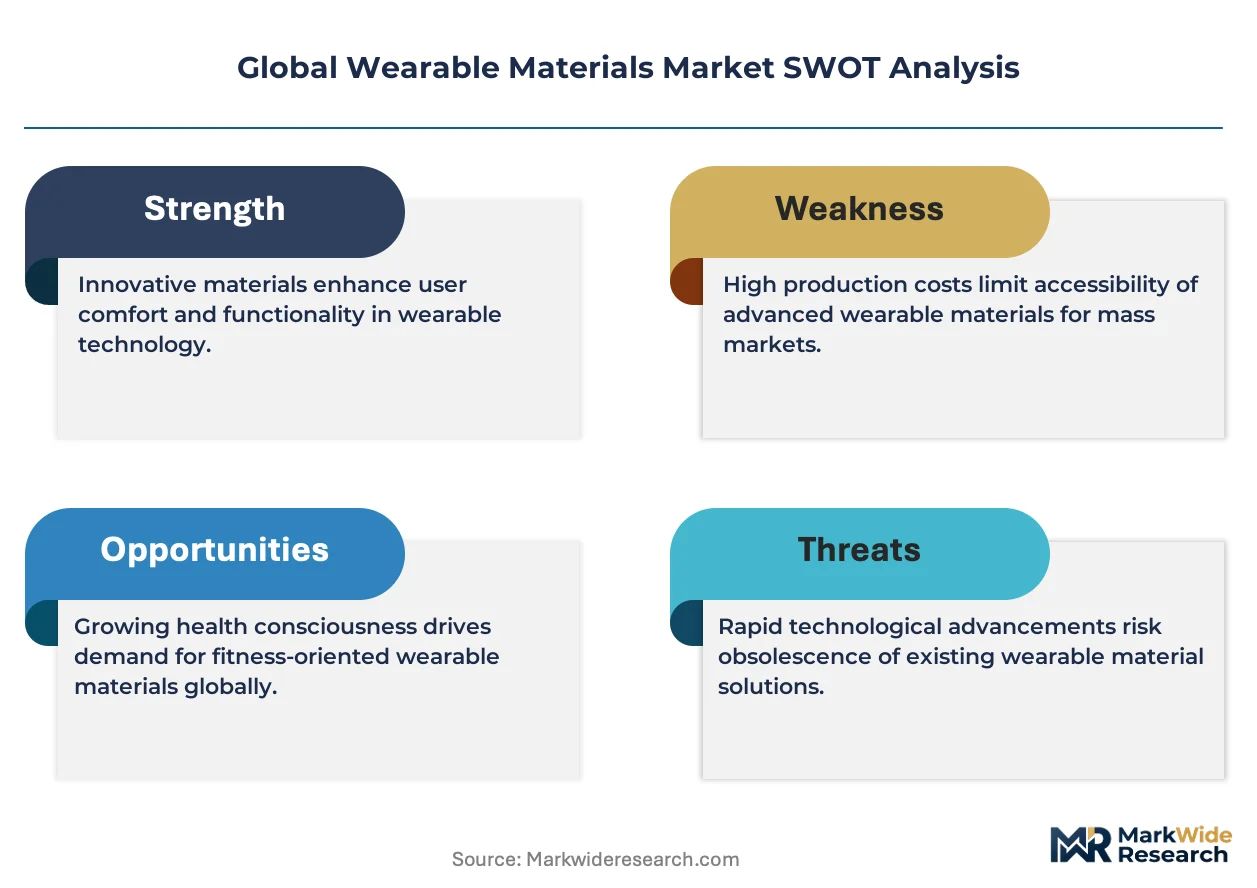
EU Green Deal chemical substitution mandates gate qualified supply for REACH-compliant thermoplastic polyurethane formulations, restricting premium-tier pricing access to compounders with bio-based polyol feedstock capabilities and certified toxicology infrastructure.
Pricing Analysis
Extended warranty and biocompatibility certification bundling separate medical-grade silicone elastomer pricing from unbundled consumer TPU film transactions. Three-tier pricing structure across ISO 10993-certified premium, FCC/CE-marked standard, and commodity economy levels reflects certification investment recovery. Cost compression in mid-volume TPU compounding intensifies because petrochemical input volatility destabilizes polyether polyol and diisocyanate costing models. Hospital procurement coalitions show least price sensitivity, while fitness tracker brands sourcing through Shenzhen clusters demonstrate highest elasticity.
Supply Chain Analysis
FDA 510(k) and EU MDR technical documentation requirements gate qualified supply, concentrating medical-grade silicone elastomer production in Jiangsu and Zhejiang provinces of China and platinum-cured compounders in Germany. Raw material flows draw from US Gulf Coast polyether polyol production, Rhine corridor diisocyanate facilities, and Asian silicone monomer crackers. Single-source vulnerability in FDA-certified medical elastomer supply creates structural risk. Distribution runs through direct specification partnerships with VR headset manufacturers and hospital procurement coalitions, bypassing traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as multi-jurisdiction certification timelines force capital-intensive toxicology infrastructure investments that weaker compounders cannot sustain.
For Market Incumbents: Anticipate margin compression from bio-based polyol entrants by securing captive supply agreements with European feedstock producers and expanding Berlin notified body relationships to compress EU MDR approval cycles. Backward integration into optical-grade polycarbonate resin production defends positioning against Covestro specification partnerships with direct-to-consumer VR brands. For New Entrants and Emerging Players: Screen-printed graphene conductive pathways offer a technology-first wedge into regional textile converter networks previously dependent on Asian rigid PCB fabrication. Target India's PLI scheme electronics manufacturing zones for TPU compounding facilities serving wearable assembly operations shifting from Dongguan. Pursue direct specification partnerships with sports apparel brands piloting biometric jersey programs. For Investors and Strategic Acquirers: German notified body capacity expansion announcements are the leading indicator that EU MDR documentation backlogs are clearing, accelerating consolidation timelines for prepared medical-grade compounders. Over the medium-term horizon, acquisition targets center on specialized elastomer compounders with captive ISO 10993-5 and ISO 10993-10 testing infrastructure and established FDA 510(k) dossier libraries. Monitor CDSCO regulatory tightening in India as a signal for import-substitution investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyol Feedstocks | REACH compliance secures European healthcare procurement contracts against petrochemical volatility. |
| ISO 10993 Captive Toxicology Infrastructure Investment | Third-party certification documentation displaces price-based supplier selection in US hospital systems. |
| Direct Specification Partnership with VR Headset Manufacturers | Optical-grade polycarbonate lens molders bypass traditional electronics distribution channels. |
| India PLI Scheme Manufacturing Localization | Karnataka electronics zones attract component suppliers for wearable assembly shifting from China. |
| Printed Graphene Sensor Grid Pilot Programs | Regional textile converters capture value from sports apparel biometric jersey adoption. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, combined with primary interviews across polymer research directors at integrated chemical conglomerates, procurement leads at hospital system GPOs, regulatory affairs managers at wearable device OEMs, and formulation chemists at specialized elastomer compounders. Bottom-up TPU film volume estimates from Dongguan converter shipments triangulated against top-down medical silicone elastomer value projections derived from FDA 510(k) submission databases and EU MDR notified body capacity reports.
Segmentation granularity modeled material type at the formulation chemistry level, application by skin-contact duration and certification tier, end user through procurement authority structure, and form factor by manufacturing process constraint. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating graphene conductive textile adoption curves from METI-funded pilot programs and shape memory polymer hospital procurement patterns from German post-surgical recovery device tenders.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH substance restriction expansions or NMPA registration timeline accelerations. Forecasts reflect assumptions about biocompatibility certification harmonization across FDA, EU MDR, and China NMPA frameworks. A model refresh is warranted upon material change in EU Green Deal bio-based content mandates or India PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Smart Band Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Europe Watch Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
Global Smart Watch Market