
 Watertight Doors Market | 2026-2036
Watertight Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Watertight Doors Market Outlook
Buyer concentration among commercial shipyards is consolidating as Korean and Chinese yards capture larger build slots, pressuring smaller European and Japanese operators to merge procurement pools. MML Marine leverages its UK manufacturing base to sustain Royal Navy and NATO contracts. IMS Marine Solutions anchors Mediterranean retrofit demand through its Italian service network. BAIER Marine differentiates via pneumatic sealing technology for high-pressure submarine hull penetrations.
Watertight doors are engineered marine access barriers constructed from steel, aluminum, or composite materials, designed to withstand hydrostatic pressure and prevent flooding between vessel compartments; they incorporate rubber or inflatable gaskets, dogging mechanisms, and in automatic variants, hydraulic or pneumatic actuators rated for specific depth pressures. Automatic doors command premium positioning due to integration with vessel damage-control systems and reduced crew response time during emergencies. Bulkhead-mounted installations lead volume in newbuild vessels where structural integration occurs during hull assembly, while surface-mounted retrofits serve aging commercial fleets facing classification society renewal deadlines.
IMO SOLAS regulations mandate watertight door testing intervals and performance standards that classification societies including Lloyd's Register and DNV enforce during vessel certification audits. The EU Marine Equipment Directive harmonizes type-approval requirements across member states, streamlining market access for certified manufacturers. Stakeholders must monitor evolving naval stealth specifications and polar code ice-class amendments that will reshape material selection and sealing system designs.
Market Dynamics
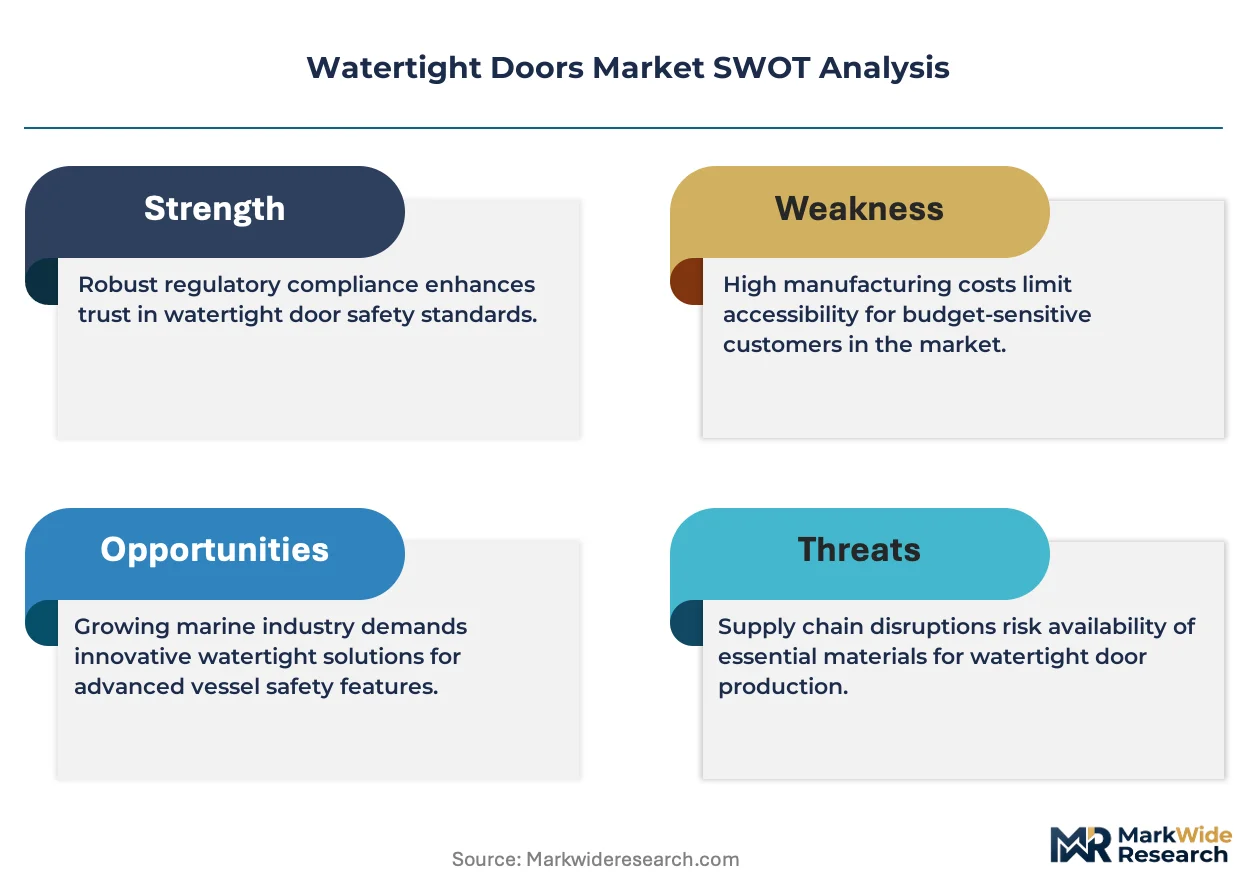
Naval fleet modernization programs and SOLAS subdivision amendments are compressing procurement cycles while concentrating demand among Korean and Chinese shipbuilders capable of integrated hull-damage-control systems.
Growth Catalysts
- IMO SOLAS Chapter II-1 Amendments:Mandatory damage stability assessments for passenger vessels and cargo ships above 500 gross tonnage are accelerating replacement of manual doors with automated systems integrated to flooding alarms.
- Composite Material Adoption:Carbon-fiber reinforced polymer doors are penetrating high-speed ferry and naval stealth applications where magnetic signature reduction and weight savings justify premium engineering.
- South Korean Shipbuilding Clusters:Hyundai Heavy Industries and Samsung Heavy Industries are consolidating multi-vessel procurement contracts that bundle watertight access systems with integrated damage-control suites.
Market Restraints
- Specialized Steel Alloy Volatility:HY-80 and HY-100 high-yield steels for submarine pressure hull penetrations face supply concentration from US and Japanese specialty mills, creating input cost instability.
- Classification Society Audit Bottlenecks:Lloyd's Register and DNV certification backlogs for prototype door testing extend product validation timelines by 8-14 months for novel sealing mechanisms.
- Remotely Operated Vehicle Substitutes:Unmanned underwater vehicle compartments are eliminating traditional access requirements on autonomous naval platforms, shrinking addressable hull penetration demand.
Strategic Opportunities
- Polar Code Ice-Class Retrofits:Antarctic and Arctic vessel operators under IMO Polar Code amendments are upgrading to reinforced sealing systems rated for ice-impact scenarios and sub-zero gasket elasticity.
- Digital Twin Integration:Convergence of hydraulic actuators with IoT pressure sensors and predictive maintenance software creates recurring revenue streams through subscription-based flooding-risk monitoring.
- Indonesian Archipelago Ferry Renewal:The country's national sea connectivity program is replacing aging inter-island vessels, generating concentrated demand for cost-optimized surface-mounted automatic doors.
Industry Challenges
- Certified Welder Scarcity:Lloyd's Register and DNV-qualified hull integration specialists are concentrated in European and Korean shipyards, constraining expansion into emerging build locations.
- Legacy Vessel Compatibility:Retrofit installations on 1970s-1990s bulk carriers require custom frame adaptations that fragment engineering resources and compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watertight Doors Market |
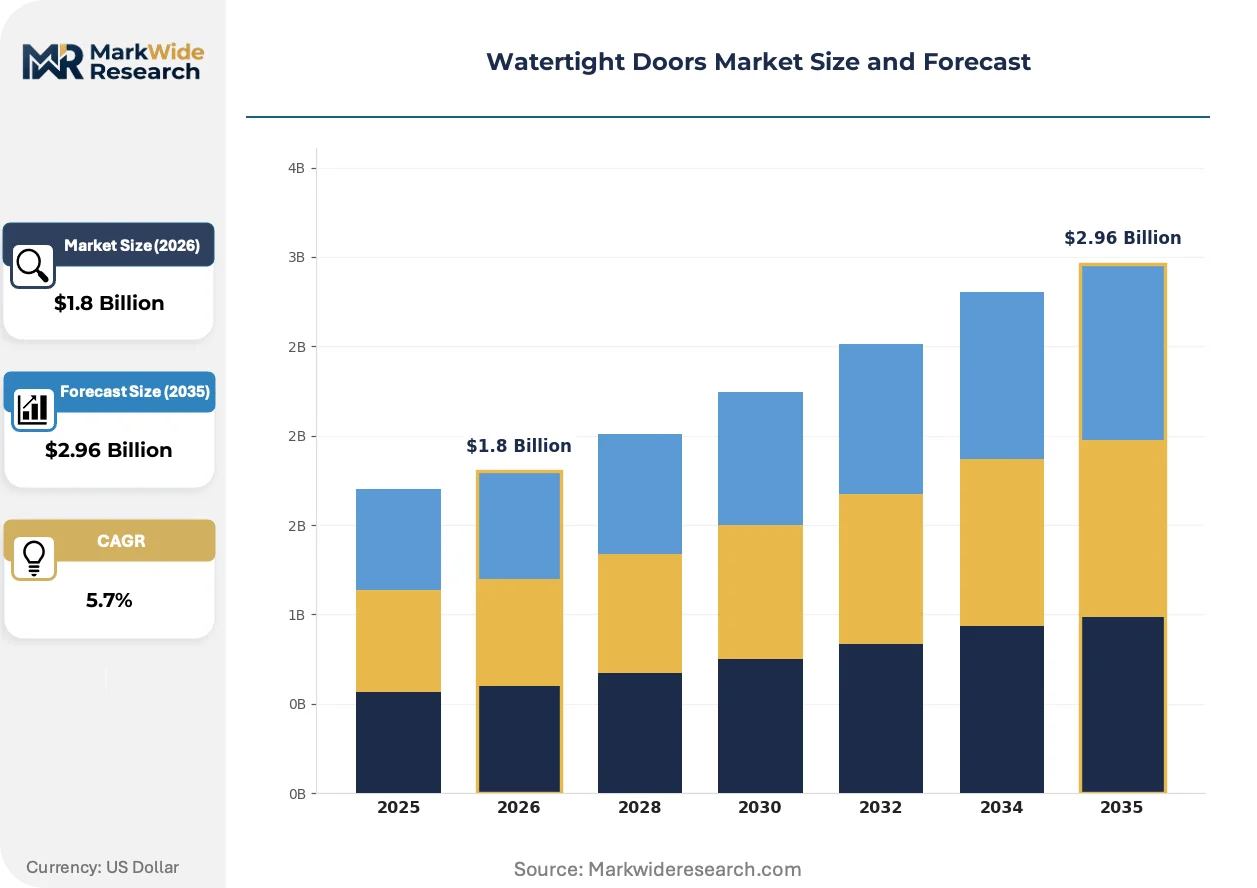
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Doors, Automatic Doors, Folding Doors, Sliding Doors End User: Marine Applications, Industrial Facilities, Submarine Use, Commercial Vessels Material: Steel, Aluminum, Composite, PVC Installation Type: Frame Mounted, Bulkhead Mounted, Surface Mounted, Flush Mounted |
| Companies Covered | MML Marine, IMS Marine Solutions, BAIER Marine, Westmoor Engineering, Ocean Group, AdvanTec Marine, Winel, SeaNet Group, Advanced Pneumatic Marine GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watertight Doors Market Strategic Shifts
Automation and predictive intelligence are redefining how vessel flooding containment operates, shifting competitive advantage from mechanical reliability to integrated damage-control ecosystem participation.
Pneumatic inflatable sealing systems are overtaking conventional rubber gasket designs in high-pressure submarine and deep-diving support vessel applications. Naval architects at French and Australian submarine programs specify these systems for their ability to maintain seal integrity under cyclic pressure loading. The technology is compressing maintenance intervals from annual gasket replacement to five-year inspection cycles.
The EU Marine Equipment Directive's 2024 harmonized type-approval framework is eliminating redundant national certification requirements across member states. Manufacturers holding MED Module B+D approvals now access 27 national markets through single conformity assessment. Mediterranean retrofit specialists are consolidating inventory positions around MED-certified automatic door variants to capture cross-border service contracts.
Shipyard procurement departments are bundling watertight door contracts into integrated damage-control system packages awarded to single-source vendors. Korean and Chinese newbuild programs favor suppliers offering doors, valves, and flooding detection sensors under unified performance warranties. This consolidation is visible at Samsung Heavy Industries' Geoje facility where multi-system procurement contracts now exceed individual component sourcing by a three-to-one ratio.
Watertight Doors Market Segmentation
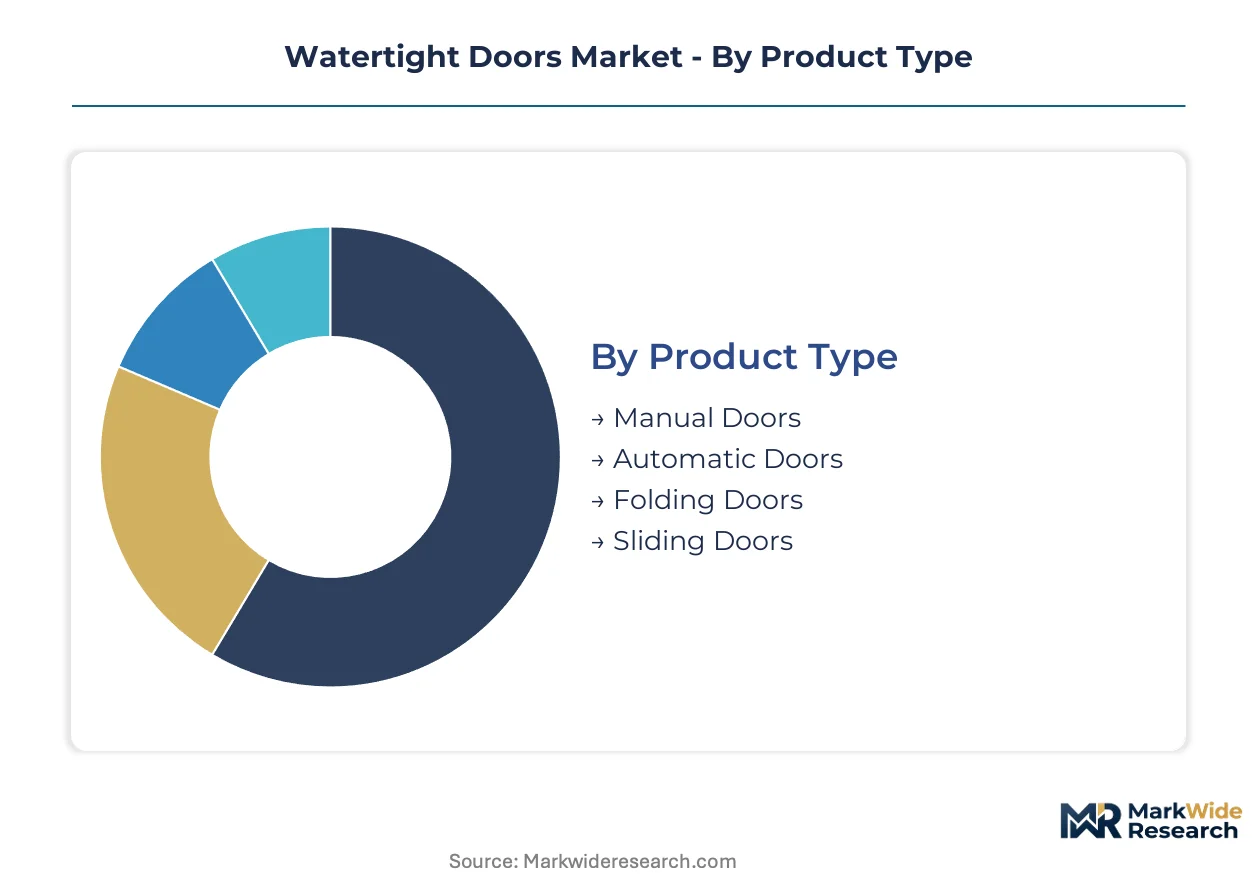
Watertight door procurement patterns diverge sharply between cost-sensitive retrofit fleets and premium newbuild programs. Segmentation reveals where engineering complexity commands price premiums versus where standardization drives volume economics.
Product Type:
Automatic doors capture premium positioning through integration with vessel damage-control systems, while manual variants dominate replacement cycles on aging commercial fleets.
- Manual Doors:Mechanical dogging mechanisms with rubber gasket seals require crew operation during flooding events. Demand concentrates in Indonesian and Philippine inter-island ferry retrofits where capital constraints favor proven mechanical systems over automation infrastructure.
- Automatic Doors:Hydraulic or pneumatic actuators interface with vessel flooding alarm networks for remote closure capability. Korean newbuild programs at Hyundai Heavy Industries and Samsung Heavy Industries specify these systems for reduced crew response time during subdivision breaches.
- Folding Doors:Articulated panel designs optimize space-constrained machinery compartments and accommodation blocks on offshore support vessels.
- Sliding Doors:Horizontal traverse mechanisms suit high-traffic crew passageways where swing radius limitations prevent hinged alternatives.
Today's leader: Automatic Doors. Tomorrow's challenger: Manual Doors in emerging-market retrofit surges.
End User:
Naval specifications drive material and sealing performance requirements, while commercial shipping volumes determine supplier capacity planning.
- Marine Applications:General-purpose commercial shipping encompasses cargo vessels, tankers, and container ships subject to SOLAS subdivision mandates. Lloyd's Register and DNV certification requirements govern procurement specifications across European and Asian flag registries.
- Commercial Vessels:Passenger ferries and cruise ships face the most stringent damage stability regulations. Mediterranean operators under EU Marine Equipment Directive harmonized rules are accelerating replacement of manual systems with automated alternatives.
- Submarine Use:Pressure hull penetrations rated for deep-submergence operations utilize HY-80 and HY-100 steel alloys with inflatable pneumatic seals.
- Industrial Facilities:Offshore platforms and coastal processing plants apply marine-grade sealing standards to flood-protection barriers in hurricane-prone zones.
Commercial Vessels anchor current procurement volumes. Submarine Use is climbing the fastest as French and Australian naval programs expand pressure hull production.
Material:
Weight-performance tradeoffs separate premium composite adoption from steel's cost efficiency in high-volume applications.
- Steel:Carbon and high-yield alloy grades dominate pressure-rated applications where hydrostatic load-bearing capacity overrides weight considerations. US and Japanese specialty mills concentrate supply for submarine-grade HY-80 and HY-100 specifications.
- Composite:Carbon-fiber reinforced polymer formulations reduce magnetic signature and structural weight for high-speed ferry and stealth naval platforms. Australian and French submarine programs specify these materials for cyclic pressure loading endurance.
- Aluminum:Corrosion-resistant grades suit superstructure-mounted access points on aluminum-hulled patrol craft and fast ferries.
- PVC:Thermoplastic formulations serve non-structural accommodation partitions on inland waterway vessels with minimal pressure exposure.
Steel maintains installed base dominance. Composite is gaining share fastest in next-generation naval architecture.
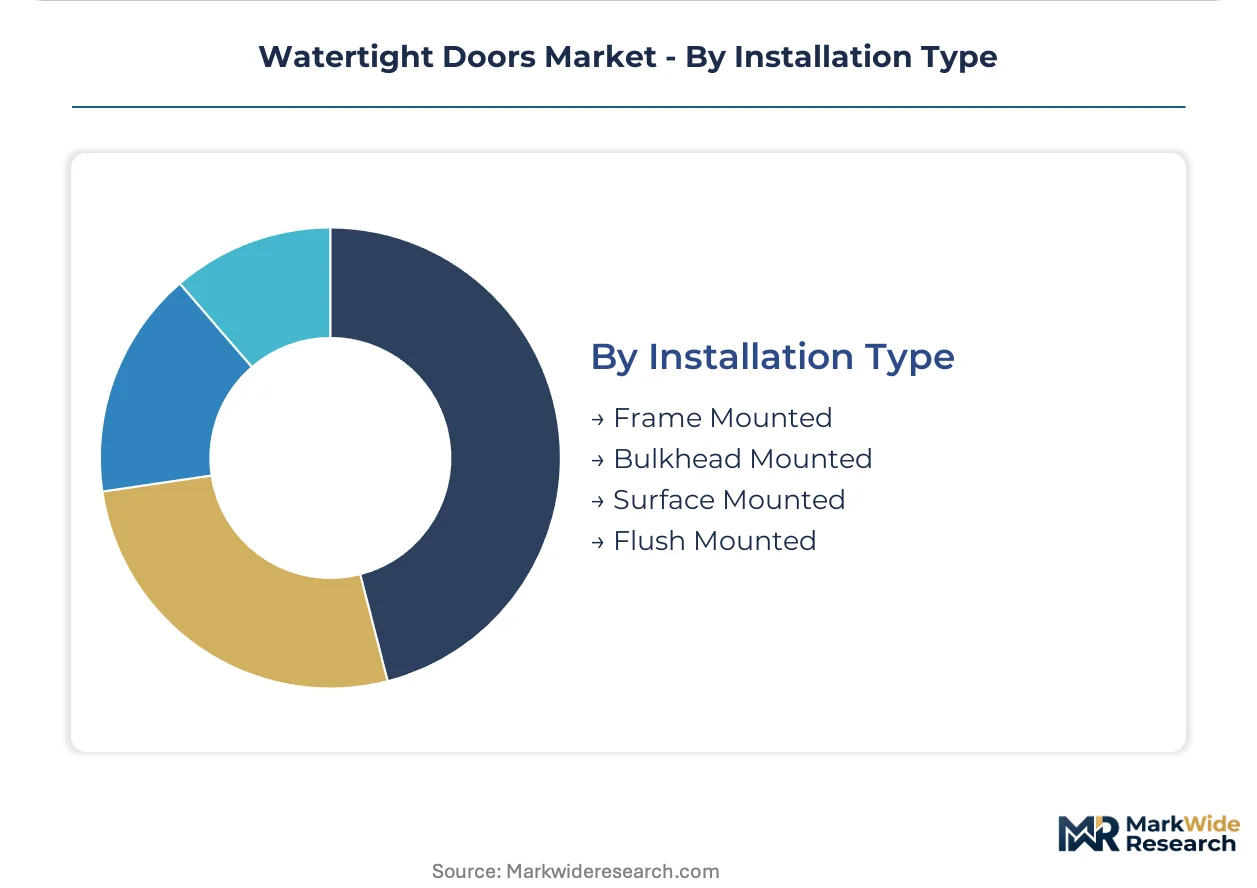
Installation Type:
Structural integration timing determines whether doors ship as hull-embedded components or field-retrofit kits.
- Bulkhead Mounted:Doors installed during hull assembly achieve full structural integration with welded frames and continuous gasket seating. Korean and Chinese newbuild yards favor this approach for integrated damage-control system warranties.
- Surface Mounted:Retrofit installations on existing vessels require custom frame adaptations to accommodate legacy hull plate thickness variations and corrosion profiles.
- Frame Mounted:Pre-fabricated frame assemblies simplify installation sequencing in modular shipbuilding workflows.
- Flush Mounted:Recessed panel designs minimize protrusion into passageways on space-optimized naval combatants and expeditionary vessels.
Bulkhead Mounted commands newbuild premiums. Surface Mounted is expanding most quickly as classification society renewal deadlines compress retrofit timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's naval modernization and commercial shipbuilding dwarf Japan's fragmented yard structure, while China's state-directed consolidation creates divergent procurement dynamics across Northeast Asian maritime clusters.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global newbuild output for LNG carriers and naval destroyers. The country's national defense procurement agency accelerates KDX-III destroyer and KSS-III submarine programs requiring pressure-rated hull penetrations. Geoje and Ulsan industrial complexes concentrate integrated damage-control system fabrication.
China
State-owned China State Shipbuilding Corporation consolidates civilian and naval construction at Dalian and Shanghai yards. MIIT shipbuilding directives mandate domestic content ratios for critical marine equipment. Jiangnan Shipyard and Hudong-Zhonghua Shipbuilding expand aircraft carrier and amphibious assault vessel production.
United States
Virginia-class and Columbia-class submarine programs at Electric Boat and Newport News Shipbuilding drive HY-80 steel demand. The US Navy's 30-year shipbuilding plan prioritizes unmanned surface vessel integration. Groton and Newport News clusters specialize in nuclear pressure hull welding certification.
Japan
Imperial Japanese Navy frigate procurement and coast guard cutter replacement sustain Mitsubishi Heavy Industries and Japan Marine United. METI maritime industrial policy supports domestic yard consolidation against Korean competition. Nagasaki and Yokohama facilities face capacity constraints from aging workforce demographics.
Italy
Fincantieri's naval and cruise ship construction at Monfalcone and Castellammare di Stabia generates Mediterranean retrofit demand. EU Marine Equipment Directive harmonization streamlines type-approval for Italian suppliers. La Spezia and Trieste clusters specialize in luxury yacht and offshore support vessel access systems.
Watertight Doors Market Competitive Environment
South Korean producers anchor one tier; European specialists hold premium retrofit and naval certification positions. Market structure bifurcates between scale-driven Asian fabricators serving newbuild programs and engineering-intensive Western vendors capturing classification society compliance work. Two strategic archetypes dominate: integrated damage-control system bundlers and standalone door specialists with MED Module B+D approvals. Competitive moves center on Korean shipyard procurement consolidation and European service network expansion for aging fleet renewal.
Within the naval-specialist tier, MML Marine and BAIER Marine exemplify certification-intensive positioning. MML Marine represents UK-based Royal Navy and NATO contract sustainment, while BAIER Marine occupies a position in pneumatic sealing technology for submarine applications. IMS Marine Solutions anchors Mediterranean retrofit demand through Italian service infrastructure. These three entities illustrate how geographic proximity to naval procurement centers and classification society headquarters shapes competitive access.
| Leading Market Players |
|---|
| MML Marine |
| IMS Marine Solutions |
| BAIER Marine |
| Westmoor Engineering |
| Ocean Group |
| AdvanTec Marine |
| Winel |
| SeaNet Group |
| Advanced Pneumatic Marine GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive integration into HY-80 and HY-100 steel supply chains anchors pricing power for submarine-grade door manufacturers, while Korean shipbuilders leverage backward control over pneumatic actuator sourcing to compress supplier margins on commercial contracts.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for automatic watertight door systems as Hyundai Heavy Industries and Samsung Heavy Industries consolidate multi-vessel procurement bundles. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified naval variants from MED Module B+D commercial units and uncertified retrofit alternatives. Pricing pressure stems from Chinese state-owned yards demanding domestic content ratios under MIIT directives. Indonesian ferry operators exhibit highest price sensitivity, while French and Australian submarine programs prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Korean and Chinese shipbuilding clusters, with secondary distribution through Mediterranean service networks for European retrofit fleets. Geographic supply concentrates in the United States, Japan, and South Korea for high-yield steel alloys; Germany and Italy for precision pneumatic components; and China for standard hydraulic actuators. Raw material dependencies rest on nickel-alloy steel plate, synthetic rubber gasket compounds, and carbon-fiber reinforced polymer feedstock. Single-source vulnerability runs through US and Japanese specialty mills controlling submarine-grade steel output. Distribution runs through shipyard-integrated procurement departments bundling doors into damage-control system packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The watertight doors market functions as a stable compounder anchored by IMO SOLAS regulatory mandates that enforce replacement cycles regardless of shipping rate volatility.
For Market Incumbents: Lock in long-term supply agreements with HY-80 and HY-100 steel mills to defend against input cost volatility from US and Japanese specialty producers. Deepen backward integration into pneumatic sealing technology to capture submarine program premiums at BAIER Marine's positioning. Invest in Lloyd's Register and DNV welding certification pipelines to constrain competitor access to naval procurement clusters. For New Entrants and Emerging Players: The gap between premium automatic systems and economy manual doors creates entry space for cost-optimized surface-mounted variants targeting Indonesian archipelago ferry renewal. Mediterranean retrofit demand offers the most penetrable white space, with EU Marine Equipment Directive harmonization enabling cross-border service contracts. Pursue partnerships with Italian and Greek ship repair networks rather than competing for Korean newbuild slots directly. For Investors and Strategic Acquirers: Roll-up economics work for MED-certified retrofit specialists because classification society compliance creates sticky customer relationships with recurring audit-driven replacement cycles. Target platform acquisitions of Western European service networks with established Lloyd's Register and DNV relationships. Monitor French and Australian submarine program budget allocations as the inflection signal for composite material adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive access to HY-80 alloys insulates margins from US and Japanese mill concentration. |
| MED Module B+D Certification Investment | Single conformity assessment unlocks 27 EU national markets for automatic door variants. |
| Pneumatic Sealing Technology Licensing | French and Australian submarine programs specify inflatable seals for cyclic pressure endurance. |
| Indonesian Service Network Expansion | National sea connectivity program generates concentrated demand for cost-optimized retrofits. |
| Digital Twin Platform Development | IoT sensor integration creates recurring revenue through predictive flooding-risk monitoring. |
Study Parameters
Direct dialogue with shipyard procurement directors, naval architects at classification societies, aftermarket service managers, and marine equipment distributors grounded the qualitative foundation, cross-referenced against IMO SOLAS amendment texts, Lloyd's Register and DNV certification databases, EU Marine Equipment Directive harmonization frameworks, and customs trade data on steel alloy shipments. Bottom-up and top-down triangulation validated segment-level demand estimates.
Bottom-up modeling aggregated shipbuilding orderbook data by vessel type and damage-control system content assumptions, while top-down approaches calibrated against aggregate marine equipment spending patterns across the projection horizon. Segmentation dimensions included product type, end-user category, material specification, and installation approach. CAGRs were derived from fitted growth curves against naval modernization program timelines and classification society renewal deadlines. Industry-specific inputs incorporated KDX-III and KSS-III procurement schedules, Polar Code ice-class retrofit mandates, and Indonesian ferry replacement targets.
Caveats apply where naval budget reallocations toward unmanned platforms, HY-80 steel supply disruptions, or classification society audit backlog extensions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Risers Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Opening Trim Weatherstrips Market