
 Risers Market | 2026-2036
Risers Market Size, Share, and Industry Trends Forecast 2026-2036
Risers Market Intelligence
The substitution of traditional steel with advanced composite materials is pivoting product economics for deepwater applications. This shift favors manufacturers with strong material science capabilities. TechnipFMC leverages its integrated engineering and manufacturing to offer flexible composite risers for ultra-deepwater fields. Aker Solutions specializes in developing lightweight, high-pressure riser systems that reduce topside load requirements for floating production units.
A riser is a specialized pipe system that forms a vertical conduit between a subsea wellhead and a surface facility like a drilling rig or FPSO. These systems are engineered to withstand extreme pressures and oceanic forces, often constructed in layers for specific functions. Within product types, flexible risers hold a significant share for dynamic deepwater applications due to their operational versatility. The oil and gas sector remains the largest end-user, but the renewable energy segment is expanding rapidly with the development of floating offshore wind projects.
Product design and market access are governed by stringent international standards, including those from the American Petroleum Institute (API) and the International Organization for Standardization (ISO). National regulators, such as the UK's Health and Safety Executive (HSE), enforce compliance for regional operations, mandating rigorous integrity management programs. Consequently, operators must weigh the upfront capital expenditure of advanced material risers against their potential for reduced long-term maintenance and enhanced operational life.
Market Dynamics
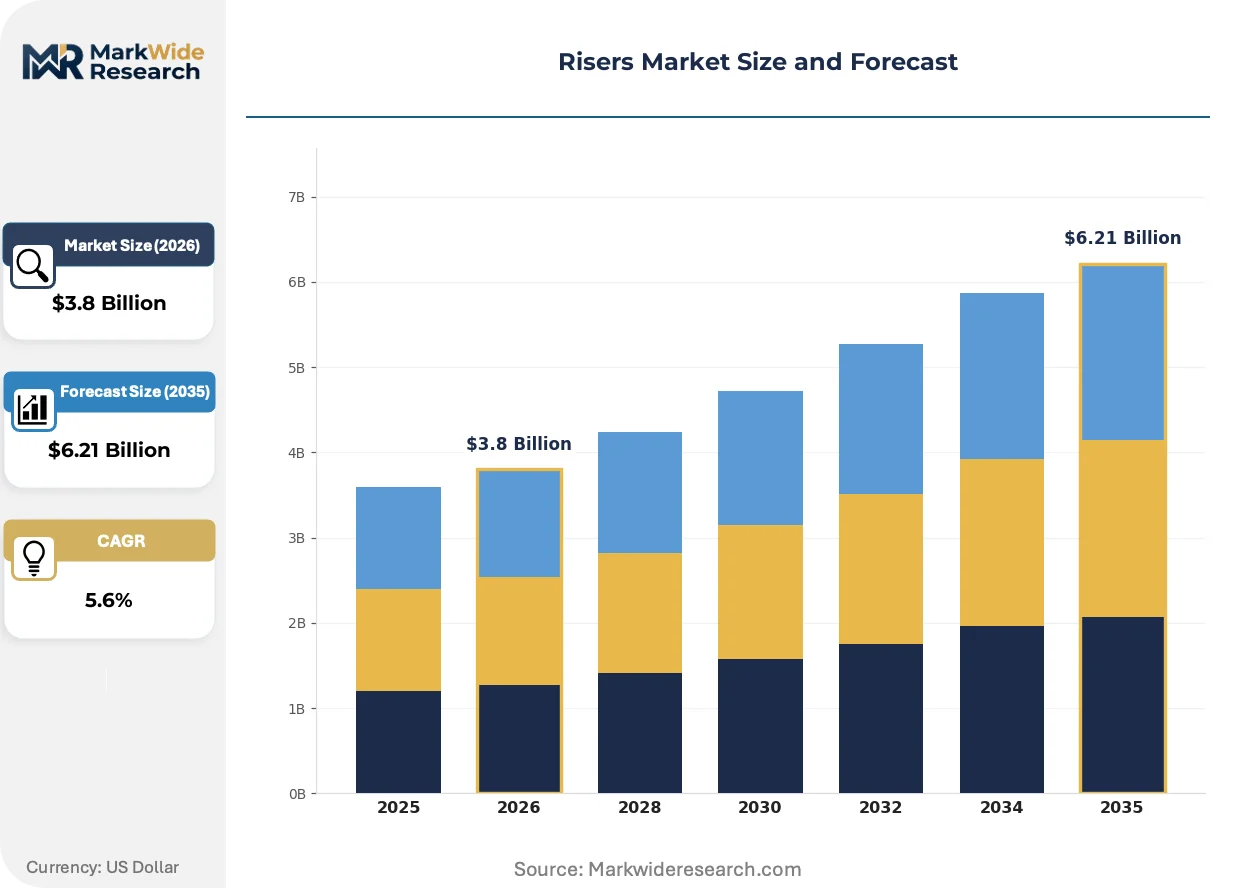
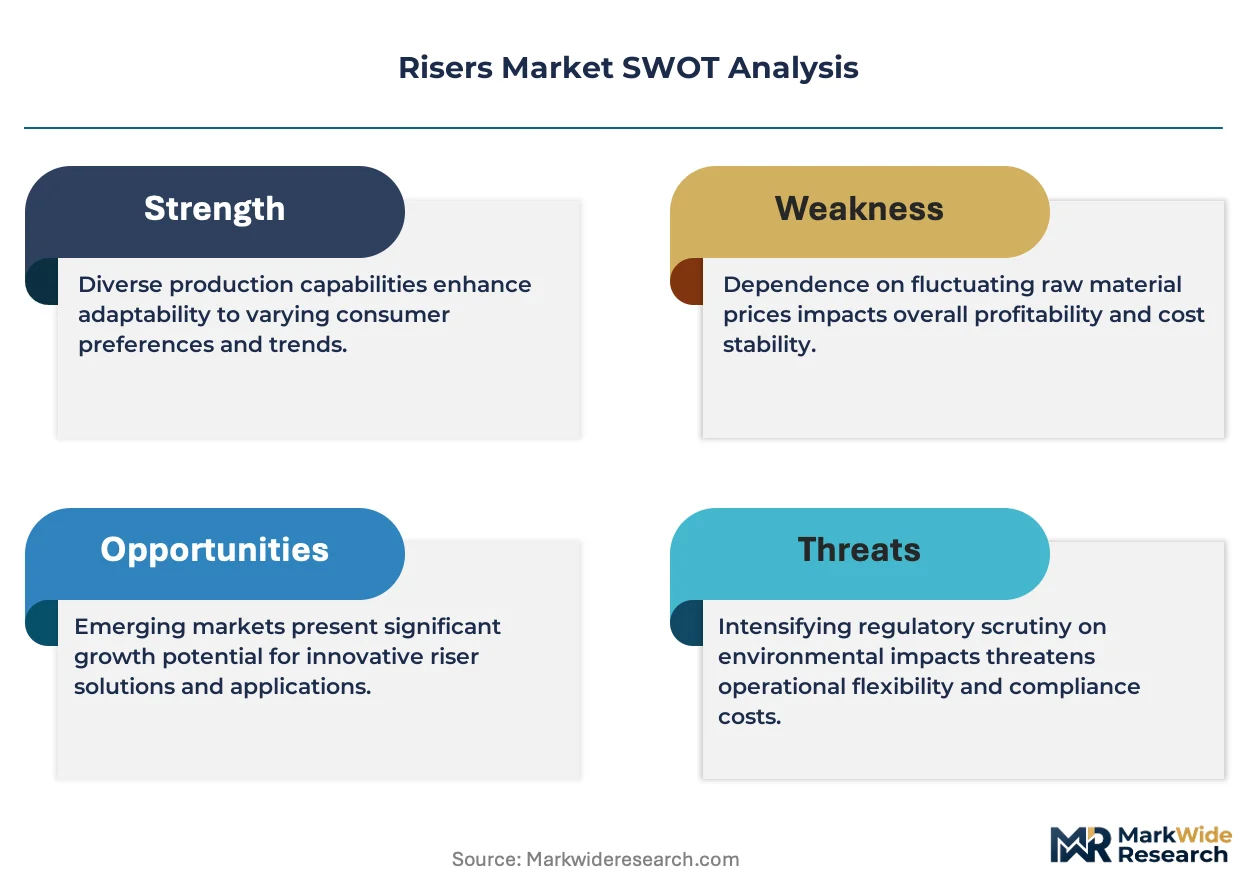
The central dynamic in the risers market is the tension between the high capital expenditure required for advanced composite materials and the long-term operational cost reductions they promise in demanding deepwater oil and gas environments.
Growth Catalysts
- Deepwater Exploration:Sustained investment in new offshore projects, especially in Brazil's pre-salt basins and offshore Guyana, creates direct demand for new riser systems capable of operating at extreme depths.
- Composite Materials:The adoption of lighter, corrosion-resistant composite risers enables exploration in deeper waters and reduces topside structural load requirements on floating production units.
- Stringent Standards:Evolving environmental and safety standards from bodies like the American Petroleum Institute push operators toward higher-specification, more reliable riser technologies to prevent failures.
Market Restraints
- High Capital Cost:The significant upfront investment for composite and titanium stress joints acts as a barrier, particularly for projects with marginal economics or for smaller independent operators.
- Technical Integration:Challenges persist in ensuring compatibility and integrity when connecting new, advanced material risers to older, existing subsea infrastructure and legacy wellheads.
- Supply Concentration:Manufacturing expertise for high-specification flexible and hybrid risers is concentrated among a small number of suppliers, creating potential procurement bottlenecks and limited pricing leverage for buyers.
Strategic Opportunities
- Floating Offshore Wind:The expansion of floating wind farms presents a significant new market for dynamic power cables and specialized riser-like systems to connect turbines to the seabed grid.
- Integrated Digital Twins:Embedding fiber optic sensors to create digital twins of riser systems offers a new service model for real-time integrity monitoring and predictive maintenance services.
- Geothermal Applications:Exploration of offshore geothermal energy sources could require specialized riser systems designed to handle high-temperature fluids and corrosive subsea environments.
Industry Challenges
- Specialized Skill Gaps:A shortage of subsea engineers with dual expertise in composite material science and offshore fluid dynamics constrains new product development and project execution.
- Certification Delays:The extensive and time-consuming process for achieving API or ISO certification for novel riser designs can slow the market introduction of new, innovative technologies.
- Installation Complexity:Deploying ultra-long riser strings in harsh deepwater environments requires specialized vessels and highly experienced crews, adding significant project risk and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Risers, Rigid Risers, Steel Catenary Risers, Hybrid Risers Installation Type: Onshore, Offshore, Subsea, Deepwater End User: Oil & Gas, Renewable Energy, Marine, Industrial Material: Steel, Thermoplastic, Composite, Others |
| Companies Covered | Aker Solutions, TechnipFMC, Subsea 7, Oceaneering International, Prysmian Group, Nexans, DeepOcean, Actuant Corporation, ExxonMobil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risers Market Strategic Shifts & Innovations
Material science advancements and the integration of digital technologies are fundamentally altering riser design, performance monitoring, and lifecycle management. These shifts are pushing operational envelopes and redefining the standards for long-term asset integrity in subsea applications.
Additive manufacturing is being used to produce highly complex, performance-critical riser components like stress joints and connectors. Engineering teams at specialist suppliers are the primary adopters for rapid prototyping and small-batch production. This technology is decentralizing the supply chain for bespoke parts, reducing lead times and reliance on a few large-scale forging facilities.
Heightened regulatory focus on asset integrity, driven by standards like API Recommended Practice 17N and guidance from the UK's Health and Safety Executive, is becoming more stringent. This compels operators to invest more in inspection, repair, and maintenance activities. Aging infrastructure in mature basins like the North Sea is most affected, spurring demand for riser life-extension services.
A clear demand shift from acquiring individual components to awarding integrated riser system contracts is underway. This model disrupts the traditional transactional sale of separate riser joints and buoyancy elements in favor of a single-point-of-contact supplier. This preference for turnkey procurement is most pronounced in complex, large-scale deepwater projects in Brazil and the Gulf of Mexico.
Risers Market Segmentation
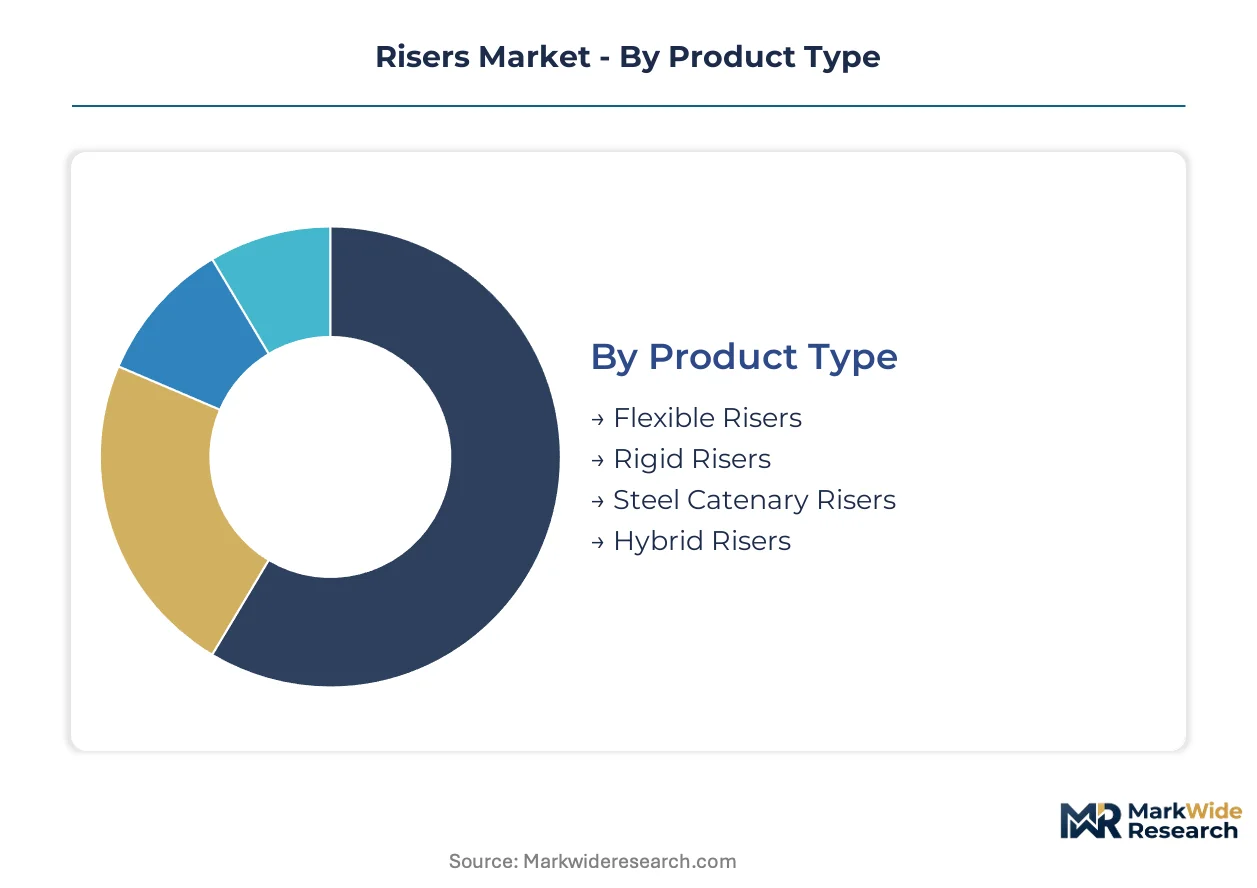
The Risers Market requires granular segmentation to understand the diverse technological requirements and economic drivers across its varied applications. This detailed breakdown illuminates where innovation and investment are concentrating, guiding strategic planning for manufacturers and operators alike.
Product Type:
Compliance with stringent international standards like API 17J for flexible risers and API RP 2RD for rigid risers dictates product development and market entry across different riser types.
- Flexible Risers:These multi-layered pipe systems accommodate dynamic movements between subsea infrastructure and floating facilities, offering high operational versatility. Demand concentrates in deepwater projects, particularly in Brazil's pre-salt basins and the Gulf of Mexico, where their flexibility minimizes fatigue.
- Steel Catenary Risers:Comprising rigid steel pipe sections, these risers are deployed in a free-hanging, S-shaped curve, suitable for high-pressure, high-temperature applications. Ultra-deepwater projects in West Africa and offshore Guyana rely on SCRs for their robust structural integrity.
- Rigid Risers:Conventional steel pipes form these systems, typically used for fixed platforms or where dynamic movement is minimal.
- Hybrid Risers:Combining elements of both flexible and rigid risers, these systems manage complex flow assurance and thermal challenges.
Leading the category by volume: Flexible Risers. Growing fastest: Hybrid Risers.
Installation Type:
The operational environment profoundly influences riser design and material selection, with extreme depths posing unique engineering challenges for system integrity.
- Deepwater:Installations in water depths exceeding 1,500 meters demand advanced materials and designs to withstand immense hydrostatic pressures and extreme temperatures. Brazil's pre-salt and the Gulf of Mexico drive demand for specialized deepwater riser systems.
- Offshore:This segment includes conventional platforms and floating production units in shallower to mid-range water depths, focusing on robust and cost-effective solutions. The North Sea and Southeast Asia represent significant offshore markets for riser maintenance and life extension services.
- Onshore:Riser systems for land-based oil and gas wells are generally less complex, focusing on material durability and ease of maintenance.
- Subsea:This category encompasses riser components directly integrated with seabed infrastructure, managing critical connections to surface facilities.
Deepwater installations represent the most technically demanding segment, while Subsea applications are expanding most quickly.
End User:
Strategic investments by major energy companies are diversifying riser applications beyond traditional hydrocarbon extraction.
- Oil & Gas:This sector remains the primary end-user for risers, deploying them for drilling, production, and export operations in both conventional and unconventional fields. Sustained activity in deepwater exploration and mature basin life extension drives demand for high-integrity riser systems.
- Renewable Energy:The expansion of floating offshore wind farms creates a significant new market for dynamic power cables and specialized riser-like systems. European waters, particularly the North Sea, are leading the development and deployment of these innovative solutions.
- Marine:Specialized vessels, research platforms, and naval applications require bespoke riser systems for fluid transfer or data transmission.
- Industrial:Niche industrial applications, such as chemical processing plants or desalination facilities, utilize specialized risers for specific fluid handling needs.
The Oil & Gas sector commands the largest share of riser demand, with Renewable Energy showing the steepest expansion trajectory.
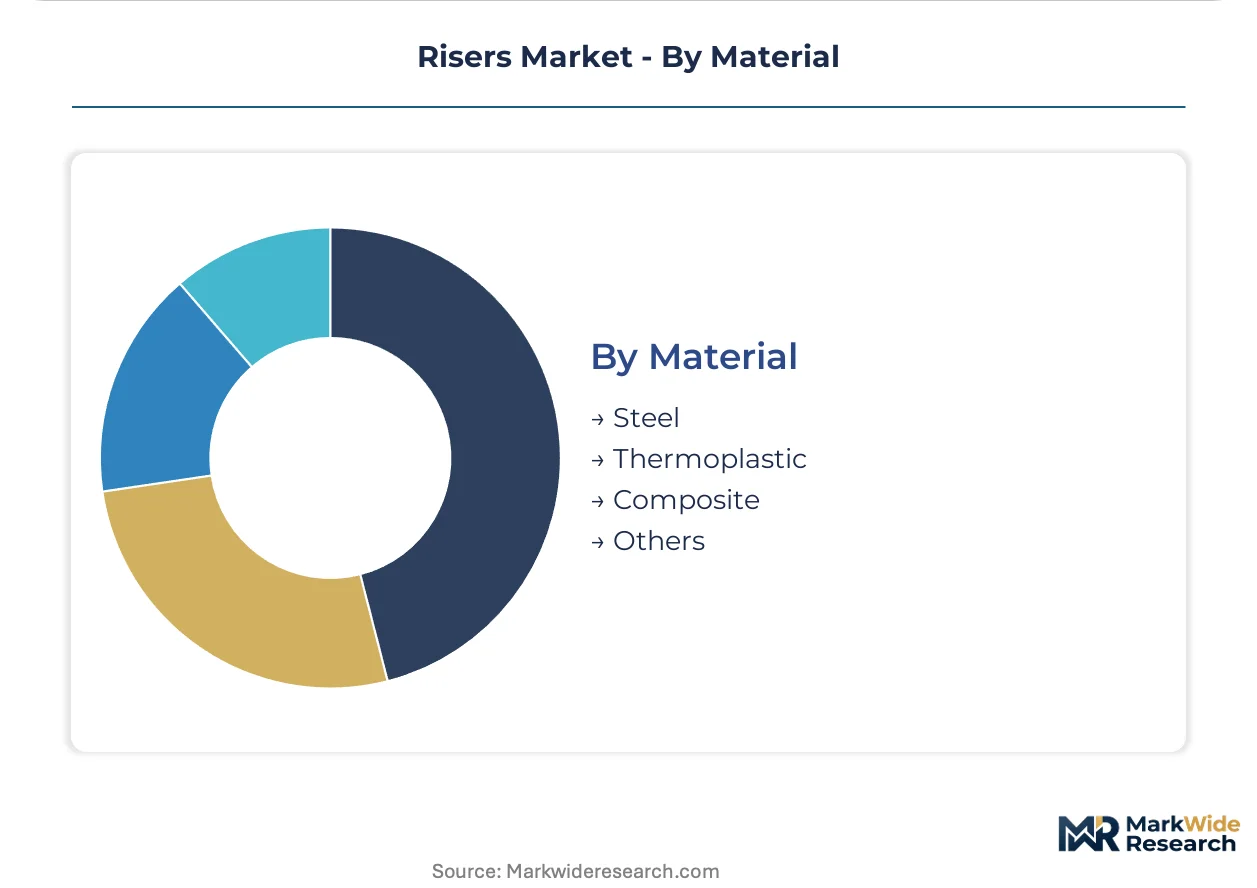
Material:
Material selection fundamentally impacts riser performance, lifecycle costs, and operational feasibility in extreme environments.
- Composite:These advanced materials offer superior strength-to-weight ratios, corrosion resistance, and fatigue performance compared to traditional steel. Demand for composite risers is concentrating in ultra-deepwater fields and high-fatigue environments, enabling reduced topside loads on floating production units.
- Steel:Conventional steel remains a foundational material for risers due to its proven strength, widespread availability, and cost-effectiveness for many applications. Shallow water and rigid riser systems continue to rely heavily on steel for its established integrity record.
- Thermoplastic:Used primarily in flexible pipes, thermoplastic materials provide good chemical resistance and are suitable for moderate water depths.
- Others:This segment includes specialized alloys like titanium for stress joints and other high-performance components, catering to niche applications with extreme requirements.
Composite materials are displacing traditional Steel in demanding deepwater applications, driven by enhanced performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in new offshore projects profoundly influences regional riser market dynamics. Deepwater exploration, particularly in hydrocarbon-rich basins, drives significant investment in advanced riser systems. Emerging floating offshore wind projects also create new demand vectors for specialized riser-like systems.
Brazil
Brazilian national regulators enforce stringent safety and environmental standards for offshore operations. Sustained deepwater exploration in the pre-salt basins drives significant demand for flexible and steel catenary risers. The Santos Basin, off the coast of Rio de Janeiro, remains a focal point for new ultra-deepwater installations.
United States
Deepwater activity in the Gulf of Mexico necessitates high-specification riser systems for challenging environments. American Petroleum Institute (API) standards guide product development and operational integrity across the region. Houston's energy hub supports extensive engineering and supply chain infrastructure for Gulf Coast projects.
United Kingdom
The North Sea basin requires continuous investment in riser life-extension services for aging infrastructure. The UK's Health and Safety Executive (HSE) mandates rigorous integrity management programs for all offshore assets. Aberdeen serves as a key operational base for both traditional oil and gas and emerging floating wind farm developments.
Norway
Norway's deepwater exploration in the Norwegian Sea and Barents Sea demands robust riser solutions capable of Arctic conditions. The Norwegian Petroleum Directorate oversees strict regulatory compliance for all offshore installations. Stavanger's offshore industry cluster drives innovation in subsea technology and high-pressure riser systems.
Guyana
New offshore projects in Guyana's prolific Stabroek Block are fueling demand for ultra-deepwater riser technologies. The country's Environmental Protection Agency establishes guidelines for sustainable and safe hydrocarbon extraction. Georgetown is rapidly expanding its port and logistics infrastructure to support these large-scale deepwater developments.
Risers Market Key Industry Players
Strategic partnerships and integrated solution offerings dominate the current landscape, reflecting a shift towards turnkey project delivery. The market structure exhibits consolidation among a few large players, alongside specialized innovators. Key archetypes include integrated engineering contractors, advanced material specialists, and dedicated subsea service providers. Companies increasingly pursue technology licensing and portfolio diversification to enhance their competitive positioning.
Within the integrated solution provider archetype, TechnipFMC and Aker Solutions exemplify companies offering comprehensive engineering and manufacturing capabilities for complex riser systems. TechnipFMC leverages its integrated approach across the subsea value chain, while Aker Solutions focuses on specialized lightweight solutions for demanding topside load requirements. Oceaneering International further anchors the specialized subsea services segment, providing crucial inspection, maintenance, and repair solutions that extend asset life and ensure operational integrity. These entities collectively represent the market's reliance on deep technical expertise and integrated project execution for demanding deepwater applications.
| Leading Market Players |
|---|
| Aker Solutions |
| TechnipFMC |
| Subsea 7 |
| Oceaneering International |
| Prysmian Group |
| Nexans |
| DeepOcean |
| Actuant Corporation |
| ExxonMobil |
| Others |
Cost & Logistics Intelligence
Steel commodity price fluctuations directly influence the cost base for rigid and steel catenary risers, creating distinct pricing tiers across the market. This impact cascades through the supply chain, affecting final product pricing.
Pricing Analysis
Volume-driven segments like conventional steel risers experience tighter margins, while specialized composite systems command premium pricing. The dominant pricing model involves project-based contracts for integrated riser solutions, particularly in deepwater projects. Price differentiation stems from advanced material science capabilities, stringent API and ISO certification levels, and customization for extreme operating environments. Pricing softness affects standard steel risers due to widespread availability, whereas major energy companies prioritize long-term operational savings over upfront cost for high-performance composites.
Supply Chain Analysis
Reverse-logistics for riser life-extension services and refurbishment flows are critical for aging infrastructure in mature basins like the North Sea. Manufacturing expertise for high-specification flexible and hybrid risers concentrates in a few specialized facilities, often located near deepwater hubs in the United States and Norway. The supply chain relies on high-grade steel alloys and advanced composite fibers, sourcing from global specialists. This concentration creates single-source vulnerability for critical components and limits pricing leverage for buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The risers market is fundamentally a cost-of-compliance story, where stringent regulations like API Recommended Practice 17N create a significant barrier-to-entry moat for new participants. This ensures only certified, high-integrity solutions reach the market.
For Market Incumbents:Anchor integrated engineering and manufacturing capabilities to counter technical integration challenges with older subsea infrastructure. Incumbents should strategically invest in advanced composite material science R&D, securing intellectual property for next-generation riser designs. Expanding life-extension services for aging assets in mature basins like the North Sea provides a stable revenue stream. Prioritizing API and ISO certification investments reinforces market leadership and compliance.
For New Entrants and Emerging Players:Begin with specialized niche applications, particularly in the rapidly expanding floating offshore wind sector where dynamic power cables are needed. New entrants can target the integration of fiber optic sensors for digital twins, offering real-time integrity monitoring services. The most penetrable segment involves bespoke components for renewable energy projects, where material flexibility and sensor integration are paramount. A strong go-to-market angle involves collaborating with established renewable energy developers to co-develop specialized solutions.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized subsea service providers in mature regions like the North Sea, where life-extension demand is high. The long-term viability centers on companies with strong material science capabilities or integrated digital twin platforms. Investors should identify acquisition targets among niche technology firms offering innovative composite solutions or predictive maintenance software. A critical signal to watch is the extensive certification delays for novel riser designs, indicating regulatory hurdles.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Composite Riser Manufacturing Capacity | Reduces procurement bottlenecks for ultra-deepwater projects in high-demand regions. |
| License Advanced Composite Material Patents | Expands market reach for specialized composite formulations and reduces R&D costs. |
| Form Strategic Partnerships with Floating Wind Developers | Secures early access to emerging dynamic power cable and specialized riser projects. |
| Launch Fiber Optic Sensor-Integrated Riser Systems | Establishes leadership in real-time asset integrity monitoring and predictive maintenance. |
| Implement Green Certification for Manufacturing Processes | Attracts operators prioritizing environmental, social, and governance compliance in procurement. |
Research Approach
Independent corroboration across API standards documents, HSE guidance, and corporate financial disclosures underwrites the qualitative findings within this analysis. Primary research involved interviews with subsea engineers, procurement managers, R&D directors, and project developers. This was complemented by secondary data from industry journals, patent databases, and government energy statistics. A rigorous bottom-up and top-down triangulation approach validated all data.
Rate-of-change decomposition analyzed market evolution across the analysis window, projecting future growth trajectories. Segmentation dimensions modeled included product type, installation type, end-user, material, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data and projected market shifts. Key forecast inputs included deepwater exploration budgets and floating offshore wind project pipelines.
Underlying measurement precision varies by segment; deepwater and composite segments carry tighter precision than others. Forecasts reflect assumptions regarding geopolitical stability and commodity price trajectories. Practitioners should monitor new regulatory mandates and material science breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Roofing Underlayment Market