
 Amphibious Excavator Market | 2026-2036
Amphibious Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious Excavator Market Analysis
Chinese pontoon fabricators is realigning global component supply for amphibious undercarriage systems. Wetland Equipment Company leverages its specialized pontoon manufacturing to anchor North American aftermarket service networks. Volvo Construction Equipment AB sustains technology leadership through integrated hydraulic-electric hybrid architectures. EIK International Corporation dominates Southeast Asian distribution channels with localized assembly operations.
An amphibious excavator consists of a standard tracked or wheeled excavator mounted on sealed pontoon hulls, typically fabricated from high-tensile steel with 2-5 mm thickness ratings and buoyancy capacities exceeding 15,000 kg, enabling operation in water depths up to 2.5 meters while maintaining ground pressure below 0.3 kg/cm² for sensitive terrain. Long reach excavators lead the product type category due to extended boom configurations essential for dredging and shoreline stabilization projects. Environmental agencies represent the fastest-growing end user segment as regulatory mandates for wetland mitigation expand across multiple jurisdictions. Hydraulic systems technology retains the largest installed base, though electric drive configurations are gaining traction in noise-restricted marine deployment zones.
The EPA enforces Section 404 permitting under the Clean Water Act, directly constraining equipment specifications for wetland disturbance projects and compelling contractors toward low-ground-pressure configurations. The EU Machinery Directive and CE marking requirements govern safety standards for amphibious equipment sold in European member states, while Indonesia's Ministry of Environment and Forestry imposes domestic content thresholds on conservation machinery procurement. Stakeholders must monitor evolving carbon border adjustments and local content rules that will reshape competitive access across priority wetland restoration markets.
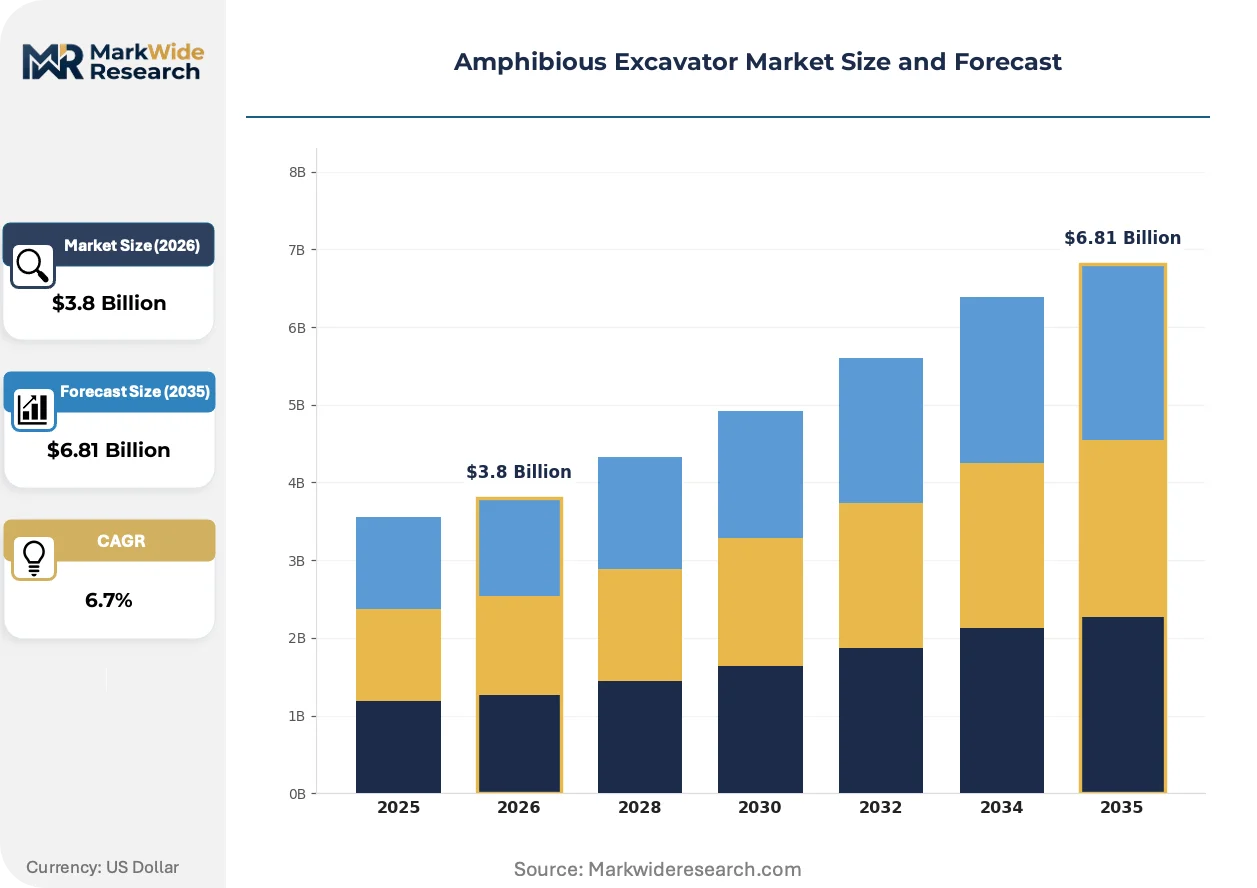
Market Dynamics
Hydraulic-electric hybrid architectures are compressing replacement cycles across contractor fleets, while EPA Section 404 permitting mandates under the Clean Water Act force specification upgrades toward low-ground-pressure configurations.
Growth Catalysts
- EPA Clean Water Act Section 404:Federal wetland disturbance permitting mandates compel contractors toward specialized low-ground-pressure equipment configurations for compliance.
- Mangrove Conservation Programs:Indonesia and Vietnam channel public conservation budgets into flood control and shoreline stabilization machinery procurement.
- Hydraulic System Upgrades:Technology refresh cycles accelerate as legacy mechanical systems face efficiency and emissions thresholds.
Market Restraints
- High-Tensile Steel Price Volatility:Pontoon hull fabrication depends on specialized steel grades with 2-5 mm thickness ratings, exposing manufacturers to raw material cost swings.
- Chinese Pontoon Fabricator Concentration:Global undercarriage system component supply concentrates among a limited base of specialized Asian suppliers.
- Buoyancy Capacity Limits:Current sealed pontoon designs cap operational water depths at 2.5 meters, constraining deployment in deeper wetland restoration zones.
Strategic Opportunities
- Electric Drive Noise-Restricted Zones:Marine deployment areas with acoustic sensitivity create openings for battery-electric propulsion configurations.
- Indonesia Domestic Content Thresholds:Ministry of Environment and Forestry procurement rules favor localized assembly operations for conservation machinery.
- Aftermarket Service Network Expansion:Specialized pontoon maintenance capabilities remain underdeveloped across North American distributor channels.
Industry Challenges
- Welding Certification for Pontoon Sealing:Specialized high-tensile steel fabrication demands qualified technicians scarce in many regional equipment service markets.
- EU Machinery Directive CE Marking Timelines:European safety standard compliance extends product launch cycles for amphibious equipment entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious Excavator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Excavators, Long Reach Excavators, Hybrid Excavators, Mini Excavators End User: Construction Companies, Environmental Agencies, Agricultural Enterprises, Mining Operations Deployment: Onshore, Offshore, Wetland, Marine Technology: Hydraulic Systems, Electric Drive, Automation, Remote Control |
| Companies Covered | Wetland Equipment Company, Volvo Construction Equipment AB, EIK International Corporation, Waterking BV, Doosan Infracore, Ultratrex Machinery Sdn. Bhd., Liebherr-International AG, Wilco Manufacturing, L.L.C., Hitachi Construction Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious Excavator Market Emerging Trajectories
Equipment architecture is bifurcating between hydraulic legacy systems and electric-hybrid platforms, with regulatory pressure and operational noise constraints driving specification divergence across end-use verticals.
Hydraulic-electric hybrid powertrains are integrating sealed electric drive motors with conventional hydraulic boom circuits to reduce acoustic signatures in sensitive wetland zones. Environmental agencies operating under EPA mandates specify these configurations for nighttime and wildlife-adjacent projects. The technology is integrating noise compliance into standard procurement specifications, compressing the addressable market for pure hydraulic alternatives.
EPA Section 404 permitting enforcement is tightening equipment documentation requirements for ground pressure ratings below 0.3 kg/cm². Contractors must now submit verified buoyancy specifications and hull material certifications with each wetland disturbance application. Long reach excavator configurations face heightened scrutiny due to extended boom leverage effects on terrain compression.
Service contract unbundling is separating pontoon hull maintenance from base machine warranties, creating independent aftermarket channels. Large environmental contractors in the United States negotiate standalone hull refurbishment agreements with specialized fabricators. This pattern concentrates service revenue among regional specialists rather than original equipment distribution networks.
Amphibious Excavator Market Segmentation
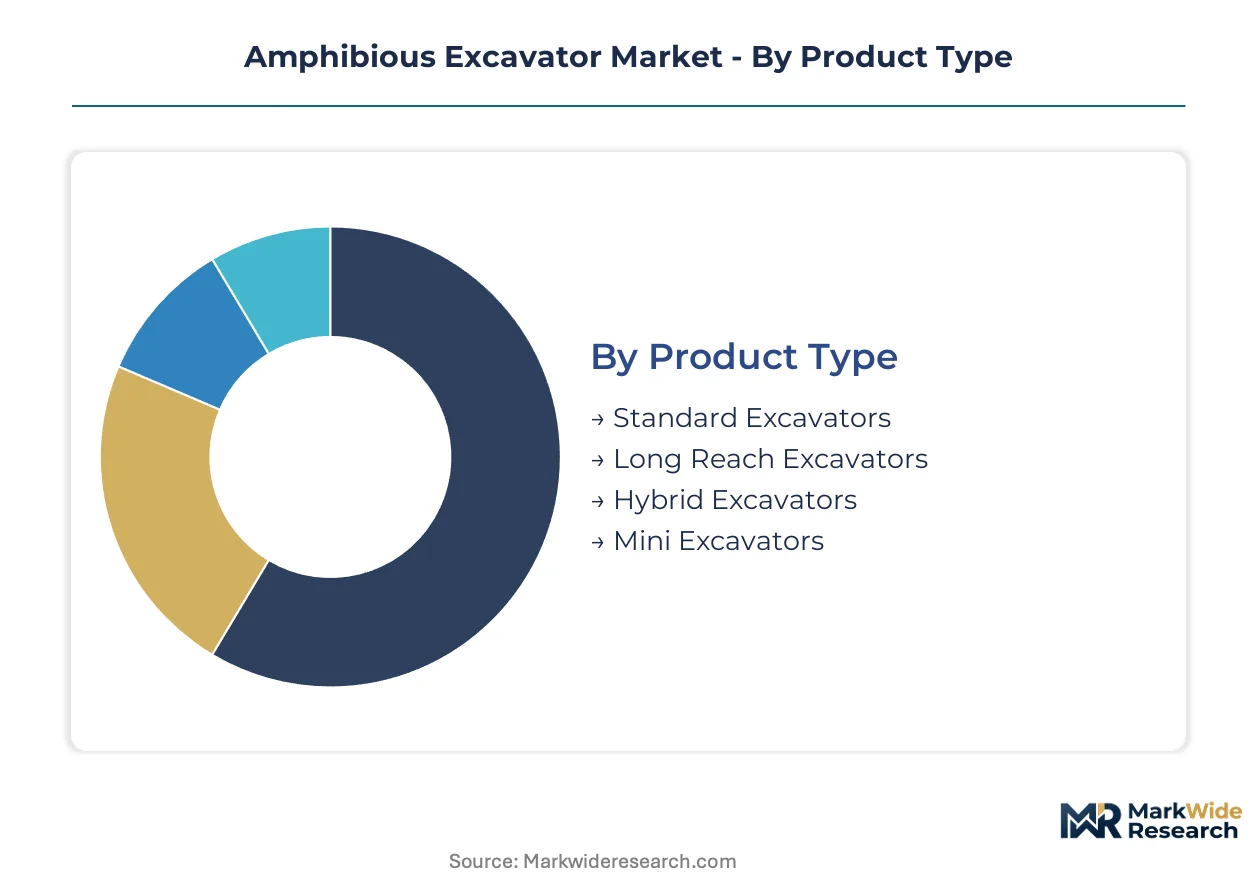
Amphibious excavator procurement splits across four distinct category axes, with equipment specification and regulatory burden varying sharply by deployment environment and powertrain architecture. Contractors and environmental agencies navigate divergent certification requirements across these segments.
Product Type:
CE marking under the EU Machinery Directive applies differentially across product configurations, with long reach variants facing extended compliance timelines due to modified structural load certifications.
- Long Reach Excavators:Extended boom configurations reaching 15-22 meters enable dredging operations and shoreline stabilization without hull repositioning. Environmental agencies in Indonesia and Vietnam specify these for mangrove conservation projects where water depth fluctuates seasonally.
- Hybrid Excavators:Dual hydraulic-electric powertrains integrate sealed electric drive motors with conventional boom circuits, reducing acoustic signatures below 75 decibels for wildlife-adjacent deployments. EPA Section 404 permitting mandates increasingly specify these configurations for nighttime wetland work.
- Standard Excavators:Conventional boom geometry suits general-purpose wetland construction with ground pressure ratings at or below 0.3 kg/cm².
- Mini Excavators:Compact pontoon hulls under 8,000 kg buoyancy capacity target confined waterway maintenance and small-scale agricultural drainage.
Long reach excavators sit at the top of the volume ranking, with hybrid excavators climbing the fastest.
End User:
Cost tier stratification separates capital-intensive fleet procurement from project-based rental arrangements, with environmental agencies commanding premium specifications through mandated compliance budgets.
- Environmental Agencies:Federal and state wetland restoration programs under EPA Clean Water Act Section 404 drive specification toward low-ground-pressure hull configurations with verified buoyancy documentation. These entities prioritize equipment with integrated telemetry for regulatory reporting.
- Construction Companies:General contractors balance purchase price against rental flexibility, with larger firms maintaining captive fleets for recurring shoreline infrastructure work while smaller operators rely on regional equipment lessors.
- Agricultural Enterprises:Drainage district cooperatives and large farming operations deploy mini and standard configurations for irrigation canal maintenance and flood control berms.
- Mining Operations:Open-pit and alluvial extraction sites in Southeast Asia utilize long reach variants for tailings pond management and sediment removal.
Construction companies anchor the installed base by unit count, with environmental agencies gaining share fastest on regulatory mandate expansion.
Deployment:
Application severity dictates hull material specifications and sealing certification intensity, with marine environments imposing the most stringent fabrication standards.
- Wetland:Shallow water operations up to 2.5 meters depth with sensitive substrate protection requirements dominate procurement volumes. EPA ground pressure verification and hull material certification accompany every Section 404 permit application.
- Marine:Saltwater exposure demands specialized corrosion-resistant coatings and enhanced pontoon sealing protocols, extending maintenance intervals but raising initial capital outlay.
- Onshore:Transitional marsh-edge work where equipment alternates between saturated and dry terrain stresses undercarriage durability.
- Offshore:Limited deployment for coastal protection and artificial reef construction, constrained by current buoyancy capacity ceilings.
Wetland deployment commands the largest equipment population, with marine applications expanding most quickly on coastal resilience infrastructure.
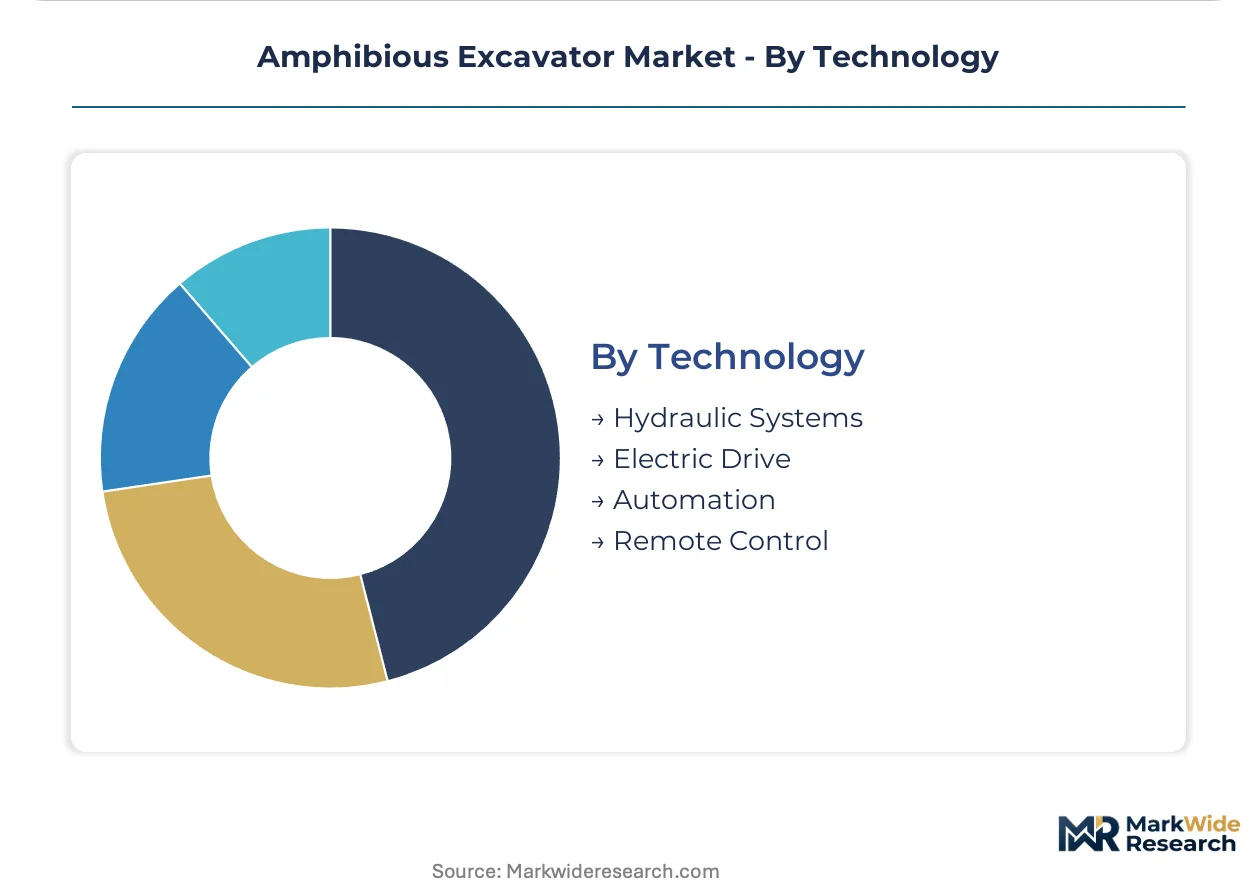
Technology:
Supply concentration in hydraulic component manufacturing contrasts with emerging electric drive localization, reshaping procurement geography for powertrain subsystems.
- Hydraulic Systems:Legacy architecture retains the largest installed base, with piston pump and valve assemblies sourced primarily from established European and Japanese suppliers. Efficiency and emissions thresholds now compress replacement cycles for aging mechanical systems.
- Electric Drive:Battery-electric and hybrid configurations gain specification share in noise-restricted marine deployment zones and European markets under tightening acoustic regulations. Chinese pontoon fabricators are realigning supply chains to accommodate electric motor integration.
- Automation:Semi-autonomous boom positioning and depth control systems reduce operator fatigue in repetitive dredging operations.
- Remote Control:Radio-linked operation enables hazardous environment deployment without onboard personnel, particularly in unstable substrate conditions.
Hydraulic systems maintain the dominant technology position, with electric drive configurations gaining share fastest on regulatory pressure and total cost of ownership improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting pontoon fabrication capacity toward jurisdictions with lower environmental compliance burdens, while equipment procurement concentrates in markets with active wetland restoration mandates and flood control infrastructure programs.
United States
EPA Clean Water Act Section 404 enforcement drives fleet modernization across federal and state environmental agencies, with wetland restoration contractors in the Gulf Coast corridor and Florida Everglades region upgrading to low-ground-pressure configurations. The Army Corps of Engineers maintains specification authority over dredging equipment deployed in navigable waters.
Indonesia
Mangrove conservation programs and flood control infrastructure channel public procurement budgets toward specialized amphibious machinery, with the Ministry of Environment and Forestry imposing domestic content thresholds that favor localized assembly operations. Java-based fabricators are expanding pontoon production capacity to meet conservation machinery demand.
Vietnam
Shoreline stabilization projects in the Mekong Delta and Red River Delta drive long reach excavator procurement, with the Ministry of Agriculture and Rural Development coordinating flood control equipment specifications. Da Nang and Ho Chi Minh City serve as distribution hubs for conservation machinery serving coastal resilience programs.
Germany
EU Machinery Directive CE marking requirements and tightening acoustic regulations in protected wetland zones create specification pull toward hybrid electric-hydraulic configurations. Bavarian and North Rhine-Westphalian environmental contractors source specialized equipment for Rhine basin floodplain restoration and noise-sensitive deployment zones.
China
Pontoon hull fabrication capacity concentrates in Yangtze River Delta manufacturing clusters, with fabricators realigning component supply chains to accommodate electric drive motor integration. Domestic demand from wetland conservation programs in the Pearl River Delta complements export-oriented production for Southeast Asian markets.
Amphibious Excavator Market Vendor Landscape
Chinese fabricators anchor the component supply tier; European and North American specialists hold equipment integration and aftermarket service positions. The vendor structure fragments across pontoon fabrication, base machine modification, and regional distribution layers rather than consolidating around full-system manufacturers. Three archetypes dominate: integrated construction equipment multinationals with amphibious product lines, specialized pontoon fabricators supplying modification kits, and regional assemblers serving domestic content requirements. Competitive moves center on strategic partnerships between base machine OEMs and pontoon specialists, plus geographic expansion through localized assembly operations.
Among integrated equipment manufacturers, Volvo Construction Equipment AB and Liebherr-International AG represent the premium-tier archetype with in-house hydraulic system development and established CE marking compliance pathways. Wetland Equipment Company and EIK International Corporation exemplify the specialized fabricator model, with the former anchoring North American aftermarket service networks and the latter occupying a position within Southeast Asian distribution channels through localized assembly. Doosan Infracore and Hitachi Construction Machinery Co., Ltd. sit within the construction equipment multinational tier, leveraging existing excavator platforms for amphibious modification partnerships.
| Leading Market Players |
|---|
| Wetland Equipment Company |
| Volvo Construction Equipment AB |
| EIK International Corporation |
| Waterking BV |
| Doosan Infracore |
| Ultratrex Machinery Sdn. Bhd. |
| Liebherr-International AG |
| Wilco Manufacturing, L.L.C. |
| Hitachi Construction Machinery Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
High-tensile steel price indices cascade through amphibious excavator supply chains, compressing margins for pontoon fabricators while amplifying pricing power for integrated manufacturers with captive steel sourcing. Equipment procurement stratifies across three tiers—premium hybrid-electric configurations for EPA-compliant environmental agencies, mid-grade hydraulic systems for construction contractors, and economy-class standard excavators for agricultural drainage cooperatives—with steel cost pass-through rates varying by buyer negotiation leverage.
Pricing Analysis
Distributor margins of 12-18 percent separate OEM delivered prices from end-user contract values, with aftermarket service bundling increasingly unbundled from base equipment warranties. Pricing stratifies across premium, standard, and economy tiers according to ground pressure certification level and hydraulic-electric hybrid integration depth. Cost compression in the standard tier intensifies because Chinese pontoon fabricators are expanding direct-to-contractor channels. Agricultural enterprises exhibit highest price sensitivity due to project-based utilization patterns, while environmental agencies accept premium pricing for verified Section 404 compliance documentation.
Supply Chain Analysis
Pontoon hull fabrication rests on high-tensile steel sheet supply from Chinese Yangtze River Delta mills, German specialty steel producers, and Japanese precision rolling operations. Critical inputs include 2-5 mm thickness rated steel grades, sealed welding consumables certified for marine environments, and hydraulic piston pump assemblies sourced primarily from European and Japanese component houses. Single-source vulnerability concentrates in Chinese undercarriage system component supply, with tariff exposure on steel imports amplifying cost volatility. Distribution runs through regional equipment lessors and specialized aftermarket service networks rather than consolidated national dealer chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amphibious excavator market represents a late-cycle quality story as EPA Section 404 enforcement and EU acoustic regulations shift procurement toward premium low-ground-pressure and hybrid-electric specifications. Equipment replacement cycles compress as compliance documentation requirements tighten across wetland restoration programs.
For Market Incumbents: Acquire specialized pontoon sealing and refurbishment capabilities to capture unbundled aftermarket service revenue migrating from base machine warranties. Backward integration into high-tensile steel inventory positions buffers margin compression from raw material volatility. Certification investment in CE marking and EPA ground pressure verification documentation defends positioning against emerging Asian assemblers with lower compliance overhead.
For New Entrants and Emerging Players: EPA Section 404 in the United States opens a window for niche contractors offering verified low-ground-pressure equipment rental with bundled permit documentation services. Indonesia's domestic content thresholds create white-space for localized assembly partnerships with Java-based fabricators. Target aftermarket service network gaps in North American distributor channels as the most penetrable entry vector, leveraging specialized welding certification capabilities scarce in regional equipment markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized pontoon fabricators possessing established CE marking pathways and EPA compliance documentation expertise. Long-term viability hinges on regulatory mandate durability across wetland restoration and flood control infrastructure programs. Watch EPA Section 404 enforcement intensity and Indonesia Ministry of Environment procurement volume as inflection indicators for premium specification demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Inventory | Captive high-tensile steel supply insulates margin compression from Yangtze Delta price volatility. |
| CE Marking Certification Investment | EU Machinery Directive compliance accelerates product launch timelines for European wetland restoration contracts. |
| Localized Assembly Partnership | Indonesia domestic content thresholds favor Java-based fabrication for Ministry of Environment procurement. |
| Aftermarket Service Network Expansion | Unbundled pontoon maintenance contracts concentrate revenue among regional specialists outside OEM distribution. |
| Hybrid-Electric Powertrain Development | Sealed electric drive integration captures EPA nighttime work specifications and EU acoustic regulation compliance. |
Methodological Framework
Bottom-up environmental agency and construction contractor fleet modeling reconciled against top-down pontoon fabrication capacity tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at federal and state wetland restoration programs, aftermarket service directors at regional distributor networks, plant engineers at Chinese Yangtze Delta fabricators, and hydraulic system technical directors at European component suppliers combined with secondary validation from EPA Section 404 permit filing databases, EU Machinery Directive CE marking registries, and Indonesian Ministry of Environment procurement disclosures. Bottom-up and top-down triangulation cross-validates equipment shipment volumes against end-user fleet expansion plans.
Input-output matrices map high-tensile steel consumption through pontoon hull fabrication into finished equipment deployment across wetland, marine, and onshore application segments over the projection horizon. Segmentation dimensions modeled include product type configuration, end-use vertical, deployment environment severity, and powertrain architecture. CAGRs derive from regression analysis of replacement cycle compression rates and regulatory mandate expansion trajectories. Industry-specific forecast inputs incorporate EPA Section 404 permit approval velocity and Indonesia domestic content threshold enforcement intensity.
Revisions become necessary when EPA enforcement intensity shifts, Chinese steel export policy changes, or Indonesia domestic content rules expand to neighboring Southeast Asian markets materialize. Forecasts reflect documented assumptions regarding regulatory mandate durability and raw material supply continuity. A small set of named triggers—EPA budget allocation volatility, EU acoustic regulation tightening schedules, and Yangtze Delta environmental compliance enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Trenchers Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Boom Cranes Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Global Crane Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Philippines Construction Equipment Market