
 Drainage System Market | 2026-2036
Drainage System Market Size, Share, and Industry Trends Forecast 2026-2036
Drainage System Market Foresight
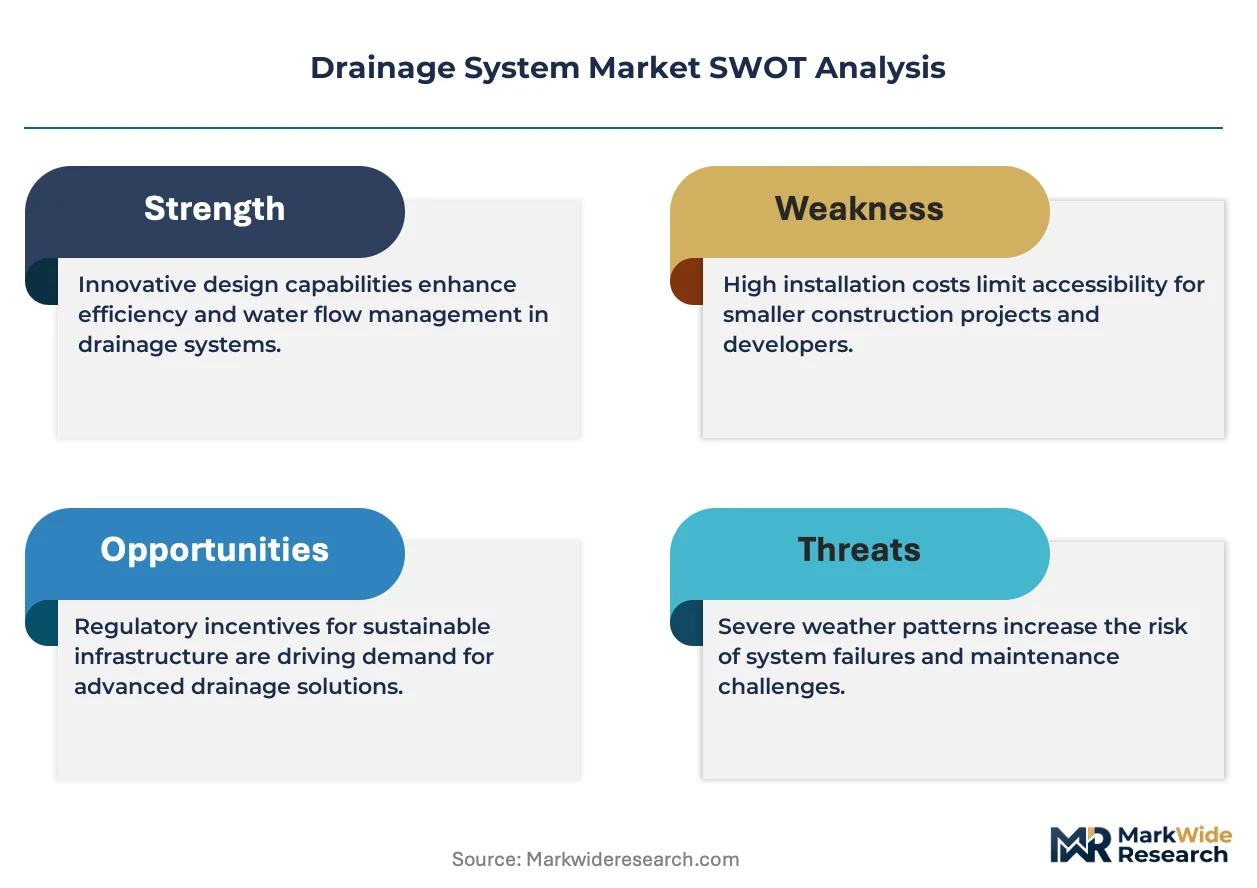
The EU Green Deal's urban runoff directives is rebalancing material specifications across European public procurement. Polypipe Group Plc leverages its thermoplastic manufacturing scale to supply large-diameter channel systems for infrastructure retrofits. Wavin Group anchors its position through backward integration into recycled polymer feedstocks, lowering embodied carbon in trench drain products. Advanced Drainage Systems Inc. dominates the North American corrugated plastic pipe segment with in-house resin compounding capabilities that control cost volatility.
A drainage system comprises engineered conduit networks, collection structures, and filtration media designed to convey surface water, groundwater, or wastewater away from built environments at controlled flow rates typically measured in gallons per minute per square foot of drainage area. These systems prevent structural damage, reduce flood risk, and protect water quality through gravity-driven or pumped conveyance to treatment facilities or natural receiving waters. Trench drains lead commercial and industrial specification due to their modular installation and high hydraulic capacity, while French drains sustain residential demand for foundation moisture control in clay-heavy soils. Plastic materials, particularly high-density polyethylene and polypropylene, are displacing concrete in new construction because of lighter handling weights and longer joint integrity, though concrete retains margin pools in heavy-load airport and port applications.
The EPA's National Pollutant Discharge Elimination System and the EU's Water Framework Directive shape product standards by mandating stormwater quality controls that filter oils, sediments, and heavy metals before discharge. Germany's KBA and state-level building codes in Bavaria and North Rhine-Westphalia enforce load-class certifications for channel drains in vehicular zones, creating compliance barriers for uncertified imports. Stakeholders must monitor how California's State Water Resources Control Board and India's Central Pollution Control Board tighten effluent limits, as these jurisdictions will determine which material formulations and filtration technologies gain preferential specification in the next procurement cycle.
Market Dynamics
The EU Green Deal's urban runoff directives are compressing specification timelines for sustainable drainage infrastructure, forcing municipal procurement departments to accelerate material transitions from concrete to thermoplastic systems while maintaining load-class certifications.
Growth Catalysts
- EPA National Pollutant Discharge Elimination System:Municipal stormwater management agencies across the United States face upgraded filtration mandates, expanding specification of oil-grit separators and sediment traps in commercial developments.
- Ruhr industrial corridor replacement cycle:Germany's aging combined sewer networks require wholesale infrastructure renewal, concentrating demand for large-diameter channel systems and modular trench drains.
- High-density polyethylene pipe extrusion:Lighter handling weights and improved joint integrity accelerate adoption in residential foundation drainage and agricultural field tile applications.
Market Restraints
- Recycled polymer feedstock volatility:Wavin Group's backward integration into post-consumer polypropylene supply chains highlights concentration risk when oil-price swings disrupt secondary raw material availability.
- KBA load-class certification barriers:Germany's federal motor transport authority enforces DIN 19580 testing protocols for channel drains in vehicular zones, creating compliance friction for uncertified imports from non-EU manufacturing bases.
- Concrete retention in heavy-load applications:Airport runways and port container yards maintain concrete specification for trench drains due to fatigue resistance requirements that thermoplastics have not yet matched.
Strategic Opportunities
- India's Central Pollution Control Board effluent tightening:Anticipated stormwater quality mandates in industrial corridor cities create specification windows for filtration-integrated drainage systems before domestic supply chains mature.
- Permeable pavement convergence with subsurface storage:Municipal green infrastructure programs in California and New York integrate modular plastic infiltration chambers with surface porous asphalt, requiring coordinated channel system design.
- Digital procurement platforms for public infrastructure:State-level transportation departments in Bavaria and North Rhine-Westphalia pilot e-tendering systems that reduce specification friction for certified drainage component vendors.
Industry Challenges
- Geotechnical engineering skill scarcity:Design of hybrid gravity-pumped systems for clay-heavy soils requires subsurface drainage expertise that consulting firms struggle to staff across municipal project pipelines.
- ISO 13008 certification timeline compression:Accelerated product qualification cycles for recycled-content drainage products strain laboratory testing capacity at notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drainage System Market |
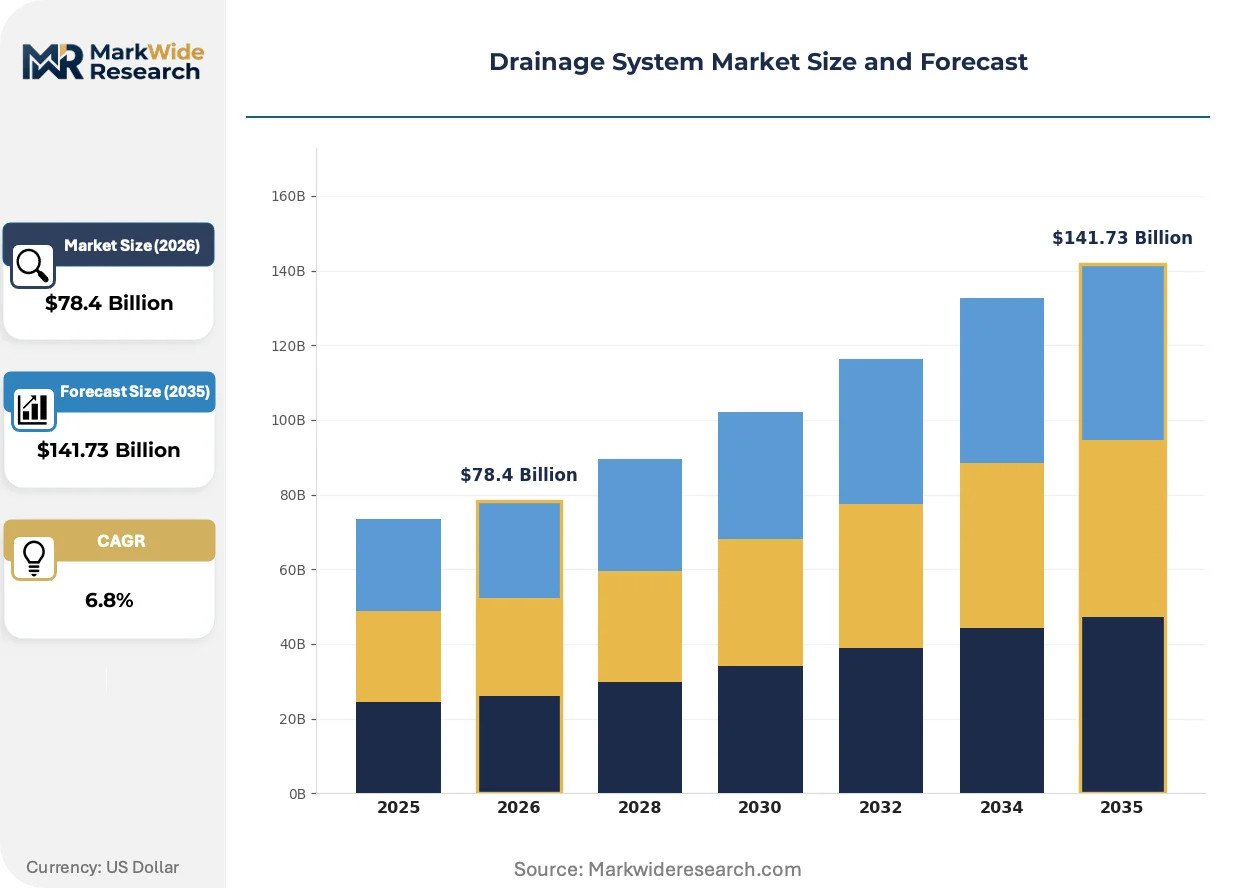
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: French Drains, Channel Drains, Trench Drains, Catch Basins Material: Plastic, Concrete, Metal, PVC Installation Type: Residential, Commercial, Agricultural, Industrial End User: Homeowners, Contractors, Municipalities, Developers |
| Companies Covered | Polypipe Group Plc, Contech Engineered Solutions, Advanced Drainage Systems Inc., MIFAB Inc., NDS, Wavin Group, ACO Group, Hauraton GmbH And Co. KG, Geberit AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drainage System Market Shifts & Advancements
Material science advances and digital specification tools are compressing product development cycles while regulatory fragmentation forces manufacturers to maintain parallel certification portfolios across jurisdictions.
Corrugated high-density polyethylene pipe is consolidating market share in agricultural and residential drainage applications. Farm operators and residential contractors specify HDPE field tile and foundation perimeter systems for snap-joint installation speed. This material transition is consolidating regional manufacturing footprints around resin compounding facilities that control feedstock cost exposure.
REACH restrictions on persistent organic pollutants in plastic additives are forcing reformulation of UV stabilizers and impact modifiers in European-sourced drainage products. Compounders serving the Benelux and Nordic markets now prioritize bio-based stabilizer packages to preempt regulatory expansion. Trench drain manufacturers supplying German automotive plant expansions face the most acute compliance timeline pressure.
Asset management software integration is altering municipal procurement patterns for drainage infrastructure. Public works departments in California and Texas now require BIM-compatible product data and predictive maintenance algorithms alongside physical components. Distributors serving these agencies are restructuring field technical support teams to include GIS specialists who can model hydraulic performance across watershed-scale networks.
Drainage System Market Segmentation
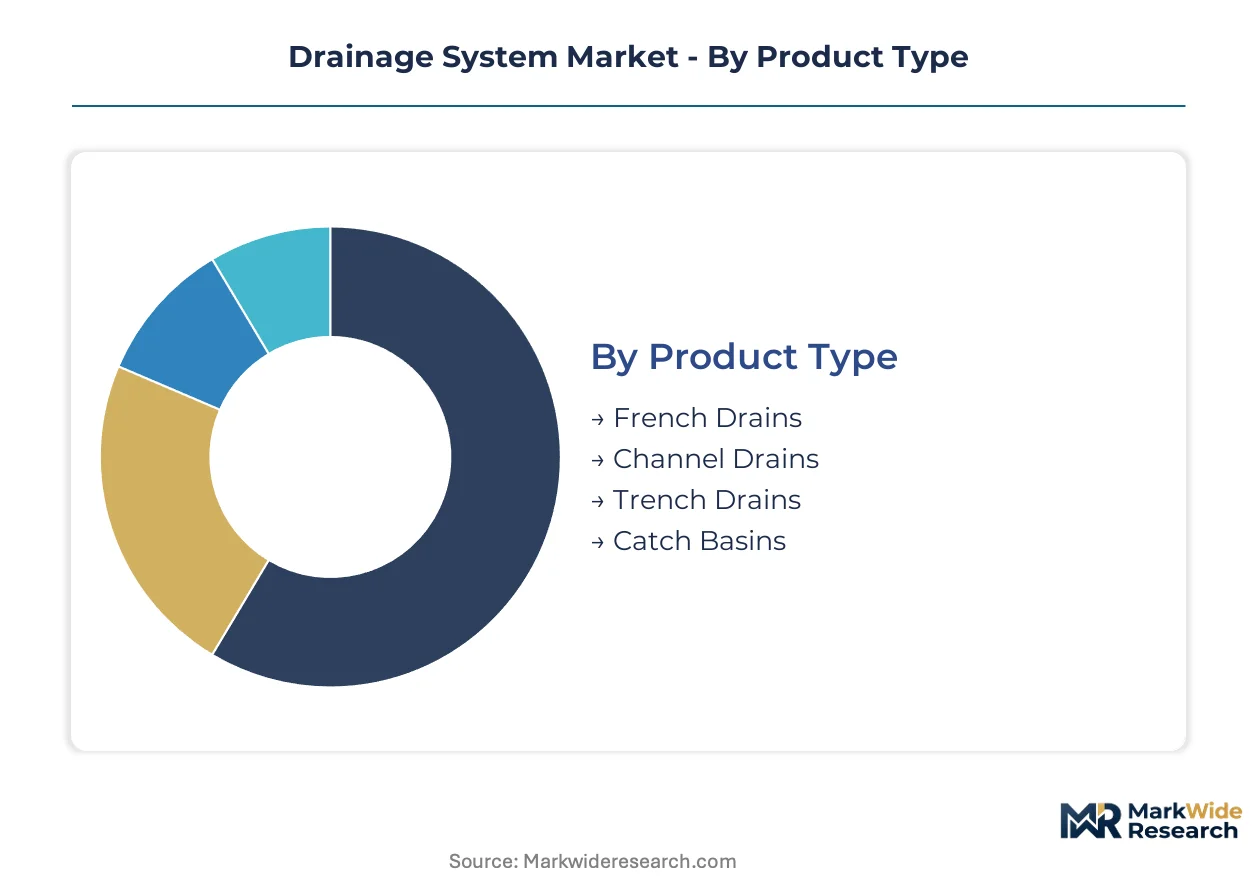
Drainage system procurement splits sharply between high-volume residential retrofit work and premium-specification municipal infrastructure. Material selection and installation complexity create distinct margin pools that manufacturers navigate through parallel product lines.
Product Type:
Volume concentrates in modular surface collection systems while premium engineering drives subsurface specification.
- Trench Drains:Modular channel systems with grated covers handle high hydraulic loads in commercial loading docks and food processing facilities. German automotive plant expansions in Bavaria and Baden-Württemberg specify stainless steel-edged polymer channels for chemical resistance and load-class DIN 19580 compliance.
- French Drains:Perforated pipe surrounded by aggregate media conveys groundwater away from building foundations in clay-heavy soils. Residential demand clusters in suburban developments across Texas and Georgia where expansive soils threaten structural integrity.
- Channel Drains:Linear surface collection systems with pre-sloped bases for gravity drainage.
- Catch Basins:Sump structures intercepting debris and sediment before conveyance to downstream pipes.
Today's leader: Trench Drains. Tomorrow's challenger: French Drains.
Material:
Cost tiers separate lightweight thermoplastics from fatigue-resistant rigid systems.
- Plastic:High-density polyethylene and polypropylene formulations dominate residential and agricultural specification. Snap-joint integrity and 60% weight reduction versus concrete accelerate installation in California municipal green infrastructure programs.
- Concrete:Reinforced polymer concrete and traditional Portland cement mixes retain specification in airport runways and port container yards. Fatigue resistance under dynamic aircraft loading exceeds current thermoplastic performance thresholds.
- Metal:Cast iron and galvanized steel gratings and frames for heavy-load vehicular zones.
- PVC:Rigid polyvinyl chloride pipe for residential foundation perimeter and agricultural field tile drainage.
Plastic holds volume leadership. Concrete defends premium positioning in heavy-load niches.
Installation Type:
Application complexity determines contractor skill requirements and project margin structure.
- Commercial:Integrated oil-grit separators and sediment traps serve retail parking lots and logistics hubs. EPA National Pollutant Discharge Elimination System filtration mandates expand specification in Texas and Florida development corridors.
- Municipal:Large-diameter combined sewer replacements dominate Germany's Ruhr industrial corridor procurement. Aging infrastructure in North Rhine-Westphalia cities drives channel system and infiltration chamber demand.
- Residential:Perimeter foundation and yard drainage for single-family homes.
- Agricultural:Subsurface field tile for farmland water table management.
Municipal commands project scale. Commercial offers fastest specification expansion.
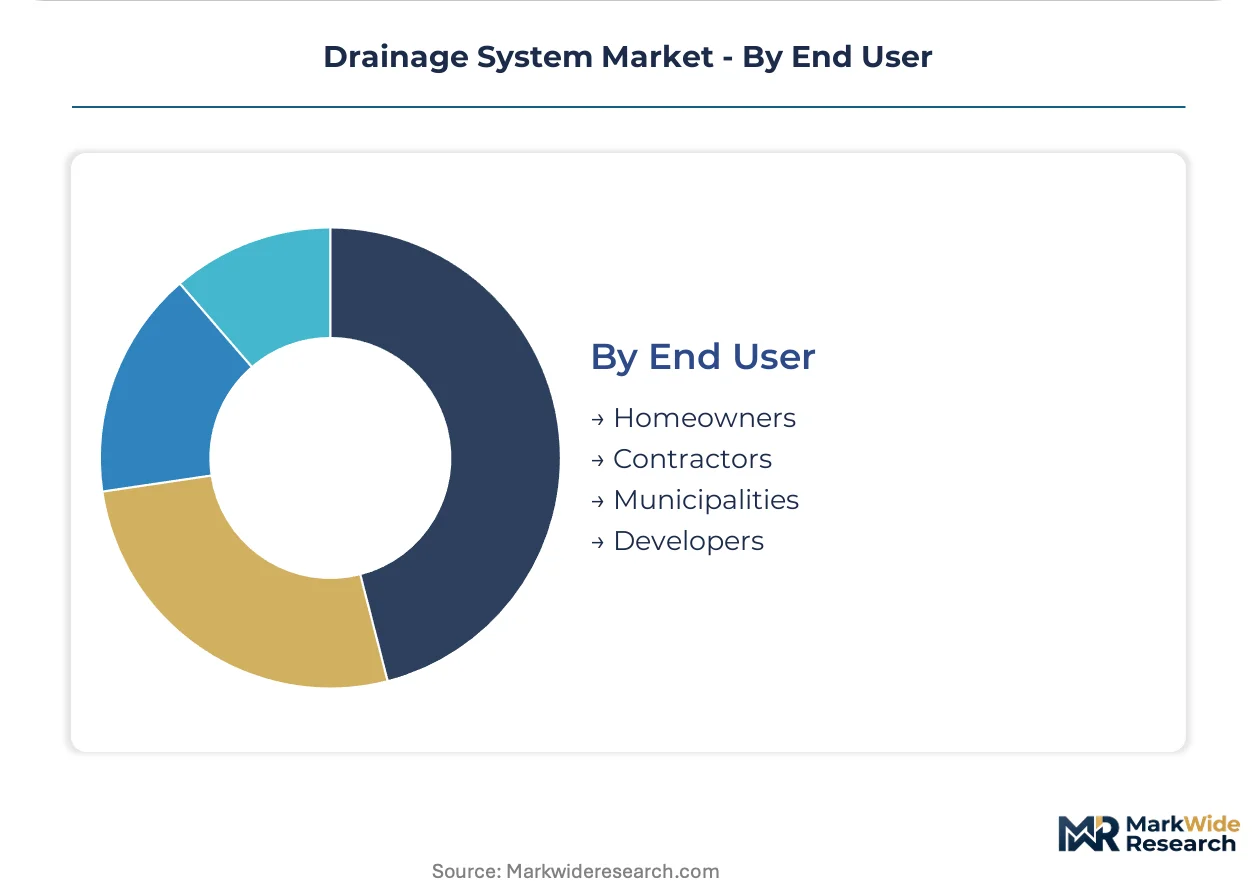
End User:
Procurement sophistication separates institutional buyers from price-sensitive retail channels.
- Municipalities:Public works departments specify BIM-compatible product data and predictive maintenance algorithms. California and Texas agencies now require GIS-integrated hydraulic modeling across watershed-scale networks.
- Contractors:Installation firms balance material cost against labor efficiency in competitive bidding. HDPE snap-joint systems reduce crew hours in residential foundation work across competitive Texas and Arizona markets.
- Homeowners:DIY retail purchasers of prefabricated drainage kits.
- Developers:Master-planned community builders integrating stormwater management into site design.
Municipalities drive technology adoption. Contractors mediate cost-performance tradeoffs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The drainage system industry traces its modern scale to post-war infrastructure reconstruction in Germany and the United States, where combined sewer networks and highway drainage standards first achieved industrial production volumes. Subsequent regulatory frameworks in both markets established certification protocols that now govern procurement across developed economies.
United States
EPA National Pollutant Discharge Elimination System upgrades are driving municipal stormwater filtration mandates in Texas and Florida development corridors. California's State Water Resources Control Board tightens effluent limits for commercial runoff. The Southeast suburban belt from Atlanta to Houston sustains residential French drain demand for expansive clay soil management.
Germany
Aging combined sewer networks in the Ruhr industrial corridor require wholesale replacement of channel systems and infiltration chambers. KBA enforces DIN 19580 load-class certifications for vehicular zone drainage, creating compliance barriers for uncertified imports. Bavarian automotive plant expansions specify stainless steel-edged polymer trench drains for chemical resistance.
China
Sponge City initiatives in 30 pilot municipalities mandate permeable pavement integration with subsurface storage systems. MEE stormwater quality directives tighten discharge standards for industrial corridor cities. Yangtze River Delta manufacturing hubs concentrate demand for large-diameter thermoplastic pipe in logistics park construction.
India
Anticipated Central Pollution Control Board effluent tightening in industrial corridor cities creates specification windows for filtration-integrated systems. Smart Cities Mission funding channels into stormwater management in Mumbai, Delhi, and Bangalore. Gujarat's petrochemical complexes drive demand for chemical-resistant channel drainage in processing facilities.
United Kingdom
Environment Agency flood resilience programs accelerate sustainable drainage adoption in new residential developments. Building Regulations Part H amendments tighten foundation drainage requirements for clay soil regions. Thames Gateway regeneration projects specify modular trench systems for commercial and logistics hub construction.
Drainage System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material formulation and installation specification tiers. The market structure concentrates around resin-compounding manufacturers with captive polymer supply chains, regional fabricators serving municipal procurement channels, and specialized designers of load-certified channel systems. Three archetypes dominate: integrated polymer producers controlling feedstock cost exposure, certification-heavy European specialists in vehicular-load drainage, and North American corrugated pipe manufacturers with distribution density. Competitive moves center on backward integration into recycled polymer feedstocks and BIM-compatible product data development for municipal digital procurement platforms.
Among integrated polymer producers, Advanced Drainage Systems Inc. exemplifies the resin-compounding archetype with in-house manufacturing capabilities that manage cost volatility. Wavin Group occupies a position within the recycled-content tier, representing backward integration into post-consumer polypropylene supply chains. Polypipe Group Plc anchors the large-diameter infrastructure retrofit segment, exemplifying scale-driven manufacturing for municipal channel system replacement cycles.
| Leading Market Players |
|---|
| Polypipe Group Plc |
| Contech Engineered Solutions |
| Advanced Drainage Systems Inc. |
| MIFAB Inc. |
| NDS |
| Wavin Group |
| ACO Group |
| Hauraton GmbH And Co. KG |
| Geberit AG |
| Others |
Supply & Pricing Matrix
Geotechnical engineering skill scarcity in Germany's Ruhr industrial corridor widens labor-cost differentials between premium-certified and standard-grade drainage installations, compressing margins for contractors bidding municipal retrofit work while elevating price spreads across specification tiers.
Pricing Analysis
Project-based contract pricing with volume-scaled discounts dominates municipal procurement, separating DIN 19580-certified channel systems for vehicular zones from uncertified residential-grade alternatives. Price differentiation rests on certification grade and geographic delivery cost, with KBA load-class compliance commanding substantial premiums over standard polymer channels. Cost compression in the residential tier is intensifying because HDPE snap-joint systems reduce crew hours and attract price-sensitive contractors in competitive Texas and Arizona markets. Homeowners represent the most price-sensitive buyer archetype, while municipalities with BIM-compatible procurement requirements exhibit lowest sensitivity.
Supply Chain Analysis
Certification gating through DIN 19580 and ISO 13008 testing protocols concentrates supply among notified-body-accredited manufacturers in Germany, the United States, and the Netherlands. Raw material dependencies draw from high-density polyethylene resin compounding, recycled polypropylene feedstocks, and Portland cement for heavy-load applications. Single-source vulnerability in post-consumer polymer supply chains creates exposure when oil-price swings disrupt secondary raw material availability. Distribution runs through municipal procurement departments, regional distributors with GIS-technical support capabilities, and contractor-direct channels for residential foundation work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drainage system market functions as a stable compounder, with EPA and EU regulatory mandates for stormwater quality controls ensuring replacement-cycle demand regardless of macroeconomic cyclicality.
For Market Incumbents: Deepen backward integration into recycled polymer feedstocks to insulate margin structures from resin price volatility, while accelerating BIM-compatible product data development to capture California and Texas municipal digital procurement shifts. Certification investment in DIN 19580 and ISO 13008 protocols defends position against lower-cost imports from non-EU manufacturing bases.
For New Entrants and Emerging Players: E-procurement platform partnerships offer a lower-friction route to municipal specification in Bavaria and North Rhine-Westphalia pilot programs, bypassing entrenched distributor relationships. Target India's industrial corridor cities before domestic supply chains mature for filtration-integrated drainage systems, leveraging anticipated Central Pollution Control Board effluent tightening as a specification window.
For Investors and Strategic Acquirers: Integrated polymer producers with captive resin compounding capabilities are the most active acquirer in this space, seeking to consolidate regional manufacturing footprints around feedstock cost control. Over a multi-year horizon, acquisition targets with notified-body certification portfolios and municipal agency relationships offer defensive cash-flow profiles. Watch California State Water Resources Control Board effluent limit revisions as an inflection indicator for filtration-technology specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstocks | Wavin Group's post-consumer polypropylene supply chains lower embodied carbon and reduce resin price exposure. |
| BIM-Compatible Product Data Development | California and Texas agencies now require predictive maintenance algorithms alongside physical drainage components. |
| DIN 19580 Certification Investment | Germany's KBA enforcement creates compliance barriers protecting certified manufacturers from uncertified import competition. |
| Digital Procurement Platform Integration | Bavarian e-tendering pilots reduce specification friction for drainage component vendors with pre-qualified technical data. |
| Filtration-Integrated System Design | EPA National Pollutant Discharge Elimination System upgrades expand oil-grit separator specification in commercial developments. |
Research Methodology
Bottom-up municipal and commercial installation modeling reconciled against top-down resin compounding and polymer pipe extrusion tracking forms the analytical core of this study. Primary interviews with municipal public works directors, contractor procurement leads, geotechnical consulting engineers, and drainage product distributors combined with secondary validation from EPA enforcement data, EU Green Deal implementation reports, DIN standards documentation, and state-level transportation department procurement records. Triangulation across these sources ensures segmentation integrity across product type, material formulation, and installation complexity tiers.
Historical trendline analysis of infrastructure replacement cycles and regulatory implementation timelines anchors the projection framework. The model segments volume and value across trench drains, French drains, channel drains, and catch basins; plastic, concrete, metal, and PVC materials; and commercial, municipal, residential, and agricultural installation types. CAGRs were derived from regression analysis of public procurement pipeline data and polymer feedstock cost trajectories. Key forecast inputs include Ruhr industrial corridor sewer replacement schedules, Sponge City initiative rollout pacing, and REACH restriction implementation timelines for plastic additives.
The model assumes a particular technology adoption path for thermoplastic displacement of concrete; alternative pathways favoring polymer concrete hybrid formulations or accelerated concrete fatigue-resistance improvements would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency, recycled polymer feedstock availability, and geotechnical engineering workforce expansion. A model refresh is warranted upon material change in EPA or EU stormwater quality mandate implementation pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market