
 Africa Vinyl Windows Market | 2026-2036
Africa Vinyl Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Vinyl Windows Market Analytics
Market Overview
Capital-intensity divergence between extrusion-scale specialists and import-dependent distributors is reorganizing competitive tiers across African markets. REHAU Group leverages integrated compounding facilities in Egypt to anchor supply security for East African project pipelines. Deceuninck NV sustains brand positioning through specification relationships with South African architectural practices. Fenesta Building Systems competes on installation-network density in Nigerian commercial hubs.
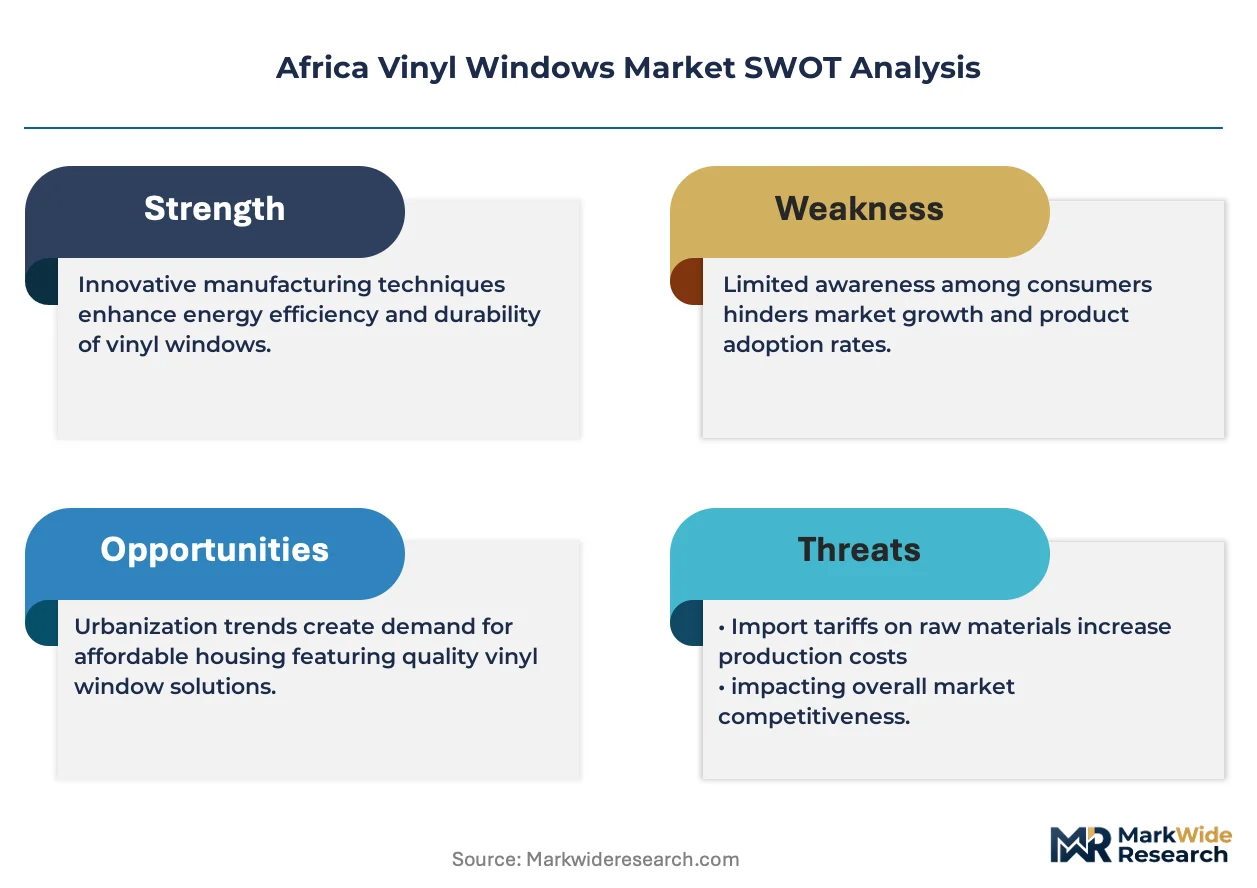
Vinyl windows are thermoplastic fenestration systems fabricated from unplasticized polyvinyl chloride (uPVC) extrusions, typically reinforced with galvanized steel inserts and glazed with double-pane sealed units for thermal and acoustic insulation. The primary purpose is delivering durable, low-maintenance building envelopes suited to climates with high UV exposure, humidity variation, and coastal corrosion. Sliding configurations dominate volume in price-sensitive residential markets across West Africa, while casement systems command premium positioning in South African institutional specifications. New construction installations absorb the majority of frame shipments, though replacement activity accelerates in mature South African housing stock where first-generation aluminum units reach end-of-life.
South Africa's SABS standards for fenestration energy performance, Nigeria's Federal Ministry of Housing building codes, and Kenya's National Construction Authority quality marks collectively shape product compliance requirements and import clearance protocols for vinyl window systems. These frameworks increasingly reference thermal transmittance thresholds that favor multi-chamber European profile designs over simplified Asian alternatives. Stakeholders must monitor evolving local content rules and certification reciprocity agreements that could reroute supply from European direct shipment toward regional compounding and fabrication investments.
Market Dynamics
Multi-chamber uPVC profile technology is compressing replacement cycles for aluminum fenestration across coastal African construction corridors. This thermal-performance shift reconfigures procurement specifications and fabrication investment priorities simultaneously.
Growth Catalysts
- SABS thermal transmittance mandates:South Africa's National Building Regulations now enforce energy-performance thresholds that disqualify single-chamber aluminum systems from new institutional builds.
- Coastal saline degradation:Nigerian port cities including Lagos and Port Harcourt experience accelerated aluminum frame corrosion, shortening replacement intervals and redirecting specification toward uPVC alternatives.
- Galvanized steel reinforcement:Steel-insert uPVC extrusions deliver structural rigidity for high-rise residential towers without thermal bridging, satisfying Kenyan National Construction Authority wind-load requirements.
Market Restraints
- Petrochemical feedstock volatility:PVC resin prices track ethylene and chlorine derivatives from Gulf petrochemical complexes, compressing margin predictability for extrusion-scale fabricators.
- Egyptian supply concentration:Integrated compounding capacity clusters along the Suez Canal corridor, creating single-point vulnerability for East African project pipelines.
- Aluminum substitution persistence:First-cost-sensitive developers in inland Nigerian markets continue specifying aluminum for low-rise residential where saline exposure remains minimal.
Strategic Opportunities
- Kenyan affordable housing pipeline:The National Housing Corporation's mass housing initiative targets 500,000 units, creating specification volume for standardized uPVC sliding systems.
- Recycled content mandates:South Africa's extended producer responsibility frameworks for construction materials incentivize post-consumer PVC recovery and re-extrusion capabilities.
- Digital specification platforms:Architectural practices in Johannesburg and Cape Town increasingly source fenestration through BIM-integrated procurement portals that filter by thermal performance metrics.
Industry Challenges
- Fabrication technician scarcity:Welding and corner-cleaning skills for multi-chamber profile assembly remain concentrated among European-trained specialists, constraining local production scale-up.
- Certification timeline compression:SABS mark approval for imported profile systems requires 12-18 month testing cycles, delaying market entry for new supply sources.
- Steel reinforcement supply coordination:Galvanized insert sourcing from South African mills must synchronize with extrusion schedules to prevent fabrication bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Vinyl Windows Market |
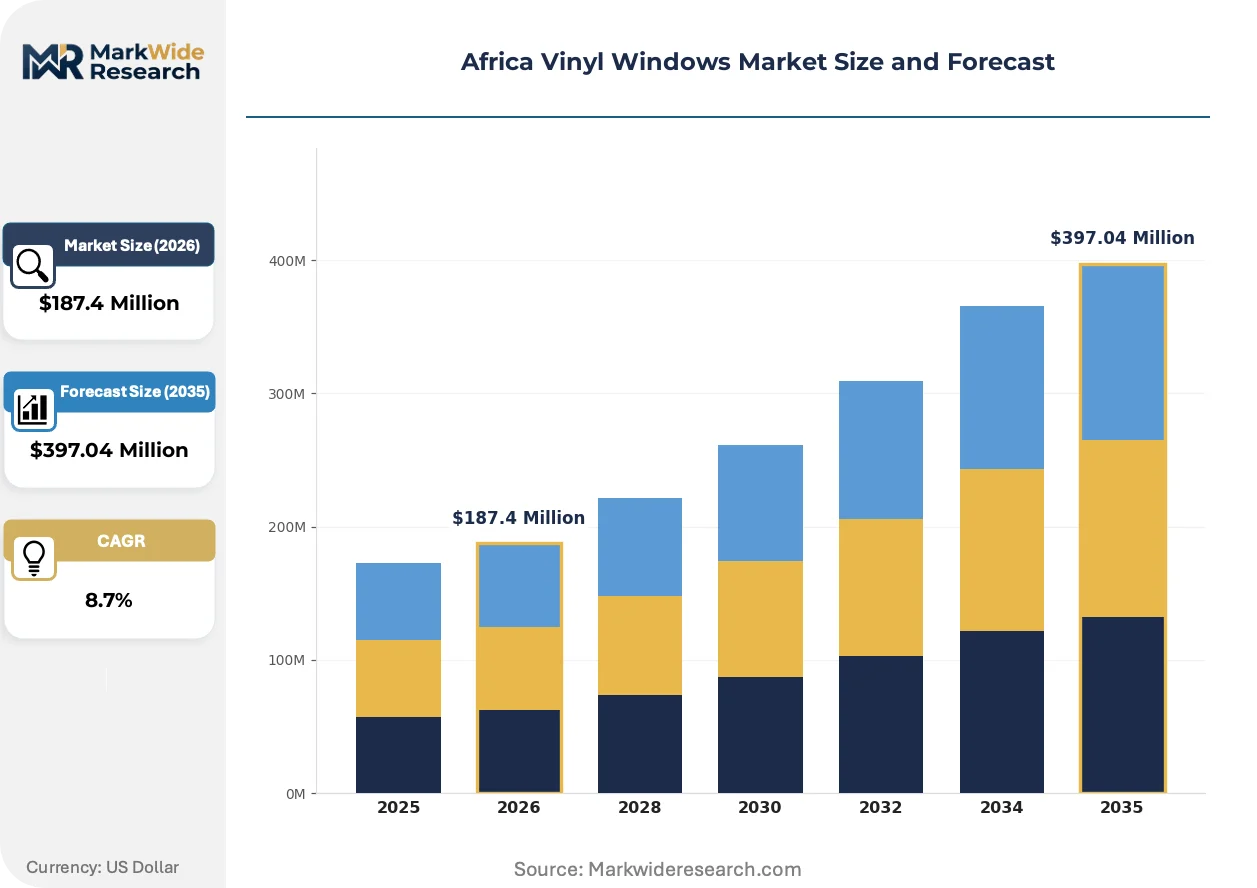
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
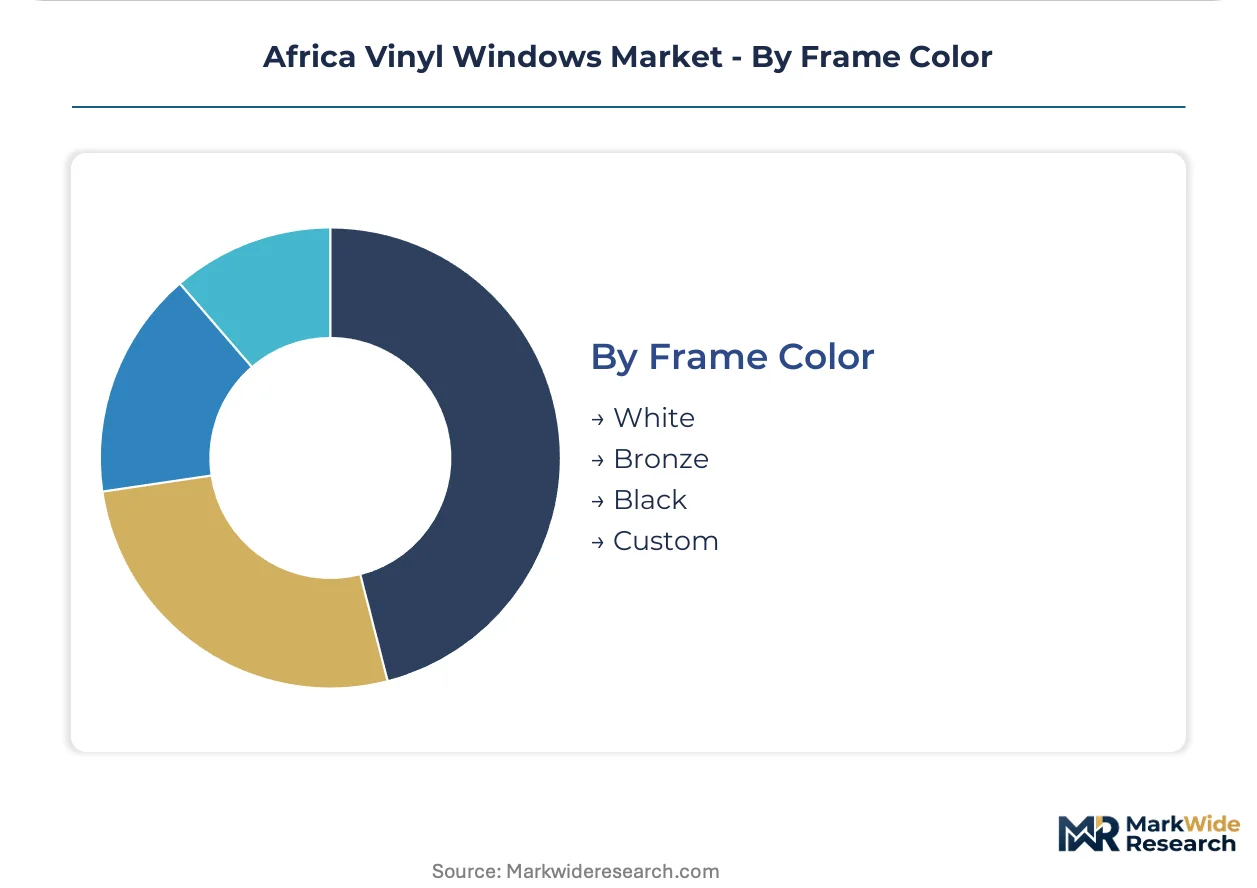
| Segmentation | Product Type: Casement, Sliding, Awning, Fixed End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Replacement, Renovation, Retrofit Frame Color: White, Bronze, Black, Custom |
| Companies Covered | VEKA AG, Deceuninck NV, REHAU Group, Fenesta Building Systems, Andersen Corporation, JELD-WEN, Inc., Pella Corporation, Aluplast GmbH, Profine Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Vinyl Windows Market Evolving Landscape
Thermal-performance engineering and digital procurement infrastructure are restructuring how vinyl window systems reach African construction sites. Three interconnected developments merit attention.
Co-extruded colored uPVC profiles with UV-stabilized acrylic capstock are decomposing the historical trade-off between aluminum aesthetics and vinyl durability. Lagos-based developers specify woodgrain and metallic finishes for premium residential towers without accepting aluminum's thermal conductivity penalty. This finish technology enables specification capture in segments previously reserved for aluminum.
South Africa's SABS 10400-XA energy-efficiency amendments now mandate solar heat gain coefficients for fenestration in climate zones with high cooling loads. These requirements compress specification tolerance for simplified Asian profile designs lacking thermal break engineering. Johannesburg architectural practices increasingly disqualify non-compliant systems at schematic design stage.
Developer procurement teams in Nairobi and Lagos now bundle window installation with waterproofing and façade subcontracting, consolidating vendor accountability. This packaging shifts specification influence from standalone distributors toward integrated building-envelope contractors. Kenyan National Construction Authority quality audits reinforce this consolidation by tracing defects to single-point responsibility.
Africa Vinyl Windows Market Segmentation
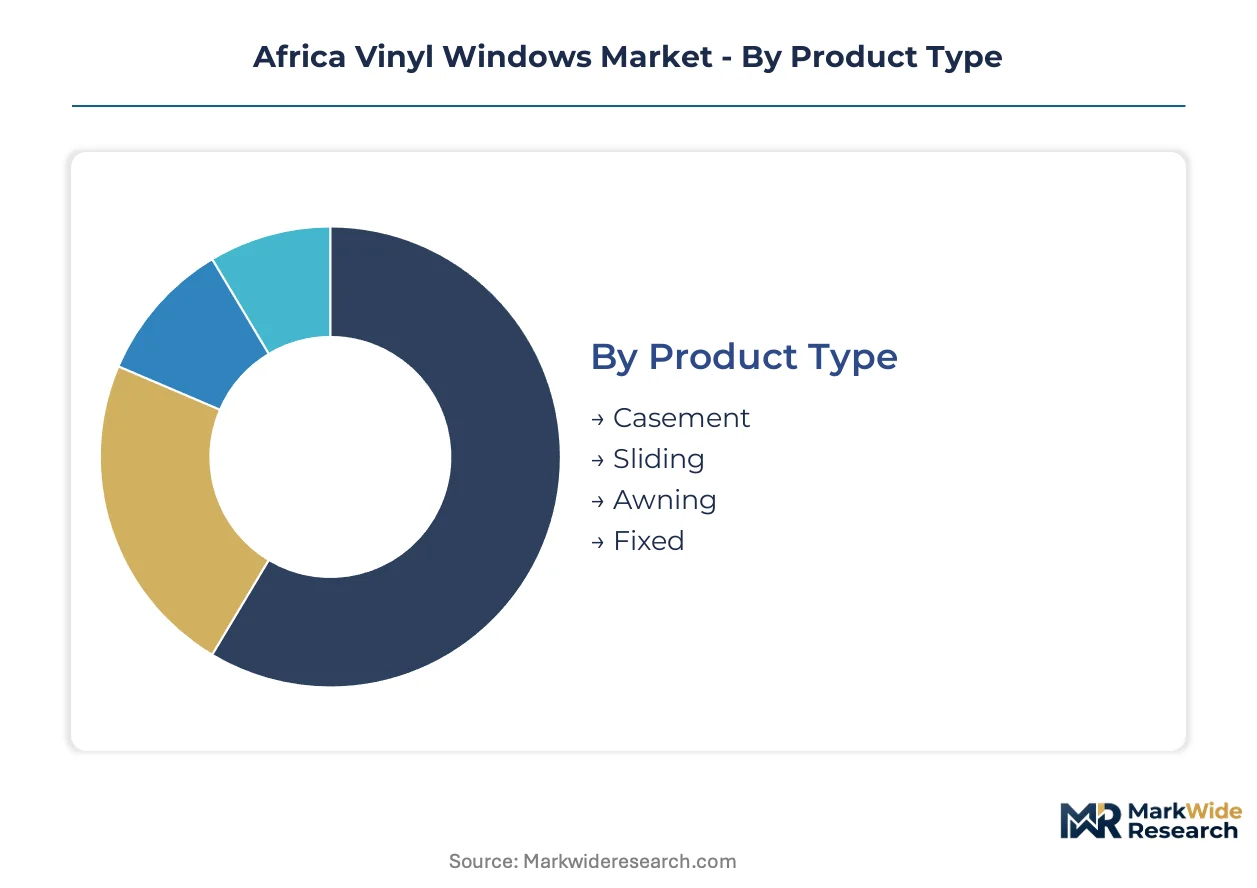
Vinyl window segmentation across Africa reflects divergent pressure from aluminum substitution, climate adaptation requirements, and specification channel evolution. Understanding how demand fragments across product configurations and end-use contexts clarifies where uPVC systems displace incumbent materials and where resistance persists.
Product Type:
Substitution pressure from aluminum framing systems concentrates most intensely on sliding configurations, where first-cost sensitivity in mass residential development creates specification vulnerability. Casement and awning systems face milder competitive threat due to performance differentiation in institutional and premium residential segments.
- Sliding:Horizontal sash configurations with tandem roller hardware and interlocking meeting rails dominate volume in Nigerian and Kenyan affordable housing. Lagos developers specify white-finish sliding systems for high-rise towers where galvanized steel reinforcement satisfies wind-load requirements without thermal bridging penalties. Coastal saline exposure accelerates specification capture from corroded aluminum predecessors.
- Casement:Side-hinged sash designs with multi-point locking hardware command premium positioning in South African institutional and commercial specifications. Johannesburg architectural practices specify casement systems for SABS 10400-XA compliance, leveraging compression-seal weatherstripping that outperforms sliding configurations in thermal transmittance testing. Multi-chamber profile engineering enables specification in segments where energy performance mandates disqualify aluminum.
- Awning:Top-hinged sash configurations with chain-winder hardware suit Kenyan coastal residential applications where outward projection must deflect monsoon precipitation without compromising ventilation.
- Fixed:Non-operable picture-window configurations with direct-set glazing prioritize thermal performance and cost minimization in South African commercial atrium installations.
Sliding configurations anchor the volume base while casement systems gain share at the steepest rate.
End User:
Cost-tier stratification separates residential volume from commercial-institutional premium capture, with industrial applications occupying a narrow intermediate position where durability requirements meet price constraints.
- Residential:Single-family and multi-family housing applications absorb the majority of frame shipments across Nigeria, Kenya, and South Africa. Kenyan National Housing Corporation mass housing initiatives standardize on white-finish sliding systems, while Lagos premium towers specify woodgrain co-extruded profiles that mimic aluminum aesthetics without thermal conductivity penalties. Coastal replacement cycles accelerate as first-generation aluminum units reach end-of-life.
- Commercial:Office, retail, and hospitality specifications prioritize thermal performance and acoustic insulation in South African urban centers. Cape Town architectural practices source fenestration through BIM-integrated procurement portals that filter by solar heat gain coefficients, compressing tolerance for simplified profile designs.
- Industrial:Manufacturing and warehouse applications balance durability requirements against capital expenditure constraints, with fixed configurations dominating where ventilation is mechanically supplied.
- Institutional:Schools, hospitals, and government buildings face the most stringent SABS energy-performance mandates, driving specification toward multi-chamber casement systems with warm-edge spacer technology.
Residential applications concentrate procurement volume while institutional specifications drive margin expansion through compliance complexity.
Installation Type:
Application-stage distribution determines fabrication scheduling, inventory positioning, and installation-network deployment across project pipelines with divergent lead-time requirements.
- New Construction:Greenfield building projects integrate window specification at schematic design stage, enabling thermal-performance optimization and bulk procurement discounts. Nairobi developers bundle window installation with waterproofing and façade subcontracting, consolidating vendor accountability through Kenyan National Construction Authority quality audit frameworks.
- Replacement:End-of-life aluminum unit substitution accelerates in mature South African housing stock, particularly coastal Cape Town and Durban markets where saline degradation has shortened frame service intervals. Retrofit measurement and custom fabrication requirements demand localized installation networks.
- Renovation:Partial building upgrades with modified opening configurations require flexible fabrication capabilities and design-assistance services from specification-stage involvement.
- Retrofit:Insert window installations within existing frames minimize structural disruption in occupied buildings, with acoustic and thermal performance gains driving adoption in Johannesburg commercial refurbishment.
New construction commands fabrication capacity allocation while replacement activity expands most quickly as coastal aluminum stocks deteriorate.
Frame Color:
Finish technology maturity determines whether uPVC systems capture specification segments historically reserved for aluminum aesthetics, with custom capabilities separating premium positioning from commodity volume.
- White:Standard titanium dioxide pigmentation dominates mass residential volume across Nigerian and Kenyan affordable housing, where cost minimization overrides aesthetic differentiation. White finishes exhibit superior UV stability in high-exposure African climates.
- Bronze:Co-extruded acrylic capstock with metallic pigmentation captures commercial and premium residential specifications seeking aluminum-like appearance without thermal bridging. Lagos developers specify bronze finishes for tower elevations where architectural continuity demands non-white fenestration.
- Black:Carbon black pigmentation with UV stabilizers commands contemporary aesthetic positioning in Johannesburg and Cape Town institutional projects, though heat absorption concerns constrain tropical applications.
- Custom:Woodgrain foiling and project-specific color matching enable specification capture in heritage-sensitive and architecturally distinctive developments, requiring extended lead times and minimum order quantities.
White finishes anchor volume production while bronze and custom coloration expand specification access into aluminum-dominated aesthetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Africa's specification-driven institutional segment while Nigerian mass residential markets compress margins through import-dependent distribution layers.
South Africa
SABS 10400-XA energy-efficiency amendments mandate solar heat gain coefficients for fenestration in high cooling-load climate zones. Johannesburg architectural practices increasingly disqualify non-compliant aluminum systems at schematic design stage. Cape Town coastal replacement cycles accelerate as saline degradation shortens first-generation aluminum frame service intervals.
Nigeria
Lagos and Port Harcourt developers specify uPVC sliding systems for high-rise residential towers where galvanized steel reinforcement satisfies wind-load requirements. Federal Ministry of Housing building codes shape product compliance requirements and import clearance protocols for vinyl window systems. Coastal saline exposure accelerates specification capture from corroded aluminum predecessors in port city construction corridors.
Kenya
National Housing Corporation mass housing initiatives target volume deployment of standardized white-finish sliding systems across affordable housing pipelines. National Construction Authority quality marks and wind-load requirements reinforce steel-insert uPVC specifications for high-rise residential construction. Nairobi developers bundle window installation with waterproofing and façade subcontracting to consolidate vendor accountability.
Egypt
Suez Canal corridor compounding facilities anchor supply security for East African project pipelines through integrated extrusion-scale production. National building regulations increasingly reference thermal transmittance thresholds that favor multi-chamber European profile designs. Cairo-based distribution networks coordinate galvanized steel reinforcement sourcing with extrusion schedules to prevent fabrication bottlenecks.
Ghana
Accra coastal residential development experiences accelerated aluminum replacement cycles due to tropical humidity and salt corrosion exposure. National construction authority frameworks shape import protocols for European-origin uPVC profile systems. Tema port logistics clusters coordinate regional distribution for West African coastal markets seeking corrosion-resistant fenestration alternatives.
Africa Vinyl Windows Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European extrusion-scale specialists commanding specification influence through thermal-performance engineering while Asian import-dependent distributors compete on first-cost positioning in mass residential segments. The vendor base organizes around three strategic archetypes: integrated compounding specialists with captive resin supply, specification-focused fabricators with architectural practice relationships, and installation-network builders with project execution density. Dominant competitive moves include backward integration into regional compounding capacity and strategic partnerships with waterproofing and façade contractors to capture bundled procurement decisions.
Among European-origin integrated specialists, REHAU Group and Deceuninck NV exemplify the compounding-plus-fabrication archetype that leverages specification relationships with architectural practices to anchor premium positioning. VEKA AG occupies a position within the extrusion-scale tier that supplies profile systems to regional fabricators across multiple African markets. These three companies represent distinct strategic postures within a competitive structure where supply security and thermal-performance credentials determine specification access in institutional and premium residential segments.
| Leading Market Players |
|---|
| VEKA AG |
| Deceuninck NV |
| REHAU Group |
| Fenesta Building Systems |
| Andersen Corporation |
| JELD-WEN, Inc. |
| Pella Corporation |
| Aluplast GmbH |
| Profine Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Suez Canal corridor compounders and East African project developers lock in PVC resin supply visibility while insulating extrusion-scale fabricators from Gulf petrochemical spot volatility. These arrangements concentrate pricing power with integrated producers who control both resin compounding and profile extrusion, forcing import-dependent distributors to absorb margin compression from feedstock swings.
Pricing Analysis
Configured-to-order pricing for woodgrain co-extruded and custom-finish profiles commands substantial premiums over standard white-finish sliding systems. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by thermal performance certification and installation service bundling. Price erosion runs through mass residential segments in inland Nigerian markets where aluminum substitution persists. Institutional buyers in Johannesburg exhibit lowest price sensitivity due to SABS compliance mandates, while affordable housing developers in Nairobi face acute first-cost constraints.
Supply Chain Analysis
Suez Canal transit corridors and Red Sea shipping lanes constitute critical chokepoints for Egyptian-origin PVC resin and profile systems serving East African markets. Supply concentrates in Egypt, Germany, and Turkey for multi-chamber profile extrusion, while China dominates simplified Asian alternative sourcing. Raw material dependencies span PVC resin from Gulf petrochemical complexes, galvanized steel inserts from South African mills, and UV-stabilized acrylic capstock from European specialty chemical producers. Single-source vulnerability around Egyptian compounding capacity threatens project pipeline continuity. Distribution runs through regional fabricator networks with installation-service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SABS thermal transmittance mandates and coastal saline degradation are accelerating uPVC displacement of aluminum across African construction corridors, creating high-growth disruption for specification-capture strategies.
For Market Incumbents: Consolidate specification relationships with Johannesburg and Cape Town architectural practices through BIM-integrated procurement portal presence. Deepen backward integration into regional compounding capacity to reduce Suez Canal corridor dependency. Defend against Asian import price pressure by emphasizing SABS mark certification and multi-chamber thermal performance credentials. For New Entrants and Emerging Players: Installation-network density gaps in Nigerian commercial hubs and Kenyan mass housing corridors present white-space capture opportunities. Target bundled waterproofing and façade subcontracting relationships where Kenyan National Construction Authority quality audits consolidate vendor accountability. Penetrate through design-assistance services for renovation and retrofit segments requiring flexible fabrication capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward integrated compounding specialists with captive resin supply and established SABS certification timelines. Long-term viability hinges on post-consumer PVC recovery capabilities under South Africa's extended producer responsibility frameworks. Watch for Kenyan National Housing Corporation procurement volume inflections as affordable housing pipeline acceleration signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Compounding | Egyptian resin capacity anchors supply security for East African project pipelines. |
| SABS Certification Investment | Multi-chamber profile approval unlocks Johannesburg institutional specification access. |
| Installation-Network Density Buildout | Lagos and Nairobi service coverage captures bundled procurement decisions. |
| Post-Consumer PVC Recovery Capability | South African extended producer responsibility frameworks incentivize re-extrusion investment. |
| BIM-Integrated Procurement Portal Integration | Cape Town architectural practices filter specifications by solar heat gain coefficients. |
Research Methodology
Desk research of customs and trade databases, SABS technical standards documentation, and National Housing Corporation procurement disclosures preceded structured interviews with uPVC extrusion plant managers, architectural specification consultants, waterproofing contractors, and Kenyan National Construction Authority quality auditors. Secondary validation drew from Egyptian General Authority for Supply Commodities resin import records, South African customs data, and European profile system manufacturer sustainability reports. Bottom-up volume triangulation across product configurations reconciled with top-down construction sector expenditure analysis.
Variance decomposition across product type, end user, installation stage, and regional regulatory cluster shaped the analytical framework. Modeled dimensions included sliding versus casement configuration splits, residential versus institutional demand tiers, new construction versus replacement cycle timing, and SABS-compliant versus non-compliant specification tracks. CAGRs were derived from segment-level volume build-ups calibrated to housing starts and aluminum replacement velocity indicators. Industry-specific inputs encompassed coastal saline exposure indices and thermal transmittance threshold adoption curves.
Forecasts assume regulatory continuity in South Africa's National Building Regulations, Nigeria's Federal Ministry of Housing codes, and Kenya's National Construction Authority frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Egyptian supply concentration risks and petrochemical feedstock volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Plastic Formwork Market