
 Waterproof Fabrics Market | 2026-2036
Waterproof Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Fabrics Market Analytics
Market Context
Skilled polymer chemist availability in Western Europe is collapsing as retirement waves outpace university pipeline output. W. L. Gore & Associates, Inc. leverages its decades of ePTFE membrane expertise to sustain premium positioning across alpine and defense channels. Toray Industries, Inc. anchors Asian supply through integrated filament-to-fabric operations in Japan and expanding Southeast Asian finishing capacity. Sympatex Technologies GmbH differentiates via 100% recyclable polyester membrane chemistry that navigates tightening EU substance restrictions.
Technical Definition and Segment Structure
Waterproof fabrics are engineered textile structures achieving sustained hydrostatic resistance, typically rated above 10,000 mm water column pressure through microporous membranes, dense polymer coatings, or multi-layer lamination bonding. These materials block liquid water penetration while permitting vapor transmission, serving critical functions in protective equipment, architectural membranes, and medical barrier systems. Membrane fabrics dominate value pools due to performance premiums in professional outdoor and military applications, while coated fabrics occupy volume leadership in industrial tarpaulin and construction shelter segments. Laminated fabrics are gaining share fastest as bonding adhesives improve wash durability for fashion apparel crossover lines targeting urban commuter wear.
Regulatory Framework and Outlook
REACH substance restrictions and the EU Green Deal's chemical sustainability roadmap are forcing reformulation of long-chain fluorinated water repellents across European supply chains. EPA chemical safety evaluations under TSCA Section 6 are creating parallel compliance pressure in United States markets, with state-level regulations in Maine and Washington accelerating phase-out timelines. Stakeholders must monitor PFAS substitution progress across their supplier tiers and validate alternative durable water repellent performance under accelerated aging protocols before specification lock-in.
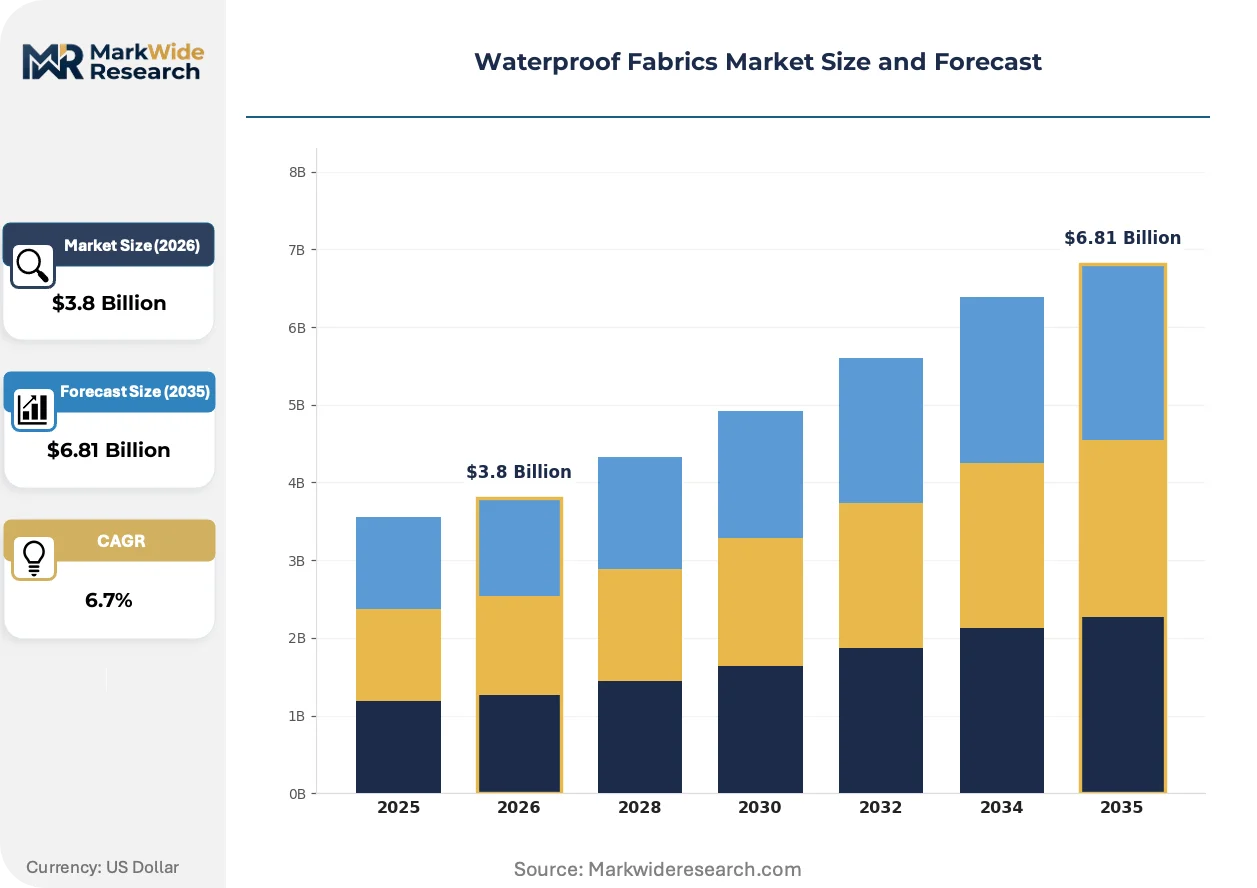
Market Dynamics
PFAS phase-out mandates across multiple jurisdictions are forcing immediate chemistry transitions while membrane fabrication capacity concentrates in East Asian industrial clusters, creating supply bottlenecks for Western outdoor gear brands.
Growth Catalysts
- EU Green Deal chemical sustainability roadmap:REACH substance restrictions on long-chain fluorinated compounds are accelerating reformulation investments by European textile finishers, opening procurement windows for PFAS-free alternatives.
- Alpine equipment standards tightening:Professional mountaineering associations are mandating higher hydrostatic resistance ratings for expedition-grade apparel, pulling membrane-based laminates into premium product tiers.
- China military uniform programs:Domestic procurement scaling for specialized coated fabrics is concentrating demand in Yangtze River Delta textile clusters with integrated polymer coating capabilities.
Market Restraints
- Petrochemical feedstock volatility:Polyester and polyurethane raw material costs fluctuate with crude oil derivatives, compressing margin predictability for coating operations.
- East Asian membrane supply concentration:Microporous ePTFE and TPU film production clusters heavily in Japan and coastal China, exposing Western brands to logistics disruption risks.
- Performance gap in PFAS substitutes:Silicone and hydrocarbon-based durable water repellents exhibit inferior oil repellency and wash durability versus legacy fluorinated chemistries.
Strategic Opportunities
- India technical textiles expansion:PLI scheme incentives for man-made fiber and technical fabric production are attracting membrane lamination investments in Tamil Nadu and Gujarat.
- Medical barrier systems:Surgical gown and isolation drape specifications are incorporating breathable waterproof laminates, creating demand orthogonal to outdoor apparel cycles.
- Biomass-derived membrane polymers:Polyhydroxyalkanoate and cellulose-based microporous films are converging with solvent-free adhesive bonding to enable compostable protective wear categories.
Industry Challenges
- Polymer chemist pipeline collapse:Retirement waves in Western Europe and North America outpace university graduation rates for fluoropolymer and coating formulation expertise.
- Accelerated aging protocol gaps:No standardized test methods exist for validating PFAS-free durable water repellent performance across multi-year garment lifecycles, delaying specification lock-in decisions.
- Multi-tier supplier auditing:Chemical substance compliance must be validated through coating houses, converters, and finished goods assemblers, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Fabrics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Fabrics, Coated Fabrics, Laminated Fabrics, Composite Fabrics Application: Outdoor Gear, Technical Textiles, Fashion Apparel, Industrial Use Material: Polyester, Nylon, Polypropylene, PVC End User: Consumers, Sports Professionals, Military, Construction |
| Companies Covered | schoeller Switzerland, Nitto Denko Corporation, W. L. Gore & Associates, Inc., HeiQ Materials AG, Milliken & Company, Toray Industries, Inc., 3M Company, eVent Fabrics, Sympatex Technologies GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Fabrics Market Evolving Landscape
Membrane chemistry diversification and bonding process innovation are fragmenting the traditional laminate value chain while regulatory pressure compresses reformulation timelines across supplier tiers.
Biomass-derived microporous membranes from polyhydroxyalkanoate and cellulose ester feedstocks are entering pilot production for medical and disposable protective applications. European surgical gown manufacturers are qualifying these materials for steam sterilization compatibility. This technology is decomposing the petroleum-dependent supply structure that has dominated waterproof breathable fabrics since ePTFE commercialization.
EPA chemical safety evaluations under TSCA Section 6 are creating parallel compliance pressure to EU REACH restrictions, with Maine and Washington state regulations accelerating PFAS phase-out timelines beyond federal schedules. Outdoor apparel brands selling into both markets must maintain dual certification tracks. The United States market is responding through accelerated supplier diversification into Southeast Asian finishing houses with established PFAS-free chemistries.
Direct-to-consumer technical apparel brands are compressing traditional wholesale cycles by building specification relationships directly with membrane and coating suppliers. These buyers are bypassing converter intermediaries to control chemistry transparency and accelerate product development timelines. Urban commuter wear segments in Germany and Japan exhibit the most visible disintermediation, with brands publishing full material composition data as competitive differentiation.
Waterproof Fabrics Market Segmentation
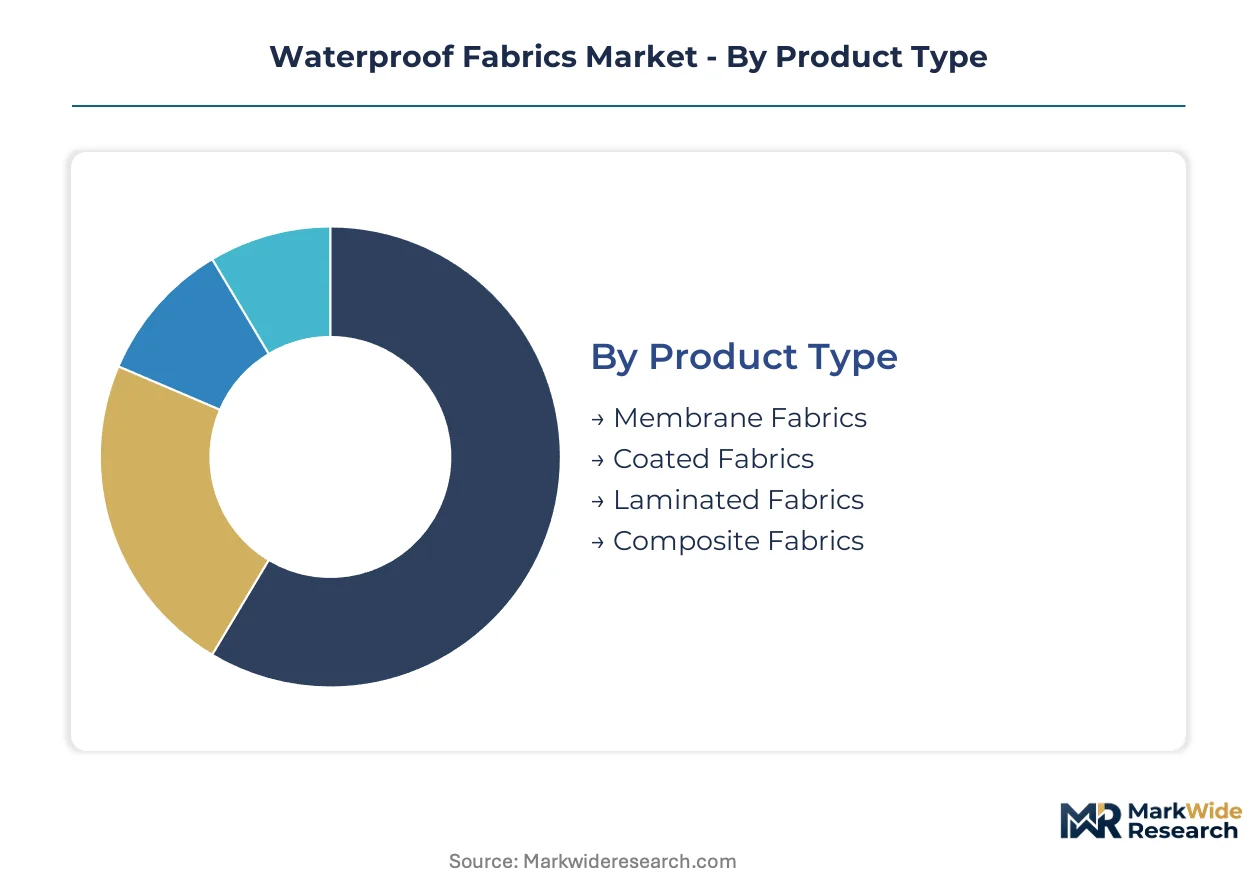
Segmentation in waterproof fabrics reveals how performance specifications, regulatory pressures, and end-use durability requirements fragment procurement patterns across supplier tiers. Buyers in alpine equipment and military channels prioritize hydrostatic resistance ratings over unit cost, while industrial purchasers optimize for tear strength and UV degradation resistance.
Product Type:
Membrane fabrics command the widest margin spreads due to microporous technology licensing fees and performance certification requirements in professional outdoor channels.
- Membrane Fabrics:Microporous ePTFE or TPU films bonded to textile substrates achieve breathability ratings exceeding 10,000 g/m²/24hr while blocking liquid water penetration above 20,000 mm hydrostatic pressure. Demand concentrates in German and Austrian alpine equipment manufacturers as DAV and UIAA certification standards tighten for expedition-grade apparel.
- Coated Fabrics:Direct polymer application—polyurethane, PVC, or acrylic—onto woven substrates creates dense waterproof layers without vapor transmission capability. Yangtze River Delta textile clusters in China are scaling specialized coated fabric volumes for domestic military uniform programs and construction tarpaulin contracts.
- Laminated Fabrics:Multi-layer bonding of membranes to face fabrics and protective backings through solvent-free adhesive systems. Urban commuter wear lines in Tokyo and Berlin are adopting these structures for wash-durable fashion crossover applications.
- Composite Fabrics:Hybrid constructions integrating membrane, coating, and reinforcement layers for extreme-duty specifications. Mining and offshore oil platform protective gear in Western Australia and the North Sea drives qualification timelines.
The dominant share belongs to membrane fabrics, while laminated fabrics are closing the gap fastest as bonding adhesive durability improves.
Application:
Volume distribution across applications tracks directly to replacement cycle frequency and regulatory exposure in end-use environments.
- Outdoor Gear:Technical apparel, tents, and sleeping bag shells requiring sustained performance across temperature differentials. Japanese mountaineering cooperatives and Scandinavian outdoor brands are mandating PFAS-free durable water repellent finishes ahead of regulatory deadlines.
- Technical Textiles:Medical barriers, architectural membranes, and agricultural covers where vapor permeability meets biocompatibility or structural load requirements. Surgical gown manufacturers in Switzerland and Germany are qualifying steam-sterilizable breathable laminates.
- Fashion Apparel:Urban rainwear and commuter-focused outerwear prioritizing aesthetic drape over extreme performance. Direct-to-consumer brands in Seoul and New York are publishing full material composition data as competitive differentiation.
- Industrial Use:Construction shelters, cargo covers, and containment systems where cost-per-square-meter dominates specification. Indian infrastructure projects under the technical textiles PLI scheme are absorbing coated polyester volumes from Tamil Nadu production lines.
Outdoor gear retains the largest value pool, though technical textiles are expanding most quickly as medical barrier specifications incorporate breathable waterproof laminates.
Material:
Feedstock selection determines coating adhesion chemistry, membrane lamination compatibility, and end-of-life recyclability pathways.
- Polyester:Dominant substrate for membrane lamination due to dimensional stability under heat-press bonding and established mechanical recycling streams. Sympatex Technologies GmbH and comparable European finishers specify recycled polyester face fabrics to align with EU Green Deal circular economy targets.
- Nylon:Superior abrasion resistance positions nylon substrates in military and tactical applications where tear strength outweighs cost premiums. US Defense Logistics Agency procurement specifications for ECWCS outer layers specify nylon 6,6 face fabrics with ePTFE membranes.
- Polypropylene:Lightweight olefin substrates for disposable protective wear and single-use medical barriers. Steam sterilization incompatibility limits penetration into surgical gown markets dominated by polyester.
- PVC:Cost-optimized coated constructions for industrial tarpaulin and construction shelter segments with minimal breathability requirements. REACH substance restrictions on plasticizer chemistries are forcing reformulation in European supply chains.
Polyester substrates anchor the majority position, while nylon is gaining share fastest in defense and tactical channels.
End User:
Procurement authority concentration varies sharply: military and construction buyers centralize specification control, while consumer channels fragment across retail and direct-to-commerce distribution.
- Consumers:Recreation-focused purchasers prioritizing brand reputation and warranty terms over technical specification sheets. German and Japanese urban commuter segments exhibit the strongest willingness-to-pay premiums for chemistry transparency and repair service programs.
- Sports Professionals:Athletes and expedition operators requiring equipment validated under accelerated aging protocols for multi-year lifecycle performance. IFMGA mountain guide associations in France and Switzerland are influencing brand specification decisions through equipment partnership programs.
- Military:National defense procurement agencies with centralized technical specification authority and multi-year contract structures. China's military uniform programs are scaling domestic coated fabric volumes while NATO-aligned forces prioritize membrane-based laminates for interoperability.
- Construction:Project-based buyers optimizing for unit cost in temporary shelter and containment applications with short deployment horizons. Indian infrastructure contractors under technical textiles PLI incentives are qualifying domestic coated fabric suppliers against Chinese import alternatives.
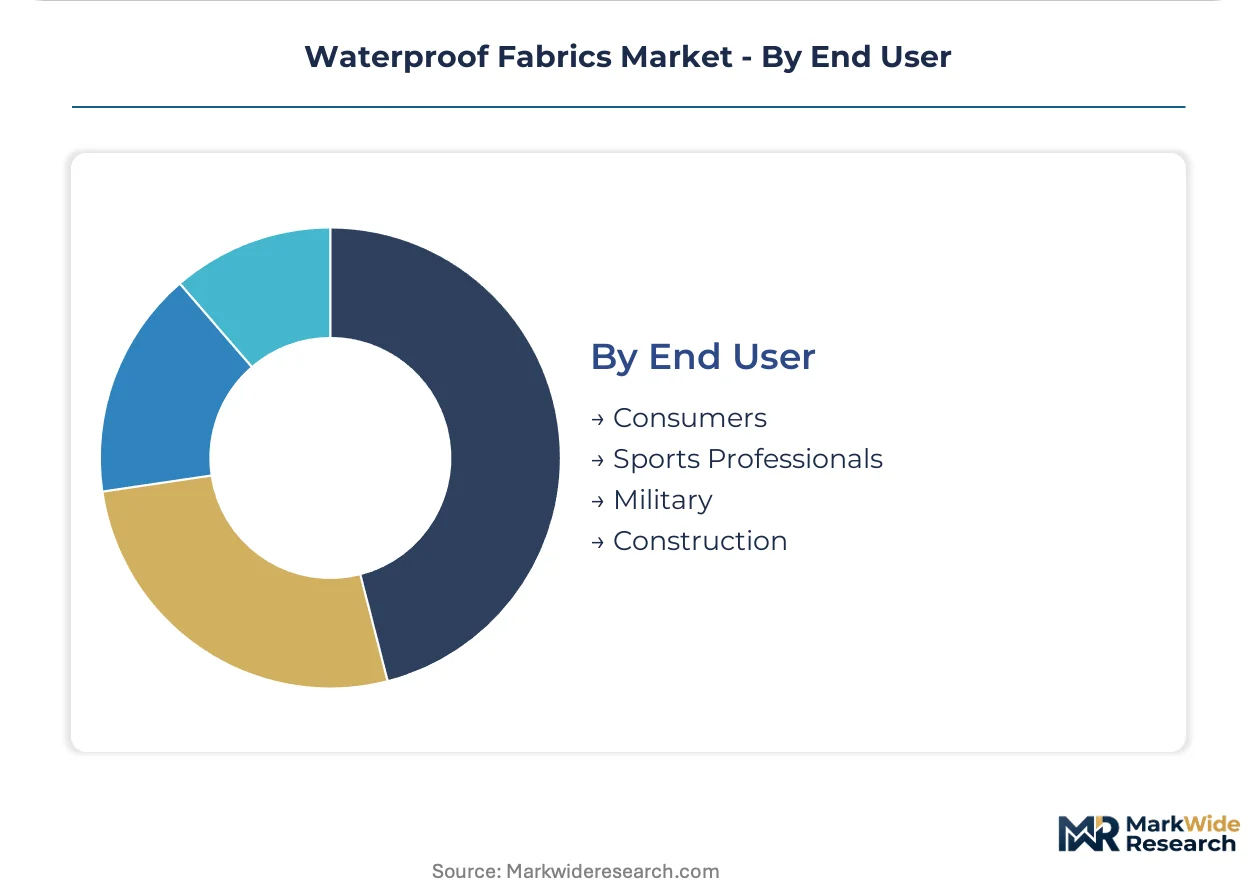
Military procurement commands the highest specification barriers, while sports professionals are driving the steepest expansion trajectory as certification standards proliferate across national mountaineering associations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with European buyers prioritizing chemistry transparency and circular end-of-life pathways while Asian procurement concentrates on scale-driven coated fabric volumes for military and infrastructure applications.
United States
Outdoor apparel brands and defense contractors drive membrane fabric demand through ECWCS program specifications and alpine equipment standards. EPA chemical safety evaluations under TSCA Section 6 are accelerating PFAS phase-out timelines beyond federal schedules, pressuring reformulation investments. Technical textile production clusters in North Carolina and Massachusetts are qualifying PFAS-free coating chemistries for surgical barrier applications.
Germany
Alpine equipment manufacturers and urban commuter wear brands anchor European demand for high-performance laminates with full material disclosure. REACH substance restrictions on long-chain fluorinated compounds are forcing immediate chemistry transitions across textile finishing operations. The Bavarian textile belt around Augsburg and Memmingen hosts membrane lamination specialists serving DAV-certified mountaineering cooperatives.
China
Domestic military uniform programs and construction tarpaulin contracts concentrate demand for specialized coated fabrics in Yangtze River Delta clusters. The country's dual carbon goals are pressuring petrochemical-dependent coating operations toward energy efficiency retrofits. Shanghai and Suzhou textile hubs are scaling integrated filament-to-fabric operations with captive polymer coating capabilities.
Japan
Mountaineering cooperatives and precision medical barrier manufacturers sustain premium membrane demand with stringent performance validation requirements. METI industrial standards for technical textiles are converging with international certification protocols for surgical gown applications. Osaka-based finishing houses are expanding solvent-free adhesive bonding capacity for fashion crossover laminates.
India
Infrastructure contractors and domestic outdoor brands are absorbing coated polyester volumes under technical textiles PLI scheme incentives. BIS certification requirements for man-made fiber fabrics are tightening quality thresholds for construction shelter applications. Tamil Nadu and Gujarat production lines are attracting membrane lamination investments targeting export markets.
Waterproof Fabrics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with membrane technology licensing and coating formulation expertise determining margin capture. The upper tier controls proprietary microporous film production and adhesive bonding IP, while mid-scale players compete on converter relationships and regional logistics. Two archetypes dominate: integrated polymer-to-fabric operators with captive membrane extrusion, and chemistry-focused innovators pivoting rapidly around PFAS substitution. Competitive moves center on backward integration into polymer feedstocks and strategic partnerships with direct-to-consumer brands seeking supply chain transparency.
Within the integrated membrane tier, W. L. Gore & Associates, Inc. and Toray Industries, Inc. occupy positions reflecting decades of microporous technology accumulation. Sympatex Technologies GmbH exemplifies the chemistry-pivot archetype through its recyclable polyester membrane positioning. Among European specialists, HeiQ Materials AG and schoeller Switzerland sit within the formulation-driven segment addressing accelerated regulatory timelines.
| Leading Market Players |
|---|
| schoeller Switzerland |
| Nitto Denko Corporation |
| W. L. Gore & Associates, Inc. |
| HeiQ Materials AG |
| Milliken & Company |
| Toray Industries, Inc. |
| 3M Company |
| eVent Fabrics |
| Sympatex Technologies GmbH |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Yangtze River Delta coating houses and domestic military procurement programs lock in both volume allocation and feedstock price visibility, insulating Chinese suppliers from petrochemical volatility that compresses margin predictability for Western converter operations.
Pricing Analysis
Project-based pricing dominates military and infrastructure procurement, while spot purchasing governs fashion apparel crossover segments. Three-tier pricing structure across premium membrane laminates, standard coated constructions, and economy industrial tarpaulins separates DAV-certified alpine equipment from construction shelter commodities. Pricing pressure stems from silicone and hydrocarbon durable water repellent performance gaps versus legacy fluorinated chemistries, forcing reformulation cost absorption. Industrial construction buyers exhibit highest price sensitivity, while German alpine cooperatives prioritize chemistry transparency over unit cost.
Supply Chain Analysis
China and Japan anchor microporous membrane fabrication, with ePTFE and TPU film production clustering in coastal Zhejiang and Osaka prefecture. Raw material dependencies center on petrochemical-derived polyester chips, polyurethane resins, and fluoropolymer alternatives under EPA TSCA Section 6 review. Single-source vulnerability concentrates in Japanese ePTFE extrusion capacity controlled by decades-proprietary licensing structures. Distribution runs through converter intermediaries in Taiwan and South Korea for Western outdoor brands, though direct-to-consumer disintermediation is accelerating in Berlin and Tokyo urban commuter channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof fabrics sit in early-cycle expansion as PFAS phase-out mandates across REACH jurisdictions and EPA evaluations force chemistry transitions that create procurement windows for substitute technologies before specification lock-in solidifies.
For Market Incumbents: Consolidate membrane lamination capacity in Tamil Nadu and Gujarat to capture PLI scheme incentives while defending European market position through accelerated PFAS-free certification investments. Threats from biomass-derived polyhydroxyalkanoate membranes and direct-to-consumer brand disintermediation require backward integration into solvent-free adhesive bonding IP to maintain converter relationships.
For New Entrants and Emerging Players: Lead with medical barrier system qualifications in Swiss and German surgical gown channels, where steam-sterilizable breathable laminates face limited incumbent penetration and orthogonal demand cycles insulate from outdoor apparel seasonality. Target India's technical textiles expansion through BIS-certified construction shelter specifications as the most penetrable geography with domestic procurement scaling.
For Investors and Strategic Acquirers: Chemistry-focused innovators with established PFAS-free formulation libraries represent the highest-conviction acquisition archetype for five-to-ten year horizon positioning. Signal to watch is accelerated aging protocol standardization by IFMGA mountain guide associations, which would trigger specification cascade across NATO-aligned defense procurement and validate alternative durable water repellent performance claims.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Transition | REACH substance restrictions and EPA TSCA Section 6 evaluations force immediate reformulation investments across European and US supply chains. |
| Backward Integration into Membrane Extrusion | Captive ePTFE and TPU film production insulates Western brands from East Asian logistics disruption risks and supply bottlenecks. |
| Medical Barrier Qualification | Surgical gown specifications in Switzerland and Germany incorporate breathable waterproof laminates, creating demand orthogonal to outdoor cycles. |
| Direct-to-Consumer Channel Development | Bypassing converter intermediaries enables chemistry transparency control and accelerates product development timelines for urban commuter segments. |
| Biomass-Derived Membrane Pilot Scaling | Polyhydroxyalkanoate and cellulose-based films decompose petroleum-dependent supply structures for compostable protective wear categories. |
Research Methodology
Initial hypotheses were tested against primary input from polymer chemists at coating houses, procurement leads at alpine equipment manufacturers, regulatory affairs specialists navigating REACH compliance, and technical textile R&D directors, then refined through secondary validation across customs trade data, ECHA substance restriction filings, SEC 10-K disclosures from integrated membrane producers, and technical textile association reports. Bottom-up volume modeling triangulated against top-down value estimates derived from military procurement databases and outdoor brand supply chain disclosures.
Variance decomposition across membrane, coated, and laminated fabric segments, polyester and nylon substrate categories, and outdoor gear versus medical barrier applications structured the analytical framework throughout the forecast period. CAGRs were derived from regression-based demand elasticity modeling anchored to alpine equipment standard tightening trajectories and PLI scheme incentive absorption rates. Industry-specific inputs included hydrostatic resistance certification timelines from DAV and UIAA, and PFAS substitution progress tracking across supplier tiers.
Forecasts assume regulatory continuity in EU REACH and EPA TSCA Section 6 enforcement regimes; material policy shifts in state-level PFAS regulations or EU Green Deal chemical sustainability roadmap acceleration would require re-modeling. Recalibration cycles align with material shifts in military uniform program procurement scaling, accelerated aging protocol standardization, and biomass-derived membrane commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Absorbent Cover Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Agri Textiles Market