
 Absorbent Cover Market | 2026-2036
Absorbent Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbent Cover Market Insights
China's Yangtze River Delta manufacturing belt is fragmenting as domestic absorbent cover production scales up alongside export-oriented capacity. Kimberly-Clark leverages its North American hygiene infrastructure to supply institutional buyers with consistent volume. Freudenberg Performance Materials anchors European medical-grade nonwoven output through specialized meltblown lines. Ahlstrom-Munksjö differentiates via sustainable fiber sourcing for European personal care brands.
An absorbent cover is a multilayer engineered material—typically comprising a fluid-acquisition distribution layer, absorbent core of fluff pulp or super absorbent polymers, and breathable backsheet—manufactured through carding, airlaid, or spunbond-meltblown-spunbond processes to capture and retain aqueous or bodily fluids. Nonwoven fabrics dominate medical dressing applications due to superior conformability and controlled evaporative transmission, while foam pads command premium positioning in post-surgical settings where pressure redistribution matters. Fiber mats serve mature industrial absorption segments with thinner margin pools, whereas gel sheets represent the fastest-expanding category in advanced wound care.
The FDA enforces biocompatibility standards under ISO 10993 for medical-grade absorbent covers, while the EU MDR requires enhanced clinical evidence for wound contact products. REACH compliance constrains chemical inputs in European manufacturing, pushing converters toward bio-based polyurethane alternatives. Stakeholders must monitor evolving state-level extended producer responsibility laws in the United States, as packaging and end-of-life regulations will reshape material selection and supplier qualification criteria.
Market Dynamics
The EU MDR is compressing certification timelines for wound-contact materials while simultaneously expanding clinical evidence requirements, forcing converters to revalidate legacy product lines and absorb extended regulatory costs before market access.
Growth Catalysts
- Advanced Wound Care Adoption:Post-acute care facilities in Germany are standardizing gel sheet dressings for chronic wound management, pulling demand toward higher-margin engineered materials.
- REACH-Driven Material Substitution:ECHA restrictions on isocyanates in polyurethane backsheet formulations are accelerating bio-based polymer qualification programs among European converters.
- Industrial Spill Containment Mandates:Manufacturing plants across the Yangtze River Delta face intensified environmental compliance inspections, expanding procurement of certified absorbent mats for chemical handling zones.
Market Restraints
- Super Absorbent Polymer Feedstock Volatility:Acrylic acid price swings tied to propylene supply disruptions compress margin stability for core material producers.
- Meltblown Capacity Concentration:European medical-grade nonwoven output clusters in southwest Germany, creating single-source risk for filtration-layer dependent products.
- Fluff Pulp Substitution Pressure:Airlaid processors face displacement from synthetic fiber cores in hygiene applications where bulk absorption matters less than thin-profile conformability.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:California's packaging waste regulations are forcing brand owners to source recyclable mono-material constructions, rewarding converters with certified circular supply chains.
- Smart Wound Dressing Convergence:Integration of pH-responsive indicators with traditional absorbent cores creates premium positioning in hospital procurement frameworks.
- Direct Hospital Contracting Channels:Group purchasing organizations in France are consolidating supplier panels, creating entry points for mid-scale converters with ISO 13485 certification and regional logistics density.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity assay capacity constraints at notified bodies extend product launch timelines by eight to fourteen months.
- Legacy Equipment Retrofit Costs:Airlaid lines built for fluff pulp processing require seven-figure capital outlays to handle super absorbent polymer blends at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbent Cover Market |
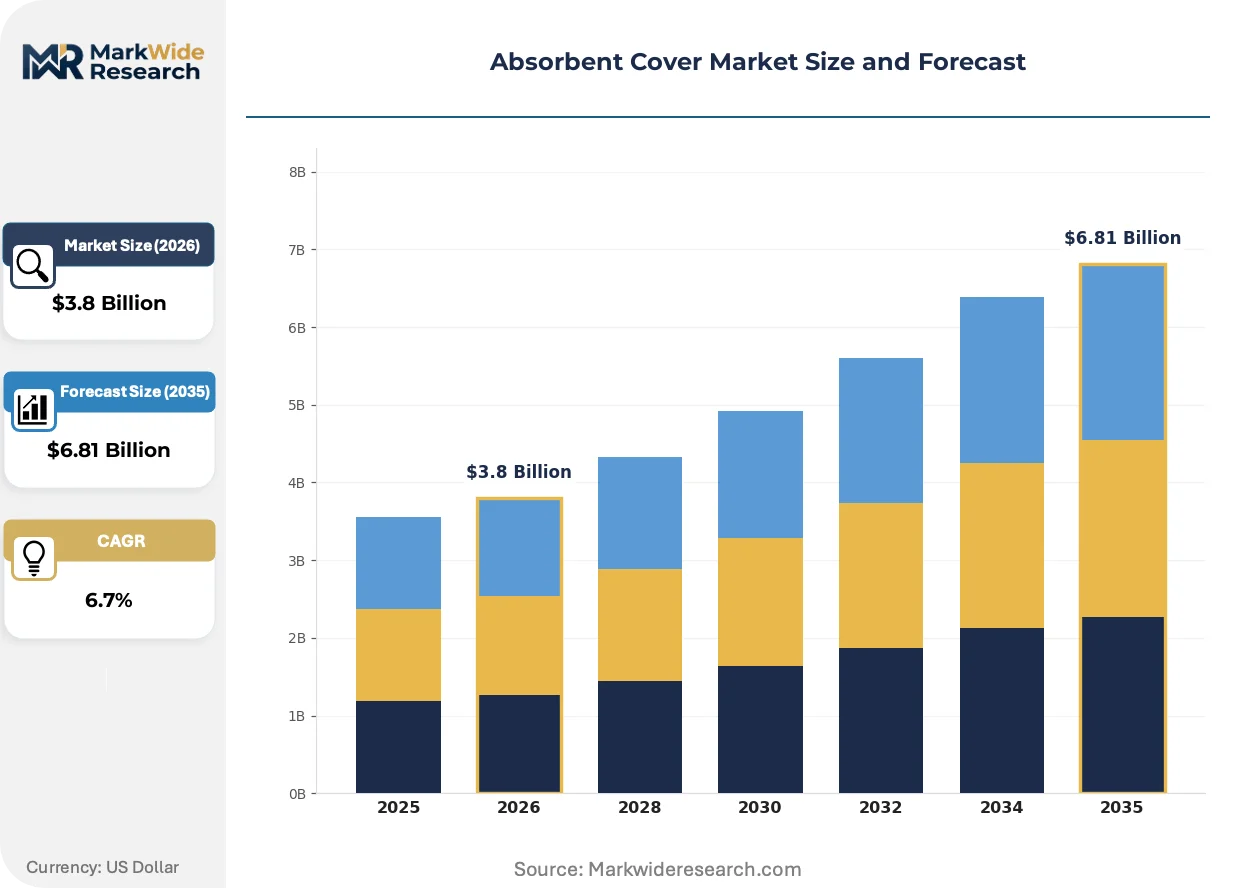
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Pads, Gel Sheets, Fiber Mats, Woven Textiles, Nonwoven Fabrics Application: Medical Dressing, Hygiene Products, Industrial Absorption, Environmental Cleanup, Agriculture Mulch Material: Polyurethane, Cellulose, Polyester, Polypropylene, Natural Fibers, Super Absorbent Polymers End User: Hospitals, Personal Care Brands, Manufacturing Plants, Agricultural Cooperatives, Waste Management Firms |
| Companies Covered | 3M, Kimberly-Clark, Berry Global, Essity, Ahlstrom-Munksjö, Freudenberg Performance Materials, Procter & Gamble, DuPont, Ontex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbent Cover Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape product architectures, with sustainability mandates and clinical performance requirements pulling development in parallel directions rather than sequential phases.
Biodegradable super absorbent polymers derived from polysaccharide feedstocks are migrating from pilot-scale demonstration to commercial wound care formulations. Hospital procurement committees in the Netherlands and Denmark are embedding carbon footprint criteria alongside clinical performance metrics in tender evaluations. This migration from petroleum-based acrylics is compressing the addressable market for conventional SAP producers while opening premium pricing tiers for certified bio-based alternatives.
REACH authorization procedures for diisocyanates in polyurethane manufacturing are tightening occupational exposure thresholds across European converting facilities. Downstream material costs are rising as formulators qualify alternative crosslinking chemistries and invest in closed-loop handling systems. Medical device manufacturers with existing MDR technical documentation are accelerating timeline advantages over competitors still navigating substance restriction compliance.
Consolidated buying by integrated health networks is compressing supplier diversity in North American hospital supply chains. Independent distributors are losing shelf space to direct manufacturer contracts and private-label arrangements with dominant group purchasing organizations. This concentration is most visible in the southeastern United States, where Catholic health systems and for-profit chains have reduced qualified wound dressing vendors from twelve to four across their combined purchasing cooperatives.
Absorbent Cover Market Segmentation
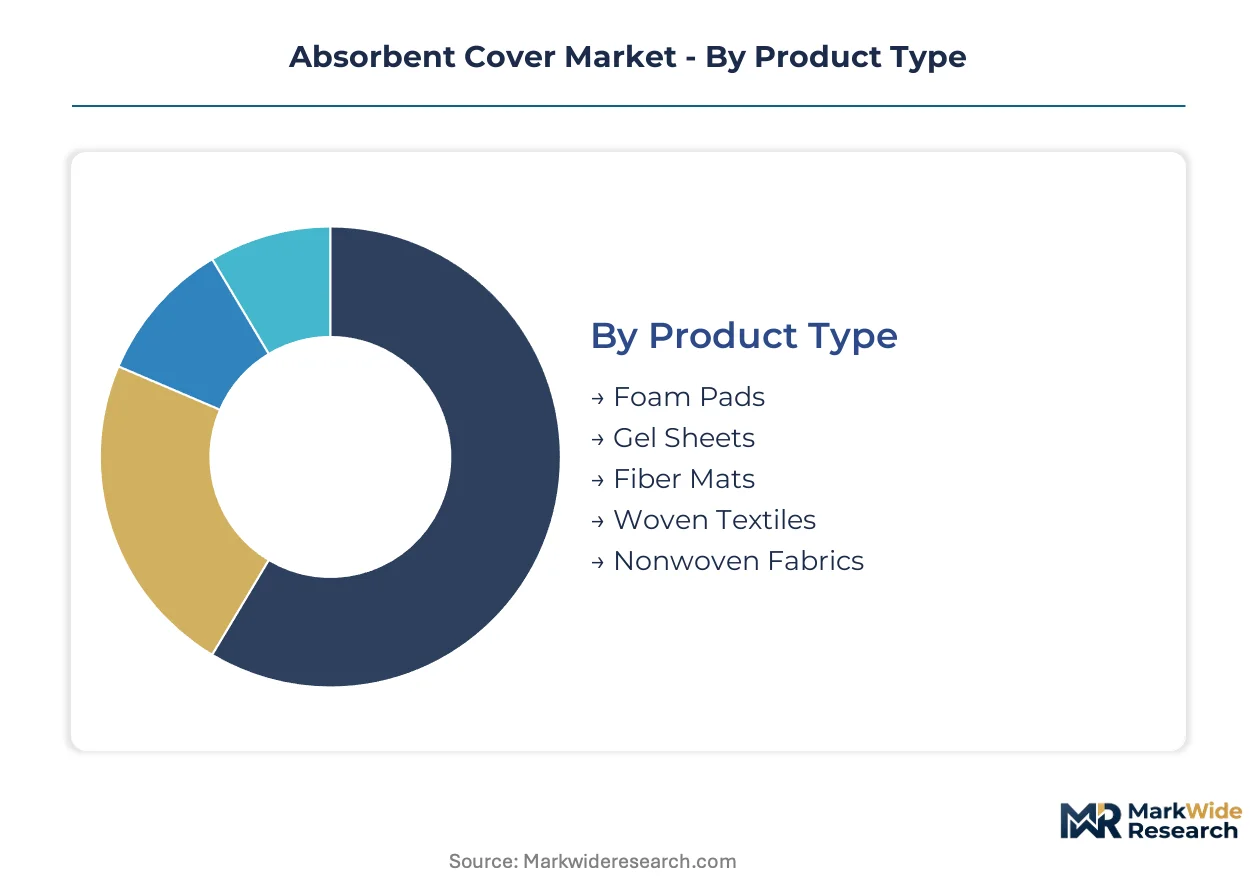
Absorbent cover procurement cycles vary dramatically by end-use context, from daily replenishment in hygiene supply chains to multi-year validation timelines for medical device integration. Understanding these velocity differentials helps suppliers align inventory models with actual consumption patterns rather than aggregated demand signals.
Product Type:
Replacement cycles stretch from single-use disposability in surgical settings to multi-year industrial deployments, compressing margin capture timelines for some formats while extending others.
- Nonwoven Fabrics:Spunbond-meltblown-spunbond laminates dominate hospital procurement for wound contact layers due to controlled MVTR (moisture vapor transmission rate) specifications. German post-acute facilities are consolidating standard dressings around SMS constructions to reduce SKU complexity and sterilization validation burdens.
- Gel Sheets:Hydrogel matrices integrated with super absorbent polymer cores enable sustained moisture donation for necrotic wound beds. Post-surgical units in France and the Netherlands are embedding these into chronic care protocols, pulling demand toward higher ASP formats with clinical outcome documentation requirements.
- Foam Pads:Reticulated polyurethane structures with hydrophilic surface treatments serve pressure injury prevention in long-term care. US nursing chains specify these for bony prominence protection.
- Fiber Mats:Airlaid cellulose constructions address mature industrial spill containment with thinner margin pools and price-driven procurement.
- Woven Textiles:Cotton gauze derivatives persist in emerging market basic wound care where cost minimization overrides performance optimization.
Nonwoven fabrics dominate installed base. Gel sheets are where expansion concentrates.
Application:
Margin structures diverge sharply between regulated medical channels and commodity industrial procurement, with certification requirements acting as the primary value capture mechanism.
- Medical Dressing:ISO 13485-certified manufacturing with biocompatibility testing under ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization protocols. FDA 510(k) clearance timelines and EU MDR technical documentation requirements compress supplier pools to established converters with regulatory affairs infrastructure.
- Hygiene Products:Baby diaper and adult incontinence applications demand thin-profile cores with optimized acquisition-distribution layer engineering. Kimberly-Clark and Procter & Gamble specify fluff pulp-SAP composites with defined centrifugal retention capacity targets.
- Industrial Absorption:Manufacturing plants in Germany's Rhine-Ruhr corridor and China's Jiangsu province require certified mats for chemical handling compliance with local environmental bureau mandates.
- Environmental Cleanup:Oil spill response and hazardous material containment applications specify oleophilic-hydrophobic fiber treatments with rapid saturation indicators.
- Agriculture Mulch:Biodegradable nonwoven ground covers for moisture retention face price pressure from conventional polyethylene sheeting despite regulatory tailwinds for soil health.
Medical dressing commands premium pricing tiers. Hygiene products absorb the greatest absolute volume.
Material:
Feedstock substitution pressures are reshaping qualification programs as REACH restrictions and sustainability procurement criteria converge on traditional petroleum-based inputs.
- Super Absorbent Polymers:Crosslinked polyacrylic acid salts dominate absorbent core engineering with retention capacity exceeding 300g saline per gram dry weight. Acrylic acid price volatility tied to propylene supply disruptions compresses margin stability for core producers.
- Cellulose:Sulfate fluff pulp from Nordic and North American softwood sources provides rapid fluid wicking in airlaid processing. Eucalyptus alternatives from Brazilian plantations are penetrating cost-sensitive hygiene applications.
- Polyurethane:Polyester and polyether foam backbones with hydrophilic surface treatments serve advanced wound care. ECHA diisocyanate restrictions are accelerating bio-based polyol qualification.
- Polypropylene:Spunbond and meltblown nonwoven layers provide fluid barrier and filtration functions in composite dressings.
- Polyester:PET fiber constructions offer dimensional stability in reusable industrial applications.
- Natural Fibers:Cotton, viscose, and emerging polysaccharide alternatives address biodegradable positioning for European personal care brands.
Super absorbent polymers anchor core functionality. Natural fibers are climbing the fastest on sustainability procurement criteria.
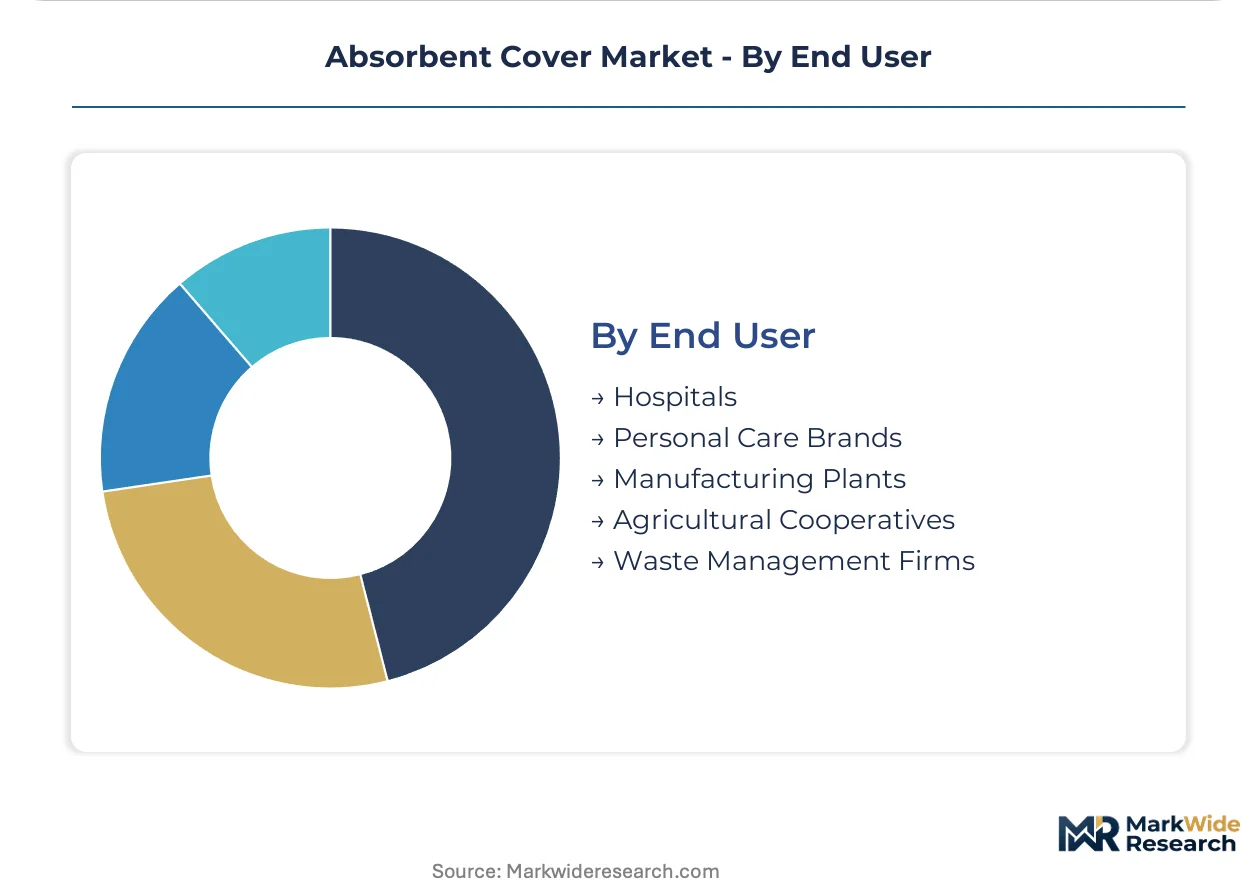
End User:
Contracting structures fragment between consolidated group purchasing organizations in hospital systems and dispersed procurement in agricultural and industrial segments.
- Hospitals:Integrated delivery networks in the US Southeast and Catholic health system purchasing cooperatives have reduced qualified wound dressing vendors from twelve to four, concentrating volume with manufacturers holding ISO 13485 certification and domestic sterilization capacity.
- Personal Care Brands:Procter & Gamble, Kimberly-Clark, and Essity specify absorbent core assemblies with defined fluff pulp basis weights and SAP distribution profiles, qualifying converters through multi-year supply agreements with volume commitment tiers.
- Manufacturing Plants:Automotive and chemical processing facilities in Germany's Baden-Württemberg industrial corridor require spill containment solutions with DIN-certified absorption capacity ratings.
- Agricultural Cooperatives:Dutch and Danish greenhouse operations specify biodegradable mulch covers with defined photodegradation timelines aligned to crop cycles.
- Waste Management Firms:Hazardous waste handling contractors procure saturated mat disposal services bundled with absorbent material supply.
Hospitals concentrate premium value capture. Manufacturing plants represent the most price-sensitive volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freudenberg Performance Materials anchors European medical-grade nonwoven output through specialized meltblown lines in southwest Germany. Kimberly-Clark leverages its North American hygiene infrastructure to supply institutional buyers with consistent volume across the United States. China's Yangtze River Delta manufacturing belt is fragmenting as domestic absorbent cover production scales up alongside export-oriented capacity.
United States
Integrated delivery networks in the Southeast have consolidated wound dressing vendors from twelve to four, concentrating procurement with ISO 13485-certified manufacturers. The FDA enforces biocompatibility standards under ISO 10993 for medical-grade absorbent covers entering hospital supply chains. Greater Boston hosts specialized converters developing smart wound dressing technologies with pH-responsive indicators.
Germany
Post-acute care facilities across Baden-Württemberg are standardizing gel sheet dressings for chronic wound management, pulling demand toward higher-margin engineered materials. The EU MDR compresses certification timelines while expanding clinical evidence requirements for wound-contact products. The Rhine-Ruhr industrial corridor requires certified absorbent mats for chemical handling compliance with local environmental bureau mandates.
China
Manufacturing plants in Jiangsu province face intensified environmental compliance inspections, expanding procurement of certified absorbent mats for chemical handling zones. The National Medical Products Administration enforces GB standards for medical device registration. The Yangtze River Delta is fragmenting as domestic production scales up alongside export-oriented capacity expansion.
France
Group purchasing organizations are consolidating supplier panels, creating entry points for mid-scale converters with ISO 13485 certification and regional logistics density. REACH compliance constrains chemical inputs in European manufacturing, pushing converters toward bio-based polyurethane alternatives. Post-surgical units in Paris and Lyon are embedding hydrogel matrices into chronic care protocols.
Netherlands
Hospital procurement committees are embedding carbon footprint criteria alongside clinical performance metrics in tender evaluations. ECHA restrictions on isocyanates in polyurethane backsheet formulations are accelerating bio-based polymer qualification programs among Dutch converters. Dutch greenhouse operations specify biodegradable mulch covers with defined photodegradation timelines aligned to crop cycles.
Absorbent Cover Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the absorbent cover supply chain. The market exhibits tiered consolidation, with multinational hygiene conglomerates anchoring high-volume procurement and mid-scale converters occupying specialized medical-grade niches. Three archetypes dominate: vertically integrated material-science platforms, regional contract converters with regulatory certification depth, and industrial spill containment specialists serving price-sensitive manufacturing segments. Competitive moves center on M&A-driven portfolio diversification into adjacent wound care formats and capacity expansion in bio-based polymer processing.
Among North American-based hygiene platforms, Kimberly-Clark and Procter & Gamble exemplify scale-driven archetypes with multi-year supply agreements anchoring volume commitment tiers. Freudenberg Performance Materials occupies a position within the European medical-grade nonwoven tier, representing specialized meltblown capacity concentration. Ahlstrom-Munksjö sits within the sustainable fiber sourcing archetype, differentiating through certified circular supply chains for European personal care brands.
| Leading Market Players |
|---|
| 3M |
| Kimberly-Clark |
| Berry Global |
| Essity |
| Ahlstrom-Munksjö |
| Freudenberg Performance Materials |
| Procter & Gamble |
| DuPont |
| Ontex Group |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor freight dynamics compress margin capture for European converters while amplifying price differentiation between ISO 13485-certified medical grades and uncertified industrial substitutes. Supply concentration in southwest Germany's meltblown belt intersects with REACH-driven material substitution costs to stratify procurement economics across hospital, hygiene, and industrial channels.
Pricing Analysis
EU MDR technical documentation requirements dictate the pricing tier structure across wound-contact materials, separating FDA-cleared surgical dressings from basic hygiene covers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO 10993-5 cytotoxicity validation commanding substantial premia over industrial absorption mats. Cost compression in the fiber mat segment intensifies because of acrylic acid feedstock volatility tied to propylene supply disruptions. Manufacturing plants in Germany's Rhine-Ruhr corridor exhibit the highest price sensitivity, while US integrated delivery networks prioritize clinical outcome documentation over unit cost.
Supply Chain Analysis
Extended payment terms from group purchasing organizations in France and the southeastern United States strain working capital for mid-scale converters without supply-chain finance facilities. Raw material sourcing draws from Germany for medical-grade meltblown, China for super absorbent polymer precursor chemicals, and Nordic countries for sulfate fluff pulp. Single-source vulnerability concentrates in southwest Germany's specialized filtration-layer capacity. Distribution runs through hospital procurement cooperatives and hygiene OEM direct contracts rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbent cover market sits at a platform-economics inflection where smart wound dressing interoperability with electronic health record systems will consolidate procurement around integrated device-data platforms rather than standalone materials.
For Market Incumbents: Pre-empt displacement from bio-based polymer specialists by accelerating MDR technical documentation for legacy product lines and securing captive supply of polysaccharide-derived super absorbent polymers. Capacity addition in the Netherlands positions converters to meet carbon footprint procurement criteria from Dutch and Danish hospital committees.
For New Entrants and Emerging Players: Mid-scale ISO 13485-certified converters with regional logistics density in France represent the most penetrable entry point for hospital supply chain penetration. Agricultural mulch applications in Dutch greenhouse operations offer a second white-space target with biodegradable qualification requirements less stringent than medical channels. Direct contracting with group purchasing organizations bypasses distributor margin extraction.
For Investors and Strategic Acquirers: Regional contract converters with regulatory certification depth and established sterilization partnerships anchor long-term viability across the analysis window. The convergence signal to watch is pH-responsive indicator integration with traditional absorbent cores, which will separate premium-positioned platforms from commodity suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Acceleration | EU MDR compressed timelines favor converters with existing clinical evidence portfolios over legacy revalidation laggards. |
| Bio-Based Polymer Qualification Program | ECHA diisocyanate restrictions in polyurethane manufacturing push formulators toward polysaccharide feedstock alternatives. |
| Direct Hospital Contracting Channel | Group purchasing organization consolidation in France and the US Southeast rewards converters with ISO 13485 certification and regional logistics density. |
| Smart Wound Dressing Platform Development | pH-responsive indicator integration with absorbent cores creates premium positioning in hospital procurement frameworks. |
| Extended Producer Responsibility Compliance | California packaging waste regulations force brand owners toward recyclable mono-material constructions with certified circular supply chains. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included FDA 510(k) clearance databases, EU MDR technical documentation repositories, hospital procurement contract disclosures, and customs trade records for fluff pulp and super absorbent polymer feedstocks. Bottom-up modeling of converter capacity and top-down demand triangulation from end-use segmentation anchored volume estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing for acrylic acid price volatility and REACH authorization timelines. Segmentation dimensions spanned product architecture, application regulatory tier, material feedstock type, and end-user contracting structure. CAGRs derived from installed base replacement cycles and penetration rate assumptions for gel sheet and smart dressing formats.
Practitioners should monitor ECHA substance restriction announcements and state-level extended producer responsibility enactments for early signals of material substitution acceleration. Forecasts reflect assumptions about regulatory timeline adherence and feedstock price stability; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
US Geotextile Market
Technical Textiles
E-Textile Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Construction Textile Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Technical Textile Market