
 Global Smart Fabrics Market | 2026-2036
Global Smart Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Fabrics Market Foresight
Multi-source component procurement is shifting toward captive yarn and fiber production among top smart fabric developers. DuPont leverages its polymer science heritage to dominate conductive fiber supply. Milliken & Company anchors North American military textile contracts through advanced weaving capabilities. Schoeller Textil specializes in European performance fabric finishing, competing on weather-responsive membrane integration.
Smart fabrics embed conductive polymers, shape-memory alloys, or piezoelectric ceramics into textile substrates to sense, react, or adapt to environmental stimuli, typically operating via integrated microcontrollers with power densities below 10 mW per sensing node. Their primary purpose spans biometric monitoring in wearable systems, thermal regulation in protective gear, and haptic feedback in automotive seating. Passive smart fabric technology leads current volume due to lower unit costs and simpler supply chains, while active smart fabric systems capture expanding margin pools in medical and defense applications where real-time data transmission justifies premium positioning. Sports and fitness applications are growing fastest as consumer electronics brands integrate muscle-oxygen sensors directly into compression garments.
The EU's REACH chemicals framework and CE marking requirements govern substance restrictions and electrical safety for conductive textiles sold in Europe, while the US FDA regulates smart fabrics making explicit health claims under wearable medical device pathways. China's GB standards through SAMR set electromagnetic compatibility thresholds for textile-integrated electronics. Stakeholders must monitor how divergent electrical safety certifications fragment product platform strategies across major demand centers.
Market Dynamics
Military procurement programs in the United States are accelerating adoption of conductive fabrics for soldier health monitoring, compressing supplier qualification timelines and reshaping volume allocation toward defense-grade certification holders.
Growth Catalysts
- Wearable Medical Device Pathways:The US FDA has clarified regulatory pathways for textile-integrated biometrics, enabling faster commercialization of cardiac-monitoring garments in clinical settings.
- EU Green Deal Textile Requirements:Mandates for recyclable phase change materials are forcing manufacturers to reformulate thermal-regulating fabrics, creating replacement demand across European performance apparel.
- Shenzhen Manufacturing Cluster Density:Proximity of apparel electronics integrators to polymer research institutes in China's eastern corridor shortens prototyping cycles for conductive yarn applications.
Market Restraints
- Silver Nanowire Cost Volatility:Conductive fiber production depends on precious metal inputs subject to commodity price swings, compressing margins on mid-tier sensor-embedded textiles.
- Single-Source Polymer Supply:Specialized piezoelectric ceramic precursors concentrate among Japanese chemical suppliers, exposing weavers to allocation risk during demand surges.
- Electromagnetic Compatibility Thresholds:China's GB standards through SAMR impose testing burdens that extend product launch timelines by four to six months for non-domestic entrants.
Strategic Opportunities
- Underpenetrated Indian Medical Textiles:CDSCO has yet to finalize wearable device classifications for fabric-based monitors, creating first-mover advantage for pre-registered product platforms.
- Agricultural Worker Safety Applications:Heat-stress monitoring in California's Central Valley and Spain's Almería greenhouse belt represents unaddressed demand for passive cooling fabrics with biometric feedback.
- Direct-to-Consumer Sports Channels:Compression garment brands are bypassing traditional sporting goods retailers, capturing margin through subscription-based sensor-data services.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Textile engineers with microcontroller programming capabilities command premium compensation, constraining R&D expansion at mid-scale weavers.
- Multi-Jurisdiction Certification Overlap:Products requiring both CE marking under EU MDR and FDA 510(k) clearance face redundant clinical testing protocols that extend capital lock-up periods.
- Legacy Garment Manufacturing Integration:Traditional cut-and-sew facilities lack cleanroom environments for conductive fiber handling, forcing costly facility retrofits or outsourced finishing.
Report Scope
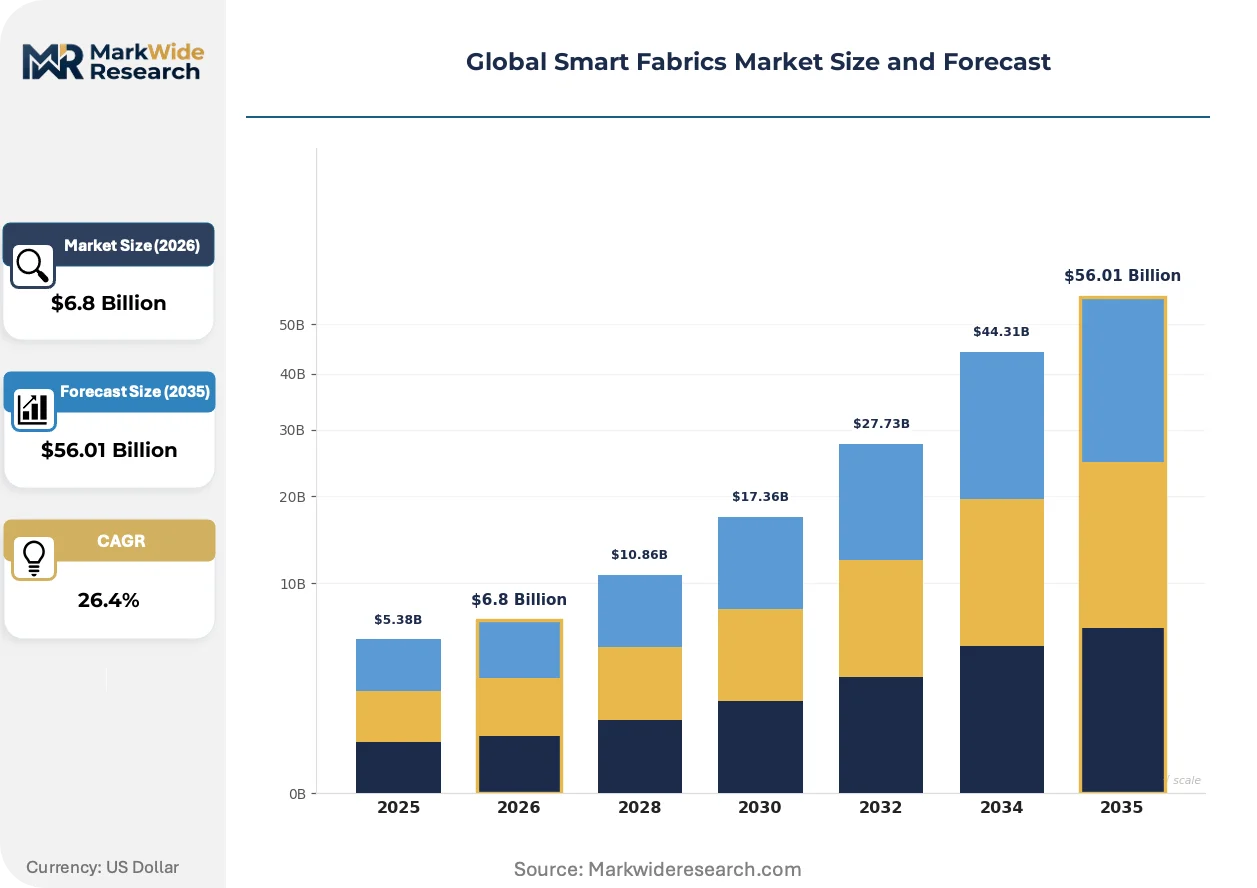
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Fabrics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $56.01 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Fabrics, Phase Change Materials, Shape Memory Fibers, Piezoelectric Textiles, Electrochromic Textiles Technology: Passive Smart Fabric, Active Smart Fabric, Ultra-Wideband, Piezoelectric, Thermochromic, Photonic Application: Military & Defense, Wearable Electronics, Automotive Interiors, Sports & Fitness, Space Exploration, Protective Clothing End User: Apparel Manufacturers, Fitness Equipment Makers, Aerospace Firms, Security Agencies, Consumer Electronics Brands |
| Companies Covered | DuPont, Textronics, Milliken & Company, Schoeller Textil, AiQ Smart Clothing, Adidas, Nike, Gentherm, Sensoria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Fabrics Market Shifts & Advancements
Conductive polymer deposition techniques are migrating from batch processing to continuous roll-to-roll manufacturing, collapsing unit economics for sensing-enabled textiles while fragmenting competitive advantage between chemical formulators and weaving specialists.
Micro-encapsulated phase change materials are integrating into polyester filament cores during melt-spinning, enabling thermal-regulating properties without secondary finishing steps. Athletic apparel brands in Germany and South Korea are adopting these fibers at commercial scale for marathon and cycling collections. This integration is compressing lead times from fiber production to finished garment by eliminating coating-stage bottlenecks.
REACH substance restrictions under ECHA oversight are tightening thresholds for halogenated flame retardants in conductive coatings, forcing reformulation of military-grade fabrics previously qualified under legacy chemistries. European defense textile contractors are responding by accelerating qualification of phosphorus-based alternatives, with Sweden's FMV procurement agency setting 2027 compliance deadlines for new supply contracts.
Hospital procurement departments are consolidating vendor lists for patient-monitoring textiles, shifting from multi-supplier spot purchasing to multi-year sole-source agreements with integrated service obligations. This concentration is displacing smaller weaving houses in Italy's Como district that lack capital reserves for inventory financing. The shift is most visible in National Health Service trusts across England, where framework agreements now bundle garment supply with data-analytics subscriptions.
Global Smart Fabrics Market Segmentation
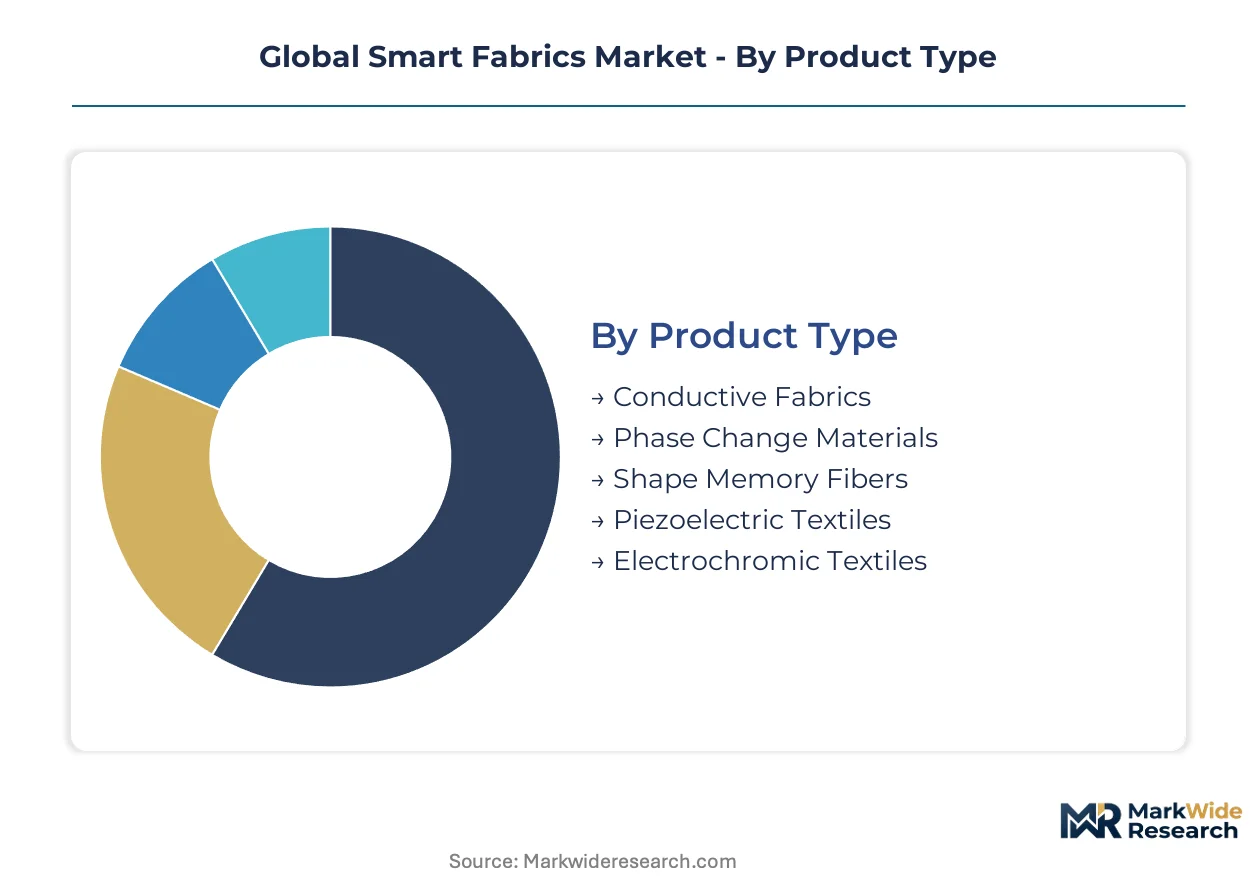
Smart fabrics demand fragments across material chemistry, power architecture, and end-use certification requirements. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Material chemistry determines conductivity mechanism, durability cycles, and integration complexity with textile substrates.
- Conductive Fabrics:Silver nanowire or carbon-based coatings enable signal transmission across garment surfaces. US military procurement programs compress qualification timelines for soldier health monitoring systems, favoring suppliers with existing defense contracts.
- Phase Change Materials:Micro-encapsulated paraffin or salt hydrates embedded in fiber cores absorb and release thermal energy. EU Green Deal recyclability mandates are forcing European manufacturers to reformulate away from petroleum-derived paraffins toward bio-based alternatives.
- Shape Memory Fibers:Nickel-titanium alloys or polymer networks revert to programmed configurations upon thermal stimulus. Medical compression therapy applications in Germany and Japan drive specification refinement.
- Piezoelectric Textiles:Ceramic or polymer films generate electrical charge from mechanical deformation. Energy-harvesting prototypes for wearable power remain pre-commercial.
- Electrochromic Textiles:Conductive polymers shift color via applied voltage. Automotive seating applications in South Korea and Italy emphasize aesthetic customization over functional sensing.
Mature deployment sits with conductive fabrics in defense and medical monitoring. Newer deployment is concentrated in phase change materials as sustainability regulations tighten.
Technology:
Power architecture separates segments by energy requirement, data transmission capability, and microcontroller integration depth.
- Passive Smart Fabric:No external power required; functionality derives from material properties alone. Thermal regulation and moisture-wicking dominate volume, with lower unit costs sustaining mass-market sports apparel in China's eastern manufacturing corridor.
- Active Smart Fabric:Integrated power sources and microcontrollers enable real-time sensing and data transmission. FDA-cleared cardiac monitoring garments in US clinical settings command premium pricing justified by continuous biometric streams.
- Ultra-Wideband:High-bandwidth wireless communication for precise indoor positioning. Warehouse worker safety applications in Germany's logistics hubs pilot location-tracking uniforms.
- Piezoelectric:Mechanical-to-electrical energy conversion for self-powered sensing. Research-stage integration with gait analysis in Japanese rehabilitation centers.
- Thermochromic:Temperature-responsive color change without electrical input. Children's safety apparel in Nordic markets indicates heat exposure thresholds.
- Photonic:Light-manipulating structures for optical signaling or camouflage. Experimental military applications in Sweden and Australia explore adaptive visibility.
Passive systems anchor current volume through simpler supply chains. Active configurations are expanding most quickly where real-time data justifies reimbursement or operational efficiency gains.
Application:
End-use certification requirements and performance specifications fragment demand across radically different procurement channels.
- Military & Defense:Soldier health monitoring, ballistic protection integration, and thermal signature management. US Army PEO Soldier and Sweden's FMV procurement agencies compress supplier qualification timelines, reshaping volume toward defense-grade certification holders.
- Wearable Electronics:Consumer-facing biometric garments with smartphone connectivity. Fitness equipment makers in Shenzhen and Seoul integrate muscle-oxygen sensors into compression garments for direct-to-consumer subscription models.
- Automotive Interiors:Haptic feedback seating and climate-responsive cabin surfaces. German and Italian OEMs prioritize occupant wellness differentiation in premium vehicle segments.
- Sports & Fitness:Performance monitoring and recovery optimization. Marathon and cycling collections in Germany and South Korea adopt thermal-regulating fibers at commercial scale.
- Space Exploration:Radiation shielding and physiological monitoring for extravehicular activity. NASA and ESA contractor specifications drive extreme environment durability requirements.
- Protective Clothing:Industrial heat-stress monitoring and chemical exposure detection. California's Central Valley agricultural operations represent unaddressed demand for passive cooling with biometric feedback.
Defense and medical applications concentrate mature procurement frameworks. Sports and fitness channels are gaining share fastest as consumer electronics brands bypass traditional retail.
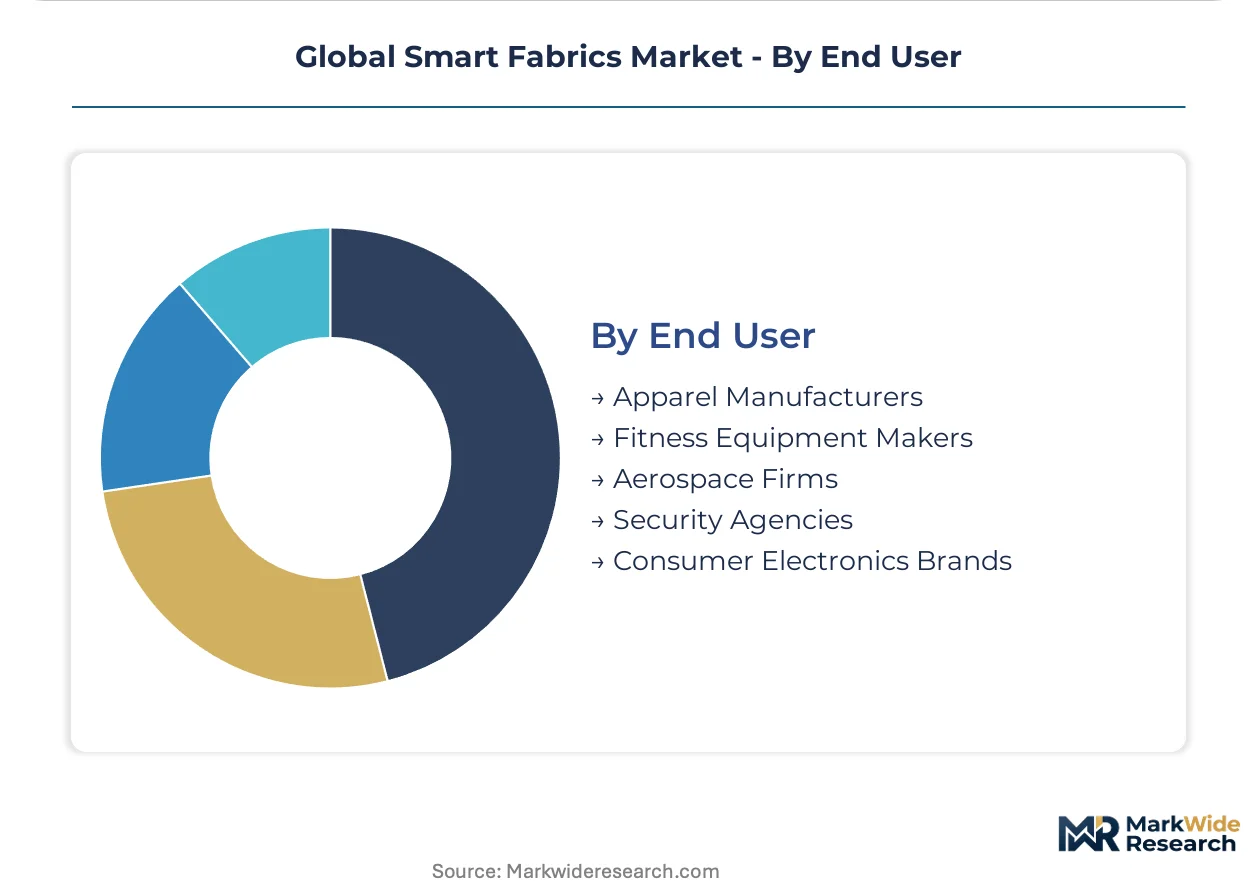
End User:
Customer type determines volume scale, customization depth, and inventory financing requirements.
- Apparel Manufacturers:Cut-and-sew operations integrating conductive components into finished garments. Italy's Como district weaving houses face displacement from NHS England framework agreements bundling supply with data analytics.
- Fitness Equipment Makers:Brands combining hardware with subscription-based sensor-data services. Direct-to-consumer compression garment brands capture margin through recurring revenue models.
- Aerospace Firms:Crew and passenger monitoring systems with extreme reliability specifications. Boeing and Airbus supplier qualification protocols extend development cycles.
- Security Agencies:Covert monitoring and personnel tracking applications. Classification requirements limit supplier visibility.
- Consumer Electronics Brands:Smartphone and wearable ecosystem integration. Shenzhen-based integrators cluster near polymer research institutes to shorten prototyping cycles.
Traditional apparel manufacturers dominate established channels. Consumer electronics brands are climbing the fastest through vertical control over sensor-data platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for smart fabrics concentrates in three distinct manufacturing and procurement corridors: US defense programs, Chinese electronics integration clusters, and European sustainability-driven reformulation mandates.
United States
US Army PEO Soldier procurement programs compress supplier qualification timelines for conductive fabrics in soldier health monitoring systems. FDA wearable medical device pathways enable faster commercialization of cardiac-monitoring garments in clinical settings. Boston-area medical device developers cluster near MIT polymer research labs to prototype textile-integrated biometrics.
China
Shenzhen-based apparel electronics integrators cluster near polymer research institutes in the eastern manufacturing corridor, shortening prototyping cycles for conductive yarn applications. SAMR GB standards impose electromagnetic compatibility thresholds that extend product launch timelines by four to six months for non-domestic entrants. Guangdong province hosts the densest concentration of fiber-to-garment vertical integration facilities.
Germany
Medical compression therapy applications in Baden-Württemberg drive specification refinement for shape memory fibers. ECHA REACH substance restrictions tighten thresholds for halogenated flame retardants in conductive coatings, forcing reformulation of legacy military-grade chemistries. Stuttgart automotive OEMs prioritize haptic feedback seating and climate-responsive cabin surfaces in premium vehicle segments.
Sweden
FMV procurement agencies set 2027 compliance deadlines for phosphorus-based flame retardant alternatives in defense textile contracts. EU Green Deal recyclability mandates push manufacturers toward bio-based phase change materials. Kista science park hosts experimental photonic textile research for adaptive military camouflage applications.
India
CDSCO has yet to finalize wearable device classifications for fabric-based monitors, creating first-mover advantage for pre-registered product platforms. Maharashtra textile belt weavers lack capital reserves for inventory financing required by hospital procurement consolidation. Tamil Nadu garment exporters face displacement from NHS England framework agreements bundling supply with data-analytics subscriptions.
Global Smart Fabrics Market Competitive Landscape
Multi-source component procurement dominates the current landscape as top developers shift toward captive yarn and fiber production. The vendor base separates into three tiers: polymer science heritage firms with conductive fiber supply control, advanced weaving specialists anchoring military contracts, and performance fabric finishers competing on membrane integration. Two strategic archetypes define competitive positioning: chemical formulators leveraging roll-to-roll manufacturing scale, and weaving houses defending through defense-grade certification holdings. Capacity expansion and strategic partnerships represent the dominant competitive moves, with facility retrofits for cleanroom conductive fiber handling proliferating among traditional cut-and-sew operations.
Within the polymer science tier, DuPont exemplifies backward integration into conductive fiber supply through material heritage advantages. Milliken & Company occupies a position among North American defense textile contractors through advanced weaving capabilities and existing military qualification holdings. Schoeller Textil AG represents the European performance finishing specialist archetype, competing on weather-responsive membrane integration and sustainability-driven reformulation compliance. These three anchors illustrate how competitive advantage fragments between chemical control, weaving certification, and regional regulatory alignment.
| Leading Market Players |
|---|
| DuPont |
| Textronics |
| Milliken & Company |
| Schoeller Textil |
| AiQ Smart Clothing |
| Adidas |
| Nike |
| Gentherm |
| Sensoria |
| Others |
Supply & Pricing Matrix
Captive yarn production among defense-grade certification holders anchors both supply security and pricing power, insulating qualified weavers from silver nanowire cost volatility while compressing margins for non-integrated competitors.
Pricing Analysis
Service-bundling separates premium-tier suppliers from commodity competitors, with NHS England framework agreements now integrating garment supply with data-analytics subscriptions. Pricing stratifies across defense-certified, medical-grade, and consumer-sports tiers, with FDA-cleared cardiac-monitoring garments commanding the widest premiums. Cost compression in mid-tier sensor-embedded textiles intensifies because silver nanowire inputs feed from precious metal commodity markets. Consumer electronics brands integrating muscle-oxygen sensors into compression garments show the least price sensitivity, while traditional cut-and-sew apparel manufacturers face the tightest margin constraints.
Supply Chain Analysis
Reverse-logistics capabilities remain underdeveloped for conductive fiber recovery, though EU Green Deal recyclability mandates are forcing pilot programs for phase change material reclamation. Manufacturing gravity centers on China's eastern corridor, Japan for piezoelectric ceramic precursors, and Germany for shape memory fiber finishing. Conductive polymer deposition draws from petrochemical feedstocks, silver nanowire inventories, and specialized ceramic precursors. Single-source vulnerability concentrates in Japanese chemical suppliers of piezoelectric precursors. Distribution runs through direct-to-consumer sports channels, hospital procurement frameworks, and military contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous roll-to-roll manufacturing is displacing batch processing for conductive polymer deposition, collapsing unit economics for legacy coating-stage operations.
For Market Incumbents: Extend defense-grade certification holdings into adjacent medical monitoring applications before CDSCO finalizes wearable device classifications in India. Deepen backward integration into conductive fiber production to offset silver nanowire cost volatility. Milliken & Company and DuPont demonstrate how polymer science heritage insulates margin position against commodity input swings. For New Entrants and Emerging Players: Agricultural worker safety applications in California's Central Valley and Spain's Almería greenhouse belt offer white-space entry with minimal incumbent saturation. CDSCO's pending regulatory clarity creates first-mover positioning for fabric-based biometric monitors in Maharashtra and Tamil Nadu. Pursue direct-to-consumer subscription models bypassing traditional sporting goods retail channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by consumer electronics brands seeking vertical control over sensor-data platforms. Long-term viability favors weaving houses with cleanroom retrofit capabilities and multi-jurisdiction certification holdings. Watch for FDA 510(k) clearance timelines as inflection indicators for medical-grade valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Facility Retrofit | Enables conductive fiber handling compliance for NHS England framework eligibility. |
| Backward Integration into Conductive Fiber Production | DuPont leverages polymer science heritage to secure supply against silver nanowire volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA 510(k) and CE marking pathways reduce redundant clinical testing capital lock-up. |
| Direct-to-Consumer Subscription Launch | Fitness equipment makers in Shenzhen capture recurring revenue through sensor-data services. |
| Bio-Based Phase Change Material Reformulation | ECHA REACH compliance secures European defense contracts with FMV's 2027 phosphorus-based deadline. |
Research Methodology
Multi-period observation of military procurement timelines, FDA clearance pathways, and ECHA reformulation deadlines anchored the trend analysis, supplemented by interviews with textile R&D directors, hospital procurement managers, defense contractor supply leads, and polymer research institute faculty. Secondary validation drew from FDA 510(k) filings, ECHA substance restriction updates, SAMR GB standard releases, and NHS England framework agreement disclosures. Bottom-up fiber production estimates triangulated against top-down end-use demand aggregation.
Segment-weighting applied differential growth assumptions across passive and active technology architectures, with material chemistry and power architecture as primary stratification axes. Modeled dimensions included conductive fabric type, end-use certification requirement, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and input-cost trajectory modeling. Silver nanowire price volatility and CDSCO regulatory timeline uncertainty fed scenario-based forecast ranges.
Revisions become necessary when ECHA tightens halogenated flame retardant thresholds beyond current phosphorus-based alternatives, when CDSCO accelerates wearable device classification finalization, or when US Army PEO Soldier procurement compresses qualification timelines further. Practitioners should monitor FMV defense contract award patterns and Shenzhen apparel electronics integrator clustering density for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
Waterproof Socks Market
Textile Innovations
Textile Felt Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Canvas Bags Market
Textile Innovations
GCC Textile Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Quilt Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Global Textile Market
Textile Innovations
Textile Acoustic Panel Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Smart Textile Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Handloom Products Market