
 Aramid Conveyor Belt Market | 2026-2036
Aramid Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Conveyor Belt Market Insights
Steel cord reinforcement is shifting toward aramid fiber cores in heavy-haul mining belts, cutting weight by roughly half while preserving tensile ratings. DuPont leverages its Kevlar polymer supply chain to anchor premium product lines across North American coal and copper operations. Kolon Industries competes through backward integration into para-aramid polymer production, sustaining cost advantages in Asian bulk-materials markets. Fenner Dunlop specializes in splicing-intensive installations where belt longevity determines total ownership economics.
An aramid conveyor belt incorporates aromatic polyamide fiber carcasses rated for operating temperatures exceeding 150°C, with tensile strengths surpassing 1000 N/mm in multi-ply configurations. Manufacturers calibrate cover compounds to resist abrasion, hydrocarbon exposure, and fire propagation in continuous-loop bulk handling systems. Solid woven constructions dominate underground mining procurement due to their anti-static and flame-retardant certifications, while modular belt formats capture food processing lines requiring hygienic washdown compatibility. Steel cord segments retain share in ultra-long overland routes where elongation control matters, though aramid hybrid designs are displacing pure steel in intermediate-distance applications.
OSHA mandates govern fire suppression and belting flammability in US underground mines, while REACH compliance in Europe restricts certain halogenated flame retardants in rubber compounds. China's SAMR enforces GB 7984 and GB 10822 standards for general-purpose and flame-resistant conveyor belts, respectively. Stakeholders must monitor evolving MEE enforcement on industrial product carbon footprints, as embodied emissions in aramid fiber production become a procurement criterion for ESG-screened mining houses.
Market Dynamics
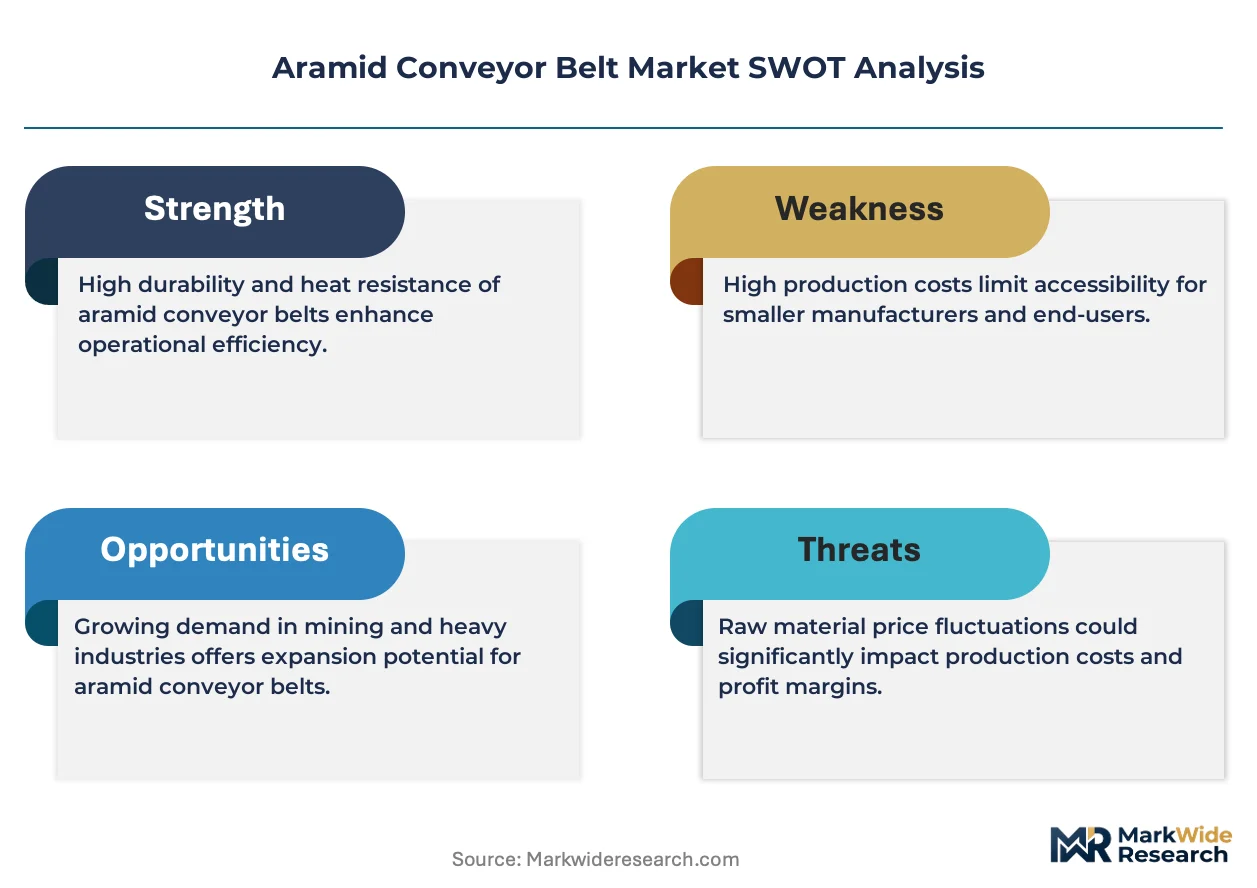
Steel cord displacement by aramid fiber cores is compressing belt weight by half while preserving tensile ratings, forcing manufacturers to reconfigure cover compound formulations and splicing protocols for mining procurement committees.
Growth Catalysts
- Underground safety mandates:Australia's state mining regulators enforce flame-resistant belting specifications for coal and hard-rock operations, accelerating solid woven procurement cycles.
- REACH compliance deadlines:ECHA restrictions on halogenated flame retardants in rubber compounds are pushing European compounders toward phosphorus-based alternatives compatible with aramid carcasses.
- Platinum belt ore intensity:South Africa's Bushveld Complex drives replacement demand as ore transport volumes strain belt lifecycles in continuous-loop configurations.
Market Restraints
- Para-aramid polymer supply concentration:DuPont and Kolon Industries control upstream polymer production, creating input cost volatility for mid-tier belt fabricators without captive supply.
- Steel cord retention in ultra-long routes:Elongation control requirements in overland systems exceeding 15 kilometers limit aramid penetration to intermediate-distance applications.
- GB 10822 certification timelines:China's SAMR flame-resistance testing protocols extend product approval cycles by 8-14 months for imported belting.
Strategic Opportunities
- Modular belt format expansion:Food processing lines requiring hygienic washdown compatibility present white space for aramid-reinforced thermoplastic modules in North American poultry and dairy plants.
- Dual carbon procurement criteria:China's MEE enforcement on industrial product carbon footprints creates preference premiums for low-embodied-emission aramid fiber in ESG-screened mining house tenders.
- Sensor-embedded predictive maintenance:RFID and fiber-optic strain monitoring convergence enables outcome-based service contracts replacing transactional belt sales in Chilean copper operations.
Industry Challenges
- Splicing technician certification gaps:Fenner Dunlop's specialized installation protocols require trained crews that mining contractors struggle to retain in remote Australian and South African sites.
- Legacy steel cord infrastructure retrofit:Existing pulley diameters and take-up configurations in mature mining districts complicate aramid belt integration without capital-intensive system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Conveyor Belt Market |
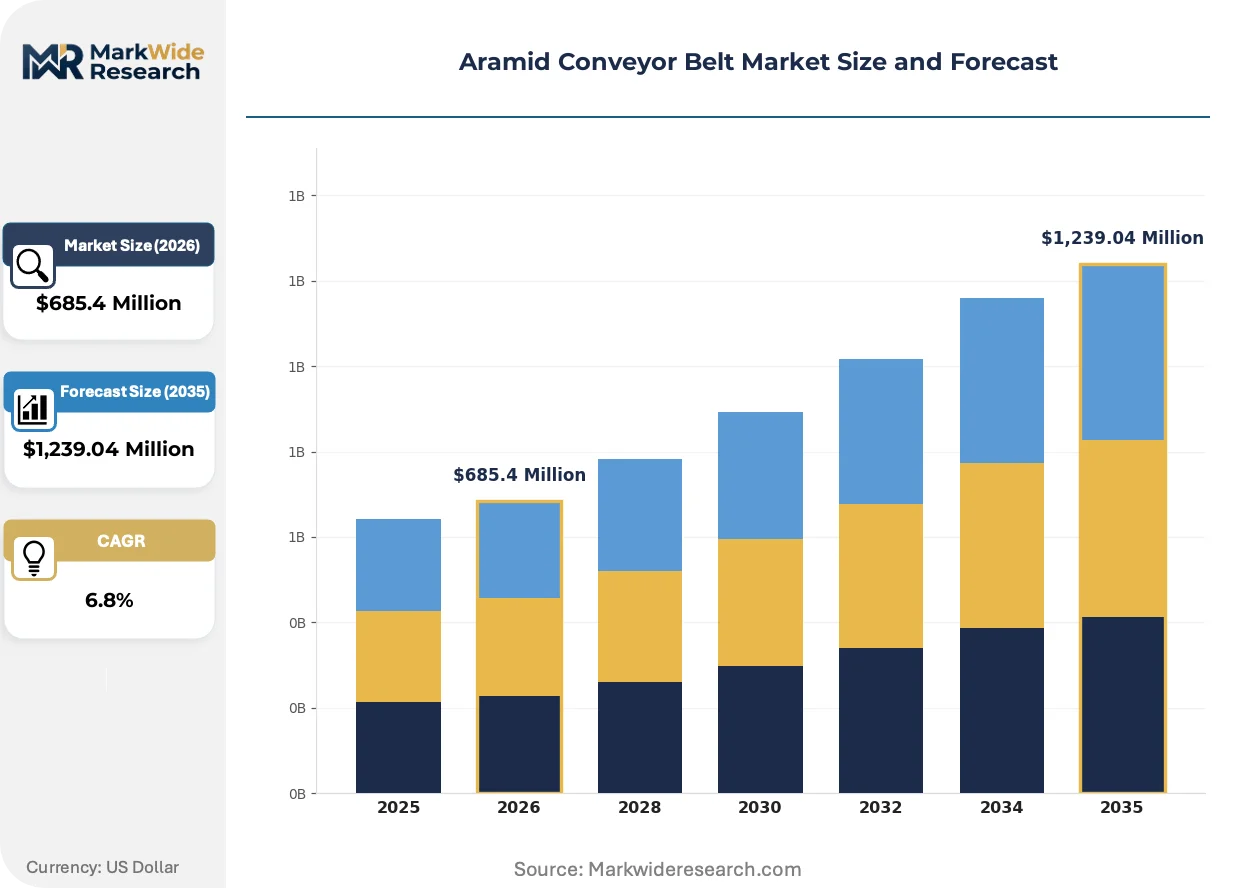
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Woven, Steel Cord, Modular Belt, Lightweight Application: Mining, Manufacturing, Food Processing, Logistics End User: Mining Companies, Food Manufacturers, Automotive, Warehousing Material: Polyester, Nylon, Aramid, Others |
| Companies Covered | Kolon Industries, Sinochem International, DuPont, Sinopec Yizheng, Yantai Tayho, Teijin, Toray Advanced Materials, Metso Outotec, Fenner Dunlop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Conveyor Belt Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are compressing traditional belt construction paradigms while opening modular formats for new end-use verticals previously served by steel or polyester alternatives.
Hybrid aramid-steel carcass construction is unifying tensile strength with weight reduction in heavy-haul mining belts. Anglo American's Chilean copper operations piloted these configurations in 2022, compressing energy consumption per ton-kilometer by reducing rotating mass. The technology is unifying procurement specifications across intermediate-distance routes previously segmented by pure material type.
ECHA's REACH restrictions on short-chain chlorinated paraffins are forcing compounders to reformulate cover rubbers for European underground mining. The industrial consequence is accelerated validation of phosphate ester and metal hydrate flame retardants that maintain aramid fiber thermal stability. German coal operations and Polish lignite transport systems face the tightest compliance deadlines, with procurement committees now requiring pre-certified compound documentation.
Lifecycle contracting is displacing transactional belt sales in Australian iron ore and South African platinum operations. Mining houses unbundle splicing, monitoring, and replacement scheduling into multi-year service agreements with availability guarantees. This shift concentrates purchasing authority with head-office engineering teams rather than site maintenance managers, compressing vendor margins while extending contract tenures. Western Australia's Pilbara region exhibits the most advanced adoption, with Rio Tinto and BHP structuring decade-long belt management partnerships.
Aramid Conveyor Belt Market Segmentation
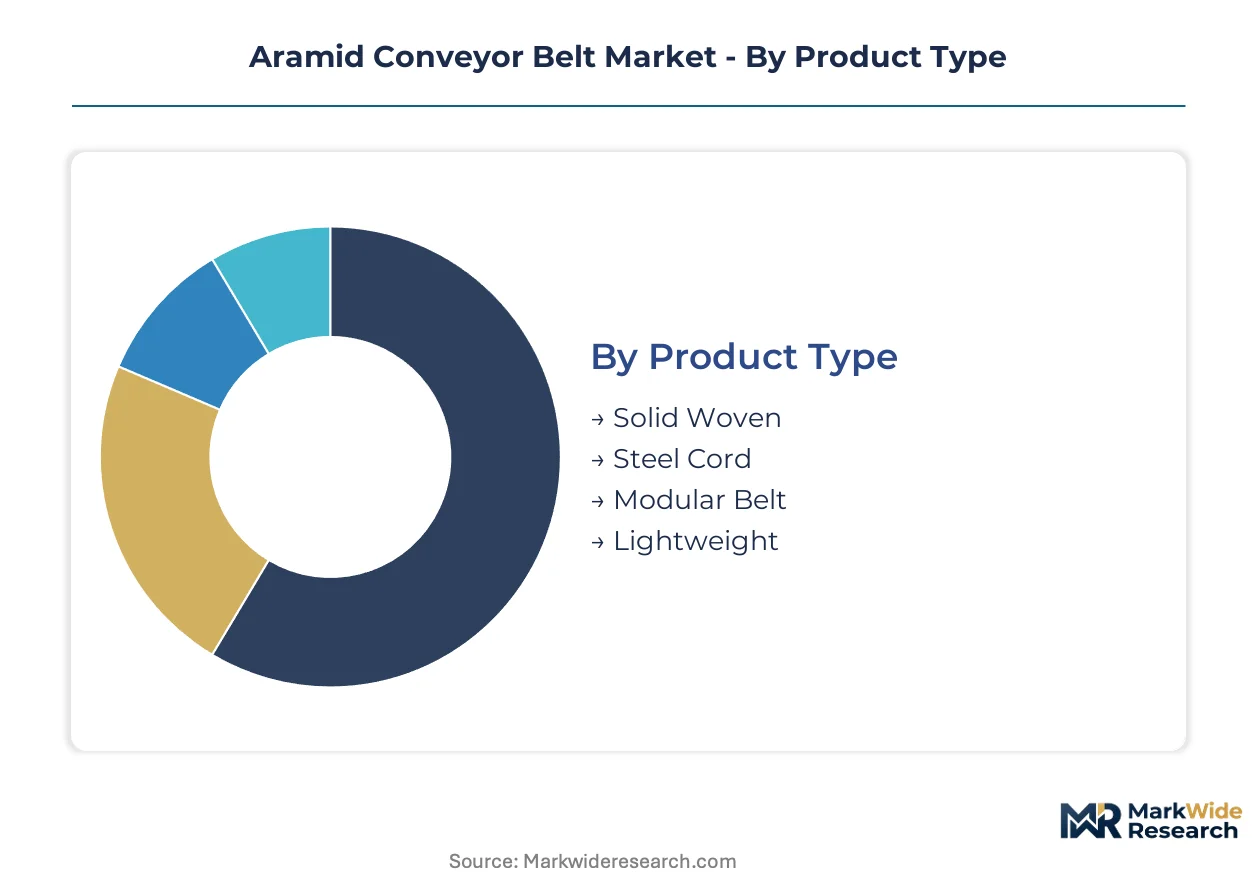
Segmentation in the aramid conveyor belt market reflects divergent procurement priorities across safety-critical underground mining, hygiene-regulated food processing, and cost-sensitive logistics operations. Buyers calibrate specifications against fire-resistance mandates, washdown compatibility, and total ownership economics rather than unit price alone.
Product Type:
Cost tier separates procurement committees—premium solid woven commands underground mining safety budgets while economy lightweight belts serve surface logistics with minimal regulatory burden.
- Solid Woven:Multi-ply aramid carcasses with solid woven construction achieve flame-retardant and anti-static certifications required for underground coal and hard-rock operations. Australia's state mining regulators enforce these specifications, accelerating replacement cycles in Queensland and New South Wales coal belts.
- Steel Cord:Hybrid aramid-steel configurations preserve elongation control for overland routes exceeding 15 kilometers while cutting rotating mass. Anglo American's Chilean copper operations piloted these designs to compress energy consumption per ton-kilometer.
- Modular Belt:Thermoplastic modules with aramid reinforcement capture food processing lines requiring hygienic washdown protocols in North American poultry and dairy plants.
- Lightweight:Reduced-ply aramid constructions serve parcel sorting and airport baggage systems where load intensity permits material minimization.
Solid woven leads volumes today; modular belt is gaining share fastest.
Application:
Volume concentration tracks ore transport intensity—underground mining generates replacement demand at 3-4x the frequency of surface manufacturing lines.
- Mining:Continuous-loop bulk handling in platinum, copper, and coal operations strains belt lifecycles through abrasion, impact, and tensile loading. South Africa's Bushveld Complex drives concentrated demand as ore transport volumes exceed design thresholds.
- Manufacturing:Assembly line conveyance for automotive and heavy equipment production employs aramid belts where heat resistance exceeds 150°C operating temperatures.
- Food Processing:USDA and FDA sanitary mandates require thermoplastic modular formats with aramid cores that withstand caustic washdown cycles without fiber degradation.
- Logistics:E-commerce distribution centers specify lightweight aramid constructions for high-speed sortation where belt weight reduction translates to motor energy savings.
Mining anchors procurement volumes; food processing shows the steepest expansion trajectory.
End User:
Customer type determines contract structure—mining houses unbundle lifecycle services while food manufacturers transact on unit replacement.
- Mining Companies:Rio Tinto and BHP in Western Australia's Pilbara region structure decade-long belt management partnerships with availability guarantees, concentrating purchasing authority with head-office engineering teams.
- Food Manufacturers:Tyson Foods and dairy cooperatives specify modular thermoplastic constructions certified for USDA poultry and FDA dairy contact surfaces.
- Automotive:OEM assembly plants deploy heat-resistant aramid belts in paint shop and welding operations where temperature spikes degrade polyester alternatives.
- Warehousing:Third-party logistics operators prioritize lightweight aramid specifications to minimize conveyor motor loads across multi-tenant distribution facilities.
Mining companies concentrate contract value; automotive end users are expanding procurement most quickly.
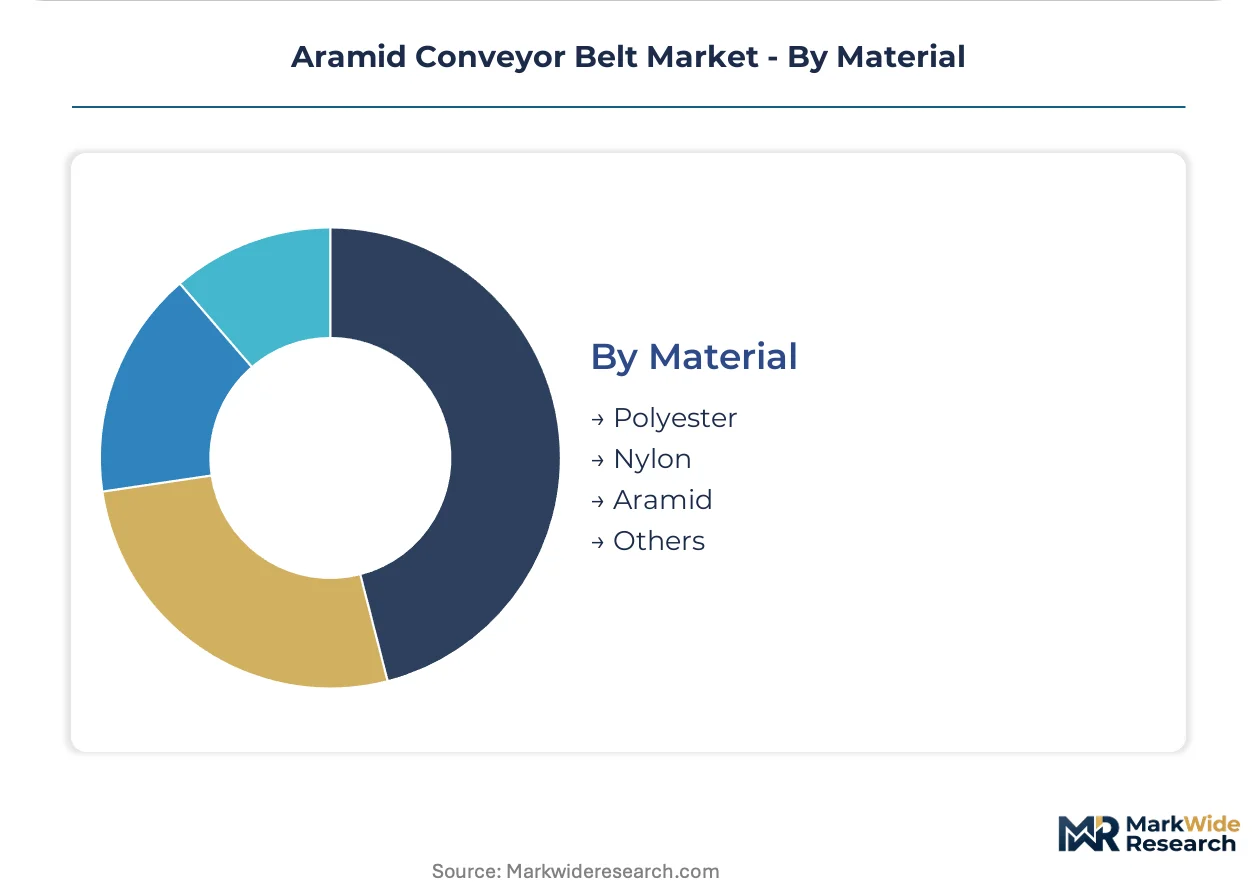
Material:
Supply concentration dictates procurement risk—para-aramid polymer production sits with DuPont and Kolon Industries, creating input cost volatility for fabricators without captive supply.
- Aramid:Aromatic polyamide fibers rated for tensile strengths surpassing 1000 N/mm and thermal stability above 150°C. ESG-screened mining houses in Australia and Chile now embed embodied carbon metrics from aramid fiber production into tender evaluations.
- Polyester:Lower-cost synthetic alternative retains share in surface logistics and light manufacturing where fire resistance and temperature ratings are non-critical.
- Nylon:Polyamide 6 and 66 constructions serve medium-duty applications requiring abrasion resistance without aramid's premium tensile performance.
- Others:PBO and carbon fiber reinforcements penetrate niche aerospace and defense material handling with extreme strength-to-weight requirements.
Aramid dominates premium procurement; polyester retains volume in cost-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara iron ore belt generates concentrated replacement demand as Rio Tinto and BHP restructure procurement around lifecycle service contracts. Underground safety mandates in Queensland coal operations accelerate solid woven adoption. The country's mining regulators enforce flame-resistant specifications that compress procurement cycles.
Australia
Queensland and New South Wales coal belts drive solid woven procurement as state mining regulators enforce flame-resistant specifications. Australia's national safety authority mandates anti-static certification for underground operations. Western Australia's Pilbara region hosts decade-long belt management partnerships between major miners and service providers.
China
GB 10822 flame-resistance testing protocols extend approval cycles for imported belting by 8-14 months. SAMR enforcement tightens material specifications for underground coal transport. Shanxi and Inner Mongolia coal basins concentrate domestic procurement as state-owned mining groups consolidate supplier relationships.
United States
OSHA mandates govern fire suppression and belting flammability in underground coal and copper mines. Appalachian coal operations and Arizona copper districts drive replacement demand. Southwestern mining clusters pilot sensor-embedded predictive maintenance systems.
South Africa
The Bushveld Complex platinum belt strains belt lifecycles through continuous-loop ore transport intensity. National mining safety regulations require flame-resistant certifications for underground operations. Limpopo and North West provinces concentrate procurement authority with head-office engineering teams.
Chile
Anglo American's copper operations pilot hybrid aramid-steel configurations to compress energy consumption per ton-kilometer. National mining safety standards align with international flame-resistance protocols. Antofagasta and Atacama regions host the most advanced lifecycle contracting adoption in Latin America.
Aramid Conveyor Belt Market Competitive Landscape
Backward integration into para-aramid polymer production dominates the current landscape as manufacturers seek supply security. The vendor base separates into three tiers: integrated polymer producers, specialized belt fabricators, and regional service providers. DuPont and Kolon Industries anchor the upstream tier through captive polymer supply. Fenner Dunlop occupies the service-intensive segment. Competitive moves concentrate on vertical integration and geographic expansion into mining-intensive regions.
Among integrated polymer producers, DuPont and Kolon Industries represent the upstream control archetype through in-house para-aramid production. Teijin and Toray Advanced Materials occupy positions within the advanced materials tier. Fenner Dunlop exemplifies the service-specialist model. These anchors demonstrate how supply chain configuration and installation expertise separate competitive positions in mining procurement.
| Leading Market Players |
|---|
| Kolon Industries |
| Sinochem International |
| DuPont |
| Sinopec Yizheng |
| Yantai Tayho |
| Teijin |
| Toray Advanced Materials |
| Metso Outotec |
| Fenner Dunlop |
| Others |
Pricing and Supply Chain Analysis
Mining house procurement committees in Australia and Chile concentrate purchasing authority with head-office engineering teams, shifting contract structures toward lifecycle service agreements that embed splicing, monitoring, and replacement scheduling into multi-year availability guarantees. This buyer consolidation compresses vendor margins while extending contract tenures, creating pricing power asymmetries that favor integrated polymer producers over mid-tier fabricators.
Pricing Analysis
Input-cost pass-through from para-aramid polymer supply concentration governs pricing dynamics, with DuPont and Kolon Industries controlling upstream production and creating volatility for fabricators without captive supply. Three-tier pricing structure across premium solid woven, standard hybrid configurations, and economy lightweight tiers separates procurement by certification grade and fire-resistance rating. Cost compression in the economy tier intensifies as polyester alternatives retain share in surface logistics applications. Mining companies exhibit the lowest price sensitivity due to total ownership economics focus, while third-party logistics operators prioritize unit cost minimization.
Supply Chain Analysis
Reverse-logistics flows for belt refurbishment and core recovery are underdeveloped, though lifecycle contracting models in Western Australia's Pilbara region increasingly specify end-of-life material return clauses. Manufacturing concentrates in China, South Korea, and the United States, with para-aramid fiber production anchored in DuPont's North American facilities and Kolon Industries' Korean operations. Raw material dependencies center on p-phenylenediamine and terephthaloyl chloride feedstocks for polymer synthesis. Single-source vulnerability in para-aramid polymer supply creates structural risk for mid-tier fabricators. Distribution runs through mining equipment distributors and direct OEM relationships with major mining houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through weight-reduction engineering that cuts rotating mass per ton-kilometer, enabling premium pricing for hybrid aramid-steel configurations that compress energy consumption in heavy-haul routes.
For Market Incumbents: Deploy backward integration into para-aramid polymer production to secure input cost stability against DuPont and Kolon Industries supply dominance. Anchor premium positioning through GB 10822 and REACH pre-certification investments that accelerate approval timelines for mining procurement committees. Defend against modular belt entrants by extending splicing technician certification programs that create switching costs in remote Australian and South African installations. For New Entrants and Emerging Players: The price-point gap between premium solid woven mining belts and economy lightweight logistics specifications creates white-space opportunity for mid-tier hybrid configurations targeting intermediate-distance overland routes. Food processing modular formats in North American poultry and dairy plants represent the most penetrable segment given USDA and FDA sanitary mandates that disqualify steel alternatives. Pursue private-label partnerships with established mining equipment distributors to bypass direct procurement committee access barriers. For Investors and Strategic Acquirers: Mining equipment OEMs are the most active acquirer in this space, seeking to bundle belting into integrated material handling system offerings. Long-term viability hinges on carbon footprint differentiation as China's MEE enforcement and ESG-screened mining house tenders embed embodied emissions metrics into supplier evaluation. Target mid-tier fabricators with established splicing service capabilities in Chilean copper or South African platinum districts. Monitor REACH compliance deadline acceleration and SAMR carbon disclosure expansion as inflection indicators for premium-tier demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Kolon Industries' captive para-aramid supply sustains cost advantages against non-integrated Asian competitors. |
| Lifecycle Service Contract Expansion | Rio Tinto and BHP's decade-long belt management partnerships in Western Australia concentrate vendor relationships. |
| Modular Belt Format Development | Tyson Foods and dairy cooperatives drive USDA poultry and FDA dairy contact surface certification requirements. |
| Sensor-Embedded Predictive Maintenance | RFID and fiber-optic strain monitoring convergence enables outcome-based contracts in Chilean copper operations. |
| REACH-Compliant Compound Reformulation | ECHA restrictions on halogenated flame retardants force phosphate ester validation for German coal and Polish lignite systems. |
Research Methodology
Multiple input streams — technical interviews with mining maintenance directors and plant engineers, procurement lead discussions at Anglo American and BHP, and splicing technician field assessments — were reconciled against customs and trade data, mining safety regulator filings from Australia's state authorities and China's SAMR, and SEC disclosures from integrated polymer producers. Bottom-up belt volume estimates by mining route distance and replacement cycle frequency were triangulated against top-down mining capex flow analysis.
Cross-referencing historical procurement patterns with panel input from mining house engineering teams shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product construction type, application intensity tier, end-user contract structure, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates in high-ore-intensity routes and modular format penetration trajectories in food processing. Forecast inputs incorporated GB 10822 approval timeline extensions and REACH compliance deadline acceleration.
Caveats apply where SAMR enforcement intensity on industrial carbon footprints or MEE disclosure expansion could materially shift the outlook toward low-embodied-emission aramid fiber premiums. Forecasts reflect assumptions on mining production volume continuity and polymer supply concentration stability. Practitioners should monitor ECHA restriction list updates and Chinese dual carbon procurement criteria adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Agro Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
US Geotextile Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Global Agricultural Textiles Market