
 Global PTFE Fabric Market | 2026-2036
Global PTFE Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global PTFE Fabric Market Outlook
China is fragmenting global PTFE fabric supply as domestic producers expand woven and coated capacity for electronics and food processing lines. W. L. Gore & Associates leverages its vertical integration in membrane-laminated architectures to sustain premium positioning in aerospace sealing. Saint-Gobain Performance Plastics Corporation anchors European demand through specialized PTFE-coated glass fabrics for industrial insulation. DAIKIN INDUSTRIES, Ltd. competes on fluoropolymer resin backward integration, controlling feedstock quality for tape and gasket grades.
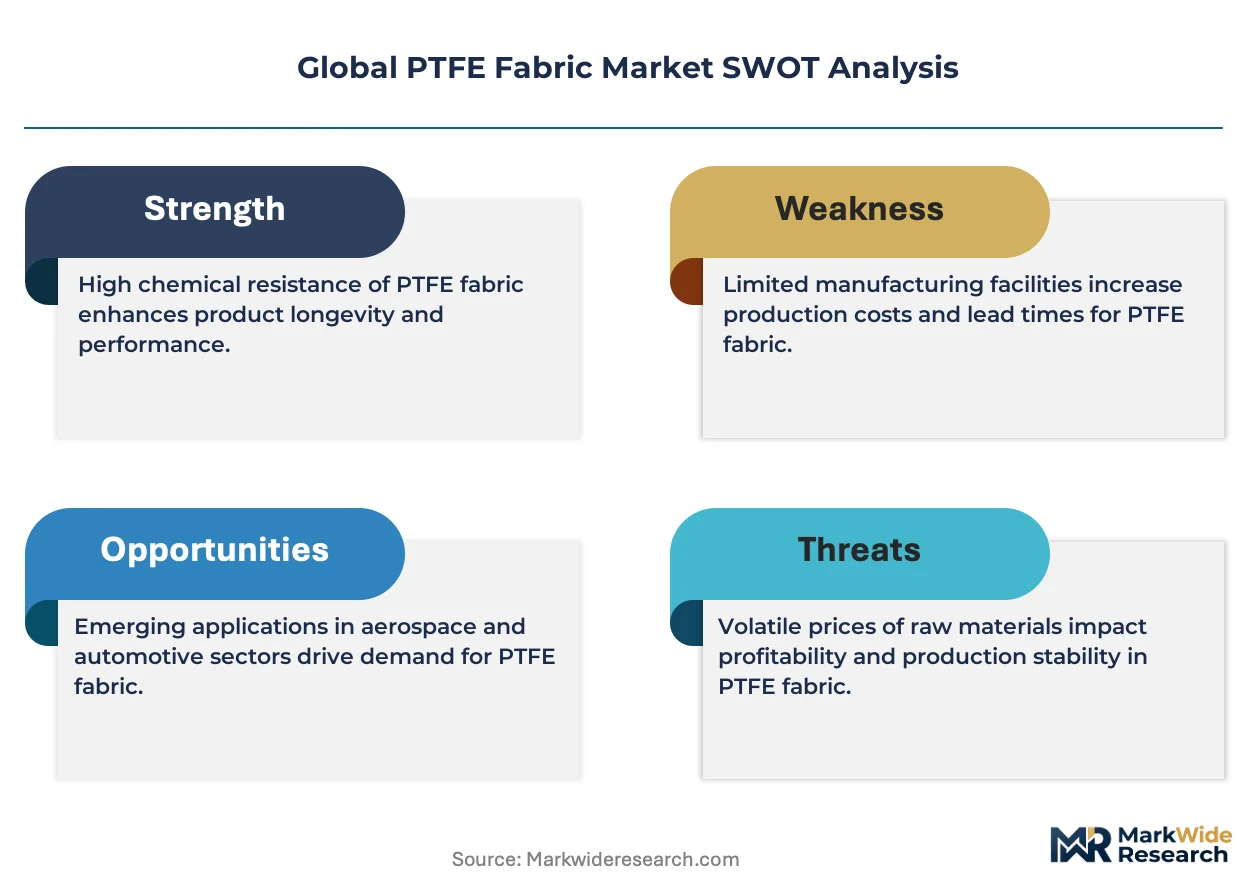
PTFE fabric comprises polytetrafluoroethylene resin extruded or sintered into woven, non-woven, laminated, or coated textile forms, typically operating between minus seventy degrees Celsius and two hundred sixty degrees Celsius with dielectric constants below 2.1. These properties serve sealing, thermal insulation, and low-friction conveying across chemical processing, electronics, and aviation systems. Sheets and tapes dominate current revenue pools where gasket and sealing applications command specification-driven procurement. Coated fabrics represent the fastest-expanding technology segment as food processing and automotive buyers prioritize surface-release and chemical resistance in conveyor belt deployments.
FDA food-contact regulations, EPA fluoropolymer emissions guidelines, and REACH perfluorinated substance restrictions collectively elevate compliance costs and favor producers with certified resin traceability. EMA medical device standards and EU Green Deal fluoropolymer phase-down timelines are redirecting R&D investment toward modified PTFE and alternative fluoropolymer architectures. Stakeholders must monitor regulatory divergence between European restriction pathways and United States grandfathering approaches to anticipate which product grades retain multi-jurisdiction market access.
Market Dynamics
PTFE fabric supply chains are bifurcating between resin-backward integrated Asian producers and specification-certified Western converters, as aerospace and medical end-users impose dual-source mandates and batch-traceability requirements that fragment procurement patterns.
Growth Catalysts
- Aerospace Thermal Protection:FAA certification timelines for new aircraft programs are compressing qualification cycles for PTFE-coated insulation systems, pulling forward specification lock-ins from Boeing and Airbus tier-one suppliers.
- REACH Perfluorinated Substance Restrictions:ECHA's evolving PFAS roadmap is redirecting European demand toward certified resin-traceable grades, favoring producers with verified supply chain documentation.
- Food Processing Automation:Surface-release conveyor belt specifications in automated bakery and meat processing lines are accelerating coated fabric replacement cycles in Germany and Japan.
Market Restraints
- Fluorspar Concentration:Acid-grade fluorspar feedstock for PTFE resin synthesis concentrates in Chinese and Mexican mining jurisdictions, exposing converters to export quota volatility.
- EU Green Deal Phase-Down Timelines:The European Commission's fluoropolymer reduction pathway is compressing long-term demand visibility for standard PTFE grades in industrial insulation.
- Modified PTFE Substitution:Perfluoroalkoxy (PFA) and fluorinated ethylene propylene (FEP) alternatives are displacing conventional PTFE in semiconductor wafer handling above 200°C thresholds.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating first-mover openings for PTFE-coated cleanroom conveyor systems in Gujarat and Tamil Nadu clusters.
- EMA Medical Device Convergence:EU MDR recertification waves are forcing device manufacturers toward PTFE-impregnated antimicrobial textiles for implantable mesh applications.
- Carbon-Neutral Resin Architectures:Fluoropolymer producers with bio-based or recycled-content PTFE pilot lines can capture premium positioning ahead of CSRD disclosure mandates.
Industry Challenges
- Fluoropolymer Sintering Expertise Gap:Specialized technicians for controlled-temperature PTFE film calendering are concentrated in aging workforces across Japanese and German manufacturing bases.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA food-contact, EPA emissions, and REACH SVHC compliance is extending product launch timelines by 14-22 months for new coated fabric grades.
- Legacy DCS Integration:PTFE fabric lamination lines in North American chemical processing plants require costly SCADA retrofits to meet current ISA cybersecurity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PTFE Fabric Market |
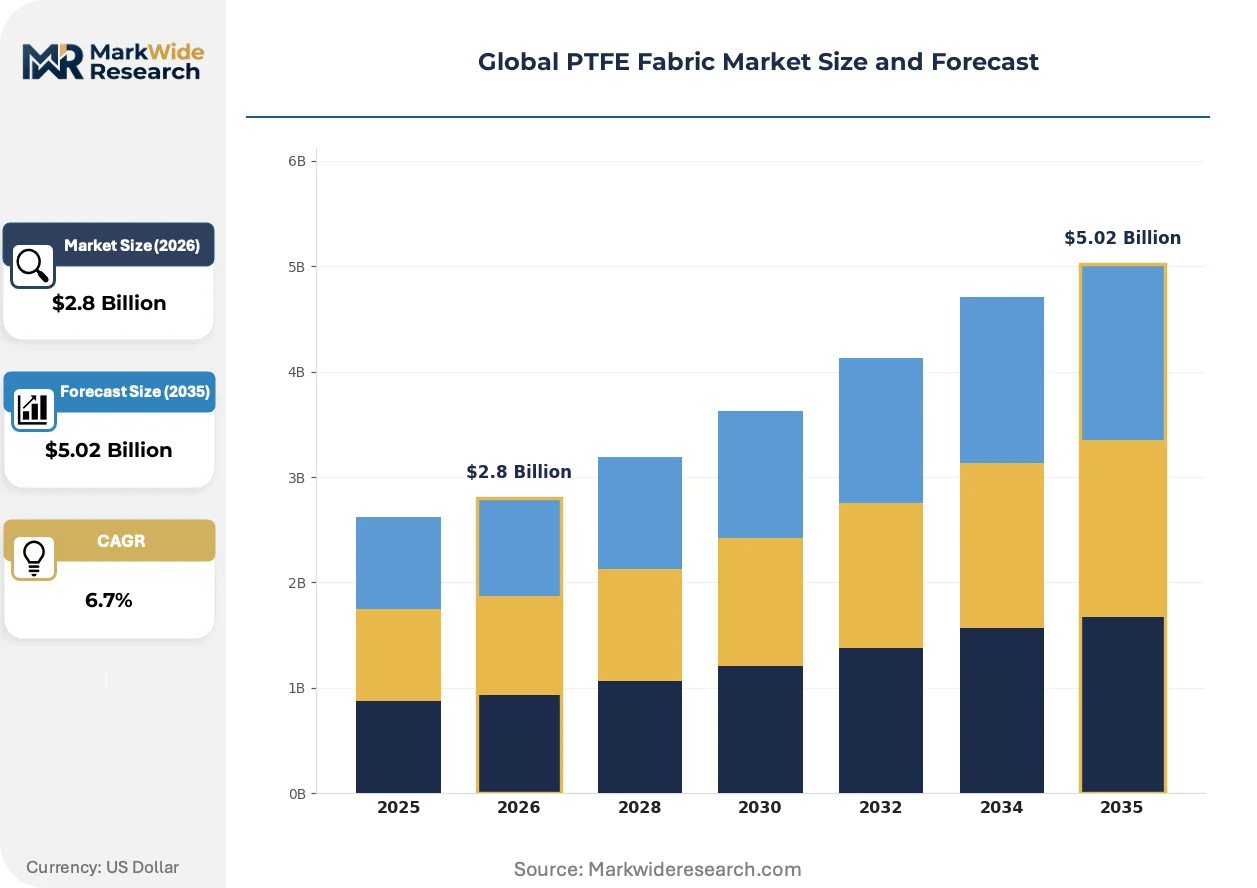
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Tapes, Coatings, Fabrics End User: Aerospace, Electronics, Automotive, Food Processing Application: Sealing, Insulation, Conveyor Belts, Gaskets Technology: Woven, Non-Woven, Laminated, Coated |
| Companies Covered | W. L. Gore & Associates, Inc., Saint-Gobain Performance Plastics Corporation, DAIKIN INDUSTRIES, Ltd., Taconic, 3M, The Chemours Company, Fothergill Group, Birdair, Inc., Sefar AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PTFE Fabric Market Strategic Shifts
Digital twin deployment across PTFE resin synthesis and fabric finishing lines is compressing batch-to-batch variation while enabling predictive maintenance that reduces unplanned downtime in continuous sintering operations.
Modified PTFE (mPTFE) with perfluoropropyl vinyl ether comonomer incorporation is virtualizing the performance gap between standard PTFE and PFA in chemical processing gaskets, allowing seal manufacturers to consolidate inventory SKUs while maintaining creep resistance at 150°C operating temperatures. mPTFE adoption is accelerating among German chemical valve OEMs seeking REACH-compliant alternatives to conventional grades.
EPA fluoropolymer emissions guidelines under the Clean Air Act are forcing US-based resin producers to install thermal oxidizer upgrades at Ohio and West Virginia manufacturing sites, redirecting capital from capacity expansion toward compliance infrastructure. The aerospace sealing segment is absorbing these cost pass-throughs through multi-year specification lock-ins.
Specification-driven procurement is consolidating buyer power among tier-one automotive and electronics OEMs, compressing supplier margins while elevating the importance of certified resin traceability and lot-level documentation. Direct mill relationships are displacing distributor intermediaries in high-volume coated fabric purchasing for Japanese and South Korean electronics conveyor deployments.
Global PTFE Fabric Market Segmentation
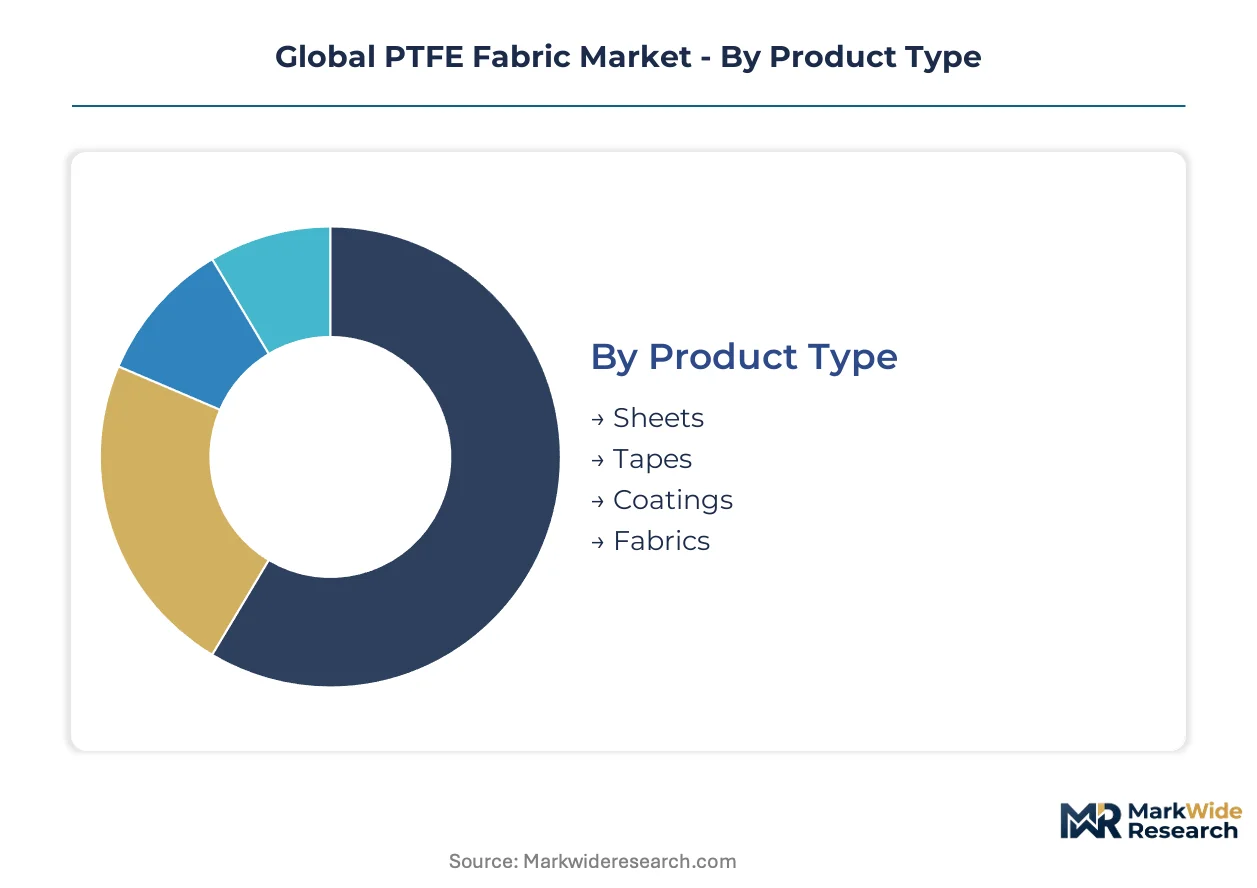
PTFE fabric procurement patterns diverge sharply across product geometries and end-use specifications. Aerospace buyers prioritize lot-traceable laminated systems while food processors drive volume through coated conveyor substrates. Understanding these segment boundaries clarifies where specification premiums apply versus where resin cost dominates.
Product Type:
Cost tier separates specification-driven aerospace grades from commodity industrial supply.
- Sheets:Calendered PTFE films ranging from 0.05mm to 6mm thickness serve die-cut gasket production and chemical tank lining. German chemical valve OEMs specify creep-resistant modified PTFE sheets for 150°C steam service, absorbing REACH-compliant resin premiums.
- Tapes:Skived or extruded PTFE with silicone or acrylic adhesive backing seals threaded pipe joints and electrical cable entries. Boeing and Airbus tier-one suppliers lock in multi-year tape specifications during compressed FAA certification cycles.
- Coatings:Liquid PTFE dispersions applied via spray, dip, or powder processes protect industrial equipment surfaces.
- Fabrics:Woven fiberglass or aramid substrates impregnated with PTFE resin form flexible composite textiles.
Sheets command the established base. The steepest expansion runs through tapes.
End User:
Application criticality determines whether buyers accept resin-traceability premiums or prioritize unit cost.
- Aerospace:Thermal protection systems, fuel cell seals, and wire harness insulation require FAA-certified PTFE fabrics operating across minus seventy to two hundred sixty degrees Celsius. W. L. Gore & Associates leverages membrane-laminated architectures to sustain premium positioning in this segment.
- Electronics:Cleanroom conveyor belts, wafer handling components, and cable insulation demand low-particulation PTFE surfaces. Semiconductor fabricators in Gujarat and Tamil Nadu clusters under India's PLI scheme are creating first-mover openings for coated cleanroom systems.
- Automotive:Gasket and sealing applications in fuel systems and thermal management use PTFE fabrics for chemical resistance.
- Food Processing:Automated bakery and meat processing lines specify surface-release conveyor belts with FDA food-contact certification.
Aerospace commands the established base. Electronics climbs the fastest.
Application:
Functional performance requirements dictate resin grade selection and fabrication method.
- Sealing:Static and dynamic gasket applications in chemical processing, aviation, and automotive systems rely on PTFE's chemical inertness and compressibility. German valve OEMs are accelerating modified PTFE adoption as REACH-compliant alternatives to conventional grades.
- Insulation:Thermal and electrical barrier applications in aerospace and industrial equipment utilize PTFE's dielectric constant below 2.1.
- Conveyor Belts:Food processing and electronics manufacturing deploy PTFE-coated fabrics for low-friction, high-temperature material transport.
- Gaskets:Die-cut or formed PTFE fabric seals provide chemical resistance in flange connections and equipment enclosures.
Sealing commands the established base. Conveyor belts gain share fastest.
Technology:
Manufacturing method determines performance tier and addressable end-use scope.
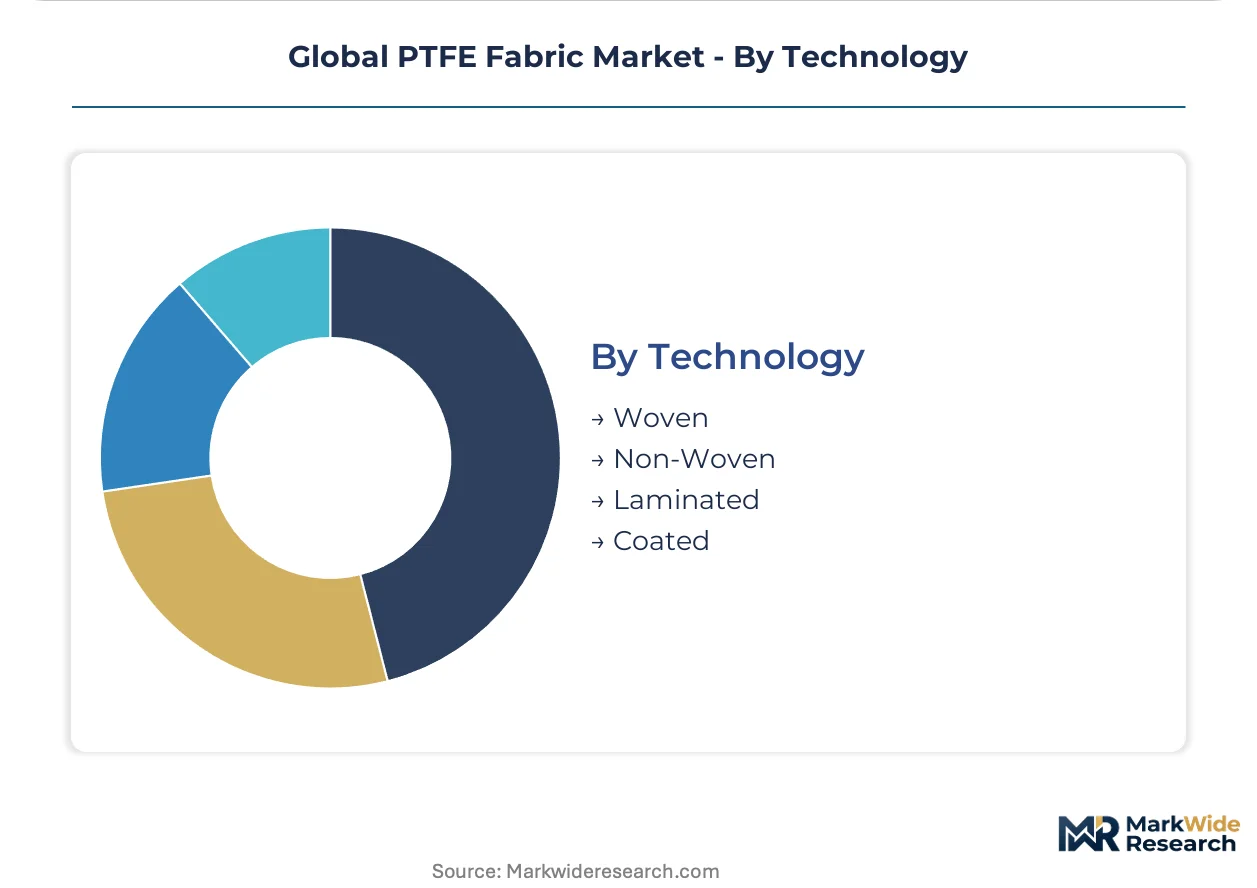
- Woven:PTFE yarns or PTFE-impregnated glass/aramid fibers woven into textile structures provide dimensional stability for industrial belting and architectural membranes.
- Non-Woven:Needle-punched or spun-bonded PTFE felts offer filtration media and cushioning applications.
- Laminated:Multi-layer composites bonding PTFE films to fabric substrates create high-performance seals and barriers. W. L. Gore & Associates anchors premium aerospace positioning through proprietary membrane-lamination expertise.
- Coated:Fabric substrates impregnated or surface-coated with PTFE dispersions dominate food processing and electronics conveyor deployments. Japanese and South Korean electronics manufacturers are consolidating direct mill relationships for high-volume coated fabric purchasing.
Coated technology commands the established base. Laminated architectures climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific fluoropolymer logistics, channeling acid-grade fluorspar feedstock to coastal resin synthesis plants while European PTFE fabric demand flows through Rotterdam's chemical handling infrastructure.
United States
Aerospace thermal protection systems at Boeing's Everett facility and SpaceX's Hawthorne operations consume specification-locked PTFE fabrics. EPA Clean Air Act enforcement is forcing thermal oxidizer upgrades at Ohio and West Virginia resin plants. The Gulf Coast petrochemical corridor concentrates coated fabric conversion for chemical processing gaskets.
Germany
Automated bakery and meat processing lines across Bavaria and Baden-Württemberg accelerate surface-release conveyor belt replacement cycles. REACH perfluorinated substance restrictions under ECHA's PFAS roadmap redirect procurement toward certified resin-traceable grades. The Rhine-Ruhr industrial belt hosts modified PTFE gasket production for chemical valve OEMs seeking creep-resistant steam service materials.
China
Electronics manufacturing in the Yangtze River Delta and Pearl River Delta scales PTFE-coated cleanroom conveyor deployments for semiconductor fabrication. Domestic woven and coated capacity expansion is fragmenting global supply as local producers capture food processing line demand. Shanghai's chemical industrial zone concentrates fluorspar-to-resin backward integration.
Japan
Semiconductor wafer handling equipment in the Tokyo-Yokohama corridor and Kyushu's chip fabrication parks drive low-particulation PTFE surface specifications. METI industrial standards govern fluoropolymer emissions from Nagoya-area resin finishing operations. Osaka-Kobe manufacturing clusters specialize in laminated membrane architectures for precision sealing applications.
India
PLI scheme incentives for semiconductor and display fabrication in Gujarat's Dholera cluster and Tamil Nadu's Sriperumbudur electronics corridor create first-mover openings for PTFE-coated cleanroom systems. BIS certification requirements for industrial textiles are elevating import substitution pressure. Mumbai-Pune chemical processing belt demands FDA-compliant conveyor fabrics for pharmaceutical packaging lines.
Global PTFE Fabric Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and substrate supply. The market structures around three tiers: resin-backward integrated Asian producers, specification-certified Western converters, and regional fabric finishers serving food processing and industrial belting. Competitive moves concentrate on batch-traceability documentation for aerospace dual-source mandates and direct mill relationship consolidation among Japanese and South Korean electronics buyers.
Among US-based platform integrators, W. L. Gore & Associates, Inc. occupies a position exemplifying membrane-laminated architecture specialization. Saint-Gobain Performance Plastics Corporation represents European specification-certified conversion, while DAIKIN INDUSTRIES, Ltd. anchors the resin-backward integrated archetype with captive fluoropolymer feedstock control. These three patterns—lamination expertise, regional certification compliance, and upstream integration—define the competitive vectors shaping procurement fragmentation.
| Leading Market Players |
|---|
| W. L. Gore & Associates, Inc. |
| Saint-Gobain Performance Plastics Corporation |
| DAIKIN INDUSTRIES, Ltd. |
| Taconic |
| 3M |
| The Chemours Company |
| Fothergill Group |
| Birdair, Inc. |
| Sefar AG |
| Others |
Value Chain & Pricing Dynamics
Chinese acid-grade fluorspar mining jurisdictions concentrate upstream feedstock control, anchoring resin cost structures that cascade through converter margins and specification premiums in aerospace sealing tiers.
Pricing Analysis
REACH perfluorinated substance restrictions dictate the pricing tier structure across the PTFE fabric market. Three-tier pricing structure across aerospace-certified, industrial-standard, and commodity-economy levels separates lot-traceable laminated systems from basic coated conveyor substrates. Cost compression in commodity grades intensifies because domestic Chinese producers expand woven and coated capacity for food processing lines. Electronics manufacturers in Japan and South Korea exhibit lowest price sensitivity due to dual-source mandates and batch-traceability requirements, while industrial belting buyers in emerging clusters prioritize unit cost over certification documentation.
Supply Chain Analysis
Toll converters and specialized fabric finishers in Germany, Japan, and the United States hold specification-certified capacity for aerospace and medical grade production. Geographic supply concentrates in China for resin synthesis and coated fabric conversion, in Germany for modified PTFE gasket calendering, and in Japan for laminated membrane architectures. Raw material dependencies draw from acid-grade fluorspar feedstock, high-purity PTFE resin dispersions, and woven glass or aramid substrate textiles. Single-source vulnerability runs through Chinese fluorspar export quota volatility. Distribution runs through direct mill relationships displacing distributor intermediaries in high-volume electronics conveyor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among tier-one automotive and electronics OEMs, compressing supplier margins while elevating certified resin traceability requirements that fragment procurement patterns across specification tiers.
For Market Incumbents: Insulate specification-locked aerospace positions through multi-year certification lock-ins with Boeing and Airbus tier-one suppliers during compressed FAA qualification cycles. Deepen backward integration into fluorspar-to-resin supply chains to offset feedstock volatility from Chinese export quotas. Prioritize thermal oxidizer compliance infrastructure ahead of EPA Clean Air Act enforcement waves. For New Entrants and Emerging Players: Pursue first-mover positioning in India's PLI scheme electronics manufacturing clusters, specifically Gujarat's Dholera and Tamil Nadu's Sriperumbudur corridors where PTFE-coated cleanroom conveyor demand outpaces certified supplier presence. Target carbon-neutral resin architecture pilots ahead of CSRD disclosure mandates. Anchor go-to-market strategy through BIS certification pathways for industrial textile import substitution. For Investors and Strategic Acquirers: Capital is best deployed toward resin-backward integrated specialists with verified REACH-compliant supply chain documentation and aerospace dual-source qualification status. Long-term viability hinges on regulatory divergence navigation between European restriction pathways and United States grandfathering approaches. Watch for ECHA PFAS roadmap acceleration as inflection indicator for modified PTFE substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Feedstock | Captive acid-grade supply secures resin cost stability against Chinese export quota volatility. |
| REACH-Compliant Certification Investment | ECHA PFAS roadmap compliance opens European aerospace and medical device procurement channels. |
| Direct Mill Relationship Consolidation | Bypassing distributor intermediaries captures margin in Japanese and South Korean electronics conveyor demand. |
| Modified PTFE Capacity Expansion | PFA-FEP substitution resistance at 150°C thresholds sustains gasket share in German chemical valve OEM supply. |
| Carbon-Neutral Resin Pilot Lines | Bio-based or recycled-content positioning captures premium ahead of EU CSRD disclosure mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with resin synthesis plant managers, aerospace tier-one procurement leads, chemical valve OEM technical directors, and food processing line maintenance engineers; alongside secondary validation through customs and trade flow databases, SEC 10-K filings from listed fluoropolymer producers, ECHA substance restriction notifications, and FAA certification documentation. Bottom-up segment sizing triangulated against top-down macro industrial production indices.
Forecast inputs span product geometry categories, end-use criticality tiers, technology fabrication methods, and regional regulatory cluster divergence. Modeled dimensions include specification grade, resin traceability certification, and regional production hub concentration. CAGRs were derived through segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporate PLI scheme incentive timelines for Indian electronics manufacturing and EU Green Deal fluoropolymer phase-down pathway assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, aerospace production rates, or semiconductor fabrication equipment spend would shift the trajectory. Cross-checking against fluoropolymer resin production capacity disclosures and regional customs export data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Absorbent Cover Market