
 Agri Textiles Market | 2026-2036
Agri Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Agri Textiles Market Outlook
China's agri textiles manufacturing belt is tilting toward higher-tenacity polypropylene capacity to serve Southeast Asian horticulture demand. Garware Technical Fibres Ltd. anchors India's export position through backward integration into polymer compounding. Freudenberg Performance Materials competes on non-woven crop cover technology for European greenhouse operators. Beaulieu Technical Textiles dominates Belgium's technical weaving infrastructure for geotextile applications.
Agri textiles encompass engineered fabrics manufactured from synthetic or natural fibers, typically ranging from 50 to 800 grams per square meter, designed to modify microclimates, suppress weeds, or reinforce soil structures in cultivation systems. Woven technology still occupies the largest production volume share due to its structural durability in geotextile deployment, while biodegradable materials represent the fastest-expanding margin pool as operators in the EU face landfill restrictions on conventional polymer disposal. Non-woven crop covers lead growth in frost protection applications across temperate horticulture zones.
The EU Green Deal and REACH framework restrict persistent polymer additives in mulch films sold across member states, directly redirecting procurement toward certified biodegradable alternatives. India's BIS standards for agricultural woven fabrics mandate UV stabilization thresholds that filter low-grade imports from unverified suppliers. China's GB standards and MIIT circular economy directives accelerate domestic recycling infrastructure for post-consumer shade netting. Stakeholders must monitor how divergent biodegradability certification schemes between Europe and Asia reshape cross-border product registration costs.
Market Dynamics
Precision agriculture deployment in controlled-environment farming is compressing product lifecycles and forcing substrate manufacturers to integrate climate-modulation capabilities directly into textile architecture rather than treating fabrics as passive inputs.
Growth Catalysts
- REACH biodegradability mandates:The EU Green Deal's landfill restrictions on conventional polymer disposal redirect procurement toward certified compostable mulch films, opening margin pools for substrate innovators.
- UV stabilization thresholds:India's BIS standards for agricultural woven fabrics filter low-grade imports and elevate domestic technical weaving capacity in Maharashtra and Gujarat clusters.
- Dual carbon goals:China's MIIT circular economy directives accelerate domestic recycling infrastructure for post-consumer shade netting, tightening supply loops around polypropylene recovery.
Market Restraints
- Propylene feedstock volatility:Polypropylene resin prices fluctuate with crude oil and naphtha spreads, compressing margin predictability for shade netting manufacturers lacking backward integration into polymer compounding.
- Biodegradability certification fragmentation:Divergent compostability standards between Europe's EN 13432 and Asia's emerging schemes inflate cross-border product registration costs and delay market entry timelines.
- Geographic supply concentration:Technical weaving capacity clusters disproportionately in Belgium's Flanders region and China's Shandong province, creating concentration risk for greenhouse operators seeking dual-source assurance.
Strategic Opportunities
- Underpenetrated Southeast Asian horticulture:Vietnam and Thailand's protected cultivation expansion lacks domestic high-tenacity polypropylene capacity, creating import substitution openings for Indian and Chinese exporters.
- Non-woven frost protection convergence:Spunbond-meltblown-spunbond technology hybridization with phase-change materials enables thermal buffering in temperate zone berry cultivation, displacing woven alternatives.
- PLI scheme tailwinds:India's production-linked incentive scheme for technical textiles subsidizes capital equipment for UV-stabilized crop cover manufacturing, accelerating capacity buildout in Surat and Ichalkaranji.
Industry Challenges
- Polymer compounding skill scarcity:Formulation chemists capable of balancing UV stabilizer loadings with biodegradation kinetics remain concentrated in legacy packaging film sectors, creating recruitment friction for agri textile specialists.
- Certification timeline compression:EU notified body backlogs for EN 13432 compostability testing extend validation cycles to 18-24 months, delaying revenue recognition for novel substrate launches.
- Legacy equipment retrofit complexity:Converting circular looms from geotextile to crop cover specifications requires reed and cam modifications that idle production lines for 6-8 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agri Textiles Market |
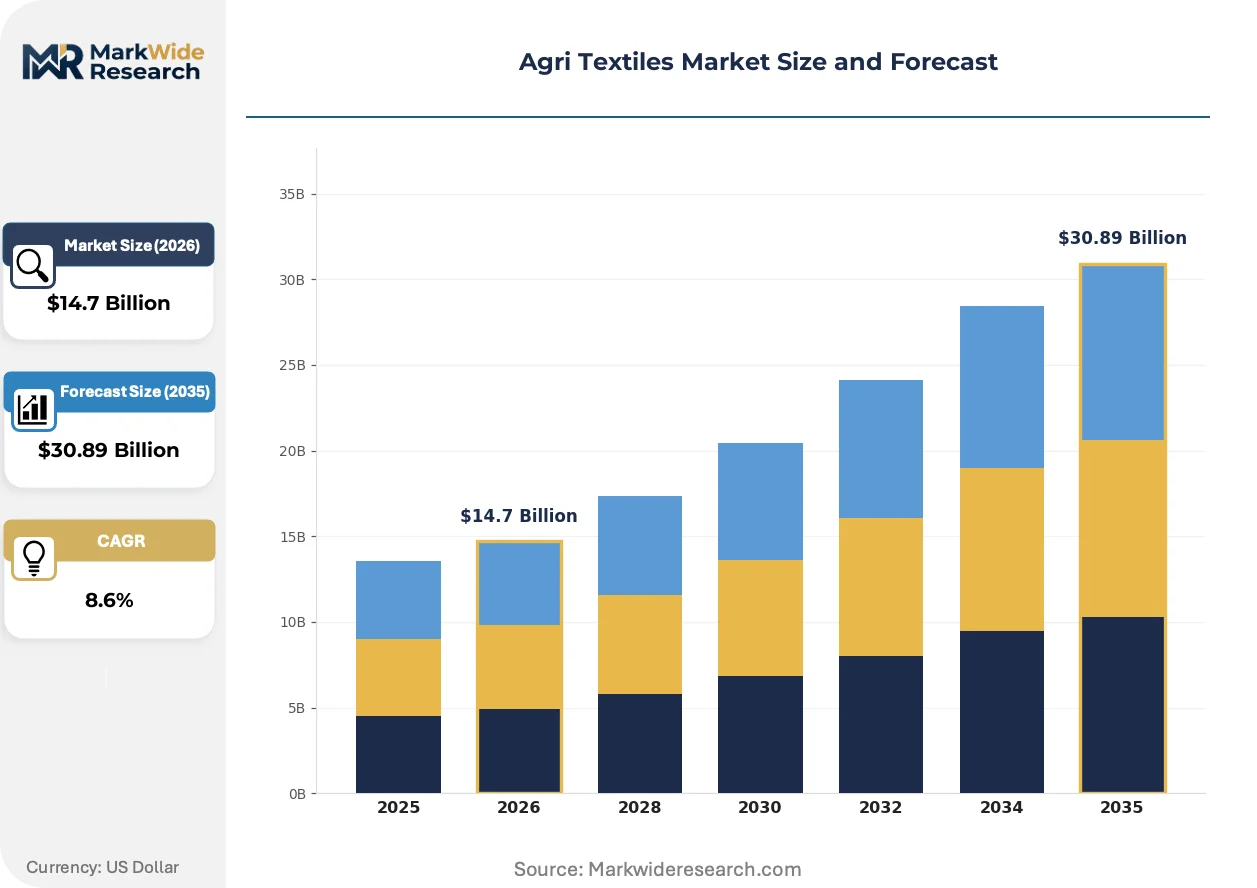
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Cover, Mulch Film, Shade Netting, Geotextiles End Use Industry: Agriculture, Horticulture, Aquaculture, Agroforestry Material: Polypropylene, Polyester, Natural Fiber, Biodegradable Technology: Woven, Non-Woven, Knitted, Coated |
| Companies Covered | Beaulieu Technical Textiles, Belton Industries, Garware Technical Fibres Ltd., TenCate Geosynthetics, Diatex SAS, Hy-Tex Limited, Freudenberg Performance Materials, Karatzis Group of Companies, Meyabond Industry & Trading (Beijing) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agri Textiles Market Strategic Shifts
Digital thread monitoring systems and bio-based polymer feedstocks are converging to transform how cultivation substrates are specified, validated, and recovered across closed-loop agricultural operations.
Sensor-embedded shade netting is virtualizing microclimate management by integrating fiber-optic temperature and humidity probes directly into polypropylene warp structures. Dutch greenhouse operators in Westland are deploying these smart textiles at pilot scale, compressing the feedback loop between environmental sensing and automated ventilation responses from minutes to seconds.
ECHA's restriction proposal on persistent organic pollutants in polymer additives is forcing reformulation of conventional mulch films across EU member states. Manufacturers serving the Spanish Almería greenhouse belt are accelerating starch-blend and polylactic acid substrate development to maintain shelf access ahead of 2027 enforcement timelines.
Direct contracting between substrate manufacturers and large-scale protected cultivation cooperatives is displacing traditional agricultural supply house distribution in California's Salinas Valley and Spain's Murcia region. Buyers are consolidating procurement volumes to secure lot-traceable quality documentation required for export certification to Northern European retail chains.
Agri Textiles Market Segmentation
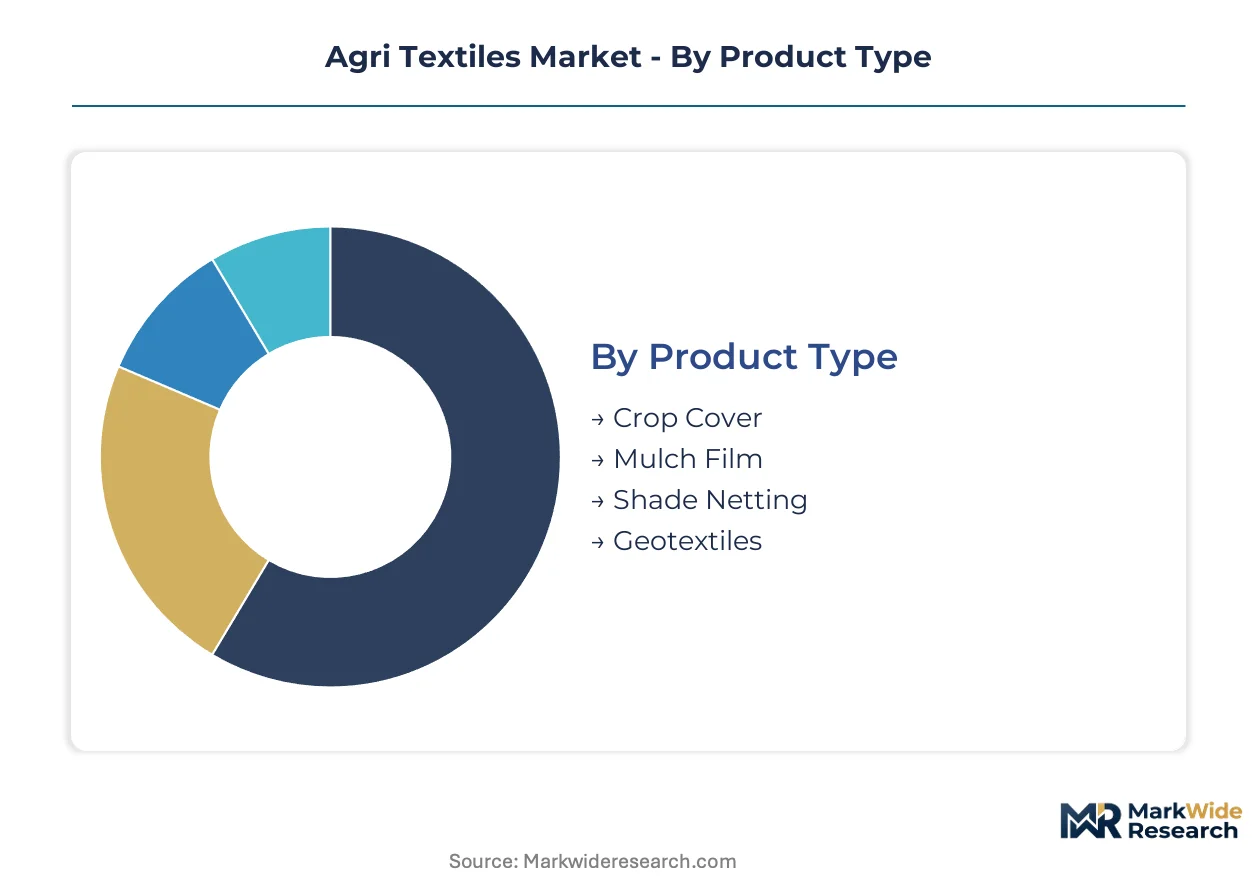
Agri textiles serve distinct cultivation functions that demand tailored substrate specifications, replacement cycles, and field-level technical support. Segment boundaries reflect how growers prioritize durability versus biodegradability, structural reinforcement versus climate modulation, and capital intensity versus operational flexibility in protected cultivation systems.
Product Type:
After-sales service intensity varies sharply across product types, with geotextile installations demanding on-site soil-engineering support while mulch films rely on seasonal technical advisories for optimal lay-down and retrieval timing.
- Shade Netting:High-tenacity polypropylene warp-knitted structures typically span 30-90% shading coefficients. Maharashtra and Gujarat greenhouse clusters drive procurement volumes for vegetable and floriculture operations under India's PLI scheme subsidies. UV stabilization formulation expertise determines field lifespan and replacement frequency.
- Mulch Film:Surface-deployed polymer sheets ranging from 15 to 50 microns thickness suppress weeds and modify soil temperature. Spanish Almería operators are accelerating starch-blend and polylactic acid substrate adoption ahead of EU Green Deal enforcement timelines for persistent additive restrictions.
- Crop Cover:Lightweight non-woven fabrics provide frost protection and pest exclusion in temperate horticulture zones. Spunbond-meltblown-spunbond technology hybridization with phase-change materials enables thermal buffering applications.
- Geotextiles:Heavy-duty woven or non-woven fabrics reinforce soil structures in drainage and erosion control. Belgian Flanders technical weaving infrastructure anchors European supply for civil engineering crossover applications.
Shade netting holds the largest share; momentum sits with mulch film as biodegradable certification reshapes procurement specifications.
End Use Industry:
Cost tier stratification separates capital-intensive protected cultivation from extensive open-field systems, with substrate pricing and service bundling calibrated to revenue per hectare differentials across end-use categories.
- Horticulture:Protected cultivation of vegetables, fruits, and ornamental crops in greenhouses and polytunnels demands climate-modulation textiles with precise spectral transmission properties. Dutch Westland operators pilot sensor-embedded shade netting with integrated fiber-optic probes for automated ventilation response.
- Agriculture:Broadacre field crop applications prioritize cost efficiency and mechanical durability in mulch film and geotextile deployment. California Salinas Valley cooperatives consolidate procurement volumes to secure lot-traceable documentation for Northern European retail chain certification.
- Aquaculture:Pond lining and cage netting applications require anti-fouling surface treatments and tensile strength specifications for submerged load conditions.
- Agroforestry:Silvicultural systems integrate weed suppression fabrics with tree establishment protocols, emphasizing biodegradation timelines aligned with canopy closure schedules.
Horticulture commands premium pricing tiers; aquaculture represents the steepest expansion trajectory as intensive pond systems proliferate in Southeast Asia.
Material:
Application-specific performance requirements dictate material selection, with load-bearing geotextile applications tolerating synthetic durability while surface-deployed mulch films face mounting regulatory pressure for biodegradable alternatives.
- Polypropylene:Dominant synthetic polymer for shade netting and woven geotextiles, offering high tenacity-to-weight ratios and chemical resistance. China's Shandong province manufacturing clusters are tilting capacity toward higher-tenacity grades to serve Vietnamese and Thai import demand.
- Biodegradable:Starch-blend, polylactic acid, and cellulosic substrates represent the fastest-expanding margin pool as EU REACH compliance redirects procurement from conventional polymers. Certification fragmentation between EN 13432 and Asian schemes inflates cross-border registration costs.
- Polyester:Higher modulus and UV stability than polypropylene for extended-lifecycle geotextile and coated fabric applications.
- Natural Fiber:Jute, coir, and hemp substrates serve erosion control and short-cycle mulch applications where complete biodegradation is operationally desirable.
Polypropylene retains volume leadership; biodegradable materials are climbing the fastest as landfill restrictions tighten across European member states.
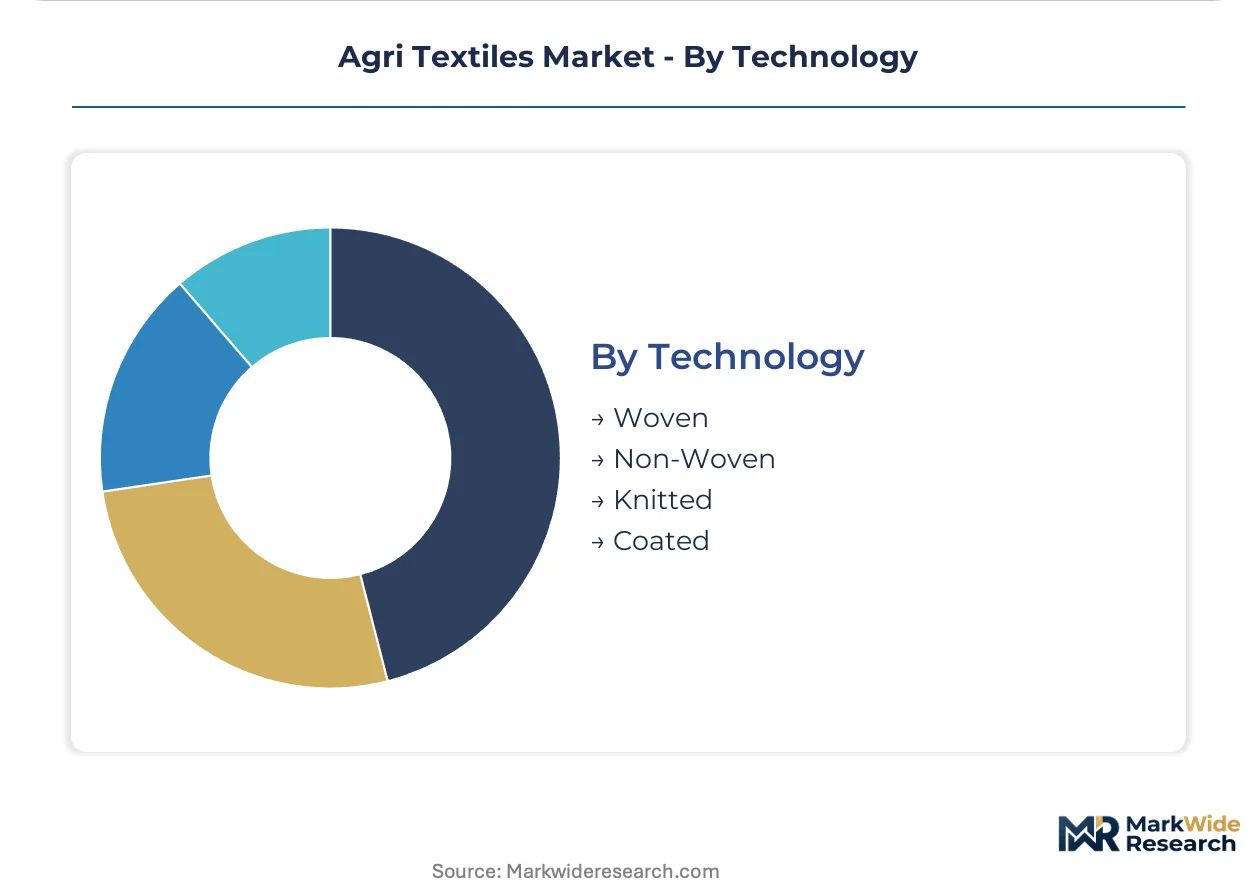
Technology:
Customer type segmentation separates infrastructure-grade woven specifications from seasonal non-woven consumables, with procurement patterns diverging between municipal engineering contractors and agricultural cooperatives.
- Woven:Interlaced warp and weft construction delivers structural durability for geotextile soil reinforcement and heavy-duty shade netting. Belgium's technical weaving infrastructure concentrates capacity for high-specification civil engineering applications.
- Non-Woven:Fiber-bonded structures via spunbond, meltblown, or needlepunch processes dominate crop cover and lightweight mulch applications. Frost protection deployment in temperate berry cultivation zones drives technology hybridization with phase-change materials.
- Knitted:Loop-structured fabrics provide dimensional stability and tear resistance for shade netting and protective crop covers.
- Coated:Polymer film lamination or chemical treatment adds waterproofing, anti-fouling, or UV-blocking properties to base textile substrates.
Woven technology maintains the largest production volume; non-woven formats are gaining share fastest in protected cultivation climate management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European procurement redirection toward certified biodegradable substrates, while divergent national standards across India, China, Spain, and Belgium reshape manufacturing concentration and cross-border trade flows.
India
Maharashtra and Gujarat greenhouse clusters drive shade netting procurement for vegetable and floriculture operations under the PLI scheme for technical textiles. BIS standards mandate UV stabilization thresholds that filter low-grade imports and elevate domestic technical weaving capacity. Surat and Ichalkaranji industrial corridors accelerate capital equipment deployment for UV-stabilized crop cover manufacturing.
China
Shandong province manufacturing clusters tilt capacity toward higher-tenacity polypropylene grades to serve Vietnamese and Thai horticulture import demand. MIIT circular economy directives accelerate domestic recycling infrastructure for post-consumer shade netting recovery. The Yangtze River Delta concentrates spunbond-meltblown-spunbond technology development for frost protection applications.
Spain
Almería greenhouse belt operators accelerate starch-blend and polylactic acid substrate development ahead of EU Green Deal enforcement timelines for persistent additive restrictions. The country's national agricultural regulator enforces compostability documentation requirements for mulch film shelf access. Murcia region buyers consolidate procurement volumes to secure lot-traceable quality certification for Northern European retail chain exports.
Belgium
Flanders technical weaving infrastructure anchors European supply for high-specification geotextile and heavy-duty shade netting applications. The EU Green Deal's landfill restrictions on conventional polymer disposal redirect procurement toward certified alternatives. Ghent and Kortrijk industrial zones concentrate circular loom capacity for civil engineering crossover applications.
United States
California's Salinas Valley cooperatives displace traditional agricultural supply house distribution through direct substrate manufacturer contracting. EPA guidelines influence polymer additive compliance frameworks for imported textiles. The Central Coast and Imperial Valley concentrate protected cultivation procurement for export-oriented vegetable operations.
Agri Textiles Market Competitive Environment
Backward-integrated polymer compounders and specialized technical weavers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: European non-woven technology specialists, Indian export-oriented integrated manufacturers, and Chinese scale-driven regional suppliers. Competitive moves center on biodegradability certification acquisition and Southeast Asian distribution partnerships.
Within the European non-woven tier, Freudenberg Performance Materials and Beaulieu Technical Textiles exemplify substrate innovation focused on climate-modulation applications. Garware Technical Fibres Ltd. represents the Indian integrated model with captive polymer compounding operations. These three anchors illustrate how geographic specialization aligns with divergent regulatory compliance requirements across REACH jurisdictions and BIS-mandated markets.
| Leading Market Players |
|---|
| Beaulieu Technical Textiles |
| Belton Industries |
| Garware Technical Fibres Ltd. |
| TenCate Geosynthetics |
| Diatex SAS |
| Hy-Tex Limited |
| Freudenberg Performance Materials |
| Karatzis Group of Companies |
| Meyabond Industry & Trading (Beijing) Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shandong province's polypropylene manufacturing clusters anchor global shade netting supply, with capacity utilization rates in China's chemical fiber belt directly transmitting into export pricing power for Southeast Asian horticulture buyers. Belgian Flanders technical weaving infrastructure and Indian Gujarat spinning mills complete a tripolar supply structure where geographic concentration shapes margin capture across biodegradable and synthetic substrate tiers.
Pricing Analysis
Price spreads between EU-certified biodegradable mulch films and conventional polypropylene alternatives span three distinct performance tiers based on EN 13432 compostability documentation and UV stabilization loadings. Certification grade and backward integration into polymer compounding emerge as the primary price differentiation drivers, with integrated manufacturers capturing premium positioning over import-dependent distributors. Pricing pressure intensifies in standard-grade shade netting as Chinese capacity expansion outpaces Vietnamese and Thai demand absorption. Smallholder cooperatives in India's Maharashtra belt exhibit highest price sensitivity, while Dutch greenhouse operators in Westland prioritize lot-traceable quality documentation over unit cost.
Supply Chain Analysis
Propylene feedstock draws from naphtha crackers concentrated in China's Shandong and Zhejiang provinces, India's Reliance-dominated western coast, and Belgian Antwerp refining complexes. Polypropylene resin, UV stabilizer masterbatches, and bio-based polymer feedstocks constitute the critical input trinity, with starch-blend and polylactic acid alternatives increasingly tethered to EU REACH compliance timelines. Single-source vulnerability concentrates in high-tenacity polypropylene filament supply, where technical weaving capacity clusters disproportionately in Belgium's Flanders region. Distribution runs through direct manufacturer contracting with large-scale protected cultivation cooperatives, displacing traditional agricultural supply house intermediaries in California's Salinas Valley and Spain's Murcia region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EN 13432 certification timelines and BIS UV stabilization mandates creating structural switching costs that lock in incumbent positioning across EU and Indian jurisdictions.
For Market Incumbents: Harden biodegradability certification portfolios ahead of EU Green Deal enforcement timelines, prioritizing notified body relationships to compress validation cycles. Secure captive polymer compounding capacity or long-term offtake agreements with Shandong and Antwerp resin suppliers to defend margin position against propylene feedstock volatility. Channel control through direct contracting with California and Murcia cooperatives reinforces pricing power over distributor-dependent competitors. For New Entrants and Emerging Players: Build out Southeast Asian distribution partnerships targeting Vietnam and Thailand's protected cultivation expansion, where domestic high-tenacity polypropylene capacity remains underdeveloped. Spunbond-meltblown-spunbond technology hybridization with phase-change materials offers the most penetrable white-space for frost protection applications in temperate berry zones. A certification-first go-to-market strategy, front-loading EN 13432 or emerging Asian compostability scheme investment, accelerates shelf access ahead of established players. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized agri textile divisions lacking backward integration into polymer compounding. Long-term viability centers on substrate manufacturers with demonstrated formulation chemistry capabilities spanning UV stabilization and biodegradation kinetics. Watch for inflection signals in EU notified body backlog clearance rates, which compress revenue recognition timelines for novel certified product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin predictability against naphtha-propylene spread volatility in Shandong manufacturing clusters. |
| EN 13432 Certification Acquisition | Notified body validation unlocks EU Green Deal-compliant shelf access ahead of persistent additive restriction enforcement. |
| Southeast Asian Distribution Partnership | Vietnamese and Thai horticulture import demand outpaces domestic high-tenacity polypropylene capacity buildout. |
| Spunbond-Meltblown-Spunbond Technology Hybridization | Phase-change material integration enables thermal buffering displacement of woven alternatives in temperate frost protection. |
| Direct Cooperative Contracting | Salinas Valley and Murcia buyer consolidation secures lot-traceable documentation for Northern European retail chain certification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with greenhouse operations managers in Netherlands Westland and Spain Almería, technical weaving plant engineers in Belgium Flanders, polymer compounding formulation chemists, and agricultural cooperative procurement directors in California Salinas Valley. Secondary validation drew from customs and trade flow databases, BIS and GB standards documentation, ECHA REACH restriction proposals, and SEC filings of listed technical textile manufacturers. Bottom-up volume modeling across shade netting, mulch film, crop cover, and geotextile product types triangulated against top-down macroeconomic agricultural investment indicators.
Calibration against historical capacity utilization rates in Shandong and Gujarat manufacturing clusters anchored projection elasticity. Segmentation dimensions spanned product type, end-use industry, material substrate, and technology format across the analysis window. CAGRs were derived from slope analysis of fitted trend lines against documented replacement cycles and regulatory compliance-driven procurement redirection. Industry-specific forecast inputs incorporated PLI scheme subsidy disbursement trajectories and EU notified body testing backlog durations.
Stress conditions across propylene feedstock price volatility, EN 13432 certification timeline extensions, and Southeast Asian import tariff regimes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and biodegradability standard convergence. Cross-checking against customs-derived trade volume data and greenhouse operator capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Absorbent Cover Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Technical Textile Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Construction Textile Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
China Geotextiles Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Smart Sports Textile Market