
 Ceramic Textiles Market | 2026-2036
Ceramic Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Textiles Market Intelligence
A fragmentation of the buyer base, driven by emerging applications in specialized electronics and medical devices, is decoupling purchasing power from traditional large-scale industrial consumers. Morgan Advanced Materials Corporation specializes in high-performance thermal management solutions for these niche sectors. 3M Company leverages its material science platform to develop advanced ceramic textile products. Luyang Energy-Saving Materials Co. Ltd. competes on manufacturing scale for high-volume industrial furnace applications.
Ceramic textiles are high-temperature insulation materials typically composed of alumina-silica fibers, engineered to withstand continuous operating temperatures exceeding 1200°C. Their primary function is to provide thermal insulation, fire protection, and structural reinforcement in extreme environments. Woven fabrics command a significant share for use in established industrial insulation wraps and curtains. The aerospace application, however, requires advanced non-woven materials and tapes for critical thermal protection systems on aircraft and spacecraft.
Regulatory frameworks such as the EU's REACH regulation and US EPA guidelines on refractory ceramic fibers directly influence material composition and worker safety protocols. In Asia, compliance with China's GB standards for industrial safety and Japan's JIS standards for material testing is critical for market access. Future material selection will balance thermal performance requirements against evolving health and environmental safety standards.
Market Dynamics
The central dynamic shaping the ceramic textiles market is the divergence between high-volume, cost-sensitive demand for industrial insulation and the expanding need for high-performance, custom materials in specialized aerospace, electronics, and medical applications.
Growth Catalysts
- Advanced Manufacturing Techniques:Innovations in 3D printing technology enable the creation of complex, near-net-shape ceramic textile components, reducing waste and expanding design possibilities for applications like aerospace engine parts.
- Aerospace Sector Expansion:Sustained investment in commercial and defense aviation programs drives demand for lightweight, high-temperature thermal protection systems, including non-woven materials and tapes for heat shields and nacelles.
- German Industrial Concentration:Demand is intensifying within Germany’s automotive and advanced manufacturing ecosystems, where ceramic textiles are integral to furnace linings, welding protection, and exhaust system insulation.
Market Restraints
- Regulatory Scrutiny:The EU's REACH regulation and US EPA guidelines on refractory ceramic fibers (RCFs) impose strict compliance costs and drive research into alternative, less hazardous fiber chemistries.
- Intense Energy Costs:Manufacturing alumina-silica fibers requires melting raw materials at extreme temperatures, making production costs highly sensitive to volatile electricity and natural gas prices in key manufacturing regions.
- Substitution from Composites:In certain moderate-temperature applications, ceramic textiles face competition from advanced polymer composites and metallic foils that offer alternative structural and thermal performance characteristics.
Strategic Opportunities
- Medical and Electronics Niches:The fragmentation of the buyer base opens opportunities in specialized electronics and medical devices, where custom-engineered textiles provide critical thermal management for high-power components and implantable devices.
- Smart Textile Development:Integrating sensor technologies with ceramic fabrics creates opportunities for self-monitoring insulation systems that can report on their structural integrity and thermal performance in real-time.
- Industrial Growth in Southeast Asia:Expanding metal processing, petrochemical, and power generation industries in nations like Vietnam and Indonesia present new markets for industrial-grade insulation wraps, curtains, and furnace linings.
Industry Challenges
- Navigating Global Standards:Manufacturers face significant operational complexity in ensuring products simultaneously comply with China's GB standards, Japan's JIS requirements, and European CE marking protocols for industrial safety.
- Specialized Talent Scarcity:A shortage of material scientists and process engineers with expertise in advanced non-woven materials and 3D ceramic printing hinders rapid innovation and production scale-up for new applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Textiles Market |
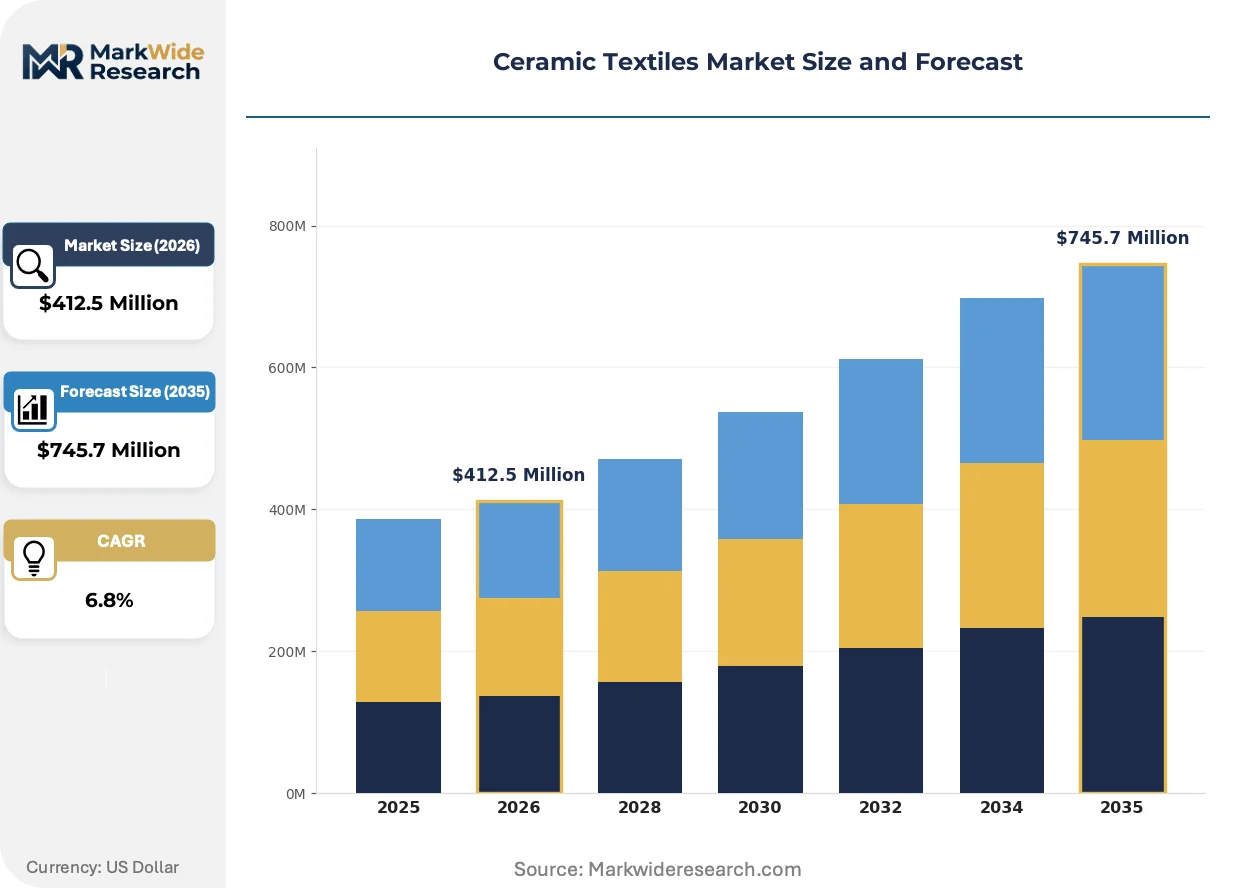
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabrics, Tapes, Woven, Non-woven Application: Aerospace, Automotive, Healthcare, Industrial Technology: 3D Printing, Coating, Thermal Protection, Reinforcement End User: Manufacturers, OEMs, Contractors, Research Institutions |
| Companies Covered | Isolite Insulating Products Co. Ltd., Luyang Energy-Saving Materials Co. Ltd., 3M Company, Unifrax Corporation, Rath Inc., Morgan Advanced Materials Corporation, Kyocera Corporation, Rauschert Steinbach GmbH, Ibiden Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Textiles Market Strategic Shifts & Innovations
Material science advancements are pushing ceramic textiles beyond their traditional role as passive insulation. The market is shifting toward functional materials engineered for specific performance outcomes in extreme environments, from aerospace thermal protection to biomedical implants.
Additive manufacturing of ceramic-based materials allows for the creation of intricate, lightweight structures previously impossible to produce. Aerospace and defense sectors are early adopters, using this for rapid prototyping and production of custom thermal shields and engine components. This technology is consolidating the design-to-production workflow, dramatically shortening lead times for complex, application-specific parts.
Heightened regulatory focus on workplace safety directly influences material development. The EU's REACH regulation, specifically its classification of refractory ceramic fibers, pressures manufacturers to invest in bio-soluble fiber technologies that have lower biopersistence. The industrial furnace and boiler insulation segment is most affected, accelerating the phase-out of traditional RCF-based products in Europe.
Buying behavior is evolving from large-scale commodity purchases toward smaller, more frequent orders for specialized materials. This change disrupts traditional distribution models built for high-volume industrial consumers, creating an opening for agile suppliers who can manage custom specifications. This pattern is most pronounced in North American and European markets, driven by R&D-intensive sectors like medical devices and specialized electronics manufacturing.
Ceramic Textiles Market Segmentation
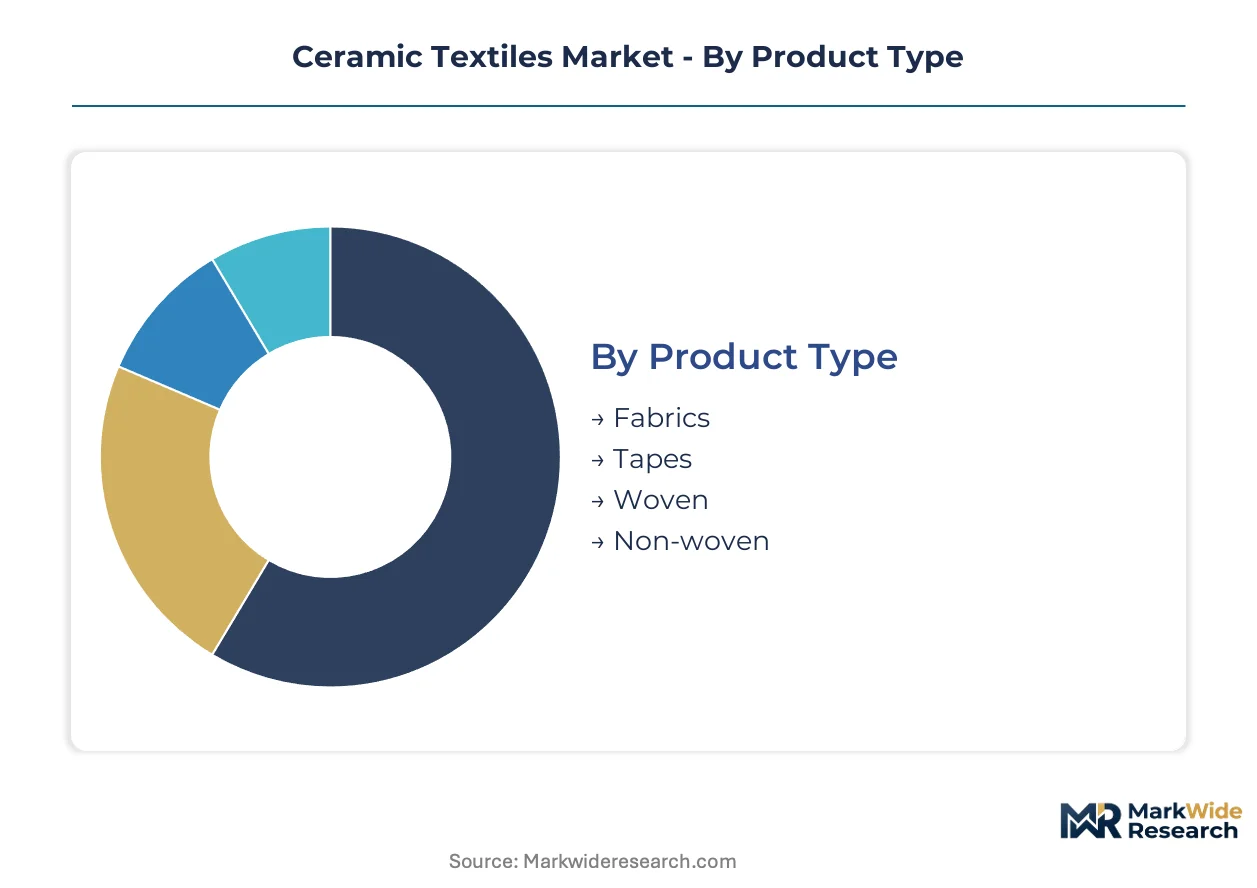
The Ceramic Textiles Market segments reflect diverse material compositions and functional requirements across various industrial and specialized applications. Understanding these distinctions is crucial for manufacturers to align product development with specific end-user demands and regulatory compliance. This segmentation highlights the critical performance attributes valued by different buyer groups.
Product Type:
Buyer decisions for ceramic textile product types hinge on the required form factor and thermal performance characteristics for specific applications.
- Fabrics:These are flexible, woven or non-woven sheets typically used for thermal insulation, fire protection, and heat shields. Demand concentrates in industrial applications like furnace linings and welding curtains, driven by their ease of installation and broad temperature resistance.
- Non-woven:Composed of randomly oriented fibers, non-woven materials offer superior thermal insulation and flexibility for complex shapes. The aerospace sector drives demand for non-woven ceramic textiles in critical thermal protection systems and engine components, requiring high-temperature stability and lightweight properties.
- Tapes:Narrow strips of ceramic textile, often used for wrapping pipes, cables, and exhaust systems requiring localized heat management.
- Woven:Characterized by interlaced fibers, woven ceramic textiles provide good structural integrity and abrasion resistance for industrial gaskets and seals.
Fabrics lead on scale for general industrial insulation; non-woven materials lead on momentum for advanced aerospace and high-performance uses.
Application:
Specific application demands dictate the material specifications and performance requirements for ceramic textiles across diverse industries.
- Aerospace:This segment utilizes ceramic textiles for thermal protection systems, engine components, and heat shields in aircraft and spacecraft. The need for lightweight, high-temperature resistant materials capable of enduring extreme conditions drives innovation in non-woven and 3D printed ceramics.
- Industrial:Ceramic textiles provide critical insulation for furnaces, kilns, boilers, and piping in heavy industries like metal processing and petrochemicals. Cost-effectiveness and large-volume supply are primary considerations for this established application area.
- Automotive:Ceramic textiles find use in exhaust system insulation, catalytic converter supports, and battery thermal management for electric vehicles.
- Healthcare:Specialized ceramic fibers are integrated into medical devices for thermal therapy, sterilization equipment, and high-temperature filtration systems.
Aerospace applications consistently push material performance boundaries, while industrial uses absorb the largest volumes of standard ceramic textile products.
Technology:
Technological advancements are redefining product capabilities and expanding the functional scope of ceramic textiles in demanding environments.
- 3D Printing:Additive manufacturing enables the creation of complex, near-net-shape ceramic textile components with intricate geometries. This technology reduces waste and shortens lead times, especially for custom thermal shields in aerospace and defense sectors.
- Thermal Protection:This core technology focuses on engineering ceramic textiles to withstand extreme temperatures, providing insulation and fire resistance. Innovations in fiber chemistry and weave structures enhance performance for critical applications like engine nacelles and industrial furnace linings.
- Coating:Surface coatings enhance ceramic textile properties, improving abrasion resistance, chemical inertness, or hydrophobicity for specific industrial uses.
- Reinforcement:Ceramic textiles serve as high-temperature reinforcement for composites, enhancing mechanical strength and structural integrity in extreme thermal conditions.
3D Printing technology represents a significant leap in design flexibility, while thermal protection remains the foundational capability for market expansion.
End User:
End-user profiles significantly influence purchasing patterns and the demand for customized ceramic textile solutions across the value chain.
- Manufacturers:These entities directly produce ceramic textile products, often integrating raw fiber production with fabrication processes. They serve as primary suppliers to other end-users, focusing on scale and material science advancements.
- OEMs:Original Equipment Manufacturers integrate ceramic textiles as components into their larger systems, such as aircraft engines, industrial furnaces, or automotive exhaust systems. OEMs demand specific performance characteristics and consistent supply for their complex product assemblies.
- Contractors:Installation and maintenance contractors utilize ceramic textiles for on-site insulation projects, repairs, and upgrades in industrial and commercial settings.
- Research Institutions:Academic and private research institutions drive material innovation, testing new fiber chemistries and exploring novel applications for ceramic textiles.
Manufacturers form the supply base, while OEMs integrate these materials into high-value final products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing ecosystem contrasts with the United States' aerospace sector in driving ceramic textile demand. European markets prioritize bio-soluble fiber technologies due to stringent regulations. Asian nations focus on industrial safety compliance for market access.
Germany
Germany's automotive and advanced manufacturing ecosystems intensify demand for ceramic textiles in furnace linings and exhaust systems. The EU's REACH regulation pressures manufacturers to adopt bio-soluble fiber technologies. Bavaria's strong automotive industry, including major OEMs, integrates these materials for thermal management solutions.
United States
United States' demand stems from aerospace thermal protection systems and specialized electronics. US EPA guidelines on refractory ceramic fibers influence material composition and worker safety protocols. California's numerous aerospace and defense contractors drive innovation in non-woven and 3D printed ceramic components.
China
China's industrial furnace applications and infrastructure development absorb significant volumes of ceramic textiles. Compliance with China's GB standards for industrial safety is critical for market access. The Yangtze River Delta, a hub for heavy industry, consistently requires large-scale insulation wraps and furnace linings.
Japan
Japanese industries emphasize material testing for high-performance applications and industrial furnace linings. Japan's JIS standards for material testing ensure product quality and reliability. The Kansai region, with its chemical and machinery manufacturing, utilizes advanced ceramic textiles for high-temperature processes.
Vietnam
Vietnam's expanding metal processing and petrochemical industries create new markets for industrial-grade insulation. Government initiatives supporting industrial growth encourage the adoption of modern thermal management solutions. Ho Chi Minh City's burgeoning industrial parks increasingly require ceramic textiles for insulation and fire protection.
Ceramic Textiles Market Key Industry Players
European producers anchor one tier, focusing on high-performance materials for niche applications, while Asian manufacturers hold positions in the high-volume industrial segment. The market structure exhibits a tiered approach, with specialists targeting aerospace and medical devices. Key strategic archetypes include material science innovators and large-scale industrial suppliers. Companies primarily engage in portfolio diversification and capacity expansion to maintain market share.
Within the material science innovators, 3M Company leverages its extensive platform to develop advanced ceramic textile products. Morgan Advanced Materials Corporation occupies a strong position in high-performance thermal management solutions for niche sectors. Luyang Energy-Saving Materials Co. Ltd. exemplifies the manufacturing scale approach, competing effectively for high-volume industrial furnace applications.
| Leading Market Players |
|---|
| Isolite Insulating Products Co. Ltd. |
| Luyang Energy-Saving Materials Co. Ltd. |
| 3M Company |
| Unifrax Corporation |
| Rath Inc. |
| Morgan Advanced Materials Corporation |
| Kyocera Corporation |
| Rauschert Steinbach GmbH |
| Ibiden Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Volatile energy costs for melting raw materials directly impact the production costs of alumina-silica fibers, influencing downstream pricing tiers for both industrial insulation and specialized aerospace materials.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume industrial ceramic textiles. The dominant pricing model for industrial applications remains contract-based long-term offtake, while specialized aerospace and medical uses adopt a value-based approach. Price differentiation stems from performance characteristics like continuous operating temperature and customization level for complex geometries. Pricing pressure stems from intense competition among large-scale industrial suppliers in Asia. The industrial segment is most price-sensitive, whereas aerospace and medical device manufacturers prioritize performance over cost.
Supply Chain Analysis
Domestic-content mandates in the United States for defense applications reshape sourcing for advanced ceramic textile components. Geographic supply concentration for ceramic textile manufacturing centers in China, Japan, and Germany. The market draws from raw material dependencies on high-purity alumina and silica. Commodity price volatility for energy, critical for fiber production, represents a significant structural risk. Downstream distribution runs through direct sales to large Original Equipment Manufacturers (OEMs) and specialized distributors serving niche sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's REACH regulation driving demand for bio-soluble fiber technologies across European markets.
For Market Incumbents: Anchor investment in bio-soluble fiber research and development to mitigate regulatory scrutiny from bodies like the US EPA. Expand advanced manufacturing capabilities, particularly 3D printing ceramic textiles, to address the growing demand for complex geometries in aerospace. Leverage existing channel control to offer certified, high-performance materials compliant with Japan's JIS standards. This strategy counters the threat of alternative, less hazardous fiber chemistries.
For New Entrants and Emerging Players: Specialized electronics manufacturers represent an underserved buyer archetype seeking custom thermal management solutions. Target the medical device and specialized electronics niches with highly engineered, application-specific ceramic textiles. The most penetrable segment lies in providing bespoke thermal protection for high-power components or implantable devices. A strong go-to-market angle involves collaborating directly with R&D-intensive OEMs for co-development and rapid prototyping.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance demands significant R&D investment and specialized manufacturing expertise. The long-term viability favors companies focused on high-performance segments like aerospace thermal protection and medical devices. Archetypal acquisition targets include agile specialists in 3D printing ceramic textile components or those with patented bio-soluble fiber technologies. Increased M&A activity involving advanced material startups serves as a signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand for industrial-grade insulation in Southeast Asia's expanding economies. |
| R&D in Bio-soluble Fibers | Ensures compliance with stringent regulatory frameworks like EU REACH and enhances worker safety. |
| 3D Printing Technology Investment | Enables the creation of complex, near-net-shape components for aerospace and defense applications. |
| Strategic Partnerships | Facilitates co-development of custom solutions for medical device and specialized electronics OEMs. |
| Geographic Manufacturing Footprint | Positions manufacturers closer to key industrial growth markets in nations like Vietnam. |
Research Approach
Direct dialogue with material scientists, aerospace engineers, industrial plant managers, and medical device developers informed the qualitative grounding of this study. This primary research was validated against secondary sources, including EU REACH reports, US EPA guidelines, China's GB standards, and Japan's JIS standards, ensuring robust data triangulation. The approach combined bottom-up market sizing with top-down validation.
The analytical framework produced comprehensive market sizing and growth projections across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and fiber chemistry. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs included global aerospace investment trends and industrial output growth rates in major manufacturing regions.
Underlying measurement precision varies by segment; established industrial applications carry tighter precision than emerging medical and electronics niches. Forecasts reflect assumptions regarding technological adoption and evolving regulatory landscapes. Volatile energy prices, unforeseen shifts in material science, and global economic slowdowns represent specific risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
E-Textile Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
Active Smart Textiles Market