
 High Temperature Fabric Market | 2026-2036
High Temperature Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Fabric Market Insights
Industrial buyers are bifurcating procurement between aerospace primes seeking certified aramid solutions and automotive suppliers prioritizing cost-optimized fiberglass alternatives. DuPont de Nemours, Inc. leverages its Kevlar fiber heritage to dominate aerospace qualification programs. Teijin Limited anchors its position through Twaron production scale and Asian manufacturing footprint. Saint-Gobain competes via integrated glass fiber-to-fabric operations serving European energy infrastructure.
High temperature fabrics are engineered textile structures, typically woven from glass, aramid, or ceramic fibers and treated with silicone or PTFE coatings, designed to maintain structural integrity above 300°C while providing thermal insulation, flame resistance, or chemical protection in extreme environments. Fiberglass fabrics occupy the largest volume position due to mature supply chains and broad industrial applicability, while PTFE-coated aramid constructions command premium positioning in aerospace and semiconductor cleanroom applications where outgassing limits apply. Coating technology generates the highest value-add segment, as fluoropolymer and silicone treatments transform base fabrics into differentiated performance materials with extended service life.
The EPA enforces emissions and workplace exposure limits that shape material selection in US oil & gas and chemical processing facilities. REACH and the EU F-Gas Regulation restrict perfluorinated compound usage, forcing European fabric formulators to reformulate coatings and validate substitutes. China's GB standards and MIIT industrial policy directives set domestic content thresholds for infrastructure and energy applications. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to segment supply chains and complicate cross-border product certification strategies.
Market Dynamics
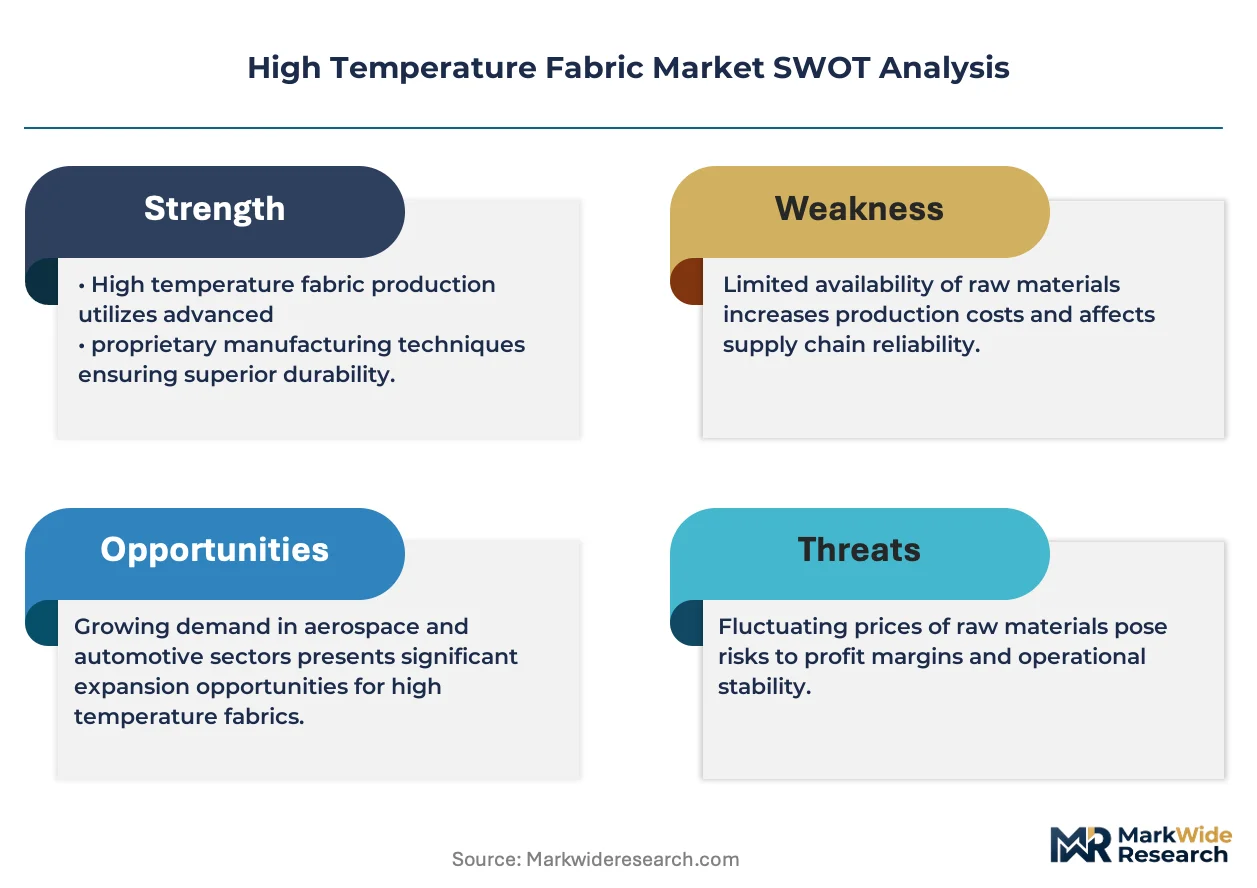
EU F-Gas Regulation and REACH compliance standards are forcing coating reformulation across European supply chains, compressing margins for PTFE-dependent fabric formulators while creating qualification windows for silicone and bio-based alternatives.
Growth Catalysts
- Aerospace thermal protection demand:Engine compartment applications require certified aramid solutions that withstand sustained exposure above 400°C. OEMs are expanding procurement programs for next-generation propulsion systems.
- REACH substitution mandates:European fabric formulators must validate fluoropolymer alternatives, accelerating R&D investment in silicone and hybrid coating chemistries.
- German automotive thermal management:Industrial belt investments in battery enclosure insulation and exhaust system shielding drive volume demand for cost-optimized fiberglass constructions.
Market Restraints
- Raw material concentration:High-purity aramid fiber supply concentrates among three global polymer producers, exposing buyers to allocation risk during aerospace demand surges.
- PTFE coating cost volatility:Fluoropolymer resin prices fluctuate with fluorspar mining output and Chinese environmental enforcement cycles.
- Technical service temperature ceilings:Fiberglass fabrics experience catastrophic strength degradation above 600°C, limiting substitution potential in hypersonic and space re-entry applications.
Strategic Opportunities
- Semiconductor cleanroom expansion:Outgassing-compliant PTFE-aramid laminates command premium positioning in wafer fabrication facility construction across East Asian manufacturing hubs.
- US energy infrastructure retrofit:IRA incentives for industrial decarbonization drive demand for high-temperature insulation in refinery and petrochemical furnace rebuilds.
- Silicone-aramid hybrid development:Coating technology convergence enables single-fabric solutions spanning 300°C to 800°C service ranges, reducing customer SKU complexity.
Industry Challenges
- Multi-jurisdiction certification timelines:FAA flame resistance approvals, EASA smoke toxicity standards, and GB fire ratings require parallel testing programs that extend product launch cycles by 18-24 months.
- Coating application skill scarcity:Thin-film fluoropolymer deposition expertise concentrates among aging technician populations in German and Japanese specialty textile regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Fabric Market |
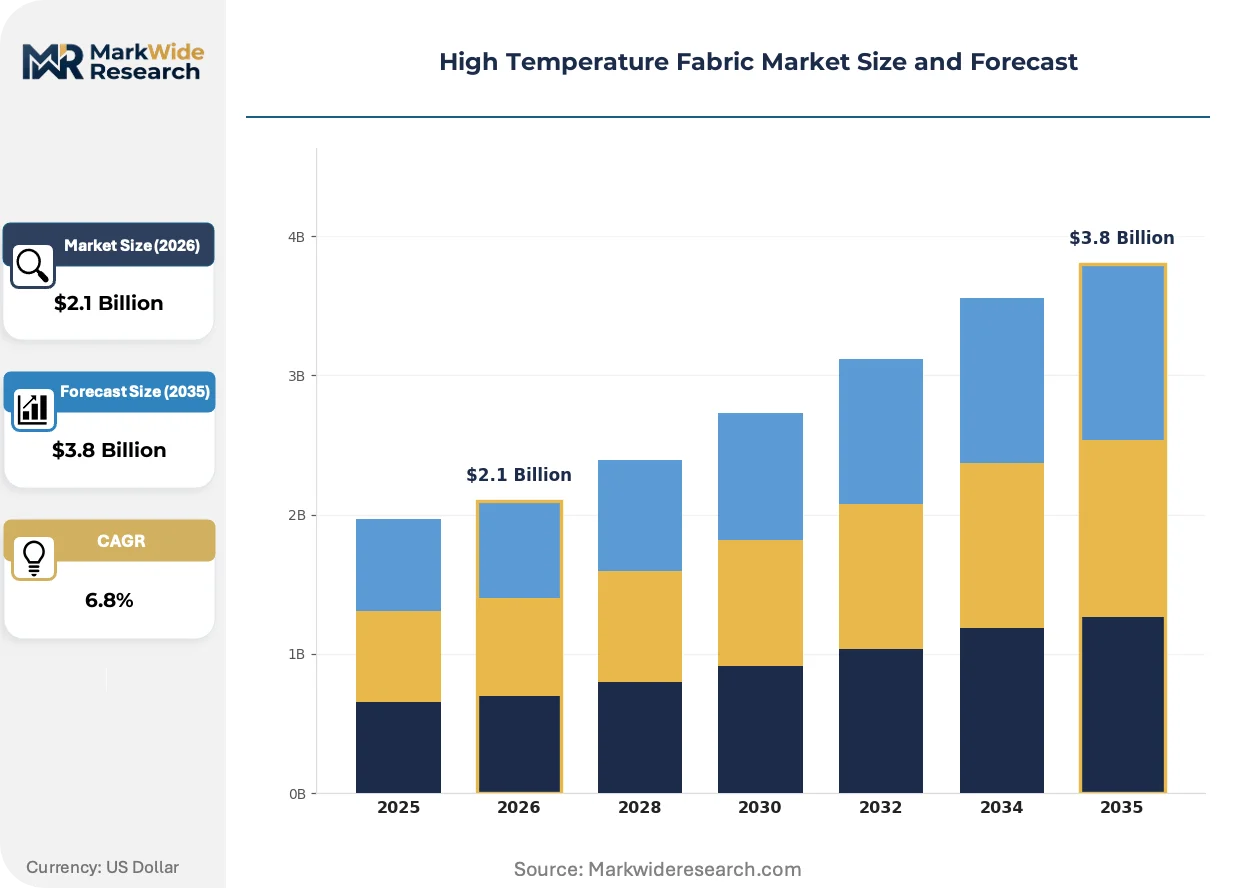
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Aramid, Silicone, PTFE Application: Insulation, Fireproofing, Protective Clothing, Gaskets End User: Aerospace, Automotive, Manufacturing, Oil & Gas Technology: Weaving, Coating, Laminating, Knitting |
| Companies Covered | DuPont de Nemours, Inc., 3M, Teijin Limited, Milliken & Company, Honeywell, Saint-Gobain, W. L. Gore & Associates, PPG Industries, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Fabric Market Trends and Innovations
Coating chemistry diversification and digital manufacturing integration are reshaping competitive positioning in high-temperature fabric production. Formulators are racing to decouple performance from perfluorinated compounds.
Silicone-modified ceramic coating technology is fragmenting the traditional PTFE-dominated premium segment. Aerospace aftermarket maintenance providers are adopting these hybrids for engine blanket refurbishment at 40% lower coating weight. The shift is compressing qualification timelines for incumbent fluoropolymer suppliers while opening supply base expansion opportunities for regional coaters.
EPA emissions enforcement under the Clean Air Act is tightening volatile organic compound limits on coating operations. US oil and gas facility operators now specify low-VOC silicone treatments for stack insulation and flare shielding. Fabric converters with captive coating capacity in Texas and Louisiana are investing in thermal oxidizer upgrades to maintain procurement eligibility.
Buyer concentration among tier-one aerospace primes is compressing supplier negotiation cycles. Long-term agreements with minimum volume guarantees are displacing spot purchasing for aramid-based protective materials. This shift is most visible in Germany's Ruhr industrial cluster, where automotive suppliers now mirror aerospace procurement discipline for thermal management component sourcing.
High Temperature Fabric Market Segmentation
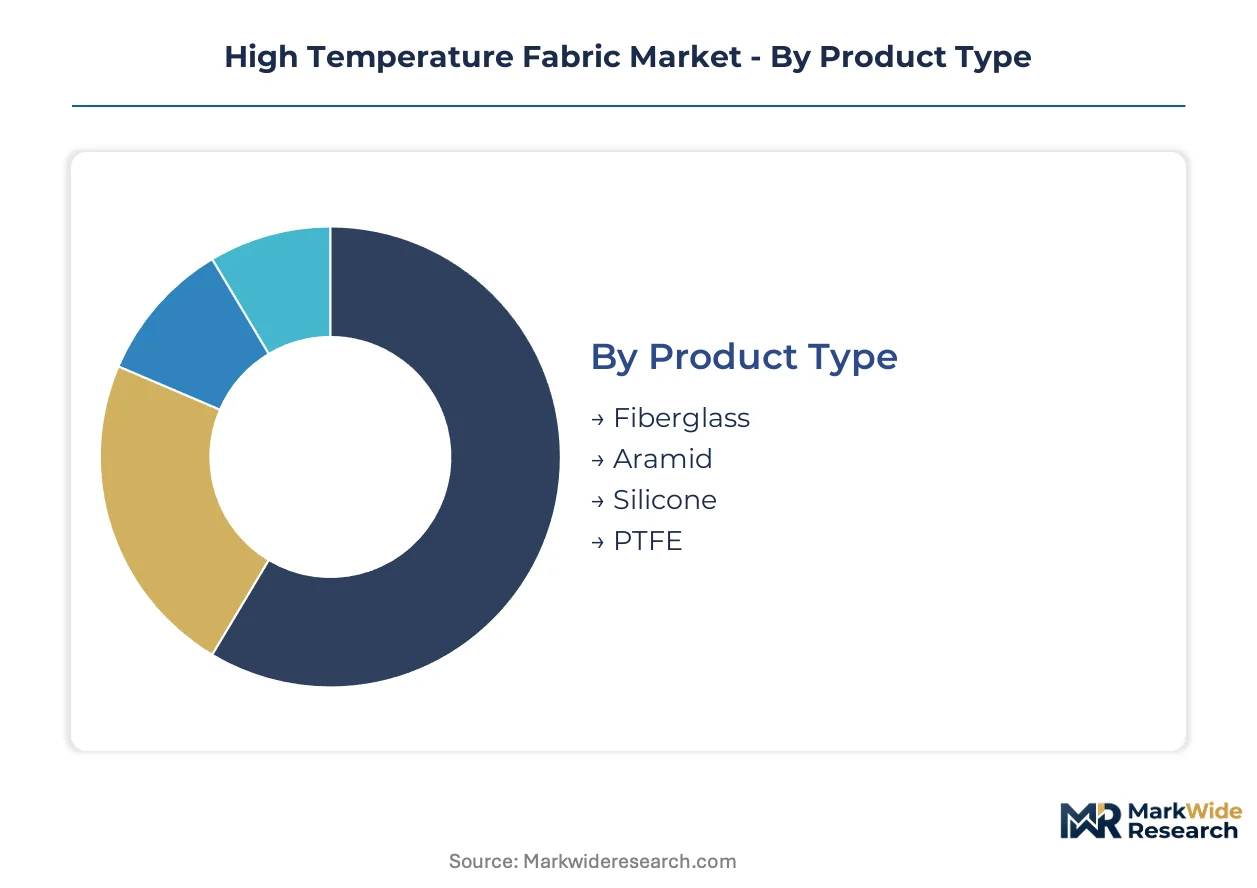
High temperature fabric procurement decisions hinge on certification requirements that vary sharply by end-use environment. Aerospace primes demand flame-resistant aramid constructions with FAA and EASA traceability, while automotive buyers prioritize cost-optimized fiberglass for thermal management. Understanding these segment boundaries enables suppliers to align R&D investment with qualification timelines.
Product Type:
REACH and EU F-Gas Regulation compliance costs diverge sharply across base fiber chemistries, with fluoropolymer-coated constructions facing the steepest reformulation burdens.
- Fiberglass:Woven E-glass and S-glass constructions dominate volume throughput due to mature supply chains and broad industrial applicability. German automotive thermal management investments in the Ruhr industrial belt accelerate procurement of cost-optimized fiberglass for battery enclosure insulation and exhaust shielding.
- Aramid:Para-aramid and meta-aramid fiber fabrics maintain structural integrity above 400°C with exceptional strength-to-weight ratios. Aerospace OEMs in the United States and France expand qualification programs for engine compartment applications requiring FAA and EASA flame resistance certifications.
- Silicone:Elastomer-coated textiles serve mid-temperature ranges with superior flexibility and weathering resistance.
- PTFE:Fluoropolymer-impregnated constructions face coating reformulation pressure under perfluorinated compound restrictions.
Fiberglass handles the majority of throughput; silicone is the fastest mover on share as formulators pivot from PTFE-dependent chemistries.
Application:
Customer procurement discipline varies by hazard severity, with aerospace and oil & gas facilities mandating certified solutions while manufacturing buyers accept broader specification ranges.
- Insulation:Multi-layer fabric systems containing ceramic fiber or microporous silica cores deliver thermal protection in furnace linings and turbine enclosures. US energy infrastructure retrofit programs under IRA industrial decarbonization incentives drive demand for high-temperature insulation in Texas and Louisiana refinery rebuilds.
- Fireproofing:Passive fire protection textiles prevent flame propagation in structural compartments and cable trays. European construction codes under the EU Green Deal tighten fire safety standards for commercial and industrial buildings, accelerating specification of certified glass and aramid barrier fabrics.
- Protective Clothing:Garment-grade fabrics balance thermal protection with wearer mobility for foundry and welding operations.
- Gaskets:Compressed fiber sheets and rope seals accommodate thermal cycling in flanged joints and valve bonnets.
Insulation commands the largest committed volume; fireproofing is climbing the fastest as building codes tighten across developed economies.
End User:
Industry-specific regulatory frameworks create distinct qualification barriers that segment supplier access and sustain margin differentiation.
- Aerospace:Engine manufacturers and airframe assemblers require materials traceable to FAA flame resistance and EASA smoke toxicity standards. Long-term agreements with minimum volume guarantees are displacing spot purchasing for aramid-based protective materials as buyer concentration among tier-one primes intensifies.
- Automotive:OEMs and tier suppliers prioritize thermal management for electrified powertrains and high-performance exhaust systems. Battery enclosure insulation demand concentrates in Germany's industrial belt where automotive suppliers now mirror aerospace procurement discipline.
- Manufacturing:Foundries, steel mills, and glass plants specify fabrics for equipment protection and personnel safety.
- Oil & Gas:Refinery and petrochemical operators face EPA emissions enforcement under the Clean Air Act tightening volatile organic compound limits on coating operations.
Aerospace generates the highest value per kilogram; automotive is expanding most quickly as thermal management complexity rises with electrification.
Technology:
Process capability concentration among aging technician populations in German and Japanese specialty textile regions constrains supply base expansion for premium coating applications.
- Weaving:Loom-based fabrication produces the foundational textile structures from glass, aramid, and ceramic yarns. Volume production concentrates in established industrial clusters with multi-decade equipment amortization and skilled workforce retention.
- Coating:Thin-film fluoropolymer and silicone deposition transforms base fabrics into differentiated performance materials with extended service life. Coating application skill scarcity compresses capacity expansion for PTFE-aramid laminates serving semiconductor cleanroom construction across East Asian manufacturing hubs.
- Laminating:Multi-ply bonding combines dissimilar materials to achieve property synergies in single constructions.
- Knitting:Interlooping yarn structures deliver stretch and conformability for complex geometries and personnel garments.
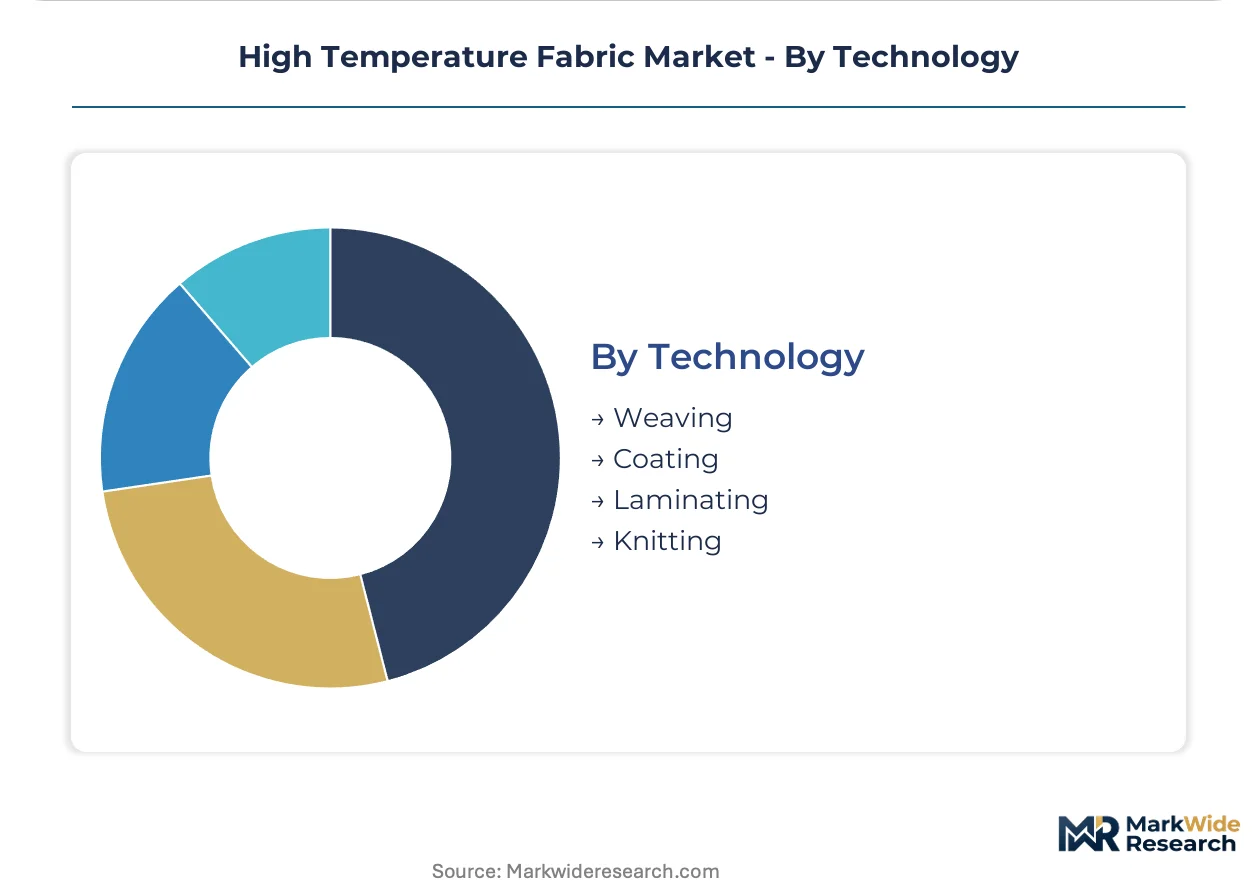
Weaving underpins baseline supply; coating captures the steepest value-add trajectory as functional chemistry differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace primes and automotive OEMs concentrate procurement authority in three distinct industrial corridors, each imposing divergent certification requirements on fabric formulators. Regional regulatory fragmentation now extends product qualification timelines and segments supplier access by jurisdiction.
United States
FAA flame resistance certifications and EPA Clean Air Act enforcement shape material selection for aerospace and energy applications. IRA industrial decarbonization incentives accelerate refinery and petrochemical furnace rebuilds across Texas and Louisiana. Houston fabric converters invest in thermal oxidizer upgrades to maintain procurement eligibility under tightening VOC limits.
Germany
REACH substitution mandates and EU F-Gas Regulation compliance force coating reformulation across the Ruhr industrial belt. Automotive thermal management investments drive volume demand for battery enclosure insulation and exhaust system shielding. Stuttgart and Munich suppliers now mirror aerospace procurement discipline with long-term agreements displacing spot purchasing.
China
MIIT industrial policy directives and GB standards set domestic content thresholds for infrastructure and energy applications. Semiconductor cleanroom construction across East Asian manufacturing hubs generates premium demand for outgassing-compliant laminates. Yangtze River Delta fabricators expand PTFE-aramid capacity to serve wafer fabrication facility builds.
France
EASA smoke toxicity standards and EU Green Deal fire safety codes tighten specification requirements for commercial and industrial buildings. Aerospace engine manufacturers in Toulouse and Paris expand qualification programs for next-generation propulsion systems. Regional coaters develop silicone-modified ceramic hybrids to capture engine blanket refurbishment contracts.
Japan
METI technology roadmaps and JIS standards guide high-temperature material development for automotive and electronics applications. Thin-film fluoropolymer deposition expertise concentrates among aging technician populations in specialty textile regions. Osaka and Nagoya formulators pursue hybrid coating chemistries to reduce dependence on perfluorinated compounds.
High Temperature Fabric Market Competitive Landscape
Player mix skews toward integrated fiber-to-fabric operators and specialized coating houses competing on qualification speed. Three polymer producers control high-purity aramid fiber supply, exposing downstream buyers to allocation risk during aerospace demand surges. Strategic archetypes include captive fiber producers with aerospace certification heritage, regional converters with coating application expertise, and diversified industrial conglomerates with glass fiber integration. Dominant competitive moves center on M&A to secure coating technology assets and capacity expansion in low-VOC treatment lines.
Within the integrated fiber-to-fabric tier, DuPont de Nemours, Inc. and Teijin Limited exemplify archetypes anchored by para-aramid heritage and Asian manufacturing scale respectively. Saint-Gobain occupies a position representing glass fiber vertical integration serving European energy infrastructure. These three anchors demonstrate how material science lineage and geographic production footprint determine qualification access across divergent regulatory jurisdictions.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| 3M |
| Teijin Limited |
| Milliken & Company |
| Honeywell |
| Saint-Gobain |
| W. L. Gore & Associates |
| PPG Industries |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with minimum volume guarantees lock in both aramid fiber supply access and forward price visibility for aerospace primes confronting raw material concentration among three global polymer producers. These contract structures insulate qualified suppliers from fluorspar-driven PTFE resin volatility while exposing uncontracted buyers to allocation risk during engine program ramp-ups.
Pricing Analysis
Cost-plus contracts with fluorspar indexation dominate PTFE-coated fabric procurement, passing through resin volatility to end-users while silicone alternatives trade on fixed-price terms. Three-tier pricing structure across aerospace-certified aramid, industrial-grade fiberglass, and emerging bio-based coatings reflects certification burden and coating complexity. Pricing pressure stems from REACH-mandated reformulation costs compressing margins for European PTFE formulators. Automotive thermal management buyers exhibit highest price sensitivity, prioritizing cost-optimized fiberglass over certified solutions.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for Japanese and Chinese specialty textile producers serving European coating houses. High-purity aramid fiber supply concentrates in the United States, Japan, and the Netherlands, while fluorspar mining for PTFE feedstock anchors in China and Mexico. Raw material dependencies span para-aramid polymer, fluoropolymer resin, and high-grade silica sand. Single-source vulnerability in thin-film fluoropolymer deposition expertise concentrates supply risk among aging technician populations in German and Japanese industrial clusters. Distribution runs through regional converters with captive coating capacity supplying qualified fabric to aerospace primes and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film coating application expertise has become the binding constraint on capacity expansion, with technician populations aging out faster than training pipelines replenish qualified labor for PTFE-aramid laminate production.
For Market Incumbents: Secure backward integration into silicone-modified ceramic coating technology to reduce fluorspar dependency as EU F-Gas Regulation tightens. Add low-VOC treatment capacity in Texas and Louisiana to capture IRA-driven refinery retrofit demand. Defend qualification heritage through accelerated FAA-EASA parallel certification programs that extend competitor launch timelines. For New Entrants and Emerging Players: Aftermarket engine blanket refurbishment services present an underserved layer where incumbents prioritize OEM qualification over maintenance revenue. Target regional aerospace MRO facilities in France and Germany with silicone-aramid hybrid solutions priced below OEM PTFE laminates. Build market presence through technical service partnerships with aging coating houses seeking succession planning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap coating specialists with captive technician training programs and existing aerospace customer relationships. Long-term viability hinges on regulatory arbitrage capability across REACH, EPA, and GB compliance frameworks. Watch for inflection when silicone-aramid hybrids achieve FAA flame resistance certification, signaling coating chemistry convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Coating Technology | Reduces fluorspar exposure under tightening EU F-Gas Regulation restrictions. |
| Low-VOC Treatment Line Expansion | Maintains procurement eligibility under EPA Clean Air Act enforcement in Texas and Louisiana. |
| Parallel FAA-EASA Certification Investment | Accelerates qualification timelines for engine compartment aramid solutions. |
| Technician Training Pipeline Development | Addresses coating application skill scarcity constraining PTFE-aramid capacity expansion. |
| Aftermarket MRO Service Partnership | Captures engine blanket refurbishment demand at 40% lower coating weight than OEM laminates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs filings, aerospace procurement databases, and specialty textile trade association reports. Primary interviews engaged coating application technicians, aerospace material qualification engineers, automotive thermal management procurement leads, and refinery maintenance directors across Germany, the United States, Japan, and China. Secondary validation drew from EPA enforcement records, ECHA substance restriction updates, FAA certification bulletins, and MIIT industrial policy directives. Bottom-up demand modeling from end-use application data triangulated against top-down supply-side capacity assessments.
Segmentation dimensions modeled span base fiber chemistry, coating technology, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derive from volume-weighted growth rates applied to each segment with cross-referencing against historical aerospace program procurement cycles and automotive electrification thermal management content trajectories. Industry-specific forecast inputs include fluorspar mining output projections and REACH substitution mandate implementation timelines.
Underlying assumptions cover sustained aerospace engine program demand, REACH compliance cost pass-through feasibility, and technician training pipeline replenishment rates, with deviation risk concentrated in regulatory acceleration or fluorspar supply disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
US Geotextile Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Technical Textile Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Global PTFE Fabric Market