
 UV Protected Tarpaulin Sheets Market | 2026-2036
UV Protected Tarpaulin Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
UV Protected Tarpaulin Sheets Market Analytics
Heavy-duty specification tiers is rotating toward premium-grade laminated constructions with enhanced tear-strength ratings. Supreme Industries Ltd. anchors Indian demand through backward integration into polymer compounding operations. Heytex specializes in precision-coated technical textiles for European transport and agricultural fleets. SRF Limited extends its fluoropolymer film expertise into multilayer tarpaulin substrates for industrial clients.
UV protected tarpaulin sheets are woven or coated flexible fabrics incorporating ultraviolet stabilizers—typically hindered amine light stabilizers or carbon black masterbatches—engineered to resist photodegradation during prolonged outdoor exposure, primarily serving weatherproofing, cargo coverage, and temporary shelter functions. Polyethylene material grades dominate volume due to cost efficiency in construction and agriculture, while PVC formulations command margin pools in fire-retardant transportation and military specifications. Heavy duty product types carry the highest replacement-cycle value, whereas lightweight segments compete on turnover velocity in outdoor events and seasonal agricultural use.
REACH restrictions on phthalate plasticizers and the EU Green Deal's embodied carbon tracking are reshaping PVC formulation strategies across European supply chains. EPA air-quality standards for coating operations affect US-based lamination facilities and import sourcing patterns. India's BIS certification mandates for tensile strength and UV resistance are creating compliance barriers for unqualified regional suppliers. Stakeholders must evaluate raw-material pass-through exposure and certification lead times before committing to capacity expansion or cross-border supply agreements.
Market Dynamics
REACH compliance deadlines and EPA coating-emission standards are forcing lamination facilities to reformulate UV-stabilizer chemistries and relocate production, compressing supplier margins while creating first-mover advantages for certified compounders.
Growth Catalysts
- India's infrastructure buildout:Central government highway and logistics corridor investments are accelerating procurement of monsoon-grade UV-stabilized covers for material stockpiles and vehicle fleets.
- Hindered amine light stabilizer advances:Next-generation HALS masterbatches are extending service life in polyethylene grades, displacing carbon black in agricultural applications where translucency matters.
- Emergency shelter standardization:UNHCR and Red Cross procurement frameworks now mandate UV resistance ratings for temporary housing textiles, institutionalizing demand for certified heavy-duty specifications.
Market Restraints
- Phthalate plasticizer restrictions:ECHA's expanding REACH Annex XVII listings are forcing PVC compounders to validate bio-based alternatives, extending reformulation cycles and raising qualification costs.
- Polyethylene resin concentration:Gulf Coast petrochemical complexes supply over half of global LLDPE feedstock, exposing converters to hurricane-related supply interruptions and price volatility.
- Mechanical recycling incompatibility:Multi-layer laminated constructions with incompatible polymer combinations resist conventional reprocessing, limiting circular-economy positioning and threatening future extended-producer-responsibility fees.
Strategic Opportunities
- Indonesian archipelago logistics:Island-to-island cargo networks lack covered storage infrastructure, creating greenfield demand for corrosion-resistant maritime-grade tarpaulins with salt-spray certifications.
- Agrivoltaic dual-use covers:UV-stabilized reflective sheets that simultaneously protect crops and boost photovoltaic output are attracting pilot deployments from European energy cooperatives.
- BIS certification arbitrage:India's mandatory tensile-strength and UV-resistance testing is disqualifying regional informal producers, opening market share for organized compounders with in-house testing facilities.
Industry Challenges
- Coating technician scarcity:Precision lamination operations require skilled operators for tension control and adhesive metering, yet vocational pipelines in manufacturing regions remain underdeveloped.
- Multi-certification stacking:Simultaneous pursuit of REACH, EPA, and BIS approvals demands parallel documentation streams, stretching quality-assurance teams and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Protected Tarpaulin Sheets Market |
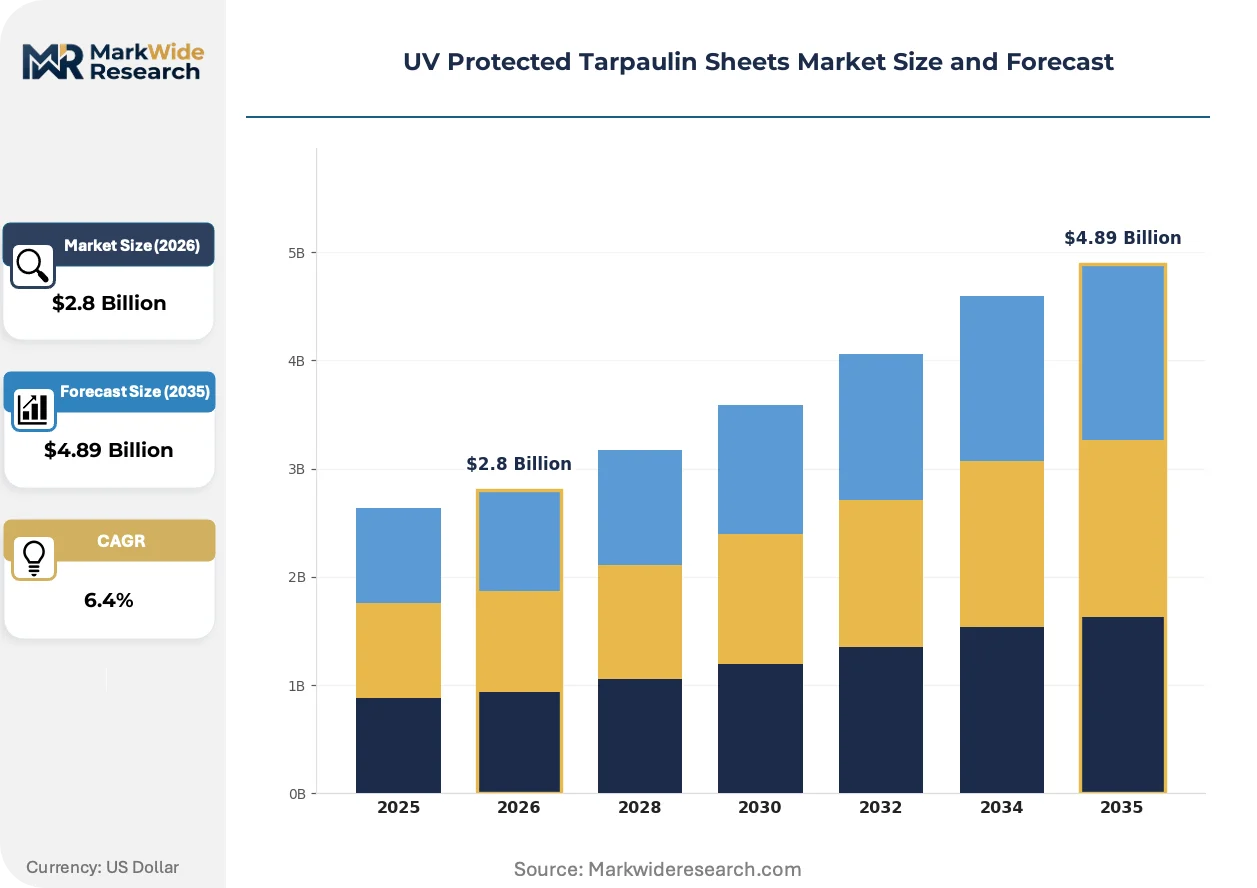
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Duty, Lightweight, Waterproof, Fire Retardant Material: Polyethylene, PVC, Canvas, Polyester Application: Construction, Agriculture, Transportation, Outdoor Events Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Supreme Industries Ltd., Tarp Supply Inc., Canadian Tarpaulin Manufacturers LTD., Heytex, SRF Limited, Seaman Corporation, Shur-Co LLC, Tuohai Plastic Co., Ltd., Sioen Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Protected Tarpaulin Sheets Market Evolving Landscape
Material science breakthroughs and regulatory tracking requirements are converging to reshape how UV protection is engineered, verified, and monetized across construction, agriculture, and transport applications.
Multilayer coextrusion with nano-dispersed UV absorbers is decomposing the traditional tradeoff between optical clarity and photostability. Agricultural greenhouse operators in the Netherlands and Spain are adopting these translucent high-barrier films to extend growing seasons. The technology is compressing replacement-cycle revenues for commodity carbon-black suppliers while opening premium positioning for optical-grade stabilizer compounders.
EU Green Deal embodied-carbon tracking mandates are forcing PVC converters to document polymer origin and lamination energy intensity. Downstream construction procurement teams in Germany and France now require Environmental Product Declarations for temporary enclosure textiles. Heavy-duty specification tiers face margin compression as low-carbon-certified imports from Nordic hydro-powered facilities capture public-sector tenders.
Rental and lease-to-own models are displacing outright purchase in European construction and event-management sectors. Equipment-hire platforms in the UK and Benelux markets bundle UV-protected covers with scaffolding and climate-control systems, capturing recurring revenue streams. This shift concentrates buyer power among national hire-fleet operators and demands standardized sizing and attachment hardware from fabricators.
UV Protected Tarpaulin Sheets Market Segmentation
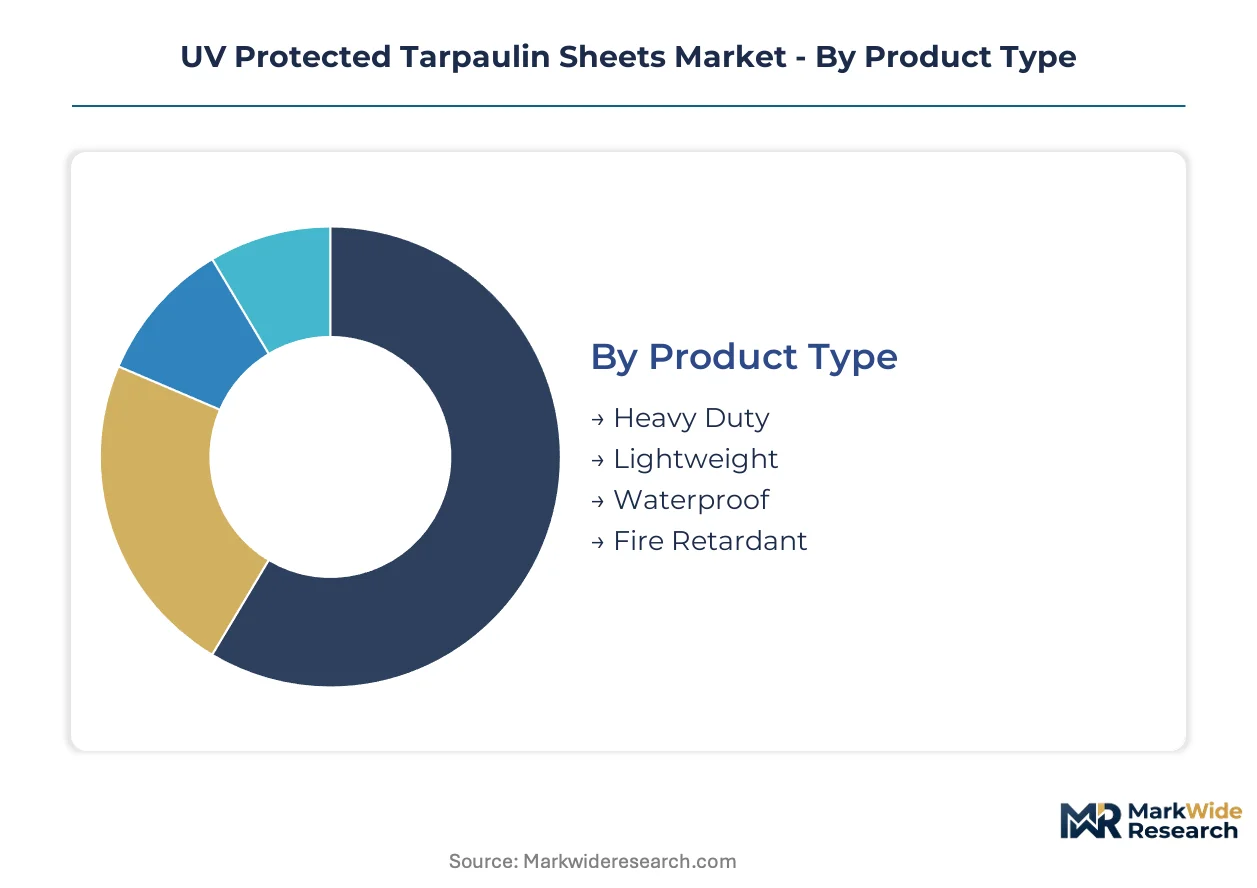
Channel configuration in UV protected tarpaulin sheets varies sharply by specification grade. Heavy-duty laminated products flow through industrial distributors and direct mill relationships, while lightweight grades reach end-users via retail hardware networks and seasonal event suppliers.
Product Type:
Channel-mix patterns separate replacement-cycle revenue from turnover velocity across construction, agriculture, and emergency response procurement channels.
- Heavy Duty:Multi-layer laminated constructions with reinforced hems and grommet spacing engineered for 5+ year service intervals. Demand concentrates in Indian infrastructure stockpiling and German construction site enclosure where BIS and REACH compliance certifications filter supplier pools.
- Lightweight:Single-ply polyethylene or non-woven covers optimized for seasonal deployment and rapid deployment logistics. Agricultural field crews in Spain and event rental fleets in the UK drive procurement through cash-and-carry distributors rather than specification-driven tenders.
- Waterproof:Heat-sealed seam constructions with hydrostatic head ratings for monsoon-grade logistics coverage.
- Fire Retardant:PVC formulations with halogenated or phosphorus-based additives meeting transportation and military specifications.
Heavy Duty dominates installed base. Lightweight is where expansion concentrates.
Material:
Cost tier stratification aligns raw material selection with end-use durability requirements and regulatory exposure.
- Polyethylene:Linear low-density grades with carbon black or HALS masterbatch stabilization dominate volume through cost efficiency. Indian highway contractors and Indonesian inter-island cargo operators specify these for 12-24 month replacement cycles in high-UV environments.
- PVC:Plasticized formulations with fire-retardant and antimicrobial additives command premium positioning. REACH phthalate restrictions and EU Green Deal carbon tracking are forcing compounders toward bio-based plasticizer validation for European transport fleet applications.
- Canvas:Cotton-polyester blends with wax or polymer coatings for heritage aesthetic and breathability requirements.
- Polyester:Woven technical textiles with PVC or PU coating for precision tensioning in architectural membrane applications.
Polyethylene captures volume leadership. PVC is where margin defense concentrates.
Application:
Customer-type differentiation separates project-based procurement from recurring operational consumption patterns.
- Construction:Temporary weather protection and site enclosure systems with debris containment and wind-load ratings. Indian central government logistics corridor investments and Dutch greenhouse renovation cycles are accelerating specification-grade procurement through qualified vendor lists.
- Agriculture:Crop protection, silage coverage, and livestock shelter applications where translucency and thermal management matter. Spanish and Dutch greenhouse operators are adopting nano-dispersed UV barrier films to extend growing seasons.
- Transportation:Flatbed truck covers, railcar liners, and maritime cargo protection with salt-spray and abrasion resistance.
- Outdoor Events:Festival infrastructure, temporary flooring, and crowd barrier systems with rapid deployment hardware compatibility.
Construction commands replacement-cycle value. Agriculture is where technology substitution concentrates.
Size:
Supply concentration favors standardized dimensions for inventory efficiency, while custom fabrication captures project-specific premiums.
- Small:Pre-cut dimensions for consumer DIY and light commercial applications through retail channels.
- Medium:Standardized widths for agricultural field coverage and single-vehicle protection.
- Large:Roll goods and panel systems for industrial site enclosure with crane-assisted deployment.
- Custom Sizes:Computer-cut patterns with welded seam integration for architectural membranes and irregular structure coverage.
Large formats dominate industrial procurement volume. Custom Sizes is where fabrication margin concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for polyethylene feedstock shapes regional competitiveness across major consumption hubs. Export-oriented compounders in Asia-Pacific leverage cost-advantaged resin access, while European and North American converters absorb premium logistics costs for specialized formulations.
India
Central government highway corridor investments and monsoon-sensitive logistics operations drive procurement of BIS-certified heavy-duty covers. The Bureau of Indian Standards mandates tensile strength and UV resistance testing that disqualifies informal regional suppliers. Organized compounders with captive testing facilities in Maharashtra and Gujarat capture market share from disqualified competitors.
Germany
Construction site enclosure and temporary weather protection systems dominate specification-grade demand from Dutch greenhouse renovation spillover. ECHA REACH restrictions on phthalate plasticizers force PVC compounders toward bio-based alternative validation. Industrial textile clusters in North Rhine-Westphalia pioneer Environmental Product Declaration documentation for public-sector tender compliance.
United States
Gulf Coast petrochemical complexes supply over half of global LLDPE feedstock, exposing domestic converters to hurricane-related supply interruptions. EPA air-quality standards for coating operations affect lamination facility siting decisions and import sourcing patterns. Texas-based resin integration provides margin buffers against Asian import competition.
China
Yangtze River Delta and Pearl River Delta manufacturing bases serve domestic infrastructure and export markets with cost-optimized polyethylene grades. Dual carbon goals and provincial emissions targets pressure coating operations toward energy-efficient lamination technologies. Zhejiang and Jiangsu provinces concentrate precision-coated technical textile capacity for maritime and agricultural applications.
Indonesia
Island-to-island cargo networks lack covered storage infrastructure, creating greenfield demand for salt-spray-certified maritime-grade tarpaulins. Domestic logistics operators specify corrosion-resistant formulations for tropical humidity exposure. Java-based fabricators scale production to replace imported covers from regional trading partners.
UV Protected Tarpaulin Sheets Market Competitive Landscape
Listed leaders compete with private specialists across certification access and resin integration depth. Market structure tilts toward tiered consolidation where organized compounders with backward polymer operations capture specification-grade segments, while fragmented regional fabricators compete on lightweight turnover velocity. Two archetypes dominate: integrated resin-to-film operators defending margin through feedstock control, and precision-coating specialists monetizing multi-certification technical competence. Competitive moves concentrate on BIS qualification arbitrage in India and REACH-compliant formulation lock-in across Europe.
Among India-based integrated operators, Supreme Industries Ltd. exemplifies the resin-integration archetype with captive compounding capabilities. SRF Limited occupies a position bridging fluoropolymer film expertise into industrial substrate applications. Heytex represents the European precision-coating specialist tier serving transport and agricultural fleet specifications. These three anchors illustrate how geographic feedstock access and regulatory certification depth separate sustainable positioning from commodity exposure.
| Leading Market Players |
|---|
| Supreme Industries Ltd. |
| Tarp Supply Inc. |
| Canadian Tarpaulin Manufacturers LTD. |
| Heytex |
| SRF Limited |
| Seaman Corporation |
| Shur-Co LLC |
| Tuohai Plastic Co., Ltd. |
| Sioen Industries |
| Others |
Value Network & Pricing Analysis
Resin-to-film scale economies in Gulf Coast petrochemical corridors compress polyethylene feedstock costs for integrated compounders, anchoring price floors that regional fabricators cannot match without captive polymer operations. This concentration rewards backward integration into compounding while exposing non-integrated converters to margin erosion when LLDPE spot markets tighten.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against resin price volatility. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European specifications from BIS-mandated Indian grades and unqualified regional alternatives. Pricing pressure stems from REACH phthalate reformulation costs that PVC compounders cannot fully pass through. Event rental fleets and agricultural field crews exhibit highest price sensitivity, while infrastructure contractors prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among Indian highway contractors facing monsoon procurement windows, while European construction fleets favor just-in-time replenishment through industrial distributor networks. Manufacturing gravity centers on China, India, and the United States, with Yangtze River Delta and Gujarat clusters serving regional and export demand. Feedstock supply draws from Gulf Coast LLDPE complexes, Hindustan Petroleum naphtha streams, and Zhejiang coal-to-olefin operations. Single-source vulnerability runs through hurricane-exposed Texas petrochemical corridors. Distribution runs through industrial distributors for heavy-duty grades and retail hardware networks for lightweight segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from rental and lease-to-own fleet management is expanding faster than hardware turnover, converting transactional tarpaulin sales into recurring platform relationships with construction and event-management operators.
For Market Incumbents: Shield specification-grade positioning by deepening captive compounding capabilities in Maharashtra and Gujarat to exploit BIS certification arbitrage against informal regional suppliers. Accelerate Environmental Product Declaration documentation for EU Green Deal compliance before Nordic hydro-powered imports capture German and French public-sector tenders. Prioritize HALS masterbatch R&D to displace carbon black in agricultural translucency applications. For New Entrants and Emerging Players: Anchor in Indonesian maritime logistics corridors where island-to-island cargo networks lack covered storage infrastructure and salt-spray-certified supply remains underdeveloped. Target agrivoltaic dual-use cover pilots from European energy cooperatives seeking UV-stabilized reflective sheets. Pursue direct mill relationships with national hire-fleet operators in UK and Benelux markets bundling covers with scaffolding systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-coating specialists with multi-certification competence over commodity resin-integrated operators facing polyethylene margin compression. Long-term viability hinges on circular-economy readiness as extended-producer-responsibility frameworks mature. Target compounders with in-house testing facilities and bio-based plasticizer validation pipelines. Watch for inflection when mechanical recycling compatibility mandates force multilayer lamination redesign.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive LLDPE supply buffers Supreme Industries against Gulf Coast price volatility. |
| Multi-Certification Technical Competence | REACH, EPA, and BIS stacking capability qualifies Heytex for cross-border infrastructure tenders. |
| Agrivoltaic Dual-Use Cover Development | Reflective UV-barrier films attract European energy cooperative pilot deployments. |
| Rental Platform Partnership Structure | UK hire-fleet bundling converts transactional sales into recurring service revenue. |
| Bio-Based Plasticizer Validation | ECHA Annex XVII compliance secures PVC compounder access to German transport fleet procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS certification registries, ECHA substance restriction filings, and SEC 10-K disclosures from listed compounders. Interviews with plant managers at lamination facilities, procurement leads at Indian highway contractors, distribution channel partners in European industrial textile networks, and technical R&D directors at stabilizer masterbatch suppliers informed demand-side validation. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against resin consumption patterns anchored market sizing.
Segmentation dimensions modeled include material grade tier, product duty classification, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections tied to infrastructure investment cycles and agricultural acreage trends. Industry-specific forecast inputs incorporate monsoon intensity patterns affecting Indian replacement cycles and EU Green Deal embodied-carbon tracking adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued Indian central government logistics corridor investment; material deviation would warrant model refresh. Specific risks include hurricane-related Gulf Coast supply interruptions, accelerated ECHA phthalate restrictions, and BIS testing mandate expansion. Revision becomes warranted when mechanical recycling compatibility mandates cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Webbing Market
Technical Textiles
Technical Textile Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Absorbent Cover Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Construction Textile Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Smart Textiles for Military Market