
 Global Cooling Fabric Market | 2026-2036
Global Cooling Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cooling Fabric Market Foresight
Vietnam's textile manufacturing corridor is reconfiguring global cooling fabric supply dynamics as foreign-owned mills expand dyeing and finishing capacity. HeiQ Materials AG leverages Swiss chemical innovation to sustain premium positioning in functional textile treatments. Nan Ya Plastics Corporation anchors Taiwanese petrochemical feedstock supply for synthetic cooling yarn production. Columbia Sportswear Company competes through direct sourcing relationships with Southeast Asian knitters.
Cooling fabrics are engineered textiles that lower skin temperature through evaporative heat transfer, moisture management, or infrared reflectance, typically incorporating specialized yarn structures, chemical finishes, or embedded phase change materials with transition temperatures between 28°C and 33°C. These materials serve commercial markets where thermal comfort directly affects human performance, safety, or endurance capacity. Phase change material fabrics occupy the highest margin tier due to energy-intensive microencapsulation processes and limited supplier bases. Moisture-wicking polyester dominates volume throughput across sportswear and workwear channels. Bamboo-derived cellulosic blends represent the fastest-expanding natural fiber category as brands navigate biobased sourcing mandates.
The US EPA regulates per- and polyfluoroalkyl substance discharge from textile finishing operations, while REACH restricts certain cooling chemical additives in EU-imported fabrics. China's GB standards mandate labeling accuracy for functional textile claims under SAMR enforcement. Japan's METI promotes Cool Biz guidelines that institutionalize breathable workwear procurement. Stakeholders must monitor evolving chemical restriction schedules and certification portability across jurisdictions to maintain market access.
Market Dynamics
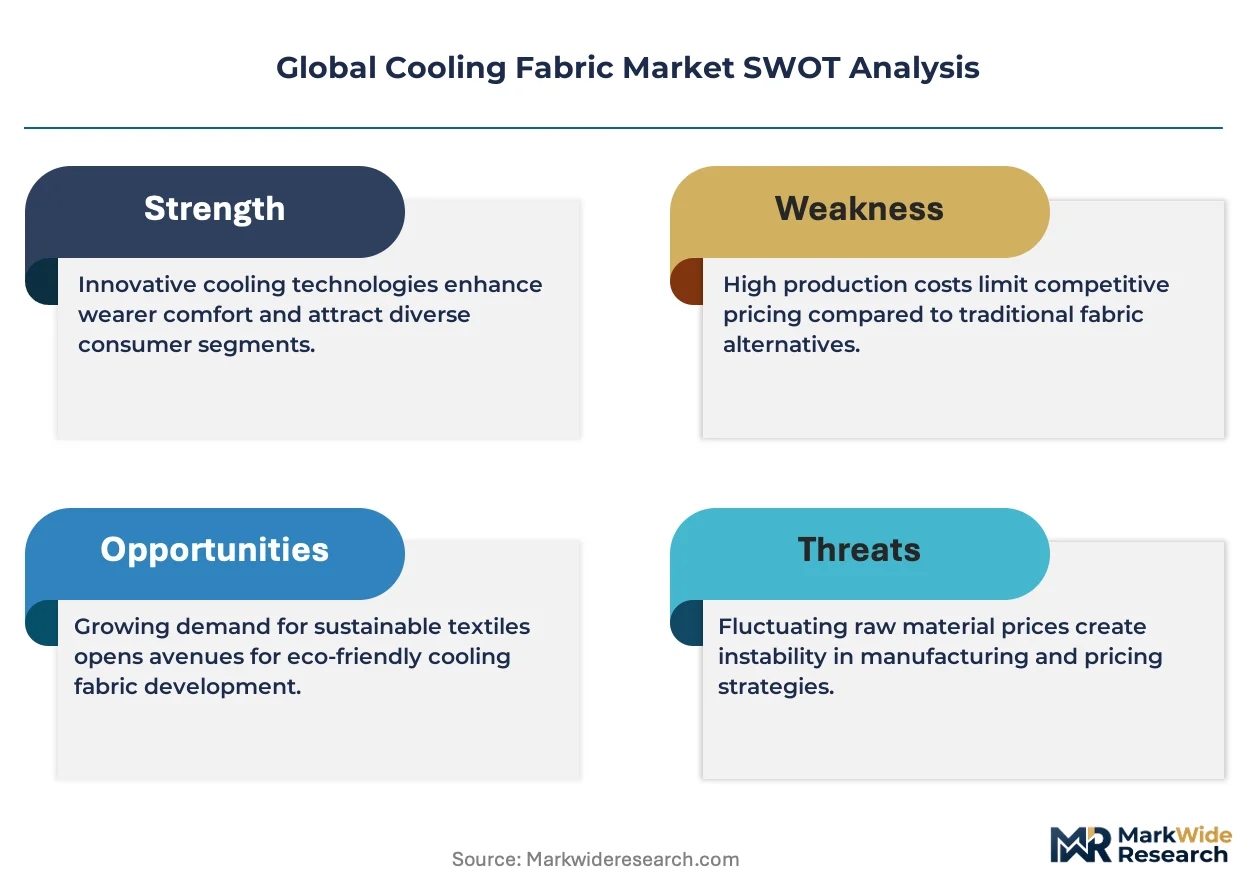
EU REACH chemical restrictions and US EPA per- and polyfluoroalkyl substance discharge rules are forcing textile finishers to reformulate cooling treatments, compressing supplier margins while opening compliance premiums for certified alternatives.
Growth Catalysts
- Athletic sportswear procurement:Moisture-wicking polyester orders from running and cycling apparel brands are pulling volume through Vietnam's integrated dyeing and finishing corridors.
- Japan's Cool Biz guidelines:METI institutionalization of breathable workwear procurement is creating institutional demand cycles for government and corporate uniform contracts.
- Phase change material microencapsulation:Energy-intensive processing of paraffin-based thermal regulators is sustaining premium pricing tiers in industrial protective wear and elite athletic applications.
Market Restraints
- Petrochemical feedstock volatility:Synthetic cooling yarn production depends on purified terephthalic acid and ethylene glycol pricing swings that compress spinner margins.
- Microencapsulation supplier concentration:Limited commercial-scale phase change material fabric processors in Germany and Switzerland create bottleneck risk for high-performance tier supply.
- Per- and polyfluoroalkyl substance substitution friction:US EPA discharge regulations and EU REACH restrictions on fluorinated cooling chemistries force costly reformulation without performance-equivalent drop-in replacements.
Strategic Opportunities
- India technical textile expansion:PLI scheme incentives for man-made fiber and technical textile investments are drawing cooling fabric finishing capacity toward Tamil Nadu and Gujarat manufacturing zones.
- Bamboo-derived cellulosic blends:Biobased sourcing mandates from European fashion brands are accelerating lyocell and modal blend development for natural-fiber cooling claims.
- Infrared-reflective mineral finishing:Convergence of ceramic particle surface treatments with digital textile printing enables customized cooling zone mapping for medical and military end-uses.
Industry Challenges
- Cross-jurisdictional certification portability:Divergent GB standards labeling requirements under China's SAMR, EU REACH compliance documentation, and US EPA discharge permits create multi-month approval timelines for global product launches.
- Phase change material thermal cycling durability:Microcapsule rupture rates after 50+ industrial laundering cycles limit warranty terms and create performance liability exposure for workwear rental service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cooling Fabric Market |
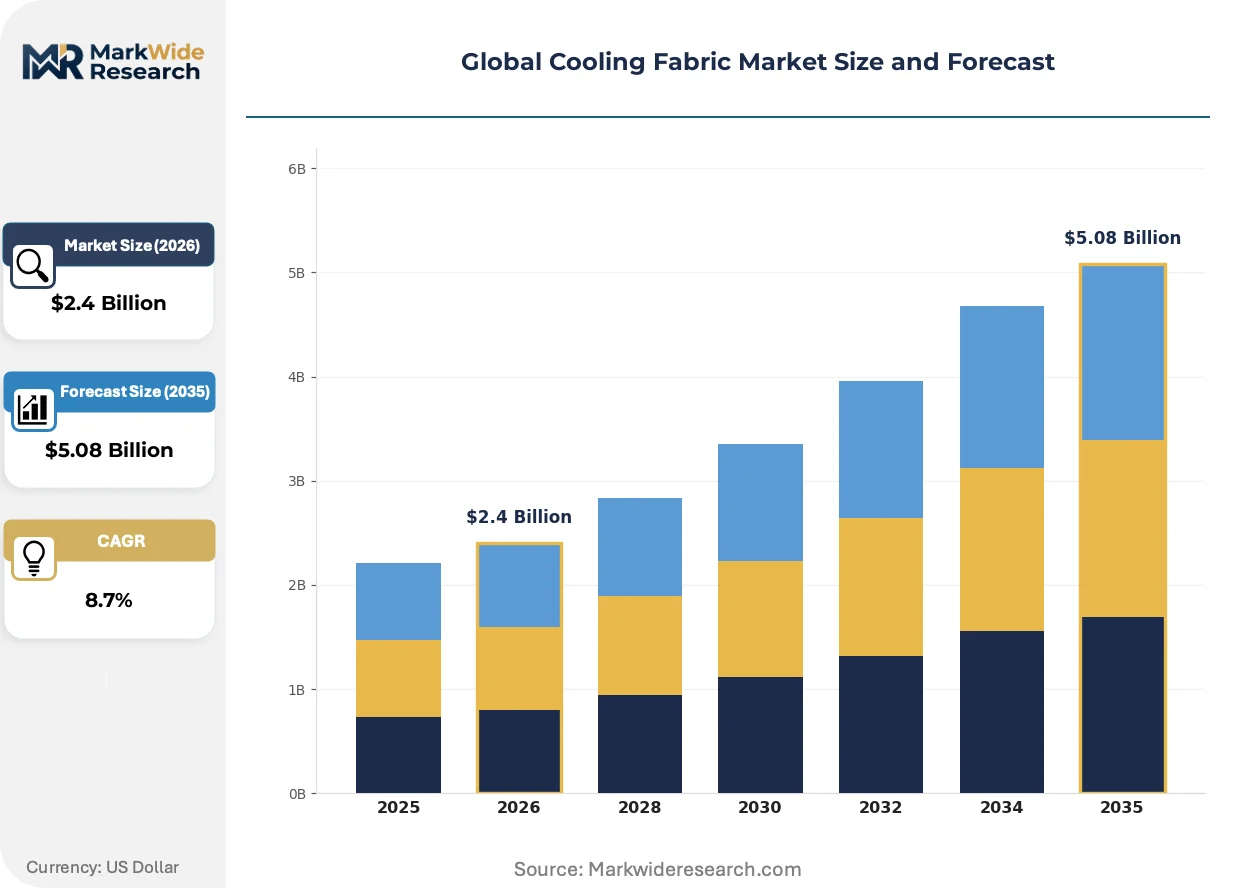
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Phase Change Material, Microfiber, Bamboo, Polyester, Nylon, Cotton Blends Cooling Technology: Evaporative, Moisture Wicking, Reflective, Phase Change, Ventilation-Enhanced, Bioceramic Application: Sportswear, Protective Clothing, Military Gear, Workwear, Outdoor Apparel, Footwear Linings End User Type: Athletes, Defense Forces, Construction Workers, Industrial Labor, Outdoor Enthusiasts, First Responders |
| Companies Covered | Coolcore, Nan Ya Plastics Corporation, Ahlstrom, Asahi Kasei Corporation, Columbia Sportswear Company, HeiQ Materials AG, NILIT, Polartec, Formosa Taffeta Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cooling Fabric Market Shifts & Advancements
Digital integration of textile finishing controls is compressing batch-to-batch variation while enabling mass-customization of cooling performance zones. Three developments are restructuring competitive positioning.
Smart manufacturing platforms are digitizing temperature and humidity sensor integration into fabric finishing lines. Athletic apparel brands in Germany and South Korea are specifying IoT-enabled quality verification for moisture-wicking performance claims. This digitizing of process control is reducing certification failure rates and compressing time-to-market for functional textile launches.
EU Green Deal chemical hazard classification expansions are extending REACH restriction schedules to cover additional cooling additive chemistries. Textile importers are restructuring supplier qualification protocols to pre-screen against anticipated substance bans. Vietnamese and Turkish finishers are most exposed given their reliance on EU export volumes and legacy chemical inventories.
Direct-to-brand sourcing relationships are displacing traditional textile trader intermediation in cooling fabric procurement. Columbia Sportswear and comparable outdoor apparel groups are establishing captive supplier development programs with Southeast Asian knitters. This pattern is most visible in Ho Chi Minh City manufacturing zones where foreign-owned mills now handle technical specification negotiation without regional distributor involvement.
Global Cooling Fabric Market Segmentation
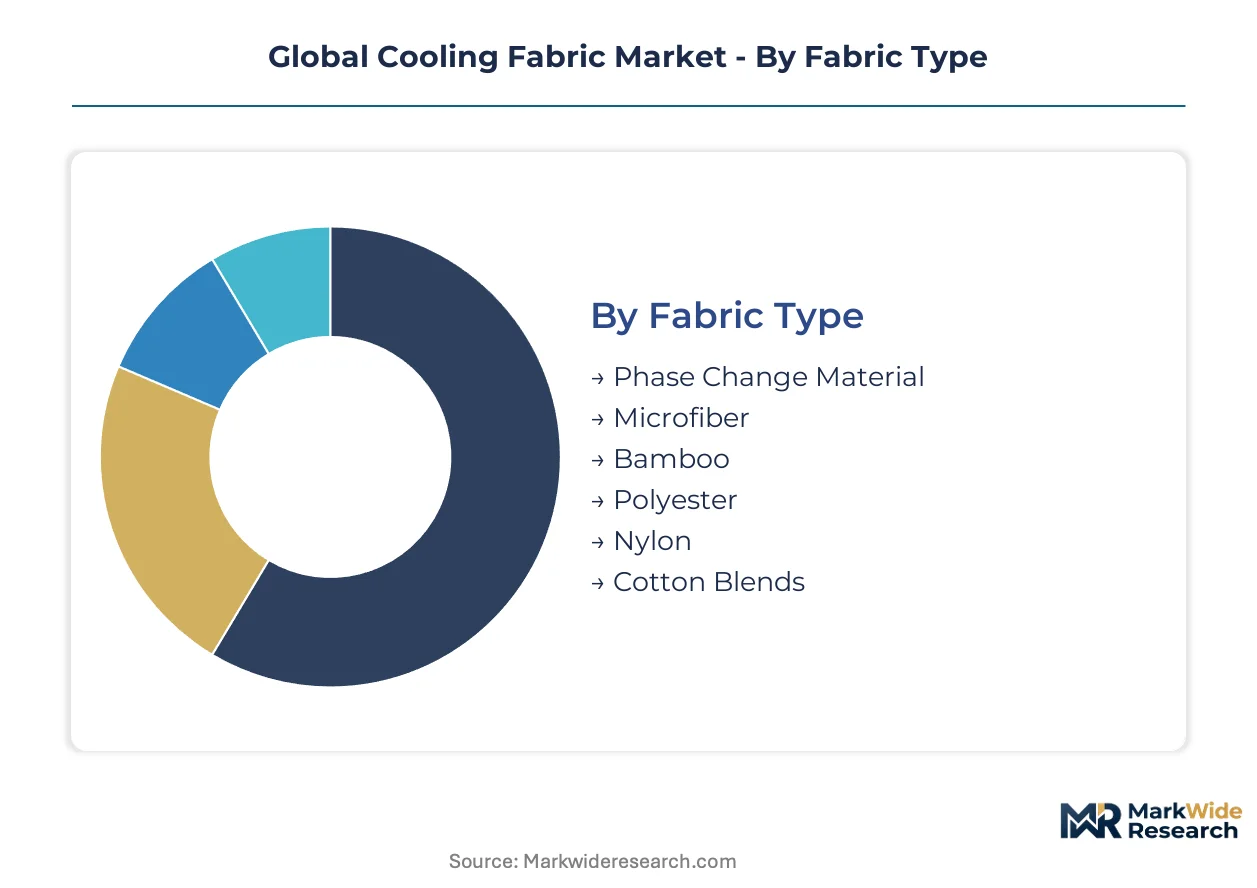
Cooling fabric procurement decisions hinge on thermal performance specifications, laundering durability, and end-use certification requirements. Each segmentation dimension reveals distinct margin structures and supplier qualification barriers that shape competitive positioning across technical textile value chains.
Fabric Type:
After-sales service intensity varies sharply across fabric categories, with phase change material fabrics demanding specialized thermal performance warranty support and industrial laundering cycle validation that standard moisture-wicking synthetics do not require.
- Phase Change Material:Microencapsulated paraffin waxes transition between 28°C and 33°C to absorb and release latent heat. Demand concentrates in German industrial protective wear rental programs where thermal cycling durability determines contract renewals. Limited commercial-scale processors in Switzerland and Germany sustain premium pricing tiers through technical service bundling.
- Microfiber:Ultra-fine synthetic filaments below 1 denier create capillary networks for rapid moisture transport. Vietnamese knitters near Ho Chi Minh City are expanding denier-splitting capacity to serve South Korean athletic brand specifications. After-sales claims center on pilling resistance and colorfastness rather than thermal performance degradation.
- Bamboo:Lyocell-processed cellulosic fibers from Chinese pulp sources enable biobased cooling claims. European fashion brand mandates are accelerating Tamil Nadu spinner investments in closed-loop solvent recovery systems.
- Polyester:Purified terephthalic acid-based filament dominates volume throughput across moisture-wicking applications. Petrochemical feedstock volatility compresses spinner margins without equivalent pricing power.
- Nylon:Polyamide 6,6 structures deliver abrasion resistance for military and workwear end-uses. US defense procurement specifications require domestic finishing capacity that limits supplier pools.
- Cotton Blends:Natural fiber hybrids with synthetic cooling yarns navigate consumer preference for tactile comfort. Processing complexity from fiber dyeing differential shrinkage raises finishing rejection rates.
By volume, Polyester leads. By growth pace, Bamboo is ahead.
Cooling Technology:
Cost tier stratification separates capital-intensive phase change microencapsulation from commodity chemical finishing, with ventilation-enhanced constructions occupying a mid-tier position where knitting equipment sophistication determines competitive access.
- Evaporative:Hydrophilic fiber surface treatments accelerate sweat vaporization rates. Australian mining workwear specifications mandate evaporative performance testing under AS/NZS 4399 standards for occupational heat stress mitigation.
- Moisture Wicking:Capillary channel engineering in filament cross-sections transports perspiration away from skin. Ho Chi Minh City integrated corridors process the majority of global athletic brand orders through automated dyeing and finishing lines.
- Reflective:Ceramic particle surface treatments reflect infrared radiation to reduce radiant heat absorption. Japanese METI Cool Biz procurement guidelines institutionalize reflective finishing requirements for government uniform contracts.
- Phase Change:Thermal regulation through solid-liquid phase transitions in microencapsulated paraffin. German industrial laundries require 50+ cycle durability guarantees that limit qualified supplier bases.
- Ventilation-Enhanced:Engineered mesh structures and strategic knit patterns enable convective cooling. Digital knitting controls in South Korean manufacturing zones enable mass-customization of ventilation zone mapping.
- Bioceramic:Mineral oxide incorporation claims far-infrared emission and thermal regulation effects. Chinese GB standards under SAMR enforcement mandate substantiation documentation for functional textile marketing claims.
Moisture Wicking commands volume leadership. Ventilation-Enhanced climbs fastest on athletic brand specification shifts.
Application:
Application-driven margin differentiation reflects certification burden variation, with military gear and protective clothing requiring multi-jurisdictional compliance documentation that sportswear and outdoor apparel categories escape.
- Sportswear:Running and cycling apparel brands specify moisture-wicking polyester with IoT-enabled quality verification. German and South Korean athletic companies are digitizing finishing line sensor integration for batch-to-batch consistency.
- Protective Clothing:Industrial heat stress mitigation drives phase change material adoption in foundry and smelting operations. Rental service providers face warranty exposure from microcapsule rupture after repeated industrial laundering.
- Military Gear:US defense procurement requires Berry Amendment compliance for domestic fiber and finishing sources. Infrared reflectance specifications for combat uniforms create specialized ceramic finishing demand.
- Workwear:Construction and logistics sectors prioritize durability and cost efficiency over thermal performance premiums. India's PLI scheme technical textile incentives are drawing finishing capacity toward Gujarat manufacturing zones.
- Outdoor Apparel:Hiking and fishing applications balance moisture management with weather protection layering compatibility. Columbia Sportswear and comparable brands establish direct sourcing relationships with Southeast Asian knitters.
- Footwear Linings:Sock and insole applications require antimicrobial finishing integration with cooling performance. Footwear brand specification fragmentation limits standardization economies.
Protective Clothing generates premium margins. Sportswear delivers volume scale.
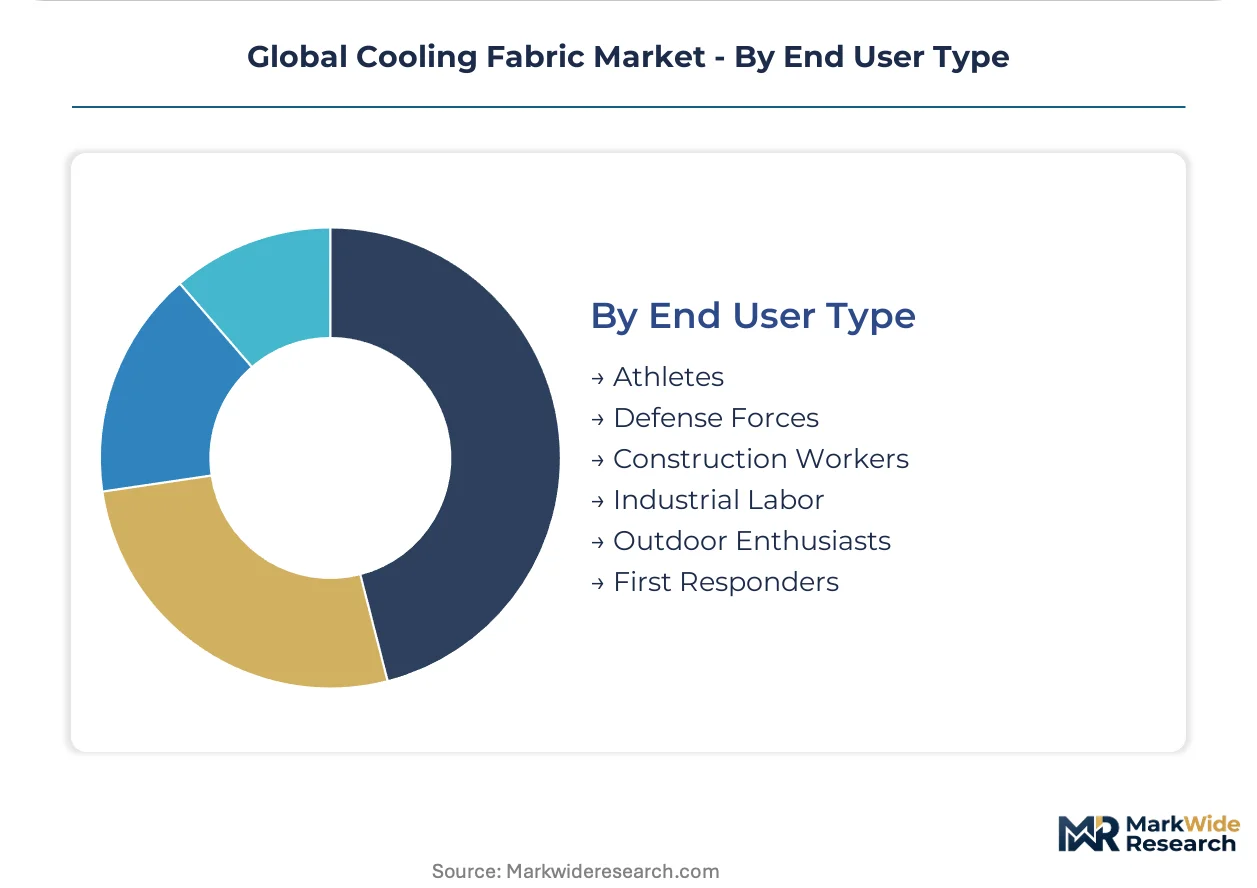
End User Type:
Customer type segmentation reveals procurement authority concentration, with defense forces and first responders operating through institutional contract vehicles that contrast with individual athlete and outdoor enthusiast retail purchasing patterns.
- Athletes:Elite and amateur competitors drive performance apparel innovation cycles. South Korean and German brand quality verification protocols are compressing time-to-market for functional textile launches.
- Defense Forces:National procurement agencies specify multi-year uniform contracts with thermal performance durability requirements. US Berry Amendment restrictions limit supplier qualification to domestic finishing capacity.
- Construction Workers:Employer-provided personal protective equipment programs prioritize cost containment over cooling performance premiums. Heat stress litigation exposure is gradually elevating specification standards in Australian and US markets.
- Industrial Labor:Foundry, smelting, and manufacturing operations mandate phase change material integration for occupational safety compliance. German industrial laundry associations are developing standardized thermal cycling test protocols.
- Outdoor Enthusiasts:Recreational hiking and fishing consumers balance technical performance with aesthetic and brand preference. Direct-to-consumer brand channels are displacing specialty retail intermediation.
- First Responders:Fire, emergency medical, and law enforcement agencies require flame resistance compatibility with cooling performance. Multi-hazard protection specifications create complex finishing chemistry requirements.
Industrial Labor concentrates premium technology adoption. Athletes drive volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooling fabric consumption patterns diverge sharply by geography. Japanese institutional procurement institutionalizes breathable workwear through METI guidelines. European fashion brands prioritize biobased sourcing mandates. American industrial laundries demand phase change material durability guarantees. Vietnamese manufacturing clusters absorb volume scale for athletic apparel.
United States
Industrial protective wear rental programs and military uniform contracts drive phase change material demand. The EPA regulates per- and polyfluoroalkyl substance discharge from textile finishing operations. North Carolina's technical textile corridor hosts domestic finishing capacity serving Berry Amendment-compliant defense procurement.
Germany
Industrial heat stress mitigation in foundry and smelting operations sustains premium phase change material adoption. ECHA REACH chemical restrictions force reformulation of fluorinated cooling chemistries. The Rhine-Ruhr manufacturing zone concentrates industrial laundry associations developing standardized thermal cycling test protocols.
Japan
Government and corporate uniform contracts institutionalize breathable workwear procurement through METI Cool Biz guidelines. JIS standards govern functional textile performance claims. The Kansai region's Osaka-Kobe textile finishing cluster processes reflective ceramic treatments for institutional contracts.
Vietnam
South Korean and German athletic brand orders pull moisture-wicking polyester volume through integrated dyeing corridors. EU Green Deal chemical hazard classifications expose Vietnamese finishers to anticipated substance bans. Ho Chi Minh City's foreign-owned mill zones handle direct technical specification negotiation without regional distributor intermediation.
India
PLI scheme incentives for man-made fiber and technical textile investments draw cooling fabric finishing capacity toward Tamil Nadu and Gujarat. BIS standards compliance requirements shape domestic market entry barriers. The Coimbatore-Tiruppur textile belt expands closed-loop lyocell solvent recovery systems for bamboo-derived cellulosic blends.
Global Cooling Fabric Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Phase change material microencapsulation demands energy-intensive processing and limited commercial-scale suppliers in Switzerland and Germany sustain premium pricing. Moisture-wicking polyester volume throughput concentrates in Vietnamese and Chinese spinner networks with automated dyeing lines. Three archetypes define competitive positioning: Swiss-German chemical innovators, Taiwanese-Japanese petrochemical feedstock suppliers, and American outdoor apparel brand owners with captive Southeast Asian sourcing. Dominant competitive moves include direct-to-brand supplier development programs displacing textile trader intermediation, and digitized finishing line sensor integration compressing batch-to-batch variation.
Among specialty chemical innovators, HeiQ Materials AG occupies a position exemplifying Swiss precision in functional textile treatments. Nan Ya Plastics Corporation anchors Taiwanese petrochemical feedstock supply for synthetic cooling yarn production. Columbia Sportswear Company represents the brand-owner archetype establishing direct sourcing relationships with Southeast Asian knitters. These three entities illustrate the capability-scale bifurcation: chemical innovation commands premium margins, feedstock integration secures volume leverage, and brand proximity captures specification authority.
| Leading Market Players |
|---|
| Coolcore |
| Nan Ya Plastics Corporation |
| Ahlstrom |
| Asahi Kasei Corporation |
| Columbia Sportswear Company |
| HeiQ Materials AG |
| NILIT |
| Polartec |
| Formosa Taffeta Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ho Chi Minh City port freight corridors absorb petrochemical feedstock volatility that compresses synthetic spinner margins while enabling Vietnamese finishers to undercut European phase change material pricing by certification-grade tiers.
Pricing Analysis
Geographic price spreads between Swiss-German phase change material microencapsulation and Vietnamese moisture-wicking polyester finishing exceed threefold across equivalent thermal performance specifications. Three-tier pricing structure across premium, standard, and economy levels separates energy-intensive paraffin microencapsulation from commodity chemical hydrophilic treatments and basic ventilation-enhanced knits. Pricing pressure stems from REACH reformulation mandates that force costly fluorinated chemistry substitution without performance-equivalent alternatives. Industrial labor rental programs exhibit least price sensitivity due to occupational safety liability exposure; construction workwear procurement shows highest elasticity as employer PPE programs prioritize cost containment.
Supply Chain Analysis
Contract manufacturing concentrates in Ho Chi Minh City integrated corridors where South Korean-owned mills handle direct brand specification negotiation, Tamil Nadu spinner networks expanding closed-loop lyocell systems, and Zurich-Basel chemical treatment specialists serving German industrial laundries. Purified terephthalic acid, ethylene glycol, and Chinese-origin bamboo pulp anchor raw material dependencies. Single-source vulnerability concentrates in Swiss-German phase change material microencapsulation where limited commercial-scale processors create bottleneck exposure. Distribution runs through direct-to-brand sourcing relationships displacing traditional textile trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Cooling Fabric Market expansion sits in early-cycle penetration as athletic brand procurement shifts from basic moisture-wicking to IoT-verified performance specifications.
For Market Incumbents: Build certification moats through preemptive REACH compliance documentation and thermal cycling durability warranties that exceed German industrial laundry association standards. Secure backward integration into Vietnamese dyeing corridors to defend spinner margins against petrochemical feedstock volatility. Counter threat from bamboo-derived cellulosic blends by accelerating closed-loop solvent recovery investments in Tamil Nadu. For New Entrants and Emerging Players: India's technical textile PLI scheme incentives represent the most penetrable geographic entry point for cooling fabric finishing capacity. Target Gujarat manufacturing zones for workwear cost-tier positioning; leverage Tamil Nadu for European fashion brand biobased mandates. Pursue digital textile printing convergence with infrared-reflective mineral finishing as differentiated go-to-market angle for medical and military end-uses. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to divest non-core textile chemical divisions amid EU Green Deal hazard reclassification pressure. Long-term viability favors specialty chemical innovators with REACH-compliant formulation pipelines over commodity synthetic spinners facing margin compression. Watch for inflection in South Korean athletic brand IoT verification specification adoption rates as signal for quality-premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dyeing Corridors | Vietnamese integrated zones enable margin defense against purified terephthalic acid price swings. |
| REACH-Compliant Formulation Investment | Swiss-German chemical specialists capture compliance premiums from fluorinated chemistry substitution mandates. |
| Closed-Loop Lyocell Capacity Expansion | Tamil Nadu solvent recovery systems satisfy European fashion brand biobased sourcing mandates. |
| IoT-Enabled Quality Verification Deployment | South Korean and German athletic brands specify sensor-integrated finishing lines for batch consistency. |
| Direct-to-Brand Supplier Development Programs | Columbia Sportswear archetypes disintermediate regional textile traders in Ho Chi Minh City zones. |
Research Methodology
Initial hypotheses were tested against primary input from textile finishing plant managers, athletic brand procurement directors, industrial laundry technical service heads, and specialty chemical R&D directors and refined through secondary validation against customs trade data, ECHA REACH substance restriction schedules, SEC textile company filings, and Vietnamese export statistics. Bottom-up volume modeling across fabric type, cooling technology, and application segments triangulated with top-down petrochemical feedstock demand analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling phase change material microencapsulation capacity constraints against industrial protective wear rental program procurement cycles. Segmentation dimensions spanned fabric type tier, cooling technology performance specification, end-use certification burden, and regional regulatory cluster. CAGRs derived from thermal performance specification diffusion curves and athletic brand sourcing pattern shifts. Key inputs included REACH chemical restriction implementation timelines and PLI scheme incentive disbursement trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed petrochemical conglomerates into Vietnamese finishing capacity would shift outcomes. Quarterly review of ECHA substance restriction proposal pipelines and South Korean athletic brand IoT verification specification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
E-Textile Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Webbing Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Technical Textile Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
US Geotextile Market