
 RV Leisure Battery Market | 2026-2036
RV Leisure Battery Market Size, Share, and Industry Trends Forecast 2026-2036
RV Leisure Battery Market Insights
Lithium iron phosphate is recalibrating cost-performance economics for deep-cycle RV applications by offering longer cycle life and reduced weight against traditional lead-acid architectures. East Penn Manufacturing sustains broad distribution across independent dealer networks and OEM supply chains. RELiON Battery LLC specializes in lithium-ion configurations purpose-built for mobile and marine environments. Trojan Battery Company anchors its position through decades of brand recognition in the flooded and AGM categories.
RV leisure batteries are rechargeable deep-cycle energy storage devices engineered to deliver sustained current over extended discharge periods, typically constructed with thick plate electrodes and electrolyte formulations optimized for cyclic durability rather than cranking amperage. Their primary commercial purpose is to power auxiliary loads including lighting, climate control, and inverter-driven appliances in vehicles lacking continuous shore power or generator operation. The lithium-ion segment commands premium pricing and captures the fastest expansion as consumers prioritize weight reduction and cycle longevity, while flooded lead-acid remains the mature volume category serving price-sensitive retrofit demand. Application demand tilts toward recreational vehicles and off-grid systems where boondocking behavior and solar integration expand battery bank sizing requirements.
The US Department of Transportation through NHTSA influences battery containment and crashworthiness standards for OEM-installed systems, while EPA guidelines govern lead-acid recycling and hazardous material handling across the aftermarket. In Europe, REACH and RoHS frameworks restrict cadmium and heavy metal content in imported cells, shaping supplier qualification and material sourcing decisions. Stakeholders must monitor evolving UN 38.3 lithium transport certification and emerging state-level energy storage fire codes that will determine which chemistries and form factors achieve retail shelf placement.
Market Dynamics
Lithium iron phosphate chemistry is compressing replacement cycles and redistributing value capture away from traditional flooded lead-acid suppliers toward integrated battery management system providers.
Growth Catalysts
- Boondocking behavior:Full-time RV residents and extended off-grid campers in the United States are expanding battery bank sizing requirements beyond traditional weekend-use patterns.
- UN 38.3 lithium transport certification:Harmonized international shipping standards for lithium cells are reducing cross-border friction for premium battery suppliers serving North American and European aftermarket channels.
- Solar integration:Photovoltaic panel installations on RV rooftops are creating paired demand for deep-cycle storage with higher charge acceptance rates and deeper discharge tolerance.
Market Restraints
- Cobalt and lithium carbonate price volatility:Raw material input swings compress margin visibility for lithium-ion pack assemblers and deter long-term OEM contracting.
- Lead-acid recycling infrastructure concentration:EPA-licensed smelter capacity clusters in the southeastern United States, creating geographic collection cost disadvantages for western aftermarket operators.
- AGM thermal runaway thresholds:Absorbed glass mat batteries face hard temperature ceilings that limit deployment in desert camping corridors where lithium alternatives tolerate wider operating ranges.
Strategic Opportunities
- Second-life automotive cell repurposing:Retired electric vehicle battery modules from Tesla and Nissan supply chains offer cost-competitive feedstock for budget RV retrofit segments.
- Bluetooth-enabled battery monitoring:Wireless state-of-charge telemetry is opening direct-to-consumer subscription revenue streams independent of dealer service bay capture.
- Inflation Reduction Act storage tax credits:Residential energy storage incentives in the United States are spilling over into RV classification debates that could unlock consumer subsidies.
Industry Challenges
- Battery management system firmware integration:Inverter and solar charge controller communication protocols fragment across Victron, Renogy, and Go Power product lines, forcing multi-platform compatibility engineering.
- UN 38.3 test report validity windows:Expiring lithium cell certifications trigger costly re-testing cycles that disrupt inventory planning for seasonal retail purchasing patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV Leisure Battery Market |
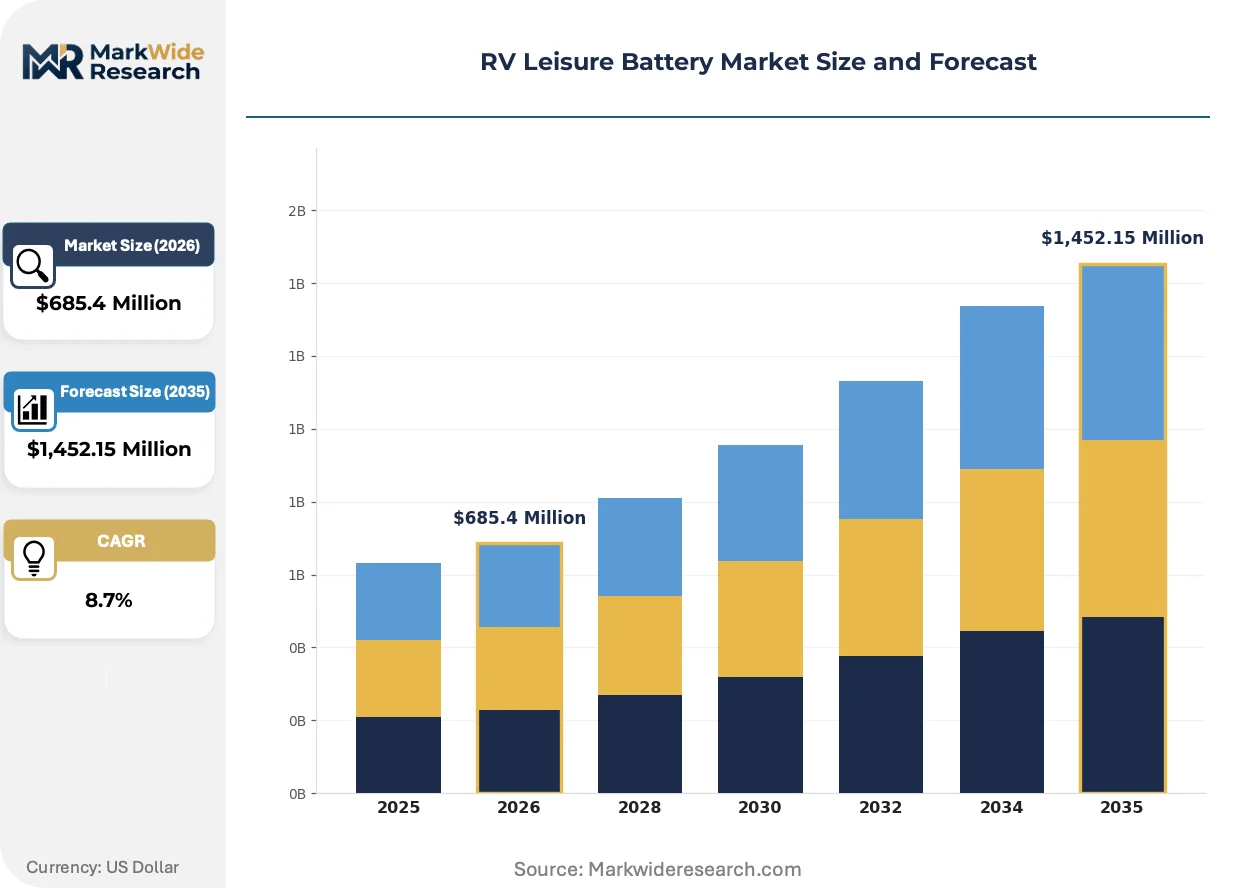
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lithium-ion, AGM, Gel, Flooded Application: Recreational Vehicles, Campers, Boats, Off-grid Systems End User: Individual Consumers, Fleet Operators, Rental Services, Manufacturers Capacity: 50Ah, 100Ah, 200Ah, 300Ah |
| Companies Covered | East Penn Manufacturing, Exide Technologies, EnerSys, Clarios, Crown Battery Manufacturing Company, Trojan Battery Company, RELiON Battery LLC, Interstate Batteries, Dragonfly Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV Leisure Battery Market Trends and Innovations
Active balancing circuitry and cloud-connected diagnostics are transforming RV batteries from passive commodities into intelligent assets that generate recurring service revenue.
Cell-level active balancing is automating voltage equalization across series strings in lithium iron phosphate installations. Premium fifth-wheel and Class A motorhome buyers are specifying these systems in factory orders at accelerating rates. This automation is compressing the service interval economics that previously sustained dealer revenue models built around annual battery maintenance.
REACH substance restrictions are tightening cadmium and heavy metal thresholds for cells imported into European Union member states. Battery assemblers serving German and Benelux caravan markets are reformulating electrode chemistries and resubmitting technical documentation. The OEM supply chain is absorbing compliance costs while independent aftermarket importers face customs detention risks.
Subscription-based battery health monitoring is displacing upfront hardware-only transactions in the United States direct-to-consumer channel. Buyers of lithium retrofit packs are selecting vendors offering mobile app connectivity and predictive replacement alerts. This shift concentrates in coastal states where tech-forward RV owners prioritize remote diagnostics over traditional dealer relationships.
RV Leisure Battery Market Segmentation
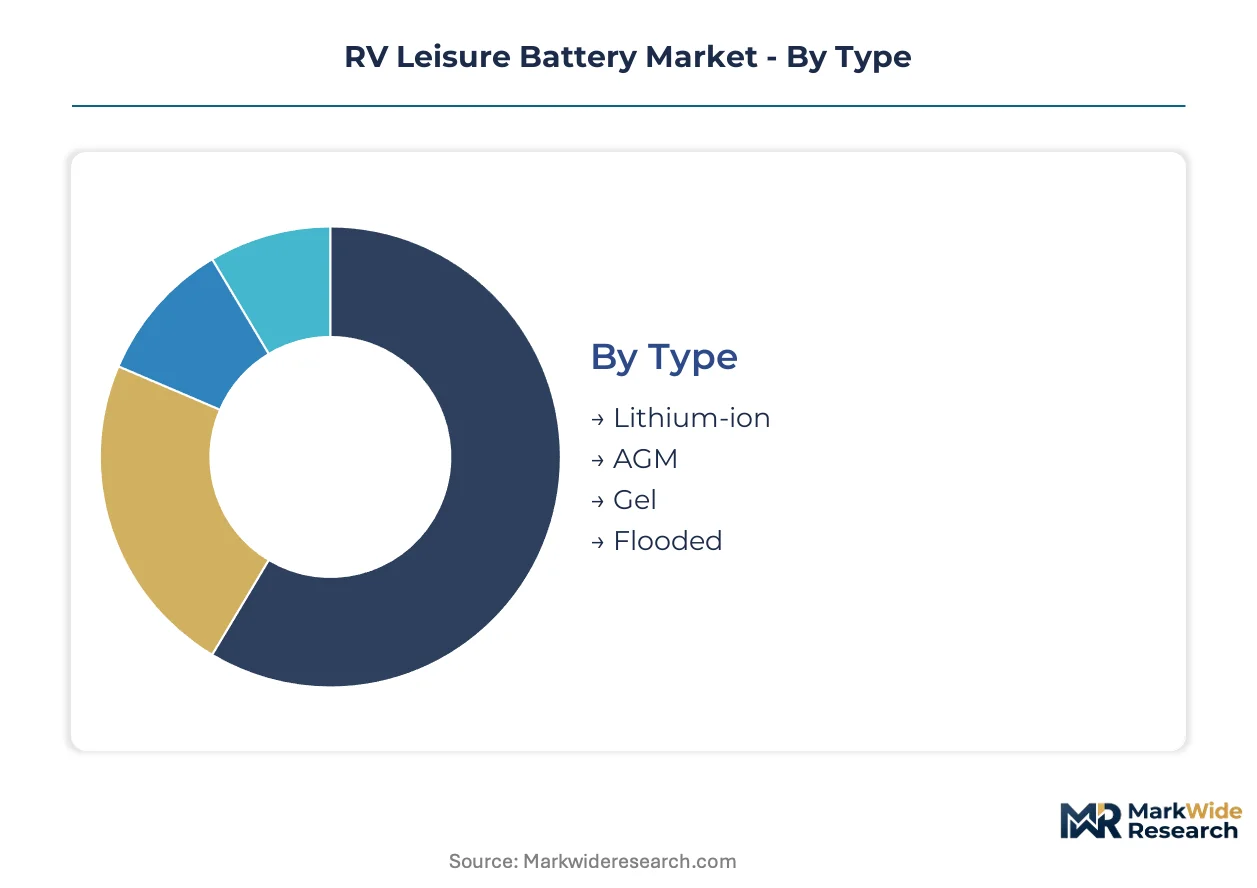
RV leisure battery purchasing splits sharply between entry-level retrofits and premium factory installations. Chemistry selection and capacity sizing diverge based on whether owners weekend-camp or live full-time off-grid. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows.
Type:
Lithium-ion commands premium positioning while flooded lead-acid anchors mass-market volume across dealer networks and big-box retail.
- Lithium-ion:Lithium iron phosphate cells deliver 3,000-5,000 cycle life with 50-70% weight reduction versus lead-acid alternatives. Demand clusters in factory-ordered Class A motorhomes and fifth-wheels bound for Arizona and Colorado boondocking corridors where solar array pairing justifies upfront cost.
- AGM:Absorbed glass mat construction eliminates electrolyte maintenance and tolerates moderate vibration in towable applications. Fleet operators running rental trailers across Utah and Nevada desert routes specify AGM for thermal stability where lithium budgets fail approval.
- Gel:Thixotropic electrolyte formulation resists stratification in deep discharge scenarios common to marine auxiliary power. European caravan owners in German and Benelux markets favor gel for cyclic durability in seasonal storage patterns.
- Flooded:Wet-cell lead-acid remains the default for price-sensitive weekend campers upgrading single batteries through independent RV service bays.
Mature deployment sits with flooded and AGM in aftermarket replacement channels. Newer deployment is concentrated in lithium-ion factory specifications and high-end retrofit conversions.
Application:
Vehicle classification determines bank sizing, enclosure standards, and integration complexity with inverter and solar charge controller systems.
- Recreational Vehicles:Class A, B, and C motorhomes require 200-400Ah lithium banks to support residential refrigerators and air conditioning through inverter loads. Factory installations at Thor and Winnebago production facilities in Iowa and Oregon are standardizing on lithium iron phosphate with active balancing.
- Campers:Truck campers and pop-up trailers typically deploy single 100Ah AGM or lithium units for basic lighting and water pump duty. Aftermarket retrofit demand concentrates in Pacific Northwest and New England regions where dispersed camping access is expanding.
- Boats:Marine applications demand corrosion-resistant enclosures and ignition protection compliance for gasoline-powered vessel compatibility. House battery banks on cruising sailboats prioritize deep-cycle gel or lithium for trolling motor and electronics endurance.
- Off-grid Systems:Skoolie conversions, van builds, and tiny home trailers often pair 300Ah lithium banks with 400W+ solar arrays for full autonomy. DIY installers sourcing through direct-to-consumer channels drive this segment's fastest expansion trajectory.
Volume concentrates in recreational vehicles through OEM supply agreements. Margin expansion is accelerating fastest in off-grid custom builds where battery-plus-solar bundling commands system-level pricing.
End User:
Procurement authority and technical sophistication vary dramatically across consumer, commercial, and industrial purchaser types.
- Individual Consumers:Retail purchasers research through YouTube van build channels and Reddit boondocking communities before selecting lithium retrofit packs. Subscription monitoring services and Bluetooth-enabled diagnostics increasingly influence vendor selection in California and Florida coastal markets.
- Fleet Operators:Commercial rental companies like Cruise America and El Monte RV standardize on AGM for maintenance predictability and nationwide service network compatibility. Procurement runs through annual volume contracts with Trojan and East Penn Manufacturing.
- Rental Services:Peer-to-peer platforms such as Outdoorsy and RVshare create fragmented demand as individual owners upgrade batteries to meet platform insurance and reliability standards.
- Manufacturers:OEM engineering teams at Forest River and Grand Design specify battery systems during chassis integration, locking in multi-year supply agreements with RELiON and other lithium specialists.
Service revenue potential is highest with individual consumers adopting connected battery platforms. Fleet operators prioritize total cost of ownership and replacement cycle predictability over feature differentiation.
Capacity:
Bank sizing correlates directly with inverter wattage ratings and days-of-autonomy targets in off-grid design calculations.
- 50Ah:Compact lithium units serve as starter battery replacements in vintage camper restorations and teardrop trailer builds where space constraints dominate. Weekend-use patterns in Texas Hill Country and Florida Panhandle state parks fit this profile.
- 100Ah:Single or dual 100Ah configurations represent the standard upgrade path for couples transitioning from tent camping to basic RV amenities. This capacity tier captures the broadest aftermarket volume through Amazon and Camping World retail channels.
- 200Ah:Parallel 200Ah lithium banks support residential refrigerators, microwave ovens, and CPAP machines through 2,000W inverters. Full-time RV residents working remotely from Bureau of Land Management land in Utah and Arizona specify this tier minimum.
- 300Ah:High-capacity installations enable multi-day autonomy without generator runtime or shore power connection. Skoolie and expedition vehicle builders targeting extreme off-grid locations in Alaska and Montana prioritize 300Ah as baseline configuration.
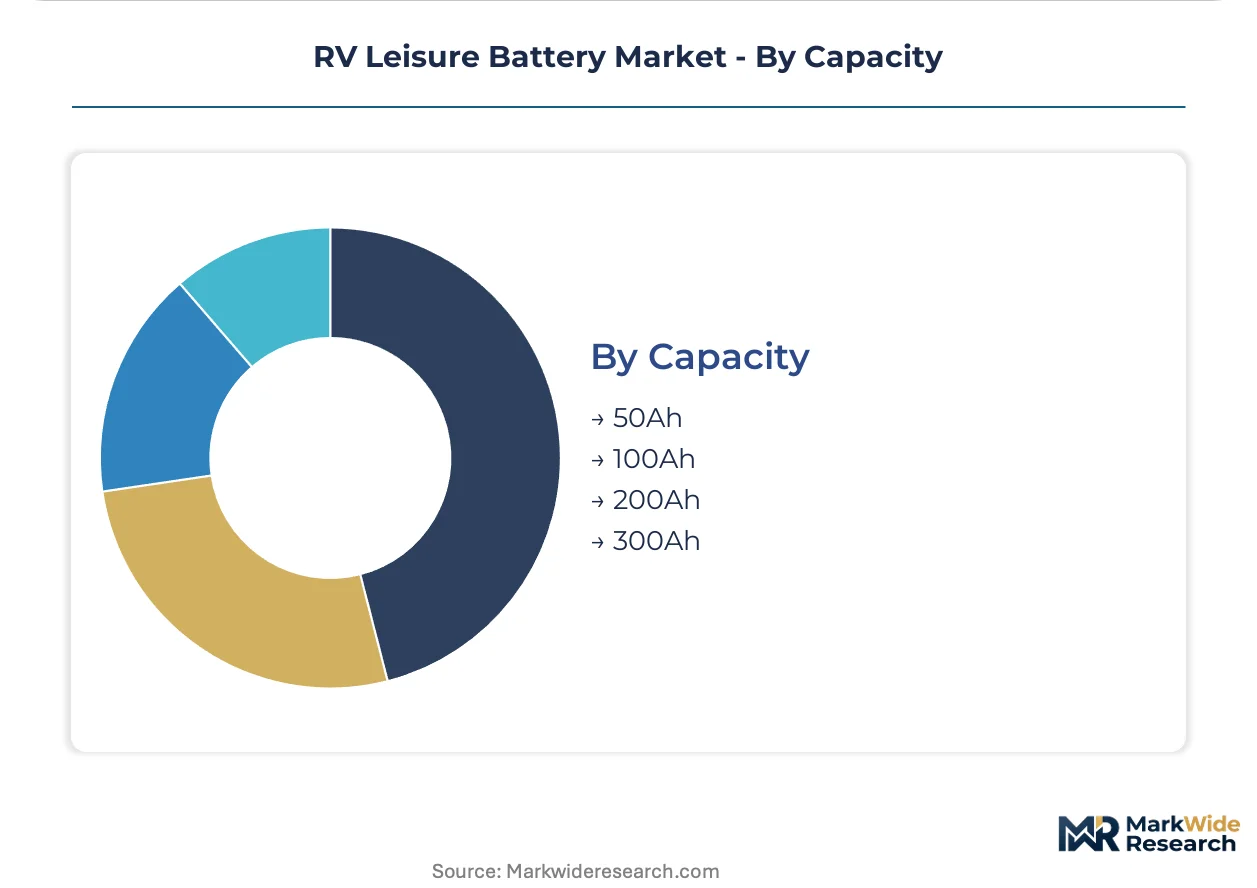
Replacement demand clusters at 100Ah where weekend campers upgrade from failing flooded units. Steepest expansion trajectory is occurring at 200Ah and 300Ah as full-time remote work lifestyles proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Arizona and Colorado concentrate lithium battery assembly capacity near dispersed camping corridors where full-time RV residents demand deep-cycle storage systems.
United States
Bureau of Land Management dispersed camping policies in Utah and Arizona expand boondocking access for remote workers needing 200-300Ah battery banks. The Inflation Reduction Act storage tax credits are spilling into RV classification debates that could unlock consumer subsidies. Factory installations at Thor and Winnebago production facilities in Iowa and Oregon are standardizing on lithium iron phosphate with active balancing circuitry.
Germany
REACH substance restrictions are tightening cadmium and heavy metal thresholds for cells imported into German and Benelux caravan markets. ECHA compliance documentation is absorbing supply chain costs while independent aftermarket importers face customs detention risks. Bavaria-based caravan manufacturers are reformulating electrode chemistries to maintain EU market access.
Canada
Parks Canada expanded backcountry camping permits are driving battery bank upgrades in Alberta and British Columbia RV markets. Health Canada electrical safety standards govern inverter integration for auxiliary power systems. Vancouver Island and Okanagan Valley service bays report accelerating lithium retrofit demand from seasonal snowbird migration patterns.
Australia
Remote area travel permits in Western Australia and Queensland require self-sufficient power systems for extended off-grid station stays. The country's national energy regulator monitors grid-disconnect safety protocols for residential-scale storage spilling into caravan applications. Melbourne and Brisbane specialty retailers are bundling 300Ah lithium banks with 400W solar arrays for expedition vehicle builders.
United Kingdom
Caravan and Motorhome Club membership growth in Scotland and Wales is expanding the retrofit battery upgrade market beyond traditional weekend-use patterns. CE marking requirements and post-Brexit UKCA transition are complicating import certification for European battery assemblers. Midlands-based independent dealers report strongest demand from retirees converting vans for full-time coastal residency.
RV Leisure Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium lithium configurations commanding distinct positioning from mass-market lead-acid volume. The vendor base organizes around three archetypes: legacy flooded battery manufacturers with deep dealer network penetration, lithium-focused specialists targeting factory installations, and diversified industrial battery producers serving fleet rental channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure cell supply agreements and inverter integration certifications.
Within the legacy manufacturer tier, East Penn Manufacturing and Trojan Battery Company anchor positions through decades of brand recognition in flooded and AGM categories. RELiON Battery LLC exemplifies the lithium-specialist archetype with purpose-built configurations for mobile environments. These three entities represent the competitive spectrum from mature volume production to premium chemistry integration.
| Leading Market Players |
|---|
| East Penn Manufacturing |
| Exide Technologies |
| EnerSys |
| Clarios |
| Crown Battery Manufacturing Company |
| Trojan Battery Company |
| RELiON Battery LLC |
| Interstate Batteries |
| Dragonfly Energy |
| Others |
Pricing and Supply Chain Analysis
EPA lead-acid recycling mandates gate qualified supply for aftermarket channels and compress premium-tier pricing access for lithium configurations that bypass smelter-dependent collection networks. Battery assemblers absorbing compliance documentation costs pass through differential pricing while independent importers face detention-driven inventory risk.
Pricing Analysis
Lead-time-driven pricing stratification rewards spot inventory holders with margin capture while long-lead factory orders trade at contracted discounts. Three-tier pricing structure across premium lithium, standard AGM, and economy flooded levels differentiates by certification grade and active balancing integration. Cost compression in entry-level flooded tiers intensifies because western aftermarket operators bear geographic collection penalties. Fleet rental channels exhibit lowest price sensitivity while DIY retrofit consumers in direct-to-consumer channels drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode active material suppliers feeding North American lithium iron phosphate cell production. Cell manufacturing concentrates in China, South Korea, and Japan while pack assembly localizes in Arizona and Colorado Qualified Opportunity Zones. Raw material dependencies center on lithium carbonate, cobalt sulfate, and electrolyte salt formulations. Tariff exposure on finished cells from Asia creates margin pressure for budget retrofit assemblers. Distribution runs through independent RV service bays and Camping World retail channels with seasonal purchasing concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cathode material refining represents the decisive upstream lever in this vertical-integration race, with cell supply agreements determining which pack assemblers secure OEM factory placement.
For Market Incumbents: Acquire lithium carbonate offtake contracts to lock feedstock cost visibility against spot market volatility. Trojan Battery Company and East Penn Manufacturing must secure active balancing firmware certifications with Victron and Renogy inverter platforms to defend dealer service bay relationships against lithium specialists. Flooded lead-acid incumbents face substitution threat from second-life automotive cell repurposing in budget retrofit segments. For New Entrants and Emerging Players: Bluetooth-enabled battery monitoring technology offers a service-revenue wedge against hardware-only transactions. White-space targets concentrate in 200Ah lithium retrofit demand from remote workers in Bureau of Land Management corridors and subscription telemetry adoption in California and Florida coastal markets. Direct-to-consumer digital acquisition paired with mobile app connectivity bypasses traditional dealer capture. For Investors and Strategic Acquirers: Inflation Reduction Act storage tax credit eligibility determinations for RV classification are the leading indicator that subsidy spillover will reshape consumer economics. Five-to-ten year viability favors pack assemblers with captive cell supply and inverter integration certifications over pure trading operations. Acquisition targets should demonstrate UN 38.3 certification maintenance capabilities and active balancing BMS development.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Supply Agreement | Locking lithium iron phosphate feedstock from CATL or BYD secures cost visibility for OEM factory placement. |
| Inverter Integration Certification | Victron and Renogy protocol compatibility opens dealer network access and reduces multi-platform engineering overhead. |
| Active Balancing BMS Development | Cloud-connected diagnostics transform hardware transactions into recurring subscription revenue streams. |
| Second-Life Automotive Cell Sourcing | Tesla and Nissan retired module feedstock enables cost-competitive positioning in budget retrofit segments. |
| UN 38.3 Certification Maintenance | Continuous testing validity ensures uninterrupted cross-border shipping and seasonal retail inventory planning. |
Research Methodology
Multi-period observation of battery bank sizing trends, solar array pairing rates, and lithium retrofit penetration anchored the trend analysis, supplemented by interviews with RV OEM platform engineers, independent dealer service managers, lithium pack assembly operations directors, and Bureau of Land Management permit issuance officers. Secondary validation drew from EPA hazardous waste manifests, NHTSA crashworthiness filings, UN 38.3 test report databases, and Parks Canada backcountry permit statistics. Bottom-up channel volume estimates triangulated against top-down OEM production data.
Input-output matrices mapped chemistry-specific demand across vehicle classifications and capacity tiers over the projection horizon. Segmentation dimensions modeled include battery chemistry type, RV vehicle class, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates. Forecast inputs incorporated solar panel installation correlation rates and dispersed camping permit issuance trajectories.
Several conditions sit outside the modeled scope, including state-level energy storage fire code adoptions, cobalt price spike scenarios, and automotive OEM second-life cell release timing. Forecasts reflect documented assumptions about IRA tax credit eligibility determinations and REACH substance restriction enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Europe Personal Watercraft Market