
 Deck Boat Market | 2026-2036
Deck Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Deck Boat Market Analysis
Capital-intensity divergence between in-house fiberglass molding capabilities and outsourced hull production is redrawing competitive boundaries in deck boat manufacturing. Sea Ray Boats leverages captive composite fabrication to sustain margin control across premium bowrider lines. Yamaha Motor Corporation anchors its position through sterndrive and outboard engine integration that competitors source externally.
A deck boat is a recreational watercraft distinguished by a broad, flat bow platform maximizing usable deck area for passenger entertaining and watersports activity, typically spanning 18 to 26 feet in length with beam widths exceeding 8 feet to enhance stability. Fiberglass dominates material selection for premium builds while aluminum occupies entry-level price tiers where weight reduction and trailering convenience matter most. Pontoon configurations lead volume in freshwater recreational use, whereas center console variants command higher margins in saltwater-adjacent coastal markets. Electric propulsion remains nascent but attracts outsized engineering investment as sterndrive installations face regulatory pressure.
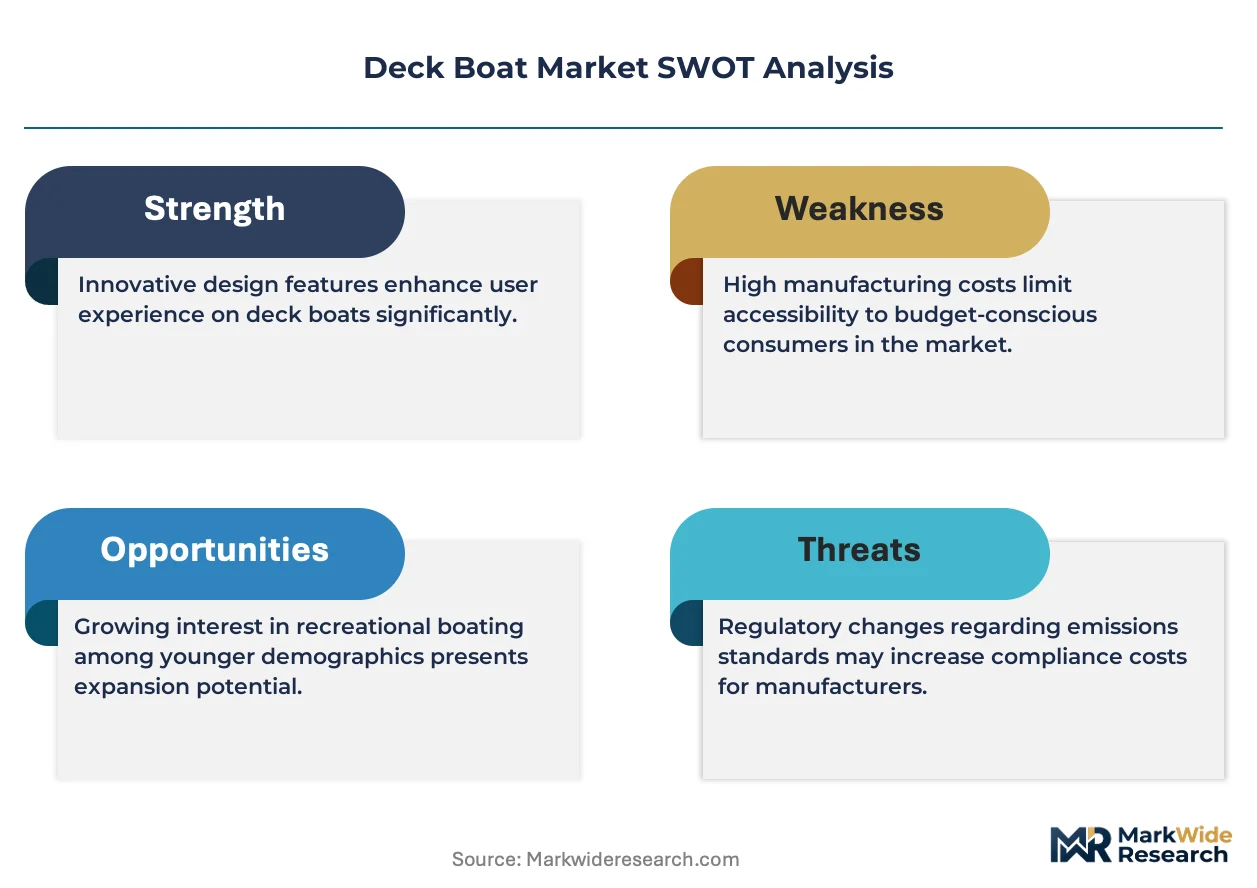
EPA marine emission standards constrain engine certification pathways while US Coast Guard flotation and structural integrity rules govern hull manufacturing compliance. NMMA certification programs further differentiate retail-ready inventory from uncertified competition. Stakeholders must weigh propulsion technology bets against evolving federal emission thresholds and shifting consumer willingness to absorb electrification premiums.
Market Dynamics
EPA marine emission standards are compressing sterndrive engine certification timelines while simultaneously accelerating electric propulsion R&D investment across fiberglass hull manufacturers. Hull-engine integration now determines competitive viability.
Growth Catalysts
- Recreational boating families:Leisure time allocation toward on-water entertaining drives bowrider configuration demand across Florida's inland lake networks.
- NMMA certification programs:Retail inventory differentiation creates pull-through for certified builders against uncertified competition in marina corridors.
- Fiberglass composite fabrication:Captive molding capabilities enable margin control and faster design iteration cycles for premium deck configurations.
Market Restraints
- Engine certification costs:EPA marine emission compliance expenses concentrate among sterndrive specialists without outboard diversification.
- Aluminum price volatility:Entry-tier hull material costs fluctuate with global metal commodity markets, compressing trailerable boat margins.
- Saltwater corrosion limitations:Pontoon configurations face structural durability constraints in coastal environments despite freshwater volume dominance.
Strategic Opportunities
- Electric propulsion convergence:Battery-electric outboard integration with lightweight aluminum hulls opens lake-restricted waterways with combustion bans.
- US Coast Guard flotation rule evolution:Updated structural integrity standards favor integrated hull-deck manufacturing over modular assembly methods.
- Center console coastal migration:Saltwater-adjacent buyers in Gulf Coast states seek higher-margin variants with offshore capability packages.
Industry Challenges
- Composite technician scarcity:Skilled fiberglass laminators and gelcoat finishers command premium wages amid boatbuilder expansion cycles.
- Hull mold capex intensity:Production-scale fiberglass tooling requires multi-year amortization against uncertain model lifecycle demand.
- NMMA certification timeline compression:Seasonal retail inventory windows constrain testing and documentation lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deck Boat Market |
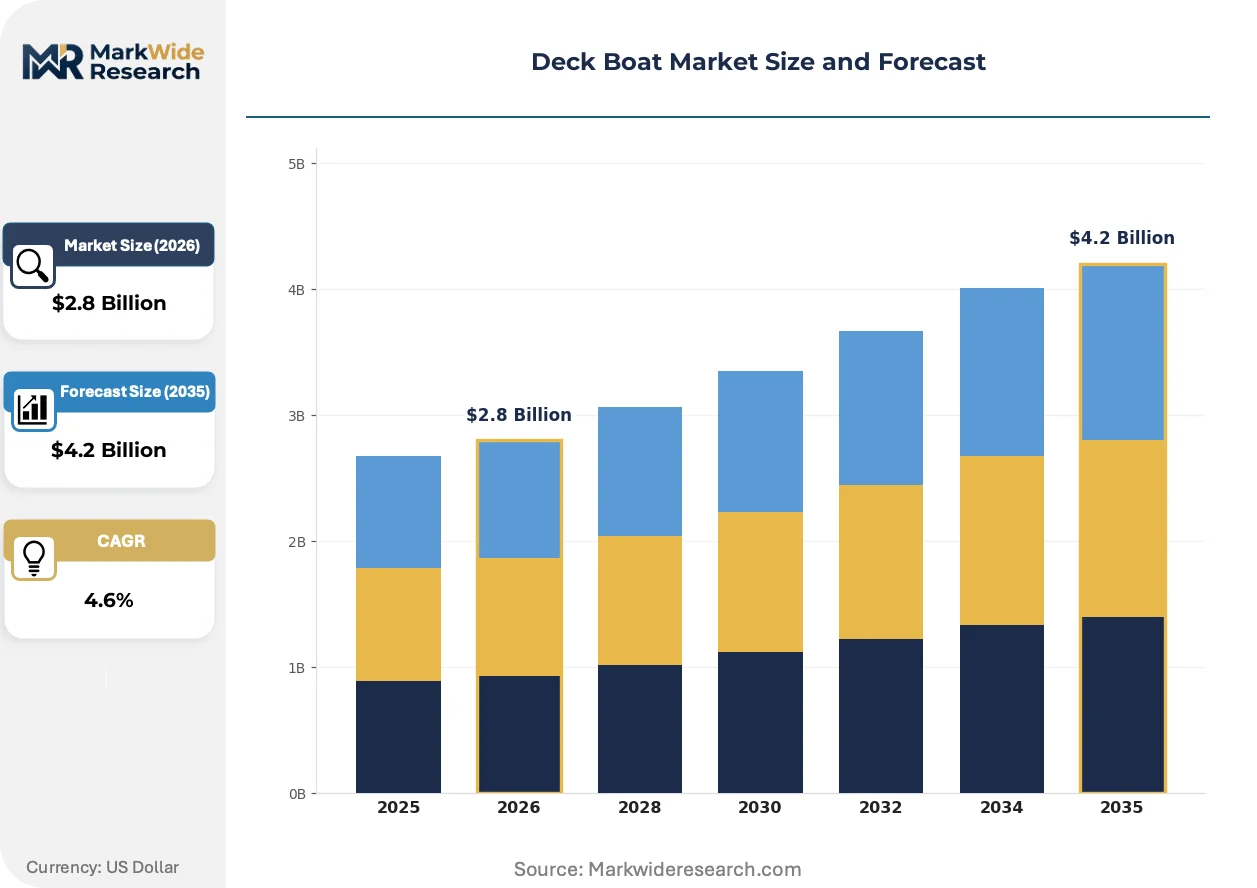
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bowrider, Center Console, Dual Console, Pontoon Engine Type: Outboard, Inboard, Sterndrive, Electric Material: Fiberglass, Aluminum, Wood, Composite End User: Recreational, Commercial, Rental, Tournament |
| Companies Covered | Sea Ray Boats, MasterCraft Boat Company, Bayliner Boats, Yamaha Motor Corporation, Starcraft Marine, Hurricane Marine Industries, Four Winns Corporation, Crownline Manufacturing, Stingray Boats Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deck Boat Market Emerging Trajectories
Propulsion technology divergence is splitting the market into three distinct engineering investment paths. Hull material selection now follows powertrain choice rather than driving it.
Electric outboard motor systems are fragmenting the traditional sterndrive-outboard boundary that has defined deck boat segmentation for decades. Freshwater marina operators in lake-restricted states are piloting charging infrastructure to capture early electrification adopters. This powertrain shift is fragmenting distribution relationships as engine manufacturers bypass traditional dealer networks for direct fleet sales.
EPA Tier 3 marine emission standards are eliminating certain two-stroke outboard configurations from new certification pathways. Sterndrive engine builders face particulate matter and hydrocarbon limits that favor four-stroke direct injection architectures. Coastal saltwater operators dependent on high-torque sterndrive performance are absorbing engine price premiums or migrating to outboard alternatives.
Buyer preference for turnkey watersports packages is displacing à la carte option selection in premium bowrider segments. Integrated wakeboard tower, ballast, and sound system configurations now dominate 22-foot and above retail transactions. This bundling concentration is most pronounced in Florida's competitive inland lake markets where rental fleet operators influence consumer expectations.
Deck Boat Market Segmentation
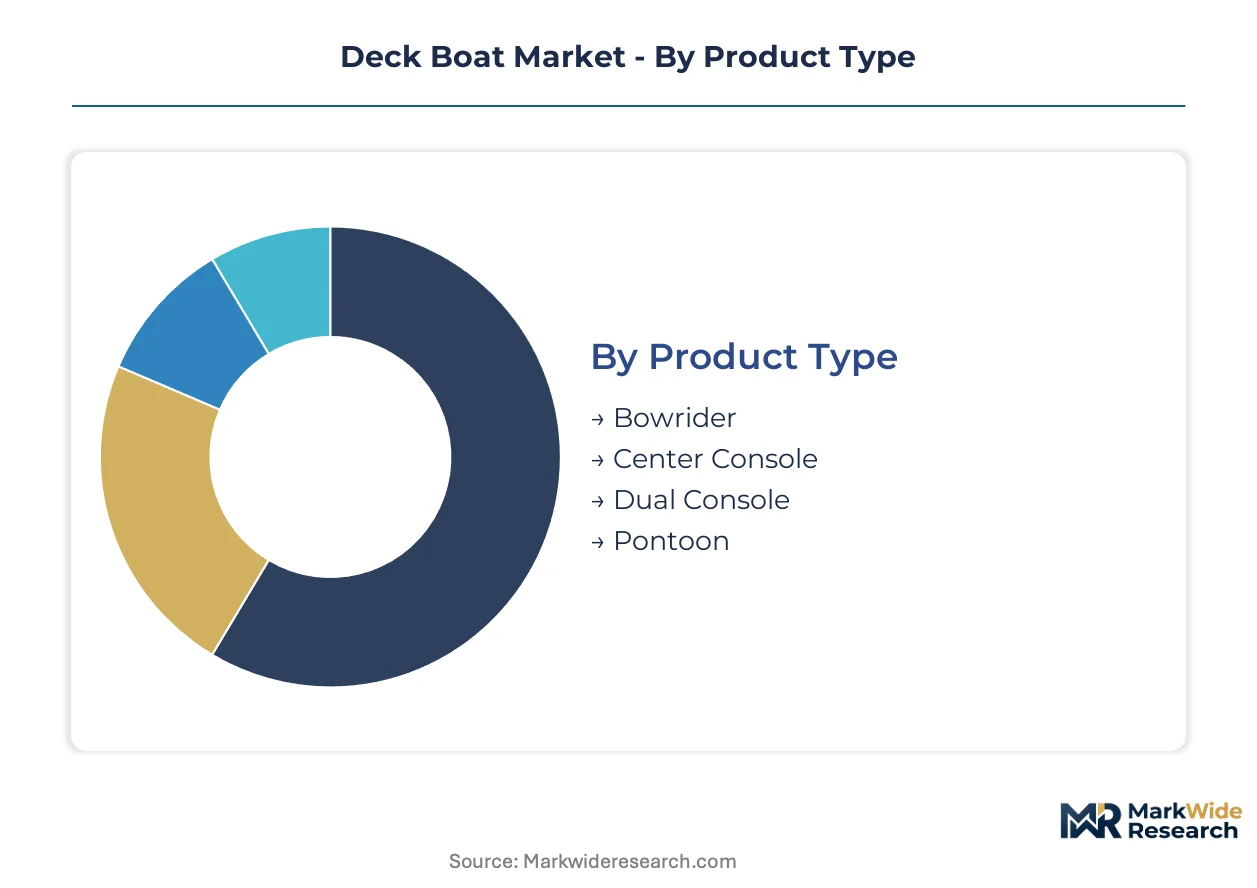
Deck boat segmentation reveals how hull configuration, propulsion choice, and material selection channel buyers toward distinct price-performance tiers. Manufacturers calibrate production capacity across these dimensions based on regional waterway regulations and marina infrastructure availability.
Product Type:
Bowrider configurations flow through premium dealer networks in Florida's inland lake corridors, while center console variants concentrate in Gulf Coast saltwater markets where offshore capability commands margin premiums.
- Bowrider:Broad, flat bow platforms maximize passenger entertaining space across 18-26 foot lengths. Demand clusters in freshwater recreational use throughout Florida's lake networks, driven by family leisure time allocation toward on-water socializing and integrated watersports packages.
- Center Console:Open deck layouts with centralized helm stations optimize 360-degree fishability and offshore handling. Saltwater-adjacent buyers in Texas, Louisiana, and Alabama absorb higher price points for corrosion-resistant hardware and deep-V hull geometries.
- Dual Console:Enclosed windshield configurations bridge bowrider entertaining with weather protection.
- Pontoon:Multi-hull aluminum platforms dominate volume in freshwater recreational use through trailerable convenience and stability.
Pontoon configurations dominate installed base volume across inland waterways. Center console variants are where expansion concentrates in coastal migration patterns.
Engine Type:
Powertrain selection now determines hull material and distribution channel alignment more than traditional size-class segmentation, with electric outboards fragmenting established sterndrive-outboard boundaries.
- Outboard:Four-stroke direct injection architectures have displaced two-stroke configurations under EPA Tier 3 marine emission standards. Yamaha Motor Corporation and Mercury Marine anchor dealer network relationships through integrated rigging and warranty coverage.
- Electric:Battery-electric outboard systems enable lake-restricted waterway access where combustion bans apply. Freshwater marina operators in California, Minnesota, and Vermont pilot charging infrastructure to capture early adopters.
- Sterndrive:Inboard-outboard configurations face particulate matter and hydrocarbon compliance pressure.
- Inboard:Direct-drive shaft arrangements persist in tournament watersports applications requiring precise wake control.
Outboard installations dominate current production volume across all product types. Electric propulsion is climbing the fastest as regulatory pressure and infrastructure investment converge.
Material:
Cost tier stratification separates captive composite fabrication from outsourced hull production, with aluminum occupying entry-level price points where trailering frequency matters.
- Fiberglass:Gelcoat-finished composite laminates enable complex hull geometries and premium aesthetic standards. Sea Ray Boats and Brunswick Corporation sustain margin control through in-house molding capabilities and faster design iteration cycles.
- Aluminum:Welded hull plate construction reduces weight for trailering convenience and resists freshwater corrosion. Entry-tier builders face margin compression from global metal commodity price volatility.
- Composite:Advanced resin-infused fabrics target specific strength-to-weight ratios in performance applications.
- Wood:Traditional cold-molded construction persists in custom restoration and heritage builds.
Fiberglass dominates premium segment revenue concentration. Aluminum is gaining share fastest in price-sensitive freshwater markets.
End User:
Customer type determines option bundling intensity and fleet procurement scale, with rental operators influencing consumer expectations through turnkey watersports configurations.
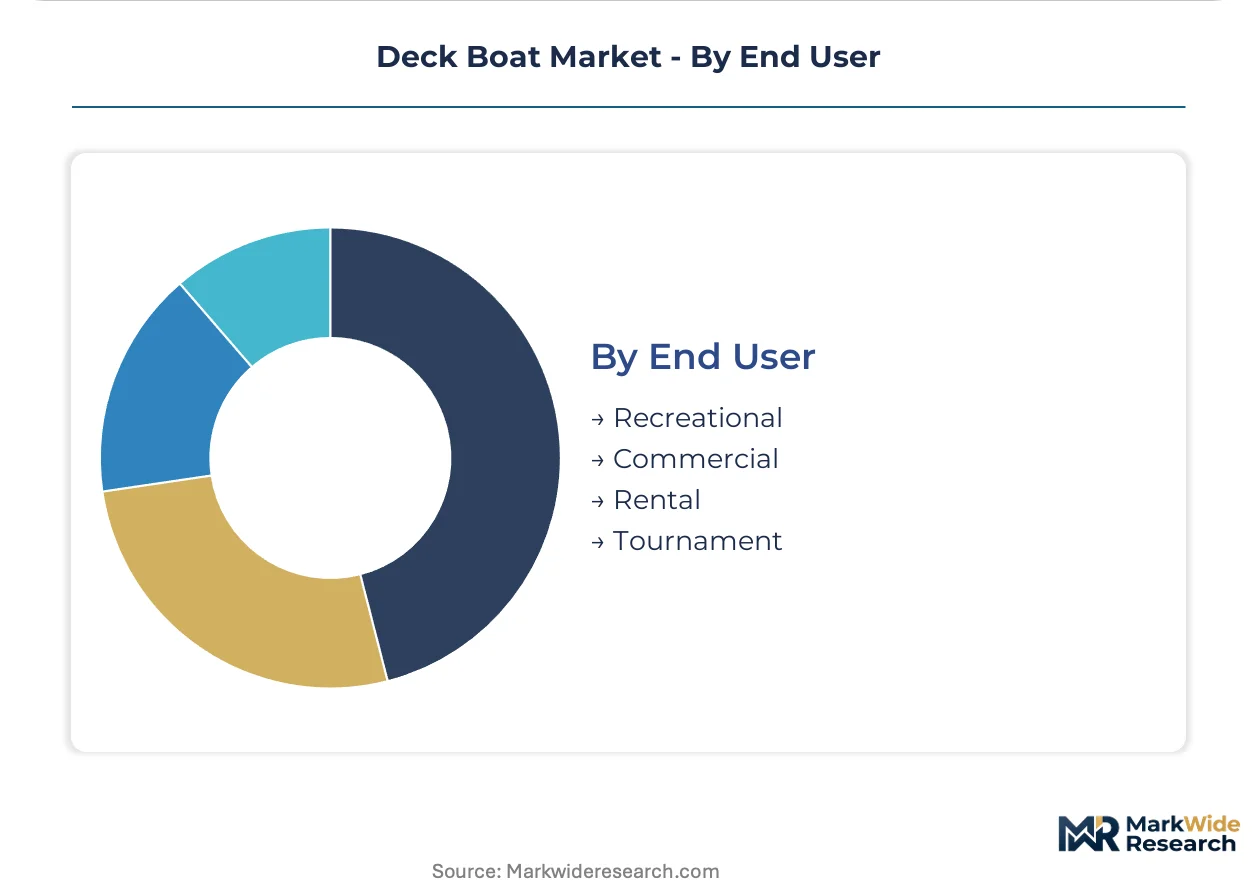
- Recreational:Family buyers prioritize integrated entertainment packages over à la carte selection, with wakeboard towers, ballast systems, and premium sound configurations now standard above 22 feet. NMMA certification programs differentiate retail inventory for this risk-averse segment.
- Rental:Fleet operators in Florida and Texas drive standardization toward durable, low-maintenance configurations with simplified operator interfaces. High utilization rates accelerate depreciation cycles and replacement demand.
- Commercial:Guide services and water taxi operators emphasize reliability and passenger capacity.
- Tournament:Competitive watersports participants demand precise wake shaping and ballast control.
Recreational buyers dominate unit volume across all product categories. Rental fleet procurement is expanding most quickly as marina operators consolidate ownership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deck boat consumption patterns diverge sharply between freshwater lake networks and saltwater coastal corridors, with geography dictating hull configuration preference and propulsion choice more than buyer demographics.
United States
Florida's inland lake networks and Gulf Coast marina corridors generate concentrated demand for bowrider and center console configurations. EPA marine emission standards compress sterndrive certification timelines while accelerating electric outboard pilots in California and Minnesota lake districts. Brunswick Corporation and Sea Ray Boats anchor manufacturing clusters across Tennessee and Florida, leveraging captive composite fabrication for premium hull production.
Canada
Ontario's Great Lakes waterfront properties and British Columbia's coastal inlets sustain steady demand for trailerable aluminum hulls suited to seasonal storage. Transport Canada vessel construction regulations align with US Coast Guard flotation standards, enabling cross-border inventory fluidity. Quebec-based marina operators in the Laurentian lake region increasingly stock pontoon configurations for multi-generational family entertaining.
Australia
New South Wales and Queensland coastal waterways drive center console preference for offshore fishing capability in rough-water conditions. Australian Maritime Safety Authority domestic commercial vessel standards influence recreational builder compliance frameworks. Sydney Harbour and Gold Coast Broadwater clusters concentrate rental fleet procurement, accelerating standardized watersports package adoption.
Germany
Bavarian lake districts and North Rhine-Westphalia reservoir networks favor compact, trailerable configurations suited to narrow waterway access. EU Stage V emission regulations for inland waterway vessels constrain combustion engine specifications while supporting electric propulsion development. Munich-area marina operators pilot battery charging infrastructure aligned with local air quality improvement targets.
France
Lac du Bourget and Mediterranean coastal marinas split demand between freshwater pontoon stability and saltwater center console offshore performance. French environmental regulations on protected waterway combustion access accelerate electric outboard trials in Alpine lake regions. Cannes and Nice yachting infrastructure influences premium deck boat specification expectations across southern European markets.
Deck Boat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in deck boat manufacturing, with captive composite fabrication capabilities separating premium-margin builders from outsourced hull assemblers. Sea Ray Boats and Brunswick Corporation exemplify vertical integration through in-house fiberglass molding, while aluminum specialists compete on trailering convenience and entry-tier pricing. Three archetypes dominate: integrated composite fabricators, engine-manufacturing conglomerates with hull operations, and regional aluminum builders serving price-sensitive freshwater markets. Competitive moves concentrate on hull-engine integration partnerships and electric propulsion technology licensing rather than pure capacity expansion.
Among US-based integrated manufacturers, Sea Ray Boats and MasterCraft Boat Company exemplify the captive fabrication archetype, leveraging in-house composite molding for design iteration speed and margin control. Yamaha Motor Corporation anchors the engine-conglomerate tier, with sterndrive and outboard integration capabilities that competitors often source externally. Bayliner Boats occupies a position within the volume-focused specialist segment, serving entry-tier price points where aluminum hull construction and outsourced powertrain procurement predominate.
| Leading Market Players |
|---|
| Sea Ray Boats |
| MasterCraft Boat Company |
| Bayliner Boats |
| Yamaha Motor Corporation |
| Starcraft Marine |
| Hurricane Marine Industries |
| Four Winns Corporation |
| Crownline Manufacturing |
| Stingray Boats Corporation |
| Others |
Supply Flow & Price Mechanics
NMMA certification programs gate both supply qualification and price differentiation simultaneously, separating certified builders from uncertified competitors in marina corridors while creating tiered margin structures that buyers recognize and reward. Certified inventory commands retail premiums against uncertified alternatives, yet compliance testing compresses seasonal production windows and concentrates pricing power among builders with captive documentation capabilities.
Pricing Analysis
Long-term offtake agreements between fleet operators and certified builders dominate procurement above fifty-unit annual volumes, while spot-market transactions persist for individual recreational buyers through dealer networks. Price differentiation stems from NMMA certification tier and captive composite fabrication versus outsourced hull production. Cost compression in aluminum entry-tier segments is intensifying because global metal commodity volatility erodes trailerable boat margins. Rental fleet operators exhibit highest price sensitivity due to depreciation acceleration, whereas tournament watersports buyers absorb premiums for precise wake control systems.
Supply Chain Analysis
United States and Canada anchor fiberglass composite fabrication for premium hull production, while China and Vietnam concentrate aluminum hull plate manufacturing for entry-tier segments. Raw material dependencies include marine-grade aluminum sheet, gelcoat resin systems, and multi-axial fiberglass fabrics. Supply chain risk centers on single-source vulnerability for EPA-certified sterndrive engines facing Tier 3 compliance deadlines. Distribution runs through NMMA-certified dealer networks in Florida's inland lake corridors and Gulf Coast marina clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deck boat manufacturing fragmentation creates opportunity niches as electric propulsion splits the traditional sterndrive-outboard boundary and lake-restricted combustion bans proliferate across state jurisdictions.
For Market Incumbents: Shield premium bowrider margins by deepening captive composite fabrication capabilities against aluminum specialist price erosion. Accelerate electric outboard integration partnerships before engine manufacturers bypass traditional dealer networks for direct fleet sales. Prioritize NMMA certification investment to maintain retail inventory differentiation against uncertified competition. For New Entrants and Emerging Players: After-sales service networks for electric propulsion systems represent an underserved layer where incumbents lack charging infrastructure deployment expertise. Target freshwater marina operators in California and Minnesota lake districts piloting battery charging installations. Pursue direct fleet sales relationships that circumvent established dealer territorial protections. For Investors and Strategic Acquirers: EPA Tier 3 marine emission standard implementation reshapes the acquisition landscape by eliminating certain two-stroke outboard configurations and compressing sterndrive specialist viability windows. Long-term viability favors integrated builders with backward control over hull molding and engine integration partnerships. Monitor sterndrive engine certification timeline delays as inflection indicators for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Integration | Battery-electric outboard partnerships open lake-restricted waterways in Minnesota and California districts. |
| NMMA Certification Acceleration | Compressed testing timelines capture seasonal retail inventory windows before uncertified competitors. |
| Captive Composite Fabrication Expansion | In-house fiberglass molding sustains margin control against outsourced hull assemblers in premium segments. |
| Center Console Coastal Migration | Offshore capability packages capture saltwater-adjacent buyers in Texas and Louisiana Gulf markets. |
| Charging Infrastructure Partnership | Marina operator alliances secure early adopter positioning in Vermont and California lake-restricted corridors. |
Methodological Framework
A standing panel of hull manufacturing engineers, marina fleet procurement managers, NMMA certification specialists, and sterndrive powertrain architects provided ongoing calibration across primary fieldwork phases. Secondary validation drew from US Coast Guard flotation standard documentation, EPA marine emission certification databases, customs trade records for aluminum hull imports, and SEC filings from publicly traded marine manufacturers. Bottom-up demand modeling triangulated against top-down production capacity estimates across fiberglass and aluminum fabrication facilities.
Consistency checks validated volume and value outputs against external benchmarks including NMMA new boat registration databases and state-level marina operator surveys. Segmentation dimensions spanned hull configuration, propulsion architecture, material grade tier, and end-use customer type across the projection horizon. CAGRs were derived from regression analysis of historical production volumes against macroeconomic leisure spending indicators and regulatory compliance cost trajectories. Industry-specific inputs included EPA Tier 3 implementation schedules and electric outboard battery energy density improvement curves.
Material uncertainties — EPA emission standard enforcement delays, aluminum commodity price spikes, and electric charging infrastructure deployment failures — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding sterndrive engine certification pathway availability and recreational leisure time allocation stability. Recalibration cycles align with material shifts in federal marine emission thresholds and state-level combustion ban enactments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
North America Hovercraft Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Jon Boat Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Electric Golf Cart Market