
 Snowmobile Trailer Axle Market | 2026-2036
Snowmobile Trailer Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Snowmobile Trailer Axle Market Analytics
Multi-source procurement toward vertically integrated in-house forging is rebalancing supplier power across the snowmobile trailer axle value chain. Dexter Axle sustains domestic manufacturing scale across its Indiana and Georgia plants. BPW Group leverages European engineering standards to compete in North American premium segments. DexKo Global anchors aftermarket distribution through its extensive dealer network.
A snowmobile trailer axle is a load-bearing rotating shaft assembly, typically manufactured from normalized SAE 1045 steel or 6061-T6 aluminum extrusions, that transmits trailer weight to wheels while accommodating torsional stress from uneven terrain. Tandem axle configurations dominate fleet purchases due to stability requirements on icy access roads, while aluminum material grades capture margin pools in lightweight racing trailer applications. Bolt-on attachment methods lead the aftermarket channel because owner-operators prioritize field-serviceability during remote winter excursions.
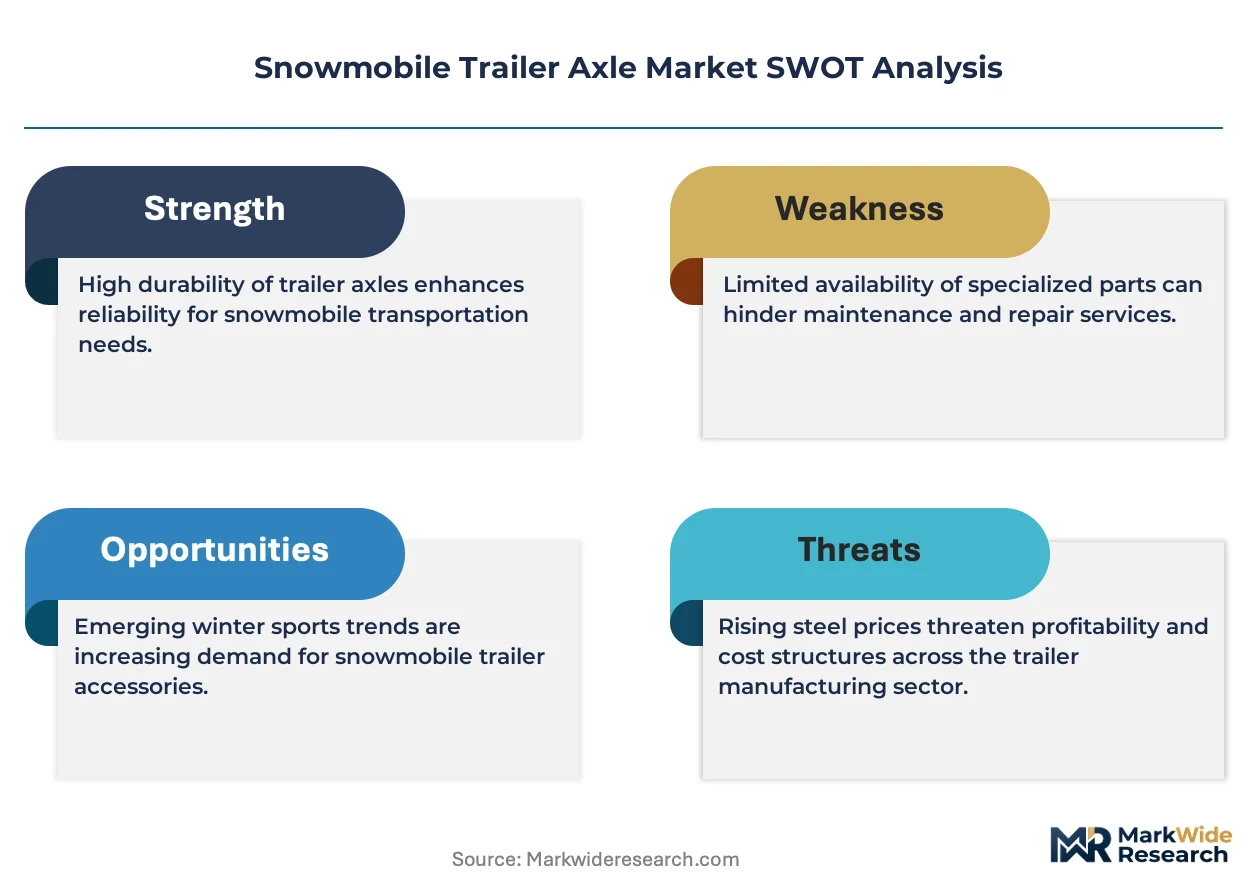
NHTSA Federal Motor Vehicle Safety Standard 108 governs lighting and conspicuity on towed equipment, while Transport Canada CMVSS regulations enforce comparable brake performance thresholds for trailers exceeding specified gross weights. State regulators in Wisconsin and Minnesota impose seasonal weight restrictions that directly influence axle load capacity selection by commercial tour operators. Stakeholders must monitor evolving electrification of snowmobile powertrains, as heavier battery architectures will force recalibration of axle ratings and suspension geometry across new trailer designs.
Market Dynamics
Electrification of snowmobile powertrains is forcing axle manufacturers to recalibrate load ratings and suspension geometry for heavier battery architectures. This structural shift cascades through material selection, forging tolerances, and aftermarket compatibility requirements across the value chain.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 108:Lighting and conspicuity mandates for towed equipment drive replacement cycles in commercial fleets. Tour operators upgrade trailers to maintain compliance during peak winter seasons.
- Normalized SAE 1045 steel forging:Advances in heat treatment processes improve fatigue resistance on icy access roads. Fleet purchasers specify these grades for tandem axle configurations in high-frequency rental applications.
- Upper Midwest corridor concentration:Wisconsin and Minnesota weight restriction regimes create predictable demand spikes. Seasonal permit windows force operators into scheduled axle capacity upgrades.
Market Restraints
- Aluminum extrusion input volatility:6061-T6 billet pricing fluctuates with aerospace and automotive demand. Lightweight racing trailer segments face margin compression when primary metal markets tighten.
- Domestic forging capacity concentration:Indiana and Georgia plants anchor North American supply. Disruption at either facility propagates through OEM and aftermarket channels simultaneously.
- Substitution by galvanized steel alternatives:Cost-sensitive owner-operators defer aluminum upgrades. Bolt-on steel assemblies persist in remote service environments despite weight penalties.
Strategic Opportunities
- Rocky Mountain corridor expansion:Colorado and Utah backcountry touring operators underinvest in trailer infrastructure. Targeted distribution partnerships capture fleet standardization decisions.
- Transport Canada CMVSS brake performance thresholds:Cross-border compliance requirements favor suppliers with dual-certification capabilities. Canadian tour operators seek unified axle specifications for transnational routes.
- Telematics-integrated suspension monitoring:Convergence of IoT sensors with torsional stress measurement enables predictive maintenance. Premium fleet segments adopt real-time axle health monitoring for remote winter operations.
Industry Challenges
- Welding certification bottlenecks:AWS D1.1 structural welding qualifications constrain qualified technician supply. Rural service centers struggle to staff field-repair operations during peak season.
- Legacy trailer compatibility:Pre-2010 frame geometries lack standardized attachment patterns. Aftermarket bolt-on axle retrofits require custom fabrication, extending lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowmobile Trailer Axle Market |
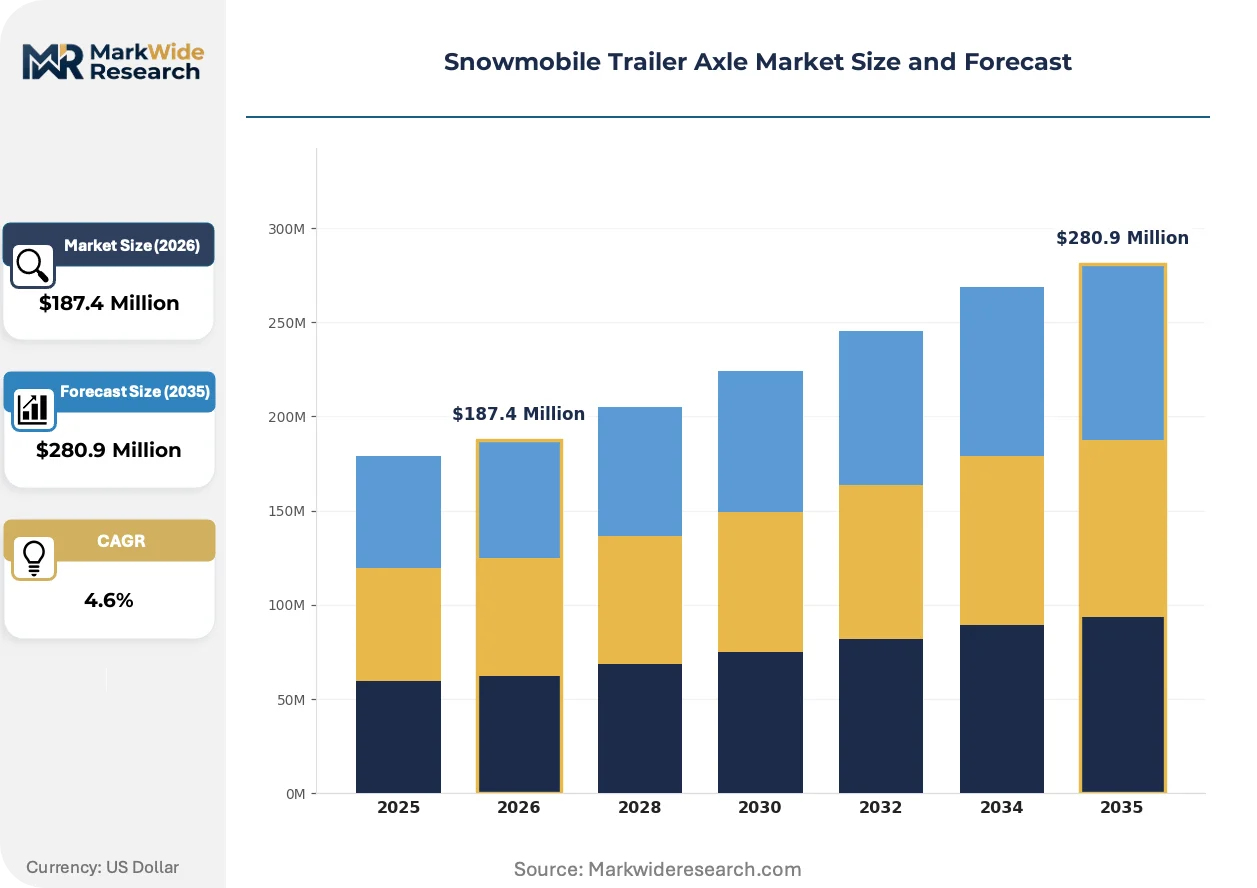
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Axle, Tandem Axle, Triple Axle, Heavy-Duty Material: Aluminum, Steel, Composite, Fiberglass Load Capacity: 1000 lbs, 2000 lbs, 3000 lbs, 4000 lbs Attachment Method: Weld-On, Bolt-On, Clamp-On, Adjustable |
| Companies Covered | Dexter Axle, BPW Group, DexKo Global, Guangdong Fuwa Engineering Group, Meritor, Hendrickson USA, SAF-HOLLAND, York Transport Equipment, JOST Werke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowmobile Trailer Axle Market Evolving Landscape
Material science advances and regulatory harmonization are compressing product development cycles. Axle manufacturers must now engineer for dual-certification markets while integrating sensor capabilities that were absent from prior generation designs.
6061-T6 aluminum extrusion is expanding into commercial touring fleets beyond its racing trailer origins. Operators in Colorado and Utah specify these assemblies to reduce tongue weight on steep mountain grades. The technology is expanding into mid-tier fleet purchases as total cost of ownership calculations incorporate fuel savings from reduced tow vehicle strain.
NHTSA trailer safety standards are tightening conspicuity and brake performance thresholds for equipment exceeding specified gross weights. Wisconsin and Minnesota regulators reference these federal benchmarks when issuing seasonal overweight permits. Commercial tour operators in the Upper Midwest now specify axles with integrated brake actuators to preempt state-level inspection failures.
Fleet procurement is consolidating around standardized tandem configurations with field-serviceable components. Owner-operators increasingly defer to commercial tour operator specifications when upgrading personal trailers. This behavioral shift concentrates design influence with fleet managers in Minnesota and Wisconsin who negotiate volume agreements with regional distributors.
Snowmobile Trailer Axle Market Segmentation
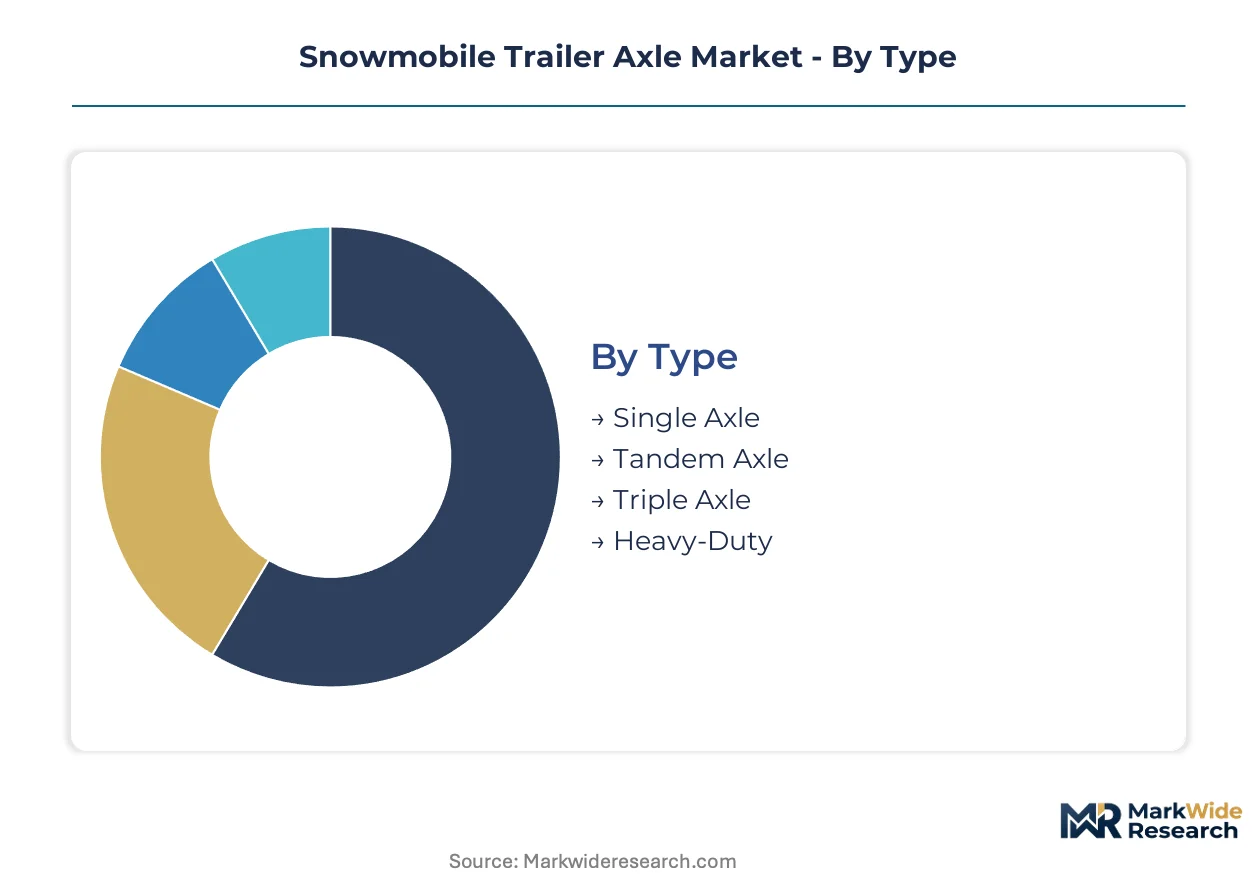
Snowmobile trailer axle procurement patterns diverge sharply between commercial fleet operators and owner-operators. Specification decisions cascade from terrain demands, seasonal weight restrictions, and serviceability requirements in remote winter environments.
Type:
Axle configuration directly determines stability margins on icy access roads and load distribution across trailer frames.
- Tandem Axle:Dual-shaft assemblies distribute torsional stress across wider wheelbases. Commercial tour operators in Wisconsin and Minnesota specify these configurations for high-frequency rental fleets operating under seasonal weight permits.
- Single Axle:Simpler rotating shaft assemblies suit lightweight personal trailers and short-haul transport. Individual owners in Colorado backcountry zones favor these for maneuverability on narrow mountain grades.
- Triple Axle:Three-shaft configurations handle extreme gross weights for multi-sled transport. Specialized expedition operators deploy these for remote lodge supply chains.
- Heavy-Duty:Reinforced spindle and bearing assemblies exceed standard load ratings. Mining support contractors in Utah specify these for equipment haul trailers.
Tandem axle leads on scale; heavy-duty leads on momentum.
Material:
Material selection trades fatigue resistance against mass reduction, with cost tiers separating racing applications from commercial durability requirements.
- Steel:Normalized SAE 1045 forged assemblies dominate fleet procurement for fatigue resistance on corrugated ice roads. Minnesota rental operators specify these grades for tandem configurations despite weight penalties.
- Aluminum:6061-T6 extrusions reduce tongue weight for steep mountain grades. Colorado and Utah touring operators are expanding adoption beyond racing origins into mid-tier commercial fleets.
- Composite:Hybrid fiber-reinforced structures combine stiffness with corrosion immunity. Experimental applications focus on salt-exposure environments.
- Fiberglass:Pultruded profiles serve niche lightweight racing trailer segments. Cost barriers limit penetration beyond premium owner-operator markets.
Steel leads on scale; aluminum leads on momentum.
Load Capacity:
Rated capacity selection follows state-level weight restriction calendars and fleet insurance requirements.
- 2000 lbs:Mid-range ratings balance single-sled transport with regulatory headroom. Wisconsin commercial operators standardize here for permit flexibility.
- 3000 lbs:Higher ratings accommodate dual-sled configurations with safety margins. Minnesota fleet managers specify these for peak-season capacity reserves.
- 1000 lbs:Entry ratings suit compact utility trailers for personal recreation. Cost-sensitive owner-operators in Michigan favor these for occasional use.
- 4000 lbs:Maximum ratings serve heavy expedition platforms and equipment haulers. Industrial applications in Alberta oilfield support drive limited demand.
2000 lbs leads on scale; 3000 lbs leads on momentum.
Attachment Method:
Installation geometry determines field-serviceability and compatibility with legacy trailer frames.
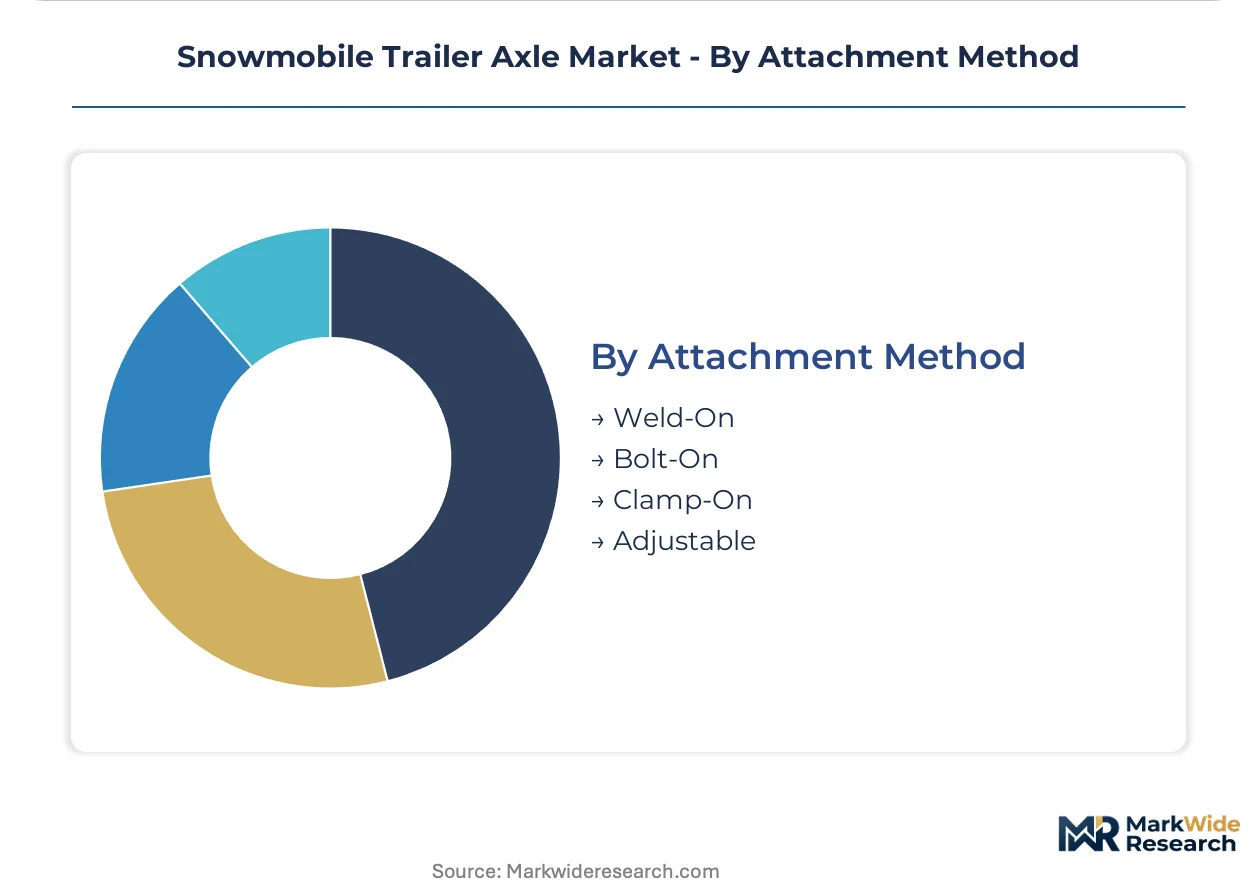
- Bolt-On:Mechanical fastening enables rapid axle replacement without welding equipment. Owner-operators prioritize this method for remote winter excursions where AWS D1.1 certified technicians are unavailable.
- Weld-On:Permanent fusion attachment delivers maximum structural integrity. OEM manufacturers specify these for new trailer production in Indiana and Georgia assembly plants.
- Clamp-On:Compression-based mounting suits temporary or retrofit applications. Rental fleets use these for seasonal capacity adjustments.
- Adjustable:Sliding track systems accommodate variable load positioning. Multi-purpose trailer owners in Montana favor these for mixed cargo configurations.
Bolt-on leads on scale; adjustable leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Upper Midwest manufacturing corridor anchors North American snowmobile trailer axle production. Wisconsin and Minnesota regulators impose seasonal weight restrictions that synchronize fleet procurement cycles. Indiana and Georgia assembly plants supply standardized tandem configurations to commercial tour operators across the northern United States and Canada.
United States
Commercial tour operators in Wisconsin and Minnesota drive fleet standardization around NHTSA Federal Motor Vehicle Safety Standard 108 compliance. State-level seasonal weight permits force synchronized upgrade cycles across rental fleets. Indiana-based forging plants and Georgia assembly facilities concentrate domestic manufacturing capacity for OEM and aftermarket channels.
Canada
Transnational tour routes spanning Ontario, Quebec, and Alberta require axle specifications meeting Transport Canada CMVSS brake performance thresholds. Canadian operators seek unified certification for cross-border fleet deployment. Quebec's recreational tourism infrastructure supports secondary distribution networks serving remote lodge supply chains.
China
Guangdong Province engineering groups manufacture forged spindle assemblies for export to North American aftermarket distributors. Chinese producers compete on cost positioning for bolt-on replacement axles. Yangtze River Delta metalworking clusters supply normalized steel billets to tier-two fabricators serving price-sensitive owner-operator segments.
Germany
BPW Group and SAF-HOLLAND leverage European engineering standards to penetrate North American premium fleet segments. German technical specifications influence brake actuator integration requirements. KBA certification protocols provide reference frameworks for dual-certification axle designs targeting transnational compliance.
Japan
Japanese steel producers supply high-grade forging stock to North American axle manufacturers under long-term supply agreements. METI-supported material science programs advance heat treatment processes for fatigue resistance. Osaka-based trading houses coordinate aluminum billet procurement for lightweight racing trailer applications.
Snowmobile Trailer Axle Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue lightweight material specialization and telematics integration. The vendor base stratifies across three capability tiers: integrated forging-to-assembly operations, component specialists, and regional fabrication shops. Strategic archetypes include domestic scale manufacturers, European premium engineering firms, and Asian cost-optimized suppliers. Competitive moves concentrate on backward integration into billet sourcing and geographic expansion into underpenetrated Rocky Mountain corridors.
Among North American integrated manufacturers, Dexter Axle represents the domestic scale archetype with captive forging and assembly operations. DexKo Global anchors aftermarket distribution reach through extensive dealer networks. BPW Group exemplifies the European premium engineering tier, applying continental brake performance standards to cross-border fleet specifications. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Dexter Axle |
| BPW Group |
| DexKo Global |
| Guangdong Fuwa Engineering Group |
| Meritor |
| Hendrickson USA |
| SAF-HOLLAND |
| York Transport Equipment |
| JOST Werke |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap forging specialists anchor North American axle production, their concentrated ownership structures enabling disciplined capacity allocation and pricing power during seasonal demand spikes in Wisconsin and Minnesota. This ownership pattern reinforces stable contract pricing for fleet purchasers while insulating premium tiers from commodity volatility in aluminum billet markets.
Pricing Analysis
Input-cost pass-through from normalized SAE 1045 steel billet and 6061-T6 aluminum extrusions governs contract negotiations between Indiana forging plants and Upper Midwest fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates BPW Group's European-engineered brake-integrated assemblies from Dexter Axle's domestic fleet specifications and Chinese-imported bolt-on replacements. Cost compression in economy-tier bolt-on segments is intensifying because Yangtze River Delta fabricators compete on spot-market billet sourcing. Owner-operators in Michigan and Colorado exhibit highest price sensitivity, while commercial tour operators in Minnesota prioritize fatigue-resistance certifications over unit cost.
Supply Chain Analysis
Domestic-content thresholds in NHTSA Federal Motor Vehicle Safety Standard 108 compliance documentation reshape sourcing toward Indiana and Georgia assembly plants for OEM channel supply. Raw material flows draw from Japanese forging-stock agreements, Guangdong spindle exports, and domestic normalized steel billet production. Single-source vulnerability concentrates at Indiana forging facilities serving both Dexter Axle and tier-two fabricators. Distribution runs through DexKo Global's dealer network for aftermarket channels and direct fleet contracts for commercial tour operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wisconsin's seasonal weight permit calendars create predictable procurement windows that lag Minnesota's by six to eight weeks, enabling inventory arbitrage across state lines for distributors with dual-state warehousing.
For Market Incumbents: Acquire captive heat-treatment capabilities to secure fatigue-resistance certification tiers against emerging composite axle entrants. Dexter Axle and BPW Group should expand Rocky Mountain distribution partnerships before Colorado backcountry operators standardize fleet specifications. Backward integration into aluminum billet sourcing insulates margin pools from aerospace demand volatility. For New Entrants and Emerging Players: Transport Canada CMVSS brake performance thresholds in Alberta and Ontario open a window for dual-certification axle designs targeting transnational tour routes. Target underpenetrated Utah expedition operators with heavy-duty triple-axle configurations for remote lodge supply chains. Telematics-integrated suspension monitoring offers a differentiated go-to-market angle for premium fleet segments. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication shops with AWS D1.1 welding certifications but limited brand recognition. Five-to-ten year viability hinges on electrification-driven axle rating recalibration for battery-heavy snowmobile architectures. Monitor NHTSA trailer safety standard revision timelines as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Sourcing | Captive supply of normalized SAE 1045 steel insulates Dexter Axle from commodity volatility. |
| Dual-Certification Axle Development | NHTSA and Transport Canada CMVSS alignment enables BPW Group's cross-border fleet penetration. |
| Telematics-Integrated Suspension Launch | IoT sensor convergence addresses predictive maintenance demand from Minnesota commercial operators. |
| Rocky Mountain Distribution Expansion | Colorado and Utah partnerships capture fleet standardization decisions before competitor lock-in. |
| Composite Material R&D Investment | Hybrid fiber-reinforced structures target salt-exposure environments in Michigan and Ontario. |
Research Methodology
Bottom-up snowmobile trailer procurement modeling reconciled against top-down forging capacity tracking forms the analytical core of this study. Primary interviews with fleet procurement managers at Wisconsin and Minnesota commercial tour operators, aftermarket distribution heads at DexKo Global dealer networks, and plant engineers at Indiana forging facilities combined with secondary validation against NHTSA compliance filings, state transportation department permit data, and SEC disclosures from publicly traded axle manufacturers. Trade flow analysis of Japanese steel billet imports and Chinese spindle exports triangulated domestic production estimates.
Historical trendline analysis of seasonal weight restriction calendars and fleet replacement cycles established baseline demand patterns across the projection horizon. Segmentation dimensions modeled include axle configuration type, material grade, load capacity tier, and attachment method, with geographic regulatory cluster as an industry-specific overlay. CAGRs derived from regression analysis of fleet capacity expansion announcements and backcountry tourism infrastructure investments. Electrification-driven axle rating recalibration and aluminum extrusion cost trajectories served as key forecast inputs.
Revisions become necessary when NHTSA trailer safety standard amendments, Transport Canada CMVSS threshold adjustments, or snowmobile powertrain electrification timelines materialize differently than baseline assumptions. Forecasts reflect documented assumptions regarding seasonal permit window stability and fleet consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Caravanning Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Teardrop Trailer Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Fifth Wheel Trailer Market
Recreational Vehicles
US Low Speed Vehicle Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Europe Recreational Vehicle Market