
 Water Utility Services Market | 2026-2036
Water Utility Services Market Size, Share, and Industry Trends Forecast 2026-2036
Water Utility Services Market Outlook
Certified water systems engineering talent is collapsing across North America and Western Europe, creating project backlogs that extend utility commissioning timelines by months. Veolia Environnement SA leverages its integrated design-build-operate model to capture complex municipal contracts that competitors cannot staff. American Water Works Company Inc. anchors its growth in regulated rate-base expansion across US states with aging lead service line inventories. Suez SA competes through specialized membrane filtration expertise in industrial water reuse segments where technical complexity deters generalist operators.
Water utility services encompass the treatment, conveyance, and reclamation of potable and non-potable water through physical, chemical, and biological processes operating at flows from thousands to billions of gallons annually, serving residential, commercial, and industrial end users under continuous regulatory oversight. Water treatment and wastewater management segments dominate revenue pools due to their recurring operational nature and capital-intensive infrastructure replacement cycles, while desalination represents the fastest-growing service type as coastal municipalities confront saltwater intrusion and freshwater depletion. Membrane filtration technology leads capital deployment in new plant construction, though biological treatment retains margin strength in industrial applications with complex organic load profiles.
The US EPA enforces the Safe Drinking Water Act and Lead and Copper Rule revisions that mandate lead service line replacement, directly accelerating capital expenditure across American Water Works Company Inc.'s regulated territories. The EU Water Framework Directive and Urban Wastewater Treatment Directive establish discharge quality benchmarks that Thames Water Utilities Limited and United Utilities Group PLC must meet through continuous infrastructure investment. Stakeholders must monitor how climate resilience mandates reshape utility capital allocation between centralized treatment expansion and distributed reuse networks.
Market Dynamics
The US EPA's Lead and Copper Rule revisions are compressing infrastructure replacement timelines across American utilities, forcing simultaneous capital deployment into lead service line removal, advanced treatment upgrades, and climate-resilient distribution networks. This regulatory pressure is reshaping competitive positioning toward operators with integrated design-build capabilities.
Growth Catalysts
- Membrane filtration advancement:Reverse osmosis and ultrafiltration systems are enabling direct potable reuse in water-stressed municipalities. California's urban water recycling mandates accelerate deployment.
- EU Urban Wastewater Treatment Directive:Stricter nutrient removal requirements are forcing infrastructure investment across German, French, and Dutch utilities. Biological nutrient removal retrofits dominate capital planning.
- Industrial water stress:Semiconductor fabrication and data center cooling in Arizona, Texas, and Taiwan are driving reclaimed water offtake agreements. Contract structures now prioritize guaranteed supply over spot pricing.
Market Restraints
- Specialized engineering talent scarcity:Certified water systems engineers in North America and Western Europe command premium compensation. Project commissioning delays extend 4-8 months.
- Polymer and chemical input volatility:Coagulants, flocculants, and membrane materials face petrochemical price swings. Margin compression hits operators without long-term supply contracts.
- Permitting complexity under NEPA:US environmental review timelines for new intake structures and discharge points stretch 3-5 years. Smaller utilities abandon expansion plans.
Strategic Opportunities
- Australia's urban corridors:Sydney, Melbourne, and Perth water recycling networks remain underdeveloped relative to policy targets. Integrated water management contracts offer entry points.
- Digital twin convergence:SCADA integration with predictive analytics is reducing non-revenue water losses. Singapore's PUB provides the reference deployment model.
- US IIJA funding windows:Infrastructure Investment and Jobs Act allocations for lead service line replacement create design-build-operate opportunities through 2026.
Industry Challenges
- Cybersecurity certification gaps:Water sector critical infrastructure designation under US CISA rules demands OT/IT segmentation expertise. Utilities lack in-house capability.
- Legacy asset integration:Century-old cast-iron distribution networks resist smart sensor deployment. Retrofit costs exceed greenfield installation by 40-60%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Utility Services Market |
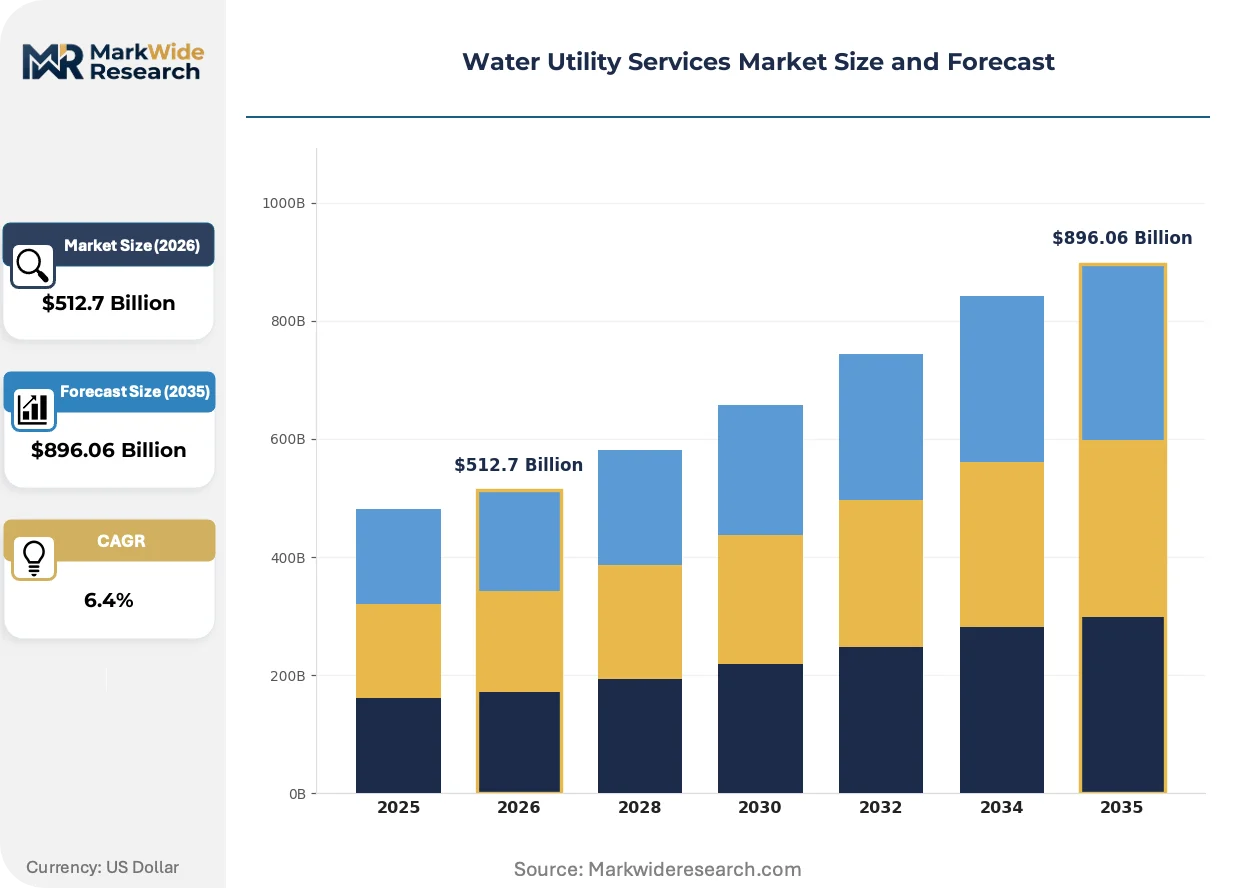
| Market Size in 2026 | $512.7 Billion |
| Market Size in 2035 | $896.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Water Treatment, Water Supply, Wastewater Management, Desalination Technology: Membrane Filtration, Reverse Osmosis, Chemical Treatment, Biological Treatment End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Veolia Environnement SA, Suez SA, American Water Works Company Inc., Aqua America Inc., United Utilities Group PLC, Severn Trent PLC, Thames Water Utilities Limited, California Water Service Group, Essential Utilities Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Utility Services Market Strategic Shifts
Digital instrumentation and advanced oxidation processes are displacing conventional treatment trains, while regulatory mandates for contaminant monitoring are expanding the analytical services layer. Competitive advantage is concentrating with operators who control both physical infrastructure and data platforms.
Advanced oxidation processes combining ozone, UV, and hydrogen peroxide are achieving pharmaceutical and personal care product removal below detection limits. Municipal utilities in Colorado, Switzerland, and South Korea are adopting these trains for indirect potable reuse. The technology is bifurcating the treatment market into basic disinfection providers and advanced contaminant destruction specialists.
The US EPA's Fifth Contaminant Candidate List and proposed PFAS maximum contaminant levels are forcing granular activated carbon and ion exchange upgrades. Industrial pretreatment programs in Michigan, North Carolina, and the Netherlands now require PFAS source tracking. Facilities without analytical capabilities face consent decree exposure.
Performance-based operating contracts are displacing traditional unit-rate agreements for wastewater treatment services. French and British water companies now guarantee effluent quality outcomes rather than process inputs. Australian utilities lead in adopting these structures for desalination and water recycling assets.
Water Utility Services Market Segmentation
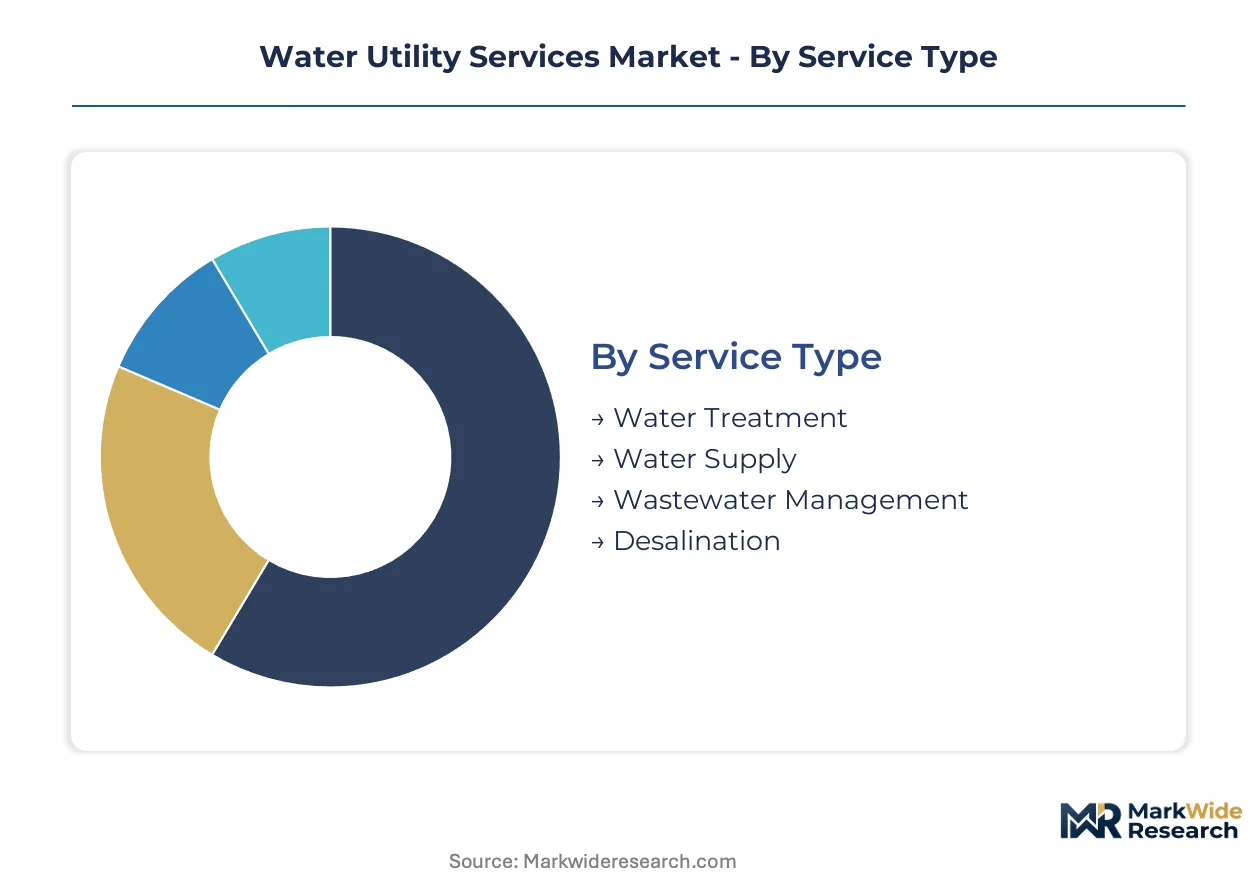
Segmentation in water utility services reveals how regulatory pressure, technology maturity, and customer concentration reshape capital allocation and margin structures across distinct operational categories.
Service Type:
Regulatory differentiation separates recurring operational revenue from project-based capital deployment, with compliance mandates dictating investment priority across service portfolios.
- Water Treatment:Physical, chemical, and biological processes render source water potable through coagulation, sedimentation, filtration, and disinfection stages. Municipal utilities in the US, Germany, and Australia concentrate procurement here as EPA, EU Urban Wastewater Treatment Directive, and TGA standards tighten contaminant thresholds.
- Wastewater Management:Collection, conveyance, and tertiary treatment of sewage and industrial effluent operates under continuous discharge permits. Biological nutrient removal retrofits dominate capital planning in Dutch and French utilities facing EU directive compliance deadlines.
- Water Supply:Distribution network operation and non-revenue water reduction through pressure management and leak detection. Legacy cast-iron infrastructure in older US and UK cities limits smart sensor deployment economics.
- Desalination:Seawater and brackish water reverse osmosis serving coastal municipalities confronting saltwater intrusion. This segment climbs the fastest as Perth, Singapore, and California utilities expand capacity.
Established volume favors Water Treatment; emerging adoption favors Desalination.
Technology:
Cost tier separation distinguishes premium membrane systems from conventional chemical and biological alternatives, with complexity premiums widening at the high end.
- Membrane Filtration:Ultrafiltration and microfiltration barriers remove particulates, pathogens, and colloids without chemical dependency. Industrial water reuse contracts in Arizona and Taiwan specify membrane performance guarantees over spot pricing.
- Reverse Osmosis:Semi-permeable membranes achieve dissolved solids and contaminant rejection for potable and industrial-grade water production. California's urban water recycling mandates accelerate municipal deployment alongside semiconductor fabrication demand.
- Chemical Treatment:Coagulation, flocculation, and disinfection using aluminum salts, polymers, and chlorine-based oxidants. Petrochemical price volatility compresses margins for operators lacking long-term supply contracts.
- Biological Treatment:Activated sludge and fixed-film processes degrade organic loads in municipal and industrial applications. Margin strength persists in food and beverage, pulp and paper, and pharmaceutical effluent where organic complexity deters generalist operators.
Capital intensity peaks with Reverse Osmosis; operational margin stability concentrates in Biological Treatment.
End User:
Application-driven segmentation maps infrastructure scale against regulatory exposure, with industrial users commanding customized treatment trains and performance guarantees.
- Industrial:Semiconductor fabrication, data center cooling, and process water for pharmaceuticals and chemicals. Arizona and Texas facilities now structure reclaimed water offtake agreements around guaranteed supply volumes rather than spot market exposure.
- Residential:Single-family and multi-unit dwelling consumption through metered municipal connections. Lead service line replacement mandates across Michigan, Wisconsin, and Illinois utilities accelerate infrastructure capital deployment.
- Commercial:Office complexes, retail, hospitality, and institutional facilities with variable demand profiles and pretreatment obligations. PFAS source tracking requirements in North Carolina and the Netherlands reshape compliance costs.
- Agricultural:Irrigation and livestock operations drawing from surface water, groundwater, and reclaimed sources. Water stress in Australia's Murray-Darling Basin and California's Central Valley intensifies allocation conflicts.
Revenue concentration aligns with Industrial contracts; regulatory exposure concentrates in Residential infrastructure.
Distribution Channel:
Customer type and procurement scale determine channel economics, with direct engagement dominating capital-intensive utility contracts and retail serving fragmented small-user markets.
- Direct Sales:Design-build-operate contracts between utilities and integrated service providers. Veolia and Suez capture municipal and industrial accounts through long-term concession and availability-based agreements.
- Wholesale:Bulk water and treated effluent transfers between utilities and large industrial offtakers. Singapore's PUB supplies semiconductor parks through dedicated industrial water agreements.
- Retail:Metered residential and small commercial service through utility billing systems. Rate-base regulation in US states governs revenue recovery and return on equity.
- Online:Digital procurement platforms for chemicals, consumables, and analytical services. Adoption concentrates in chemical and membrane replacement logistics rather than core infrastructure.
Contract value concentrates through Direct Sales; transaction frequency peaks in Retail billing systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water utility services consumption patterns diverge sharply by geography: coastal municipalities prioritize desalination and reuse infrastructure, while inland industrial corridors concentrate on treatment capacity expansion for manufacturing clusters.
United States
The US EPA's Lead and Copper Rule revisions mandate lead service line replacement across Michigan, Wisconsin, and Illinois, accelerating capital deployment into aging residential distribution networks. Industrial water stress in Arizona and Texas semiconductor corridors drives reclaimed water offtake agreements with guaranteed supply structures. California's urban water recycling mandates push membrane filtration deployment in Los Angeles and San Diego metropolitan areas.
Germany
Biological nutrient removal retrofits dominate capital planning as utilities confront EU Urban Wastewater Treatment Directive compliance deadlines. The Ruhr industrial basin and Rhine corridor concentrate wastewater treatment upgrades for chemical and pharmaceutical effluent. German utilities lead performance-based operating contract adoption, guaranteeing effluent quality outcomes rather than process inputs.
Australia
Sydney, Melbourne, and Perth water recycling networks remain underdeveloped relative to federal policy targets, creating integrated water management contract opportunities. The Murray-Darling Basin intensifies allocation conflicts between agricultural irrigation and urban supply. Western Australia's Perth-Peel corridor expands desalination capacity to address chronic freshwater depletion and saltwater intrusion.
United Kingdom
Thames Water Utilities Limited and United Utilities Group PLC face continuous infrastructure investment requirements under EU Water Framework Directive discharge quality benchmarks. London's century-old cast-iron distribution networks resist smart sensor deployment, with retrofit costs exceeding greenfield installation substantially. The UK's performance-based contract structures for wastewater treatment now guarantee environmental outcomes.
Singapore
PUB's reference deployment model for digital twin convergence—integrating SCADA with predictive analytics—reduces non-revenue water losses and attracts technology transfer interest. The Tuas desalination complex and NEWater facilities anchor the city-state's circular water economy. Semiconductor parks in the western industrial corridor operate under dedicated industrial water agreements with guaranteed supply volumes.
Water Utility Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in water utility services, with design-build-operate capabilities separating the top stratum from equipment-only vendors. The market structure favors operators controlling both physical infrastructure and data platforms, as regulatory complexity and talent scarcity raise barriers to full-service delivery. Two archetypes dominate: integrated multinational concessionaires and regional rate-base utilities with regulated territory exclusivity. Competitive moves concentrate on strategic partnerships for technology access and geographic expansion through concession bidding.
Within the integrated multinational tier, Veolia Environnement SA and Suez SA exemplify the design-build-operate model that captures complex municipal contracts competitors cannot staff. American Water Works Company Inc. anchors the regulated rate-base archetype, expanding across US states with aging lead service line inventories where EPA mandates accelerate infrastructure replacement cycles. These three occupy positions reflecting divergent strategic foundations: European concession expertise versus American regulatory rate-base growth.
| Leading Market Players |
|---|
| Veolia Environnement SA |
| Suez SA |
| American Water Works Company Inc. |
| Aqua America Inc. |
| United Utilities Group PLC |
| Severn Trent PLC |
| Thames Water Utilities Limited |
| California Water Service Group |
| Essential Utilities Inc. |
| Others |
Value Chain & Pricing Dynamics
US EPA Lead and Copper Rule revisions gate both membrane filtration supplier qualification and municipal procurement price tiers simultaneously, compressing timelines for utilities that must replace lead service lines while upgrading treatment trains. This regulatory scaffolding forces buyers toward integrated operators who bundle design-build capabilities with long-term performance guarantees, widening spreads between certified and uncertified vendors.
Pricing Analysis
Long-term offtake agreements now dominate industrial water procurement in Arizona and Texas semiconductor corridors, displacing spot-market exposure as fabs prioritize supply certainty over unit cost optimization. Price differentiation hinges on guaranteed volume commitments and membrane performance certifications, with municipal utilities least sensitive to per-unit rates due to regulated cost recovery mechanisms. Cost compression in chemical treatment tiers is intensifying because petrochemical feedstock volatility erodes margins for operators lacking multi-year polymer supply contracts. Industrial offtakers exhibit highest price sensitivity, negotiating reclaimed water agreements around total cost of ownership rather than headline tariffs.
Supply Chain Analysis
China, Japan, and South Korea anchor global production of reverse osmosis membranes and ultrafiltration modules, concentrating specialized polymer manufacturing expertise in East Asian chemical corridors. The supply chain draws from petrochemical feedstocks for membrane substrates, rare earth elements for specialized coatings, and precision manufacturing equipment for module assembly. Single-source vulnerability runs through Japanese suppliers of high-rejection seawater desalination membranes, where geopolitical friction or shipping disruption would constrain capacity expansion in Perth, Singapore, and California. Distribution runs through direct manufacturer-to-utility contracts for large capital projects, with regional distributors handling consumables and replacement logistics for smaller municipal accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: concession agreements and rate-base exclusivity create switching costs that lock in multi-decade revenue streams once infrastructure is embedded.
For Market Incumbents: Shield rate-base expansion in Michigan, Wisconsin, and Illinois by accelerating lead service line replacement programs ahead of EPA enforcement deadlines, capturing infrastructure investment cycles that smaller competitors cannot finance. Deepen backward integration into membrane manufacturing or digital twin analytics platforms to defend margin position against specialized technology vendors who threaten to disaggregate the integrated service stack.
For New Entrants and Emerging Players: Lead with Australia's underdeveloped urban water recycling corridors in Sydney, Melbourne, and Perth, where federal policy targets outpace incumbent capacity deployment and integrated water management contracts remain contested. Target semiconductor fabrication and data center cooling segments in Arizona and Texas with reclaimed water offtake structures built around guaranteed supply volumes rather than commodity spot exposure, leveraging performance-based contracting as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: US EPA PFAS maximum contaminant level finalization reshapes the acquisition landscape toward operators with granular activated carbon and ion exchange upgrade capabilities, as consent decree exposure concentrates value in compliant infrastructure platforms. Favor regulated rate-base utilities and design-build-operate concessionaires with embedded territorial exclusivity over equipment-only vendors lacking operational revenue streams. Monitor EPA enforcement action intensity in Michigan and North Carolina as the signal indicating whether capital deployment timelines compress or extend across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead Service Line Replacement Program | EPA mandate acceleration in Michigan, Wisconsin, and Illinois locks in decade-long capital deployment cycles for integrated operators. |
| Membrane Technology Partnership | Collaboration with Japanese or South Korean suppliers secures supply certainty for desalination expansion in Perth and California coastal zones. |
| Digital Twin Platform Deployment | SCADA-predictive analytics integration following Singapore PUB model reduces non-revenue water losses in aging distribution networks. |
| Reclaimed Water Offtake Agreement | Guaranteed supply structures with Arizona and Texas semiconductor fabs displace spot-market exposure with predictable revenue streams. |
| Performance-Based Operating Contract | Outcome guarantees for effluent quality in German and Dutch utilities align operator incentives with EU directive compliance deadlines. |
Study Parameters
Operator-level perspectives from municipal utility planning officers, membrane technology procurement leads, industrial water managers at semiconductor fabs, and regulatory compliance directors anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement databases, EU Urban Wastewater Treatment Directive compliance filings, state utility commission rate-case dockets, and desalination project development trackers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to ensure consistency across volume and value outputs.
Sensitivity analysis frameworks tested forecast robustness across regulatory enforcement intensity scenarios, petrochemical price volatility bands, and engineering talent availability assumptions throughout the projection horizon. The analytical framework segmented by service type, technology tier, end-user application, and regional regulatory cluster, with CAGRs derived from infrastructure replacement cycle timing and policy mandate implementation schedules. Modeled inputs included lead service line inventory data, membrane capacity expansion pipelines, and industrial water stress indices for semiconductor corridor regions.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement pressure, stable petrochemical feedstock pricing, or uninterrupted membrane supply chains would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure investment continuity. Recalibration cycles align with material shifts in EPA rulemaking, EU directive revision schedules, or breakthrough membrane technology commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Water Free Urinals Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Water Filters Market
Water Management
Water Trading Market
Water Management
Global Water Market
Water Management
Mexico Water Consumption Market
Water Management
Municipal Water Market
Water Management
Chile Water Consumption Market
Water Management
Smart Water Management Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
North America Water Sink Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Spain Water Consumption Market
Water Management
NRW Smart Leak Management Market
Water Management
Smart Water Network Market
Water Management
France Water Consumption Market