
 France Water Consumption Market | 2026-2036
France Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
France Water Consumption Market Insights
Aftermarket service revenue in water utility infrastructure is reshaping margin distribution across the France Water Consumption Market. Veolia Environnement SA leverages its nationwide network of treatment facilities and service contracts to sustain recurring income streams. Suez SA anchors its position through specialized industrial water processing capabilities. Saur SAS competes aggressively in municipal outsourcing, where long-term operational contracts generate predictable cash flows.
France water consumption encompasses the extraction, treatment, distribution, and end-use of water resources across residential, commercial, industrial, and agricultural applications, with treatment facilities typically achieving potable standards through coagulation, filtration, and disinfection processes delivering water at 0.1 to 0.3 megapascals in municipal networks. Surface water and groundwater together dominate the Water Source segment, though recycled water represents the fastest-growing category as industrial users seek to reduce freshwater withdrawals under tightening environmental permits. The Residential end user segment remains the largest volume pool, while Industrial Processing under Usage Type commands premium pricing due to specialized purity requirements and regulatory compliance costs.
France's water sector operates under the EU Water Framework Directive, national implementation through the Ministry of Ecological Transition, and local oversight by basin agencies such as Agence de l'Eau, which collectively enforce abstraction limits, quality standards, and reuse targets that directly shape infrastructure investment priorities. ANSM and regional health agencies monitor potable water compliance, creating certification barriers for new market entrants. Stakeholders must monitor evolving reuse regulations and basin-level allocation restrictions that will determine competitive positioning in constrained supply zones.
Market Dynamics
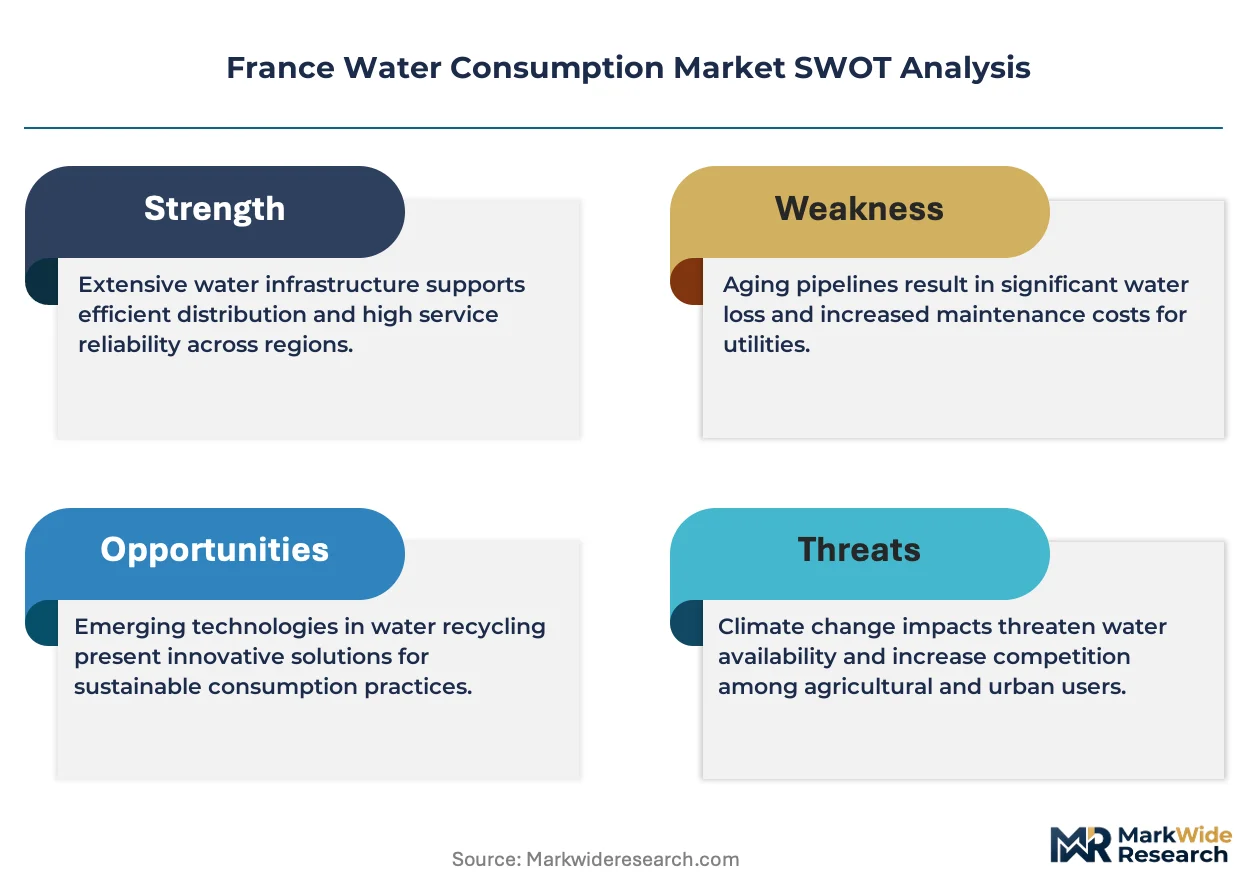
The EU Water Framework Directive's tightening abstraction limits are forcing agricultural and industrial users toward recycled water infrastructure, compressing traditional freshwater distribution economics across France's basin agencies.
Growth Catalysts
- Agence de l'Eau allocation reforms:Basin-level water pricing mechanisms incentivize efficiency investments in drought-prone zones like Occitanie, accelerating metered irrigation adoption.
- Membrane bioreactor diffusion:Industrial food processors deploy advanced filtration to meet discharge permits, creating captive recycled water loops that reduce freshwater intake.
- Occitanie agricultural concentration:Intensive vineyard and orchard operations in this region drive demand for precision irrigation systems with soil-moisture feedback controls.
Market Restraints
- Energy cost volatility:Pumping and treatment operations face margin pressure from electricity price swings, particularly affecting small municipal operators without long-term supply contracts.
- Aquifer depletion physics:Groundwater table decline in the Rhône-Méditerranée basin imposes hard extraction ceilings that cannot be engineered around regardless of capital deployment.
- Reuse permit timelines:ANSM and regional health agency certification processes for non-potable recycled water applications extend project commissioning by 18-24 months.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur tourism infrastructure:Hotel and resort clusters seek decentralized treatment systems to reduce municipal network dependence during peak seasonal demand.
- EU Green Deal water efficiency mandates:Industrial facility retrofit requirements create turnkey service contracts combining hardware installation with decade-long operational management.
- Smart meter convergence:Integration of ultrasonic flow sensors with cloud analytics platforms enables real-time leak detection and dynamic pricing pilots in urban networks.
Industry Challenges
- SCADA cybersecurity retrofitting:Legacy treatment plant control systems require costly hardening against ransomware threats, straining municipal capex cycles already compressed by tariff politics.
- Membrane fouling expertise:Specialized technicians for ceramic and polymeric filter maintenance remain scarce outside Paris and Lyon metropolitan zones, limiting rural deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Water Consumption Market |
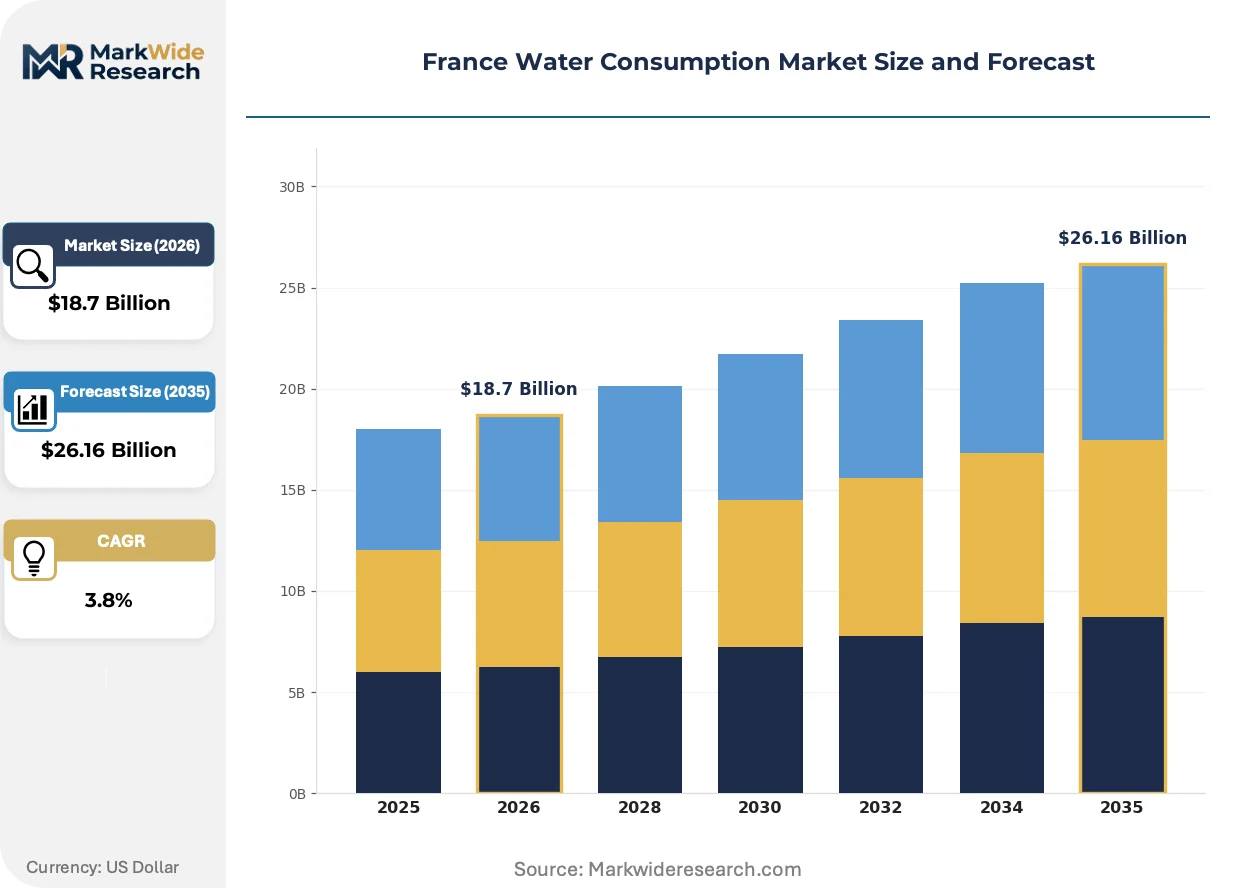
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Residential, Commercial, Industrial, Agriculture Water Source: Surface Water, Groundwater, Recycled Water, Desalinated Water Distribution Channel: Direct Supply, Retail Outlets, Distributors, Online Platforms Usage Type: Potable, Irrigation, Industrial Processing, Recreational |
| Companies Covered | Danone SA, Equinix Inc., Veolia Environnement SA, CyrusOne Inc., Digital Realty Trust Inc., Suez SA, Nestle SA, Microsoft Corporation, Saur SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Water Consumption Market Trends and Innovations
Digital water management platforms are collapsing information asymmetries between utilities and end-users, enabling demand-response programs that reshape consumption patterns in real time rather than through static tariff structures.
Membrane distillation systems are collapsing the cost gap between brackish water treatment and advanced reuse applications. Agricultural cooperatives in Languedoc-Roussillon pilot these units for nutrient recovery from livestock effluent. The technology is collapsing conventional activated sludge economics for high-strength organic waste streams.
France's ecological transition ministry enforces progressive water reuse targets through basin-specific decrees under the EU Water Framework Directive. Industrial discharge permits now mandate minimum recycled water ratios for sectors above defined consumption thresholds. Chemical manufacturers in the Lyon corridor respond by consolidating treatment assets into shared infrastructure hubs.
After-sales service unbundling is fragmenting traditional utility contracts. Large industrial water users now procure treatment hardware, chemicals, and technical support from separate vendors rather than single-source operators. This pattern concentrates in the Hauts-de-France manufacturing belt where automotive and metallurgical plants negotiate component-level service level agreements.
France Water Consumption Market Segmentation
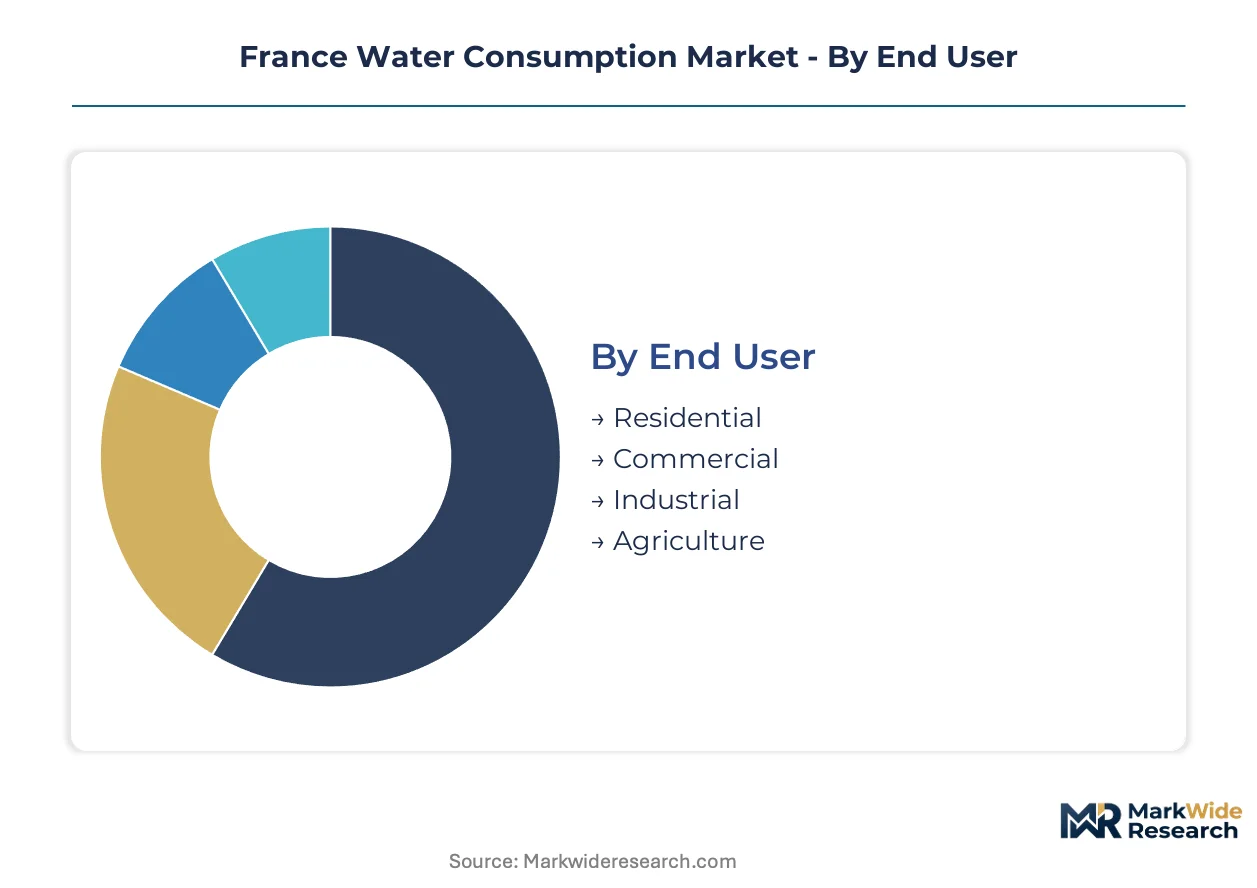
Segmentation in the France Water Consumption Market reveals how regulatory pressure and resource scarcity reshape procurement patterns across distinct user profiles. Basin-level allocation reforms and reuse mandates fragment demand into specialized supply channels with divergent technical requirements.
End User:
Cycle times vary dramatically across end user segments, with agricultural irrigation turning over equipment fastest due to seasonal intensity, while municipal residential contracts lock in decade-long operational terms.
- Residential:Municipal networks deliver treated water to households through pressure-regulated distribution at 0.1 to 0.3 megapascals. Demand concentrates in urban clusters around Paris, Lyon, and Marseille where tariff structures and leakage reduction targets drive smart meter adoption.
- Agriculture:Vineyard and orchard operators in Occitanie deploy precision irrigation with soil-moisture feedback controls. Recurring drought cycles and Agence de l'Eau abstraction limits accelerate replacement of flood systems with drip infrastructure.
- Commercial:Hotel and resort clusters in Provence-Alpes-Côte d'Azur seek decentralized treatment to reduce peak-season network dependence.
- Industrial:Chemical and food processors in the Lyon corridor consolidate treatment assets into shared infrastructure hubs under tightening discharge permits.
Residential anchors the volume base while Agriculture gains share at the steepest rate.
Water Source:
Cost tiers separate these segments, with surface and groundwater extraction representing legacy infrastructure investments, while recycled and desalinated sources command premium capital deployment for advanced treatment.
- Surface Water:Rivers and reservoirs supply treatment plants through conventional intake structures requiring seasonal turbidity management. Rhône basin facilities face algal bloom intensity that drives coagulant chemical consumption.
- Recycled Water:Membrane bioreactor and distillation systems enable industrial food processors to meet minimum recycled water ratios mandated in discharge permits. Languedoc-Roussillon agricultural cooperatives pilot nutrient recovery from livestock effluent.
- Groundwater:Aquifer extraction in the Rhône-Méditerranée basin faces hard ceilings from table decline physics regardless of capital deployment.
- Desalinated Water:Mediterranean coastal plants serve island and coastal industrial zones with reverse osmosis infrastructure.
Surface Water anchors the volume base while Recycled Water climbs the fastest under regulatory compression.
Distribution Channel:
Customer type determines channel selection, with large industrial and agricultural buyers negotiating direct supply contracts while fragmented residential and small commercial users route through intermediaries.
- Direct Supply:Municipal utilities and large industrial offtakers contract directly with treatment operators for volume-guaranteed pipeline delivery. Veolia and Suez sustain recurring revenue through long-term operational contracts with basin agencies.
- Distributors:Agricultural equipment dealers in Occitanie stock precision irrigation hardware with bundled technical support for cooperative buyers.
- Retail Outlets:Bottled water and treatment chemicals reach residential consumers through supermarket and specialty store networks.
- Online Platforms:Smart meter components and filtration consumables migrate to digital procurement channels among tech-adopter segments.
Direct Supply captures the revenue concentration while Online Platforms expand most quickly in component categories.
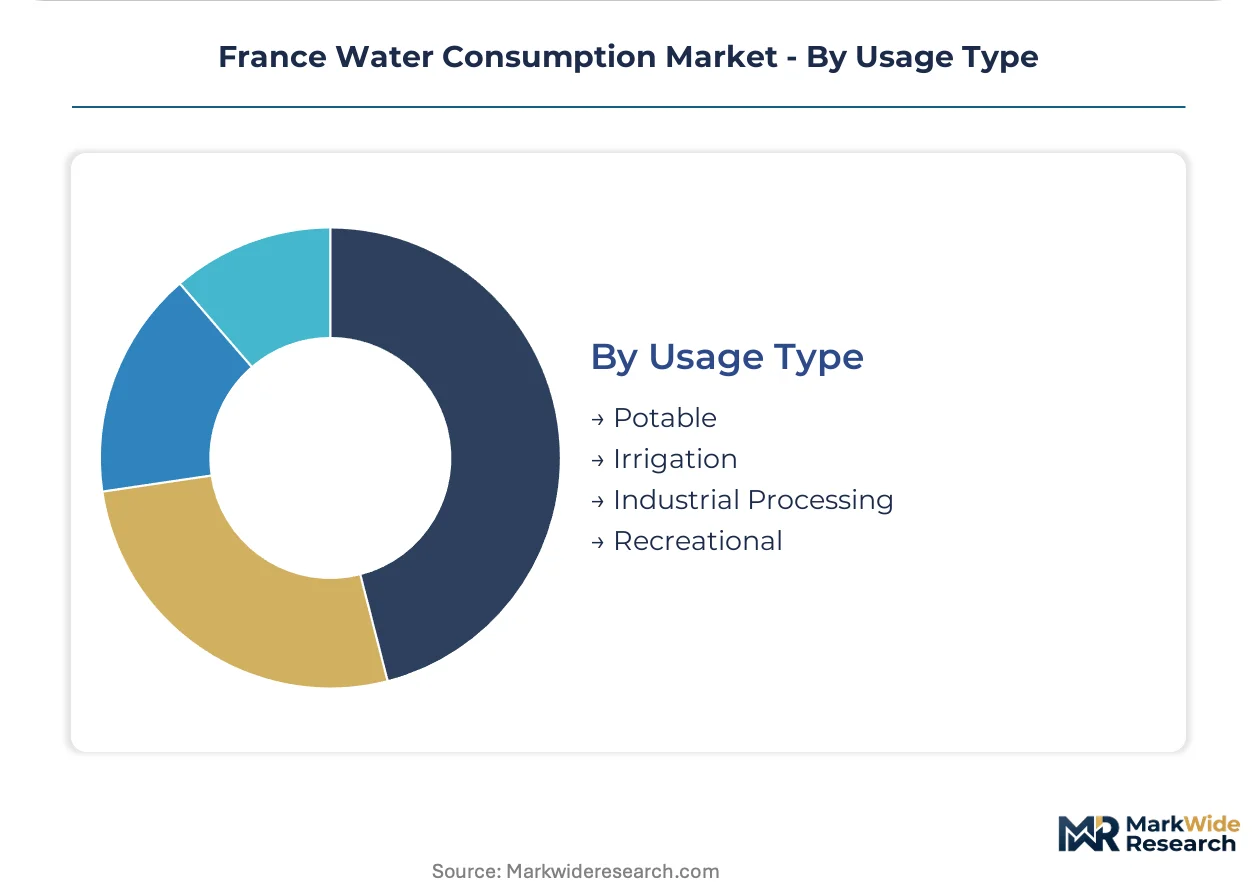
Usage Type:
Maturity gradients separate these applications, with potable supply representing century-old infrastructure, while industrial processing and recreational uses adopt advanced treatment technologies fastest.
- Potable:Coagulation, filtration, and disinfection processes achieve compliance with ANSM and regional health agency standards. Network operators face SCADA cybersecurity retrofitting costs against ransomware threats.
- Industrial Processing:Specialized purity requirements for semiconductor and pharmaceutical manufacturing command premium pricing. Membrane fouling expertise scarcity outside Paris and Lyon limits rural deployment velocity.
- Irrigation:Metered systems with ultrasonic flow sensors enable real-time leak detection and dynamic pricing pilots in basin agency territories.
- Recreational:Golf courses and municipal pools in water-stressed zones deploy closed-loop treatment to maintain access under allocation restrictions.
Potable anchors the volume base while Industrial Processing captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across French sub-regions diverge sharply. Agricultural irrigation dominates water withdrawals in Occitanie and Provence-Alpes-Côte d'Azur, while industrial processing concentrates in Auvergne-Rhône-Alpes and Hauts-de-France.
Occitanie
Vineyard and orchard operations drive intensive irrigation demand across Languedoc-Roussillon. Agence de l'Eau abstraction limits tighten each drought cycle, forcing cooperative buyers toward metered drip systems. Montpellier-Toulouse corridor treatment operators report accelerating membrane bioreactor inquiries from food processors.
Provence-Alpes-Côte d'Azur
Tourism infrastructure creates seasonal demand spikes that strain municipal networks. The ecological transition ministry's basin-specific reuse decrees push hotel clusters toward decentralized treatment. Nice-Cannes resort operators pilot closed-loop systems to maintain access during allocation restrictions.
Auvergne-Rhône-Alpes
Chemical and pharmaceutical manufacturing commands specialized purity requirements. ANSM discharge permit mandates minimum recycled water ratios above defined consumption thresholds. Lyon corridor facilities consolidate treatment assets into shared infrastructure hubs under tightening environmental compliance.
Hauts-de-France
Automotive and metallurgical plants negotiate component-level service agreements rather than single-source utility contracts. After-sales service unbundling fragments traditional operational arrangements. Lille manufacturing belt procurement patterns favor separate vendors for hardware, chemicals, and technical support.
Île-de-France
Municipal residential networks deliver the largest volume base through pressure-regulated distribution. Paris metropolitan tariff structures and leakage reduction targets accelerate smart meter adoption. SCADA cybersecurity retrofitting costs strain municipal capex cycles already compressed by political pressure on water tariffs.
France Water Consumption Market Competitive Landscape
Capability concentration sits with specialized treatment technology providers; scale advantage sits with nationwide network operators holding long-term municipal contracts. The market structure tiers between integrated utility-service hybrids and component specialists. Two strategic archetypes dominate: operational contractors securing decade-long basin agency agreements, and technology vendors supplying membrane filtration hardware. Competitive moves center on service contract unbundling and shared infrastructure consolidation.
Within the integrated utility tier, Veolia Environnement SA and Suez SA occupy positions sustained by recurring operational revenue streams. Saur SAS exemplifies the municipal outsourcing specialist archetype. These three anchors demonstrate how long-term basin agency relationships generate predictable cash flows distinct from equipment sales cycles.
| Leading Market Players |
|---|
| Danone SA |
| Equinix Inc. |
| Veolia Environnement SA |
| CyrusOne Inc. |
| Digital Realty Trust Inc. |
| Suez SA |
| Nestle SA |
| Microsoft Corporation |
| Saur SAS |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in the Rhône-Méditerranée basin's groundwater extraction infrastructure drives supplier consolidation toward long-term operational contracts and compresses spot-market flexibility for agricultural offtakers facing Agence de l'Eau allocation ceilings.
Pricing Analysis
Long-term offtake contracts dominate the France Water Consumption Market, with basin agencies locking in decade-long operational agreements that insulate Veolia and Suez from spot-price volatility. Price differentiation rests on certification grade for potable versus industrial reuse streams and volume scale for municipal versus agricultural buyers. Cost compression in membrane filtration hardware is intensifying because Chinese and South Korean equipment vendors are penetrating the European market. Small municipal operators exhibit the highest price sensitivity due to political pressure on water tariffs, while semiconductor and pharmaceutical manufacturers show the least sensitivity given specialized purity requirements.
Supply Chain Analysis
Contract-manufacturing concentration for membrane filtration modules sits with Toray Industries, LG Chem, and Suez's own production facilities in France and Spain. Geographic supply concentration centers on Germany for precision pumping equipment, Italy for ceramic filter substrates, and China for polymeric membrane materials. Raw material dependencies include polyethersulfone resins, titanium dioxide coatings, and specialized pump alloys. Single-source vulnerability runs through the Rhône basin's coagulant chemical supply chain, where algal bloom intensity strains seasonal inventory buffers. Distribution runs through direct pipeline delivery for municipal utilities and agricultural equipment dealer networks for precision irrigation hardware in Occitanie.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Water Consumption Market operates as a substitution defense against decentralized rainwater harvesting and on-site treatment systems that industrial users increasingly deploy to bypass municipal network dependence and allocation restrictions.
For Market Incumbents: Harden recurring revenue streams by extending service contract durations with basin agencies and embedding cybersecurity retrofit capabilities into SCADA modernization offerings. The ransomware threat to legacy treatment plant control systems demands proactive positioning. Backward integration into membrane module production reduces exposure to Asian supply chain volatility for critical filtration components. For New Entrants and Emerging Players: Pursue white-space opportunities in smart meter analytics platforms for municipal leak detection and dynamic pricing pilots, where ultrasonic flow sensor integration with cloud infrastructure remains underdeveloped outside Paris and Lyon. The Provence-Alpes-Côte d'Azur tourism corridor offers the most penetrable segment for decentralized treatment systems serving hotel clusters. A direct-to-utility SaaS go-to-market angle bypasses capital-intensive infrastructure buildout requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane bioreactor and distillation system manufacturing as industrial reuse mandates tighten, favoring asset-light technology licensors over integrated equipment builders. Long-term viability over the next decade hinges on positioning within the EU Green Deal water efficiency compliance stack. Acquisition targets should exhibit specialized membrane fouling expertise and ANSM certification track records. The signal to watch is basin-specific decree implementation velocity from the ecological transition ministry as an inflection indicator for contract award timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Operational Contract Extension | Secures predictable cash flows through Agence de l'Eau basin agency relationships spanning drought cycles. |
| Membrane Module Manufacturing Scale-Up | Reduces supply chain exposure to Toray and LG Chem for critical filtration components in reuse systems. |
| Smart Meter Platform Integration | Enables real-time leak detection pilots with ultrasonic sensors in Paris and Lyon municipal networks. |
| Shared Infrastructure Hub Consolidation | Captures economies of scale for Lyon corridor chemical manufacturers under tightening ANSM discharge permits. |
| Cybersecurity Certification Program | Addresses SCADA ransomware threats that strain municipal capex cycles in Île-de-France treatment plants. |
Research Methodology
Operator-level perspectives from treatment plant managers, Agence de l'Eau basin agency planners, agricultural cooperative procurement leads, and industrial facility engineers anchored the qualitative base for this study. Primary interviews combined with secondary validation from EU Water Framework Directive implementation reports, ANSM discharge permit databases, and SEC filings from listed water utilities. Customs records for membrane filtration equipment imports and basin-level abstraction statistics from the Ministry of Ecological Transition provided quantitative grounding. Bottom-up equipment deployment tallies and top-down sectoral consumption estimates were triangulated to construct market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with regulatory implementation velocity and drought frequency treated as discrete scenario inputs. Segmentation dimensions modeled include end user category, water source type, distribution channel structure, and usage application intensity. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate compliance timelines. Membrane bioreactor adoption curves in food processing and precision irrigation penetration in Occitanie vineyard operations served as industry-specific forecast anchors.
Macroeconomic conditions sit as an overlay; deviation in electricity price trajectories and agricultural commodity cycles would shift the trajectory of irrigation equipment investment and treatment plant operating cost structures. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and basin agency allocation reform sequencing. Quarterly review of Agence de l'Eau decree publications and ANSM certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Mexico Water Consumption Market
Water Management
Water Filters Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Chile Water Consumption Market
Water Management
Water Trading Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Spain Water Consumption Market
Water Management
North America Water Sink Market
Water Management
Water Free Urinals Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Municipal Water Market
Water Management
Water Utility Services Market
Water Management
NRW Smart Leak Management Market
Water Management
Smart Water Management Market
Water Management
Smart Water Network Market
Water Management
Global Water Market