
 Spain Water Consumption Market | 2026-2036
Spain Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Water Consumption Market Insights
Potable water quality upgrades across municipal networks is collapsing legacy infrastructure replacement cycles into accelerated investment timelines. Aguas de Barcelona leverages its vertically integrated treatment and distribution footprint across Catalonia to sustain margin capture from advanced membrane installations. Acciona Agua dominates EPC contracts for desalination and reuse plants, while Agbar specializes in smart metering and network digitization to extend operational control over aging pipe assets.
Spain water consumption encompasses the extraction, treatment, distribution, and end-use of water resources across residential, commercial, agricultural, and industrial applications, typically measured in cubic meters delivered through pressurized piped systems with turbidity thresholds below 1 NTU and residual chlorine maintenance of 0.2-0.6 mg/L for potable compliance. Surface water and groundwater sources still supply the majority of volume, yet desalination output is expanding fastest as coastal aquifers face salinity intrusion and irrigation demand intensifies. Quality standard tiers reveal drinking water commands the highest treatment and monitoring expenditure, while wastewater recovery for industrial reuse is emerging as a margin pool where membrane bioreactor technology reduces intake dependency.
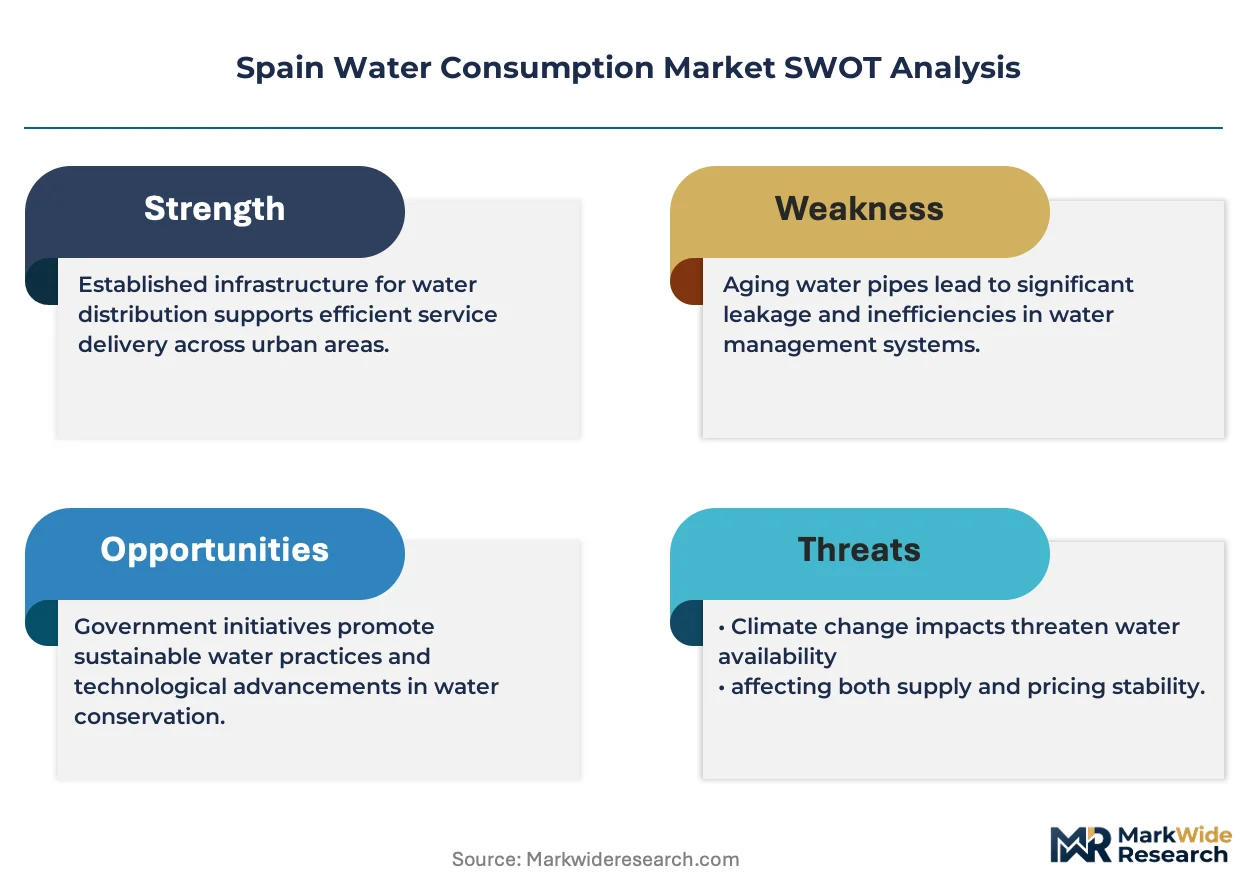
EU Water Framework Directive implementation through Spain's river basin authorities shapes abstraction licensing and environmental flow requirements, while BSI-equivalent UNE standards govern potable quality thresholds and infrastructure materials compliance. The national hydrological plan administered by MITECO restricts groundwater concessions in overexploited aquifers, redirecting investment toward alternative sourcing. Stakeholders must monitor basin-level drought declarations and desalination power cost exposure as climate variability tightens supply predictability.
Market Dynamics
Spain's water consumption landscape is being fundamentally restructured by the EU Water Framework Directive's environmental flow mandates, which are forcing irrigation districts and municipal utilities to abandon historical abstraction rights in favor of basin-level sustainability quotas.
Growth Catalysts
- EU Common Agricultural Policy water-efficiency mandates:Drip irrigation retrofits in Andalusia and Murcia are accelerating capital deployment into precision agriculture infrastructure.
- Coastal aquifer salinity intrusion:Rising saltwater penetration into groundwater basins from Almería to Alicante is redirecting industrial demand toward desalination capacity expansion.
- Smart metering infrastructure:Network digitization programs across Catalonia and Valencia are reducing non-revenue water losses below 15 percent in pilot zones.
Market Restraints
- Desalination power cost volatility:Electricity input costs represent 35-50 percent of treated water production expenses, exposing operators to Iberian wholesale market price swings.
- Overexploited aquifer concession restrictions:MITECO's national hydrological plan has frozen new groundwater permits in the Segura and Júcar basins, constraining supply elasticity.
- Membrane replacement cycles:Reverse osmosis membrane degradation requires 7-year capital refresh intervals that strain municipal budget predictability.
Strategic Opportunities
- Wastewater industrial reuse:Membrane bioreactor installations for cooling tower makeup and process water in chemical parks offer margin pools above potable tariffs.
- Basin-level drought declaration protocols:Emergency desalination procurement mechanisms create fast-track revenue windows for coastal plant operators during hydrological stress periods.
- Smart city integration:Real-time demand-response platforms linking household consumption to dynamic pricing are penetrating Barcelona and Madrid metropolitan zones.
Industry Challenges
- Legacy pipe asset condition assessment:Pre-1980 asbestos-cement and cast-iron networks in older Spanish cities lack georeferenced integrity data, complicating targeted replacement prioritization.
- Cross-basin transfer infrastructure maintenance:The Tagus-Segura aqueduct's tunnel and pumping station rehabilitation requires extended service interruptions that strain alternative supply continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Water Consumption Market |
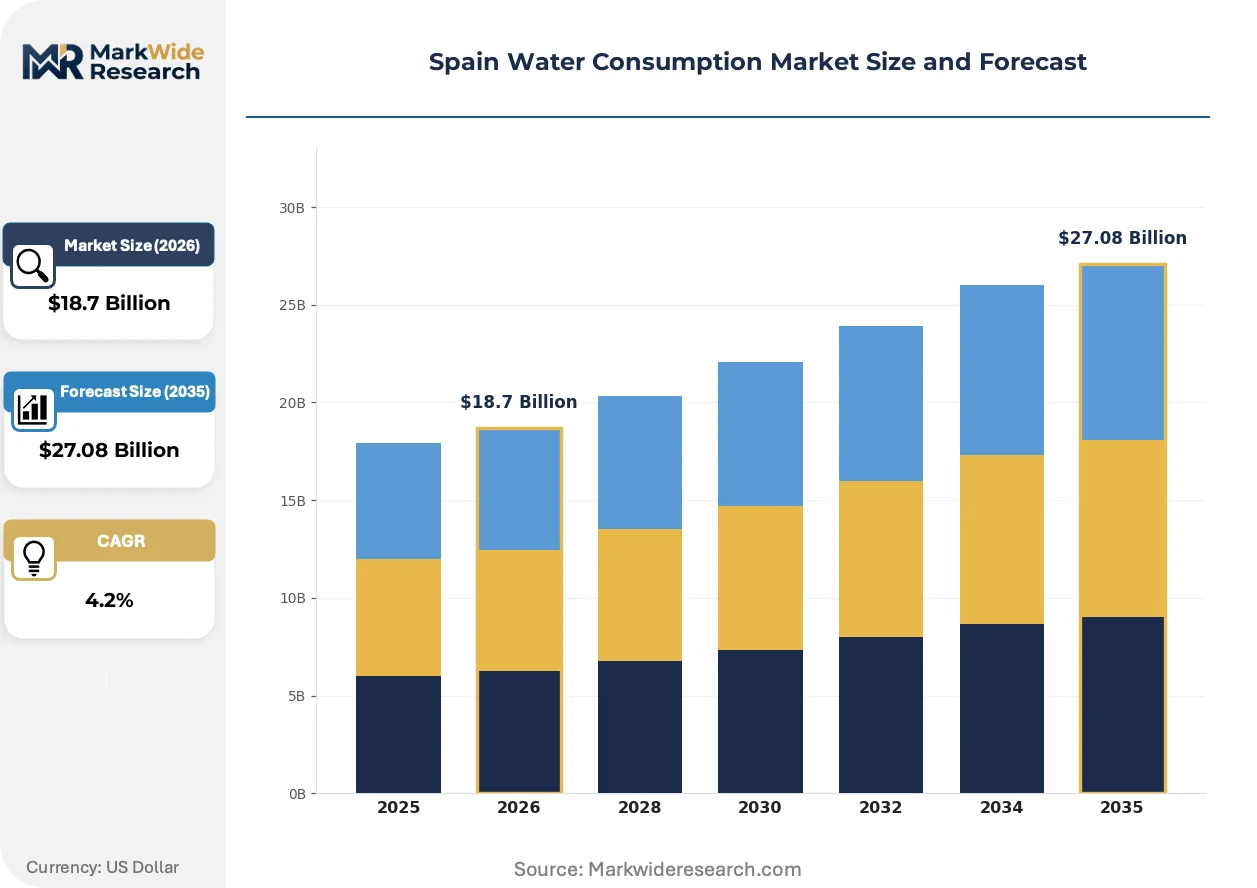
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Usage Type: Residential, Commercial, Agricultural, Industrial Source: Surface Water, Groundwater, Desalination, Rainwater Harvesting Distribution Method: Piped System, Tanker Supply, Bottled Water, Well Quality Standard: Drinking Water, Irrigation Water, Industrial Water, Wastewater |
| Companies Covered | Amazon Web Services, Aguas de Barcelona, Microsoft Corporation, Acciona Agua, Canal Isabel II, Equinix Inc., Agbar, Suez, Digital Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Water Consumption Market Trends and Innovations
Digital water management platforms are collapsing the latency between consumption measurement and network response, enabling utilities to shift from reactive leak repair to predictive pressure modulation.
Membrane bioreactor technology is supplanting conventional activated sludge systems in wastewater treatment facilities serving industrial parks and dense residential zones. Food processors and textile manufacturers in Valencia and Catalonia are adopting these compact installations to reduce freshwater intake dependency. The structural compression of treatment footprint is enabling plant retrofits within existing municipal site boundaries without land acquisition.
Spain's river basin authorities are enforcing the EU Water Framework Directive through abstraction licensing reforms that mandate environmental flow reservations. Industrial users in the Ebro and Guadalquivir basins face phased reductions in historical water rights allocations. Agricultural cooperatives are responding with deficit irrigation scheduling and crop substitution toward lower-water alternatives.
Industrial buyers are consolidating procurement through multi-year framework agreements that bundle water supply, wastewater treatment, and reuse services under single-provider contracts. Chemical and beverage manufacturers in the Mediterranean corridor are displacing spot-market purchasing with integrated water management partnerships. This concentration is most visible in Tarragona's petrochemical cluster and Almería's greenhouse agriculture belt.
Spain Water Consumption Market Segmentation
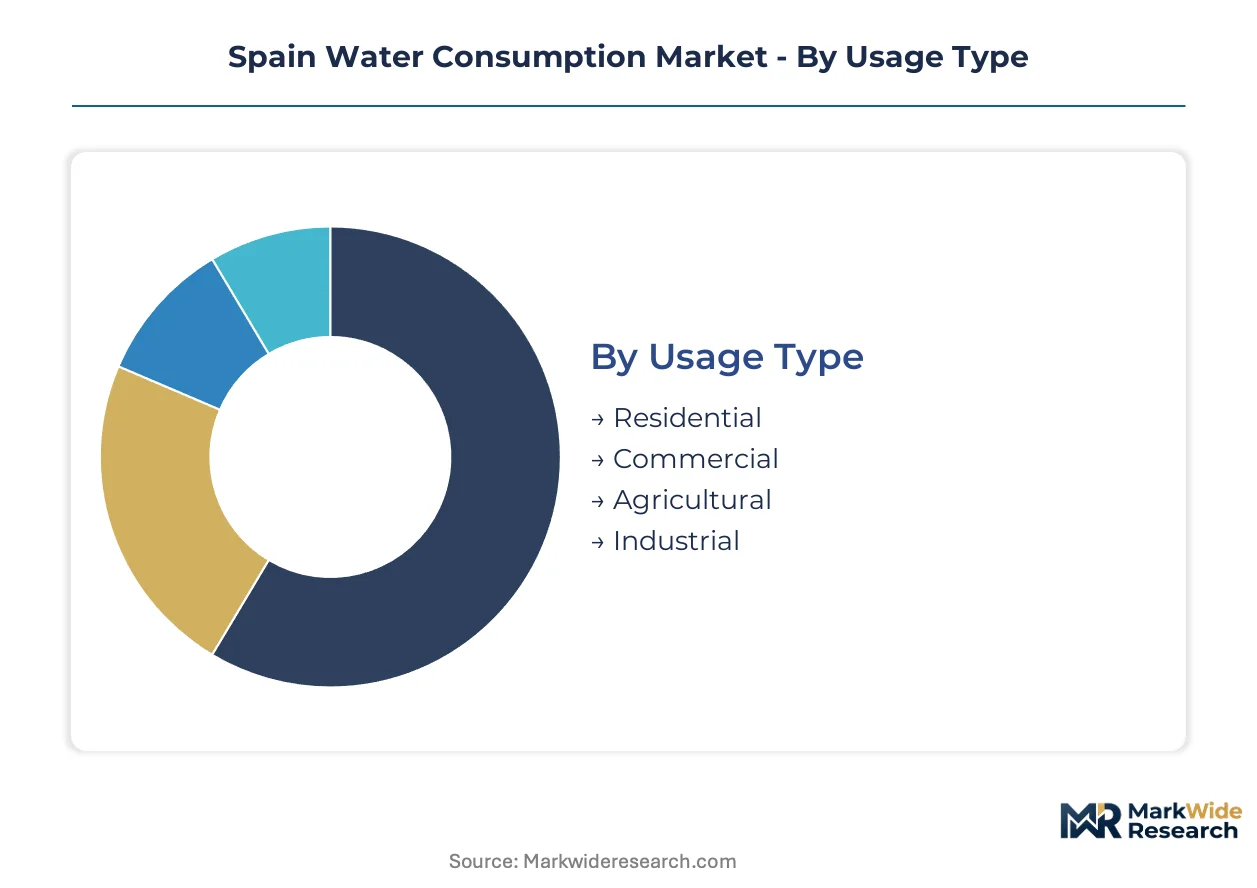
Segmentation in Spain's water consumption market reveals how regulatory pressure and resource scarcity reshape infrastructure investment priorities across distinct supply channels. Understanding these divisions exposes where EU Water Framework Directive compliance costs concentrate and where alternative sourcing technologies capture margin.
Usage Type:
MITECO's basin-level abstraction licensing creates divergent compliance burdens across user categories, with agricultural and industrial segments facing the steepest concession restrictions in overexploited aquifers.
- Residential:Municipal utilities serving Barcelona and Madrid metropolitan zones deploy smart metering to reduce non-revenue water below 15 percent in pilot districts. Household consumption patterns drive membrane installation demand as utilities upgrade treatment for potable compliance.
- Commercial:Hotels, retail complexes, and office parks in coastal provinces absorb desalination output as groundwater salinity intrusion eliminates traditional borehole reliability. Service sector buyers prioritize supply continuity over unit cost minimization.
- Agricultural:Andalusian and Murcian irrigation districts retrofit drip and precision systems under CAP water-efficiency mandates, collapsing capital deployment timelines for network modernization.
- Industrial:Chemical parks and food processors adopt membrane bioreactor wastewater recovery to reduce freshwater intake dependency and bypass allocation constraints.
Established volume favors Agricultural; emerging adoption favors Industrial.
Source:
Cost tier differentiation separates capital-intensive desalination from gravity-fed surface systems, with power price exposure determining competitive positioning for coastal supply.
- Surface Water:Reservoir-fed systems in the Ebro and Duero basins supply bulk municipal demand but face environmental flow reservations under river basin authority enforcement. Seasonal variability tightens allocation predictability.
- Groundwater:Coastal aquifers from Almería to Alicante suffer salinity intrusion that degrades borehole output quality, forcing abandonment of historical concessions in the Segura and Júcar basins.
- Desalination:Mediterranean coastal plants absorb rising industrial and municipal demand as traditional sources face MITECO allocation constraints. Electricity input costs represent 35-50 percent of production expenses, exposing operators to Iberian wholesale market volatility.
- Rainwater Harvesting:Residential and commercial buildings in Balearic and Canary Islands deploy collection systems for non-potable applications, reducing potable network load.
Surface Water retains volume dominance; Desalination climbs the fastest.
Distribution Method:
Network maturity and infrastructure integrity determine which channels can absorb real-time demand-response platform integration.
- Piped System:Pressurized municipal networks with turbidity thresholds below 1 NTU and residual chlorine maintenance of 0.2-0.6 mg/L serve dense urban cores. Pre-1980 asbestos-cement and cast-iron assets in older cities lack georeferenced integrity data.
- Tanker Supply:Emergency distribution during drought declarations or infrastructure maintenance intervals creates fast-track procurement windows for mobile operators.
- Bottled Water:Quality-sensitive consumers and remote locations without piped connectivity sustain premium-priced volume.
- Well:Agricultural cooperatives and isolated industrial facilities maintain private boreholes subject to MITECO concession restrictions in overexploited zones.
Piped System captures institutional investment; Tanker Supply gains share fastest during hydrological stress periods.
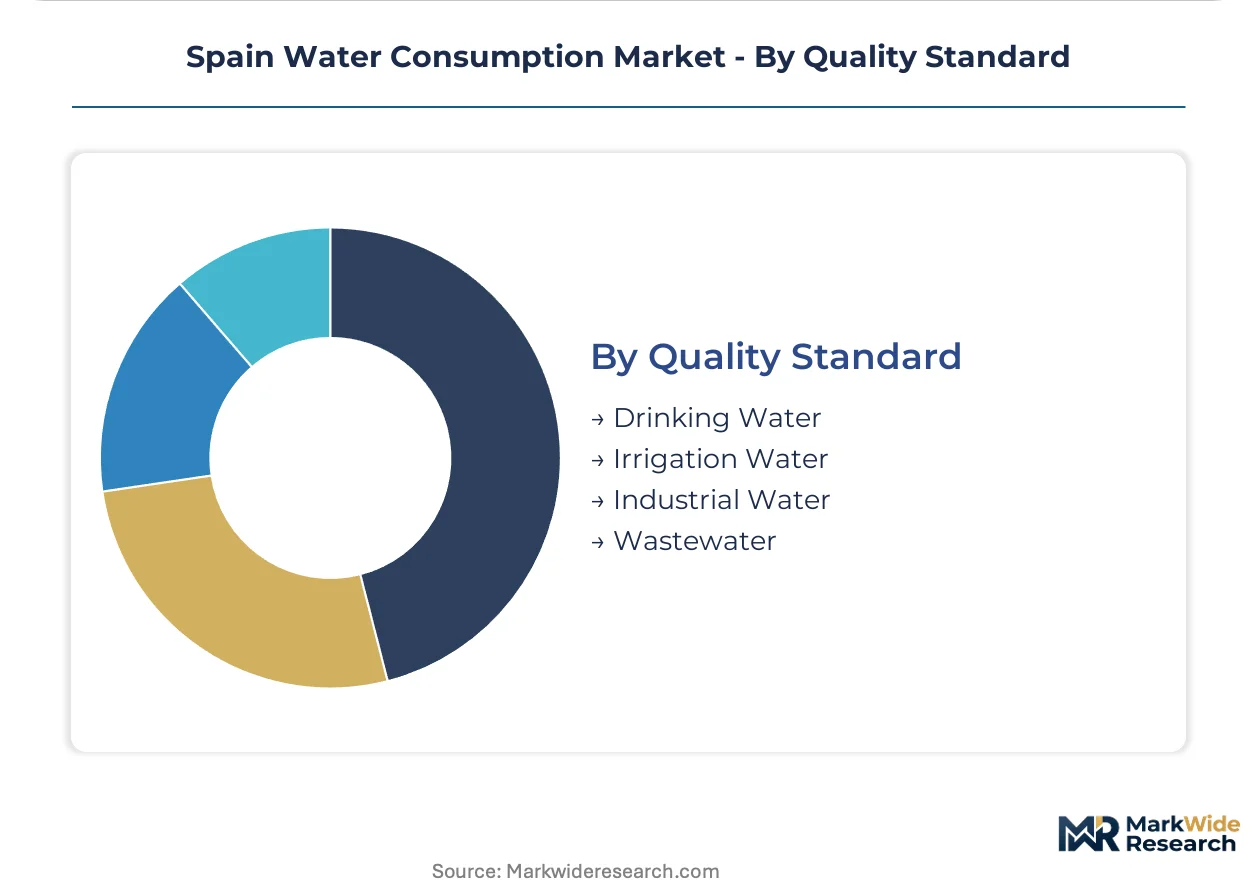
Quality Standard:
Application-specific treatment intensity drives margin stratification, with potable compliance commanding the highest monitoring expenditure.
- Drinking Water:Advanced membrane installations and residual chlorine maintenance protocols serve residential and commercial endpoints. Aguas de Barcelona leverages vertically integrated treatment footprints to sustain margin capture.
- Irrigation Water:Deficit scheduling and crop substitution toward lower-water alternatives respond to phased reductions in historical agricultural rights allocations.
- Industrial Water:Cooling tower makeup and process water specifications enable wastewater recovery margins above potable tariffs through membrane bioreactor technology.
- Wastewater:Tertiary treatment for environmental discharge or reuse applications faces UNE standards compliance for infrastructure materials and effluent quality.
Drinking Water retains treatment expenditure concentration; Industrial Water expands most quickly through reuse adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's water infrastructure investment patterns diverge sharply across autonomous communities, with coastal provinces absorbing desalination capacity while interior basins face aquifer depletion. Regional allocation priorities under MITECO's hydrological planning reshape capital deployment timelines.
Catalonia
Barcelona's metropolitan utility drives smart metering penetration and membrane-based treatment upgrades. The Catalan Water Agency enforces environmental flow reservations under the EU Water Framework Directive. Tarragona's petrochemical cluster consolidates procurement through integrated water management partnerships bundling supply, treatment, and reuse.
Andalusia
Almería's greenhouse agriculture belt deploys precision drip irrigation retrofits under CAP water-efficiency mandates. The Guadalquivir River Basin Authority restricts groundwater concessions in overexploited zones. Seville's municipal network confronts pre-1980 asbestos-cement pipe integrity gaps lacking georeferenced asset data.
Valencia
Júcar basin irrigation districts face phased reductions in historical water rights allocations. The Valencian Community's agricultural cooperatives adopt deficit scheduling and crop substitution toward lower-water alternatives. Valencia city's digitization programs reduce non-revenue water losses below 15 percent in pilot zones.
Madrid
The capital's dense urban core sustains pressurized network demand for potable compliance monitoring. Canal Isabel II manages the Tagus basin allocation system serving metropolitan consumption. Real-time demand-response platforms linking household consumption to dynamic pricing penetrate Madrid's residential zones.
Murcia
Segura basin aquifers suffer salinity intrusion forcing abandonment of historical borehole concessions. Murcian irrigation networks accelerate capital deployment into precision agriculture infrastructure. Coastal desalination plants absorb rising industrial demand as traditional surface sources face MITECO allocation constraints.
Spain Water Consumption Market Competitive Landscape
Listed leaders compete with private specialists across treatment technology and network digitization capabilities. The vendor base organizes around three strategic archetypes: vertically integrated municipal utilities, EPC contractors for desalination and reuse infrastructure, and smart metering specialists extending operational control over aging assets. Competitive positioning hinges on backward integration into membrane manufacturing and geographic expansion through concession bidding.
Among Spanish-based operators, Aguas de Barcelona and Acciona Agua occupy distinct positioning tiers. Aguas de Barcelona exemplifies the integrated utility archetype leveraging captive treatment and distribution footprints. Acciona Agua anchors the EPC contractor segment for desalination and reuse plant construction. Agbar represents the network digitization specialist archetype focused on smart metering and operational technology deployment.
| Leading Market Players |
|---|
| Amazon Web Services |
| Aguas de Barcelona |
| Microsoft Corporation |
| Acciona Agua |
| Canal Isabel II |
| Equinix Inc. |
| Agbar |
| Suez |
| Digital Realty |
| Others |
Pricing and Supply Chain Analysis
Desalination plant capacity utilization above 80 percent at Mediterranean coastal facilities creates scale economies that compress unit production costs while simultaneously concentrating supply bargaining power among membrane manufacturers and energy providers. This scale concentration establishes price floors for municipal offtake contracts and shapes how industrial buyers structure multi-year procurement frameworks across Spain's water-stressed provinces.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for desalination and reuse services, with three-tier pricing structure across premium, standard, and economy levels differentiated by quality grade certification and volume scale commitments. Cost compression in the standard tier is intensifying because Iberian wholesale electricity price volatility directly feeds 35-50 percent of production expenses. Agricultural cooperatives demonstrate highest price sensitivity due to thin crop margins, while petrochemical clusters in Tarragona exhibit lowest sensitivity given supply continuity premiums.
Supply Chain Analysis
Reverse osmosis membrane manufacturing concentrates in the United States, Japan, and South Korea, with Spain's desalination operators drawing from these sources for 7-year replacement cycles. Specialized energy recovery devices and high-pressure pumps feed from German and Italian precision engineering suppliers. Single-source vulnerability in membrane chemistry exposes operators to extended lead times during geopolitical trade restrictions. Distribution runs through EPC contractors like Acciona Agua that bundle procurement, construction, and commissioning services for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's water consumption market sits in early-cycle expansion as EU Water Framework Directive enforcement accelerates infrastructure replacement timelines and opens procurement windows for alternative sourcing technologies.
For Market Incumbents: Compound defensive positioning through backward integration into membrane manufacturing capabilities and captive energy supply agreements that hedge Iberian wholesale price exposure. Canal Isabel II and Aguas de Barcelona should prioritize smart metering deployment in pre-1980 asbestos-cement network zones to reduce non-revenue water losses below 15 percent before emerging digital-native entrants capture municipal digitization contracts.
For New Entrants and Emerging Players: Differentiate on membrane bioreactor technology for industrial wastewater reuse applications in Valencia and Catalonia chemical parks where freshwater allocation constraints create urgency. Target Murcia's Segura basin irrigation districts with precision agriculture-as-a-service models bundling drip retrofit financing with deficit scheduling software, penetrating through agricultural cooperative procurement channels rather than municipal utility RFP processes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated water utilities with captive treatment and distribution footprints over pure-play EPC contractors exposed to project cyclicality. Long-term viability rests on concession tenure security and regulatory relationship depth. Monitor basin-level drought declaration frequency as the inflection signal for emergency desalination procurement volume spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Metering Infrastructure Deployment | Agbar's network digitization reduces non-revenue water losses below 15 percent in pilot zones. |
| Membrane Bioreactor Installation | Industrial parks in Valencia adopt compact wastewater recovery to bypass MITECO allocation constraints. |
| Backward Integration into Membrane Manufacturing | Captive supply hedges 7-year replacement cycle exposure and procurement lead time volatility. |
| Energy Recovery Device Partnership | Desalination operators cut electricity input costs through German-Italian precision engineering alliances. |
| Integrated Water Management Contracting | Tarragona petrochemical clusters bundle supply, treatment, and reuse under single-provider frameworks. |
Research Methodology
Initial hypotheses were tested against primary input from desalination plant operators, river basin authority planners, agricultural cooperative managers, and municipal utility procurement directors and refined through secondary validation against MITECO hydrological planning documents, EU Water Framework Directive implementation reports, Iberian electricity market pricing data, and concession bidding records. Bottom-up capacity utilization modeling and top-down macroeconomic scenario analysis were triangulated to cross-validate volume projections.
Variance decomposition across the projection horizon isolates drivers by usage type, source technology, distribution method, and quality standard tier, with segmentation-specific CAGRs derived from basin-level abstraction licensing trajectories and desalination capacity expansion pipelines. Forecast inputs incorporate drought declaration frequency patterns, CAP water-efficiency mandate compliance timelines, and industrial reuse adoption curves in chemical parks.
The analysis sits within stated boundaries; outcomes outside sustained EU funding for agricultural retrofit programs or accelerated environmental flow enforcement would require recalibration. Practitioners should keep alternative scenarios live as Iberian wholesale electricity price regimes and membrane supply chain disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
France Water Consumption Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Smart Water Management Market
Water Management
Global Water Market
Water Management
NRW Smart Leak Management Market
Water Management
Mexico Water Consumption Market
Water Management
Water Filters Market
Water Management
Chile Water Consumption Market
Water Management
Municipal Water Market
Water Management
Water Trading Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
North America Water Sink Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Water Utility Services Market
Water Management
Water Free Urinals Market
Water Management
Smart Water Network Market