
 Mexico Water Consumption Market | 2026-2036
Mexico Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Water Consumption Market Insights
Industrial buyers are redrawing procurement patterns as manufacturing clusters near Monterrey and Guadalajara scale operations. Danone S.A. anchors its position through deep distribution into northern border states where maquiladora demand runs high. The Coca-Cola Company leverages its fountain and vending infrastructure to dominate commercial channels in urban centers. PepsiCo, Inc. competes through purified water sub-brands targeted at health-conscious middle-class households.
Water consumption encompasses all potable and non-potable water utilized across residential, commercial, industrial, and agricultural applications, with treatment parameters varying by end use from total dissolved solids thresholds to chlorination protocols. Bottled water commands premium margin pools as consumers distrust municipal supply quality in key basins. Purified water segments show structural expansion as reverse osmosis systems penetrate commercial kitchens and small manufacturing plants. Retail sales channels sustain volume leadership, though bulk delivery gains traction among hospitality and institutional buyers seeking cost efficiency at scale.
CONAGUA, Mexico's national water commission, regulates extraction permits and basin allocations under the National Water Law, directly constraining supply availability for industrial offtakers. The Secretariat of Environment and Natural Resources enforces wastewater discharge standards that force processing upgrades across manufacturing facilities. BIS-equivalent Mexican standards for bottled water purity create compliance barriers for informal producers. Stakeholders must monitor basin-level concession renewals and drought contingency declarations to anticipate supply disruptions and pricing volatility.
Market Dynamics
Aquifer depletion across the Mexico City metropolitan zone is forcing a fundamental reconfiguration of water sourcing, with municipal utilities losing reliability and industrial offtakers accelerating investment in captive treatment infrastructure.
Growth Catalysts
- National Water Law reforms:CONAGUA's tightened extraction permit requirements for groundwater basins are redirecting demand toward formal bottled and purified water channels, benefiting compliant producers with concession security.
- Maquiladora cluster expansion:Manufacturing growth near Monterrey and Tijuana is generating concentrated industrial water demand that bulk delivery operators are capturing through dedicated pipeline investments.
- Reverse osmosis penetration:Commercial kitchens and small manufacturing plants are deploying point-of-use treatment systems, creating aftermarket service revenue streams for equipment vendors and chemical suppliers.
Market Restraints
- Groundwater concession scarcity:CONAGUA's basin-level allocation limits constrain production capacity expansion for extraction-dependent bottlers in overdrawn aquifers.
- Energy cost volatility:Reverse osmosis and ultraviolet treatment systems face margin pressure from electricity price swings, particularly affecting small commercial operators without solar captive generation.
- Informal producer competition:Unregistered bottlers operating outside BIS-equivalent standards capture price-sensitive volume in southern states, eroding formal channel pricing power.
Strategic Opportunities
- Northern border states:Chihuahua and Baja California present underpenetrated bulk delivery potential as cross-border logistics hubs expand workforce housing and institutional catering.
- Hospitality channel consolidation:Hotel chains are centralizing procurement through national supply contracts, creating volume aggregation opportunities for distributors with refrigerated fleet capacity.
- Wastewater reuse mandates:Secretariat of Environment and Natural Resources discharge standards are compelling manufacturing facilities to install closed-loop treatment, opening engineering and chemical dosing service contracts.
Industry Challenges
- Concession renewal timelines:CONAGUA's multi-year permit review cycles create planning uncertainty for industrial users dependent on specific basin allocations.
- Technical workforce scarcity:Certified operators for membrane maintenance and water quality testing are concentrated in Mexico City and Monterrey, limiting facility expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Water Consumption Market |
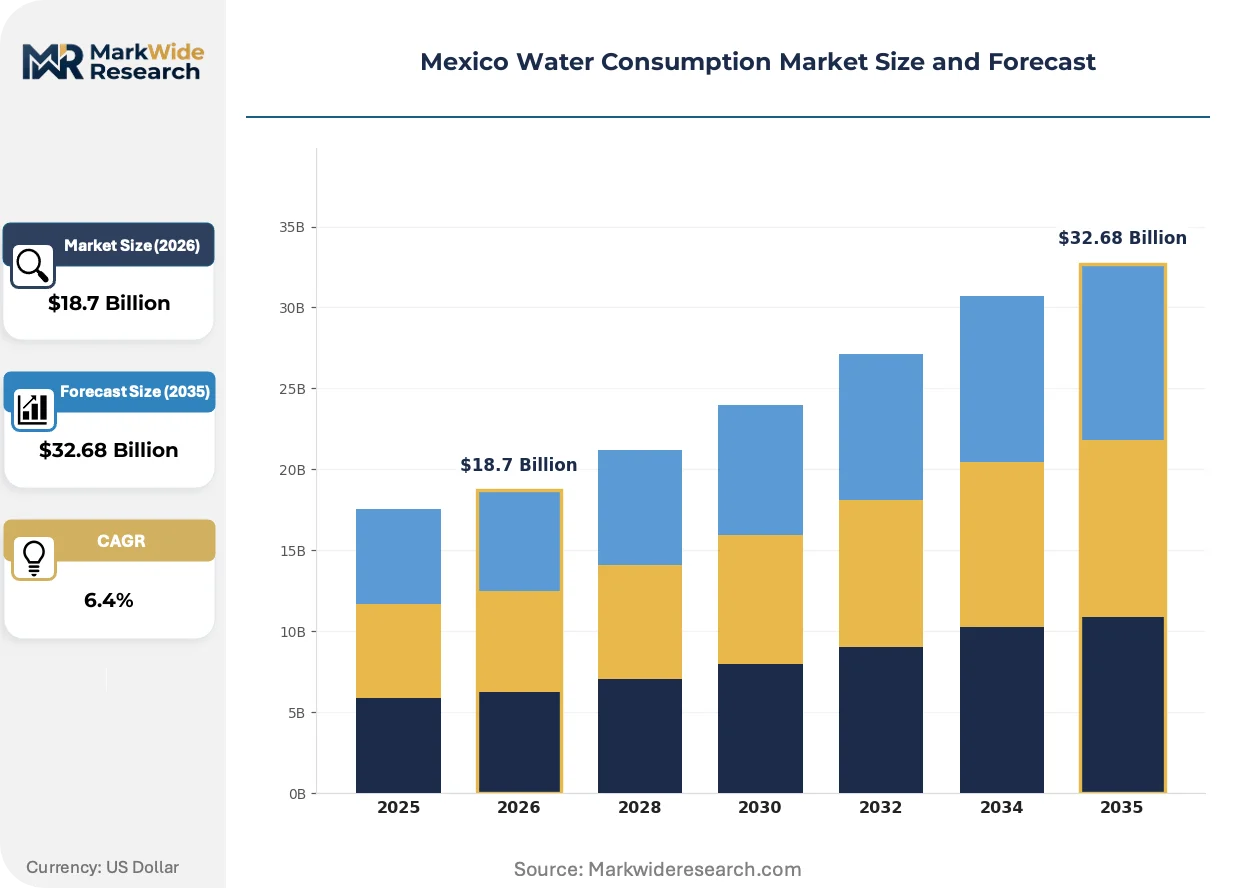
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottled Water, Tap Water, Purified Water, Distilled Water End User: Residential, Commercial, Industrial, Agriculture Delivery Mode: Bulk Delivery, Retail Sales, Online Orders, Vending Machines Seasonal Demand: Summer, Winter, Monsoon, Drought |
| Companies Covered | Danone S.A., The Coca-Cola Company, PepsiCo, Inc., Keurig Dr Pepper Inc, Nestle S.A., Primo Water Corp, Equinix Inc., Amazon Web Services Inc, KIO Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Water Consumption Market Trends and Innovations
Technology substitution and regulatory stringency are converging to reshape competitive advantage, with treatment efficiency and concession compliance becoming primary differentiators over brand equity alone.
Ultrafiltration membrane systems are displacing conventional sand filtration in municipal treatment retrofits. State water utilities in Jalisco and Nuevo León are piloting ceramic membrane installations to reduce chlorine dependency. The technology is displacing legacy infrastructure procurement patterns by bundling 15-year service contracts that transfer operational risk to equipment vendors.
CONAGUA's drought contingency declarations are tightening extraction quotas ahead of formal permit renewals. Industrial users in the Lerma-Chapala basin face mandatory 20% consumption cuts during scarcity events, forcing investment in efficiency retrofits. Food and beverage processors are responding by segregating process water grades, treating lower-quality sources for non-contact applications.
Bulk delivery subscriptions are capturing institutional volume from retail case purchases. Hospital and school cafeteria operators in Guadalajara and Puebla are contracting weekly tanker delivery with quality certification documentation, bypassing traditional wholesale distributors. The shift is most visible in states with documented municipal supply contamination events, where procurement officers prioritize audit trail completeness over unit cost minimization.
Mexico Water Consumption Market Segmentation
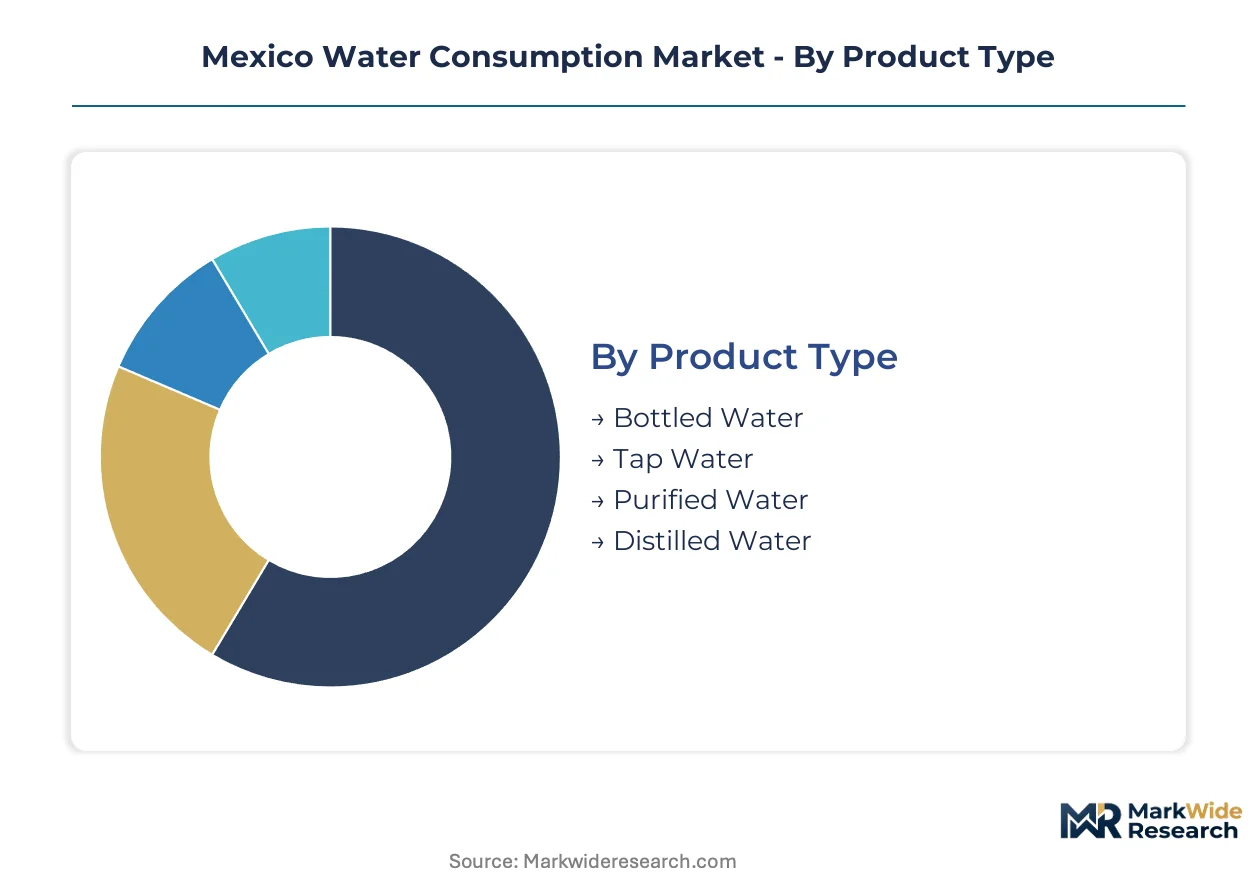
Water consumption patterns in Mexico fragment sharply across product formats, end-use applications, and delivery infrastructure. CONAGUA's extraction permit tiers and BIS-equivalent purity standards create regulatory fault lines that vendors must navigate to capture volume in each segment.
Product Type:
CONAGUA's groundwater concession classifications directly determine which producers can operate in each product tier, with extraction-dependent segments facing the steepest compliance barriers.
- Bottled Water:Sealed containers meeting NOM-141-SCFI standards command premium positioning through documented purity certification. Demand concentrates in the Mexico City metropolitan zone where aquifer depletion has eroded municipal supply trust, with maquiladora clusters near Monterrey and Tijuana driving border-state volume through workforce consumption.
- Purified Water:Reverse osmosis and ultraviolet-treated water distributed in refillable jugs or point-of-use systems. Adoption accelerates in Guadalajara and Puebla commercial kitchens where procurement officers prioritize audit trail documentation over unit cost following documented contamination events in municipal networks.
- Tap Water:Municipal utility supply governed by CONAGUA basin allocations and state water utility treatment protocols. Network coverage expansion into informal settlements drives residential access, though quality inconsistency limits commercial and industrial reliance.
- Distilled Water:Vapor-condensed water meeting pharmaceutical and laboratory grade specifications. Demand localizes in Mexico City medical device manufacturing and chemical processing facilities requiring mineral-free process inputs.
Established volume favors bottled water; emerging adoption favors purified water through reverse osmosis penetration.
End User:
Cost-to-serve economics and treatment specification intensity vary dramatically across end-use categories, with industrial buyers commanding the most sophisticated procurement infrastructure.
- Residential:Household consumption spanning drinking, cooking, and hygiene applications. The Mexico City metropolitan zone dominates volume as aquifer depletion drives substitution toward bottled and purified alternatives in middle-class and informal settlement households alike.
- Commercial:Hospitality, food service, and retail operations with variable quality requirements. Hotel chains in Cancún and Los Cabos are centralizing procurement through national supply contracts, creating volume aggregation opportunities for distributors with refrigerated fleet capacity.
- Industrial:Manufacturing process water, cooling systems, and boiler feed applications. Maquiladora clusters near Monterrey and Tijuana generate concentrated demand that bulk delivery operators capture through dedicated pipeline investments and closed-loop treatment service contracts.
- Agriculture:Irrigation and livestock watering subject to basin-level concession allocations. CONAGUA's drought contingency declarations in the Lerma-Chapala basin force mandatory consumption cuts, driving investment in efficiency retrofits and lower-grade water segregation for non-contact applications.
Industrial offtakers deliver the highest revenue per liter; residential channels provide the broadest volume base.
Delivery Mode:
Customer scale and quality documentation requirements determine delivery infrastructure selection, with institutional buyers shifting toward subscription models that guarantee supply security.
- Bulk Delivery:Scheduled tanker or cylinder distribution to commercial and institutional buyers. Hospital and school cafeteria operators in Guadalajara and Puebla are contracting weekly delivery with certification documentation, bypassing traditional wholesale distributors.
- Retail Sales:Supermarket, convenience store, and traditional trade point-of-purchase transactions. The Coca-Cola Company and PepsiCo leverage existing beverage distribution networks to dominate shelf presence in urban centers.
- Online Orders:E-commerce platforms and direct-to-subscriber replenishment services. Penetration remains limited to Mexico City and Monterrey middle-class households with predictable consumption patterns and delivery address reliability.
- Vending Machines:Point-of-use dispensing in transit hubs, educational institutions, and manufacturing facilities. Deployment concentrates in northern border states where maquiladora workforce density justifies capital investment.
Retail sales sustain volume leadership; bulk delivery gains share fastest among hospitality and institutional buyers.
Seasonal Demand:
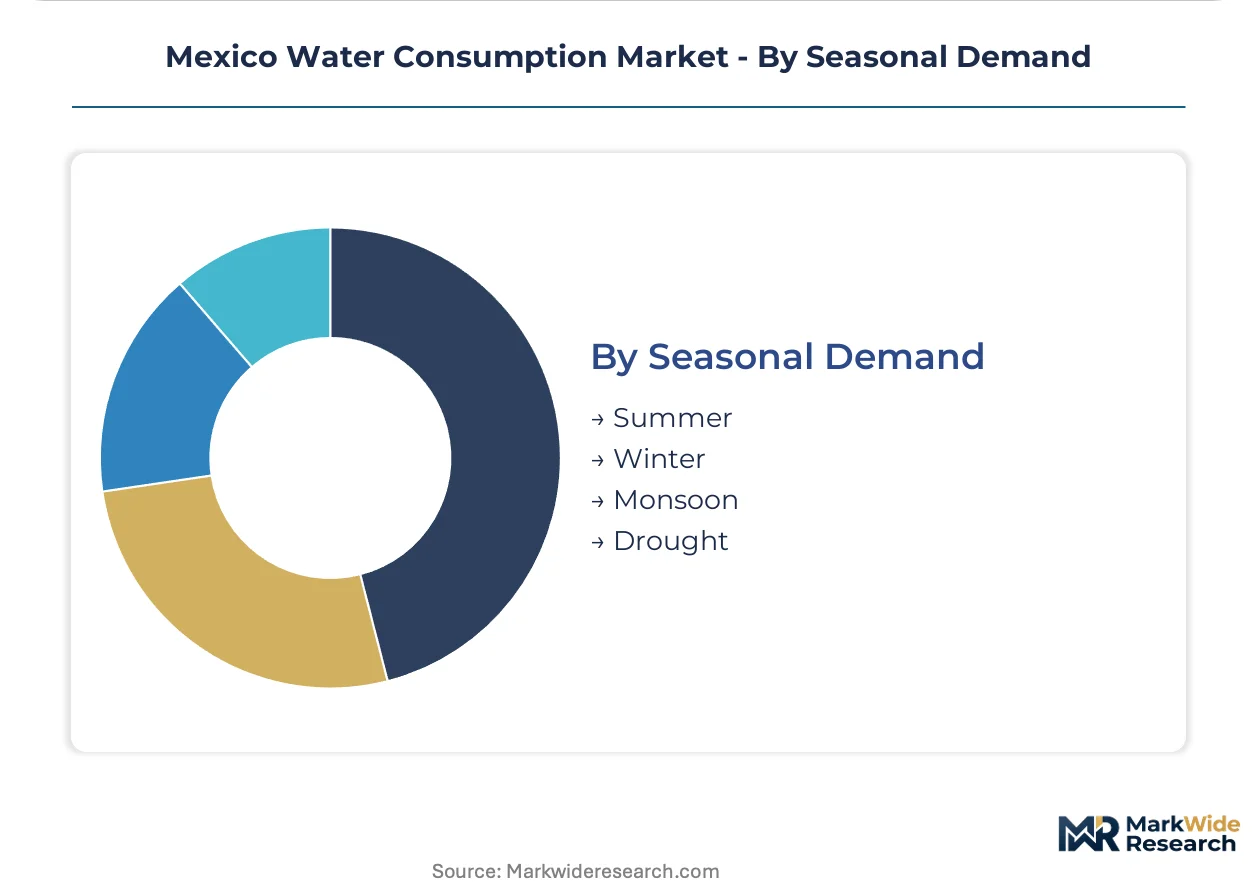
Climate variability and CONAGUA's drought contingency protocols create predictable demand cycles that vendors must anticipate through inventory and concession management.
- Summer:Peak consumption period driven by temperature-related hydration demand and tourism concentration in coastal zones. Bottled water volume surges in Baja California and Quintana Roo resort corridors.
- Winter:Reduced baseline consumption with stable industrial offtake. Maintenance windows for municipal treatment infrastructure concentrate in this period.
- Monsoon:Variable precipitation patterns affecting surface water availability and municipal treatment capacity. Runoff events periodically trigger supply contamination alerts that redirect demand toward certified bottled alternatives.
- Drought:CONAGUA-declared scarcity events triggering mandatory extraction quotas and consumption restrictions. Industrial users in overdrawn aquifers face 20% mandatory cuts, accelerating investment in captive treatment and efficiency retrofits.
Summer delivers predictable volume spikes; drought periods drive the steepest structural demand shifts toward formal certified channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lerma-Chapala aqueduct system underwrites central Mexico's industrial water security while the Monterrey-Saltillo rail corridor enables bulk logistics to northern manufacturing clusters.
Mexico City Metropolitan Zone
Aquifer depletion drives middle-class households and informal settlements toward bottled and purified alternatives as municipal supply reliability erodes. CONAGUA's basin-level extraction quotas tighten permit renewals for groundwater-dependent bottlers. Industrial parks in Tlalnepantla and Cuautitlán Izcalli are installing captive reverse osmosis systems to circumvent municipal dependency.
Nuevo León
Maquiladora clusters near Monterrey generate concentrated demand for bulk delivery through dedicated pipeline investments. The state's water utility, Agua y Drenaje de Monterrey, enforces industrial discharge standards that force processing upgrades across manufacturing facilities. García and Santa Catarina municipalities are expanding reverse osmosis penetration in commercial kitchens serving workforce housing.
Jalisco
Guadalajara's hospitality sector is centralizing procurement through national supply contracts as hotel chains prioritize audit trail documentation. State water utility SIAPA pilots ceramic membrane installations to reduce chlorine dependency in municipal treatment. El Salto industrial corridor food processors are segregating process water grades to treat lower-quality sources for non-contact applications.
Northern Border States
Chihuahua and Baja California present underpenetrated bulk delivery potential as cross-border logistics hubs expand workforce housing and institutional catering. CONAGUA's drought contingency declarations in the Río Bravo basin trigger mandatory consumption cuts for agricultural offtakers. Tijuana and Ciudad Juárez maquiladora density justifies vending machine deployment capital investment.
Bajío Region
Querétaro and Guanajuato automotive supplier parks are accelerating investment in closed-loop treatment systems under Secretariat of Environment and Natural Resources discharge mandates. León's tannery cluster faces technical workforce scarcity for membrane maintenance operators. Celaya beverage bottlers are capturing aftermarket service revenue streams from commercial reverse osmosis deployment.
Mexico Water Consumption Market Competitive Landscape
Concentration sits with multinational beverage conglomerates and regional bulk delivery specialists. The vendor base stratifies across three tiers: global FMCG giants leveraging existing distribution infrastructure, mid-cap purified water operators with concession security in stressed basins, and informal producers competing on price outside BIS-equivalent compliance. Dominant competitive moves include backward integration into captive treatment infrastructure and geographic expansion through refrigerated fleet capacity acquisition.
Within the multinational beverage tier, Danone S.A., The Coca-Cola Company, and PepsiCo, Inc. exemplify divergent channel strategies. Danone anchors its position through deep distribution into northern border states where maquiladora demand runs high. Coca-Cola leverages fountain and vending infrastructure to dominate commercial channels in urban centers. PepsiCo competes through purified water sub-brands targeted at health-conscious middle-class households. These three occupy positions that reflect distinct bets on format mix and geographic concentration.
| Leading Market Players |
|---|
| Danone S.A. |
| The Coca-Cola Company |
| PepsiCo, Inc. |
| Keurig Dr Pepper Inc |
| Nestle S.A. |
| Primo Water Corp |
| Equinix Inc. |
| Amazon Web Services Inc |
| KIO Networks |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at reverse osmosis treatment facilities in Monterrey and Guadalajara shapes both supply concentration and price floors across Mexico's water consumption landscape. Scale operators achieve unit cost advantages that informal producers cannot match, while CONAGUA's extraction permit scarcity anchors minimum viable pricing for groundwater-dependent tiers.
Pricing Analysis
Volume-discount tiering structures separate bulk delivery contracts for maquiladora clusters from per-unit retail transactions in urban centers. Pricing stratifies across certified premium, standard compliance, and informal economy tiers, with NOM-141-SCFI certification commanding measurable premiums over unregistered alternatives. Cost compression in the standard tier is intensifying because energy price volatility squeezes small commercial operators lacking solar captive generation. Industrial offtakers show lowest price sensitivity due to process-critical quality requirements, while informal settlement households exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate institutional procurement as hospital and school cafeteria operators prioritize supply security over just-in-time efficiency. Geographic supply concentration centers on Mexico's central industrial corridor, northern border states, and selected Pacific coast zones where treatment infrastructure clusters. Raw material dependencies include membrane filtration components, ultraviolet disinfection systems, and chemical dosing agents. Single-source vulnerability runs through specialized ceramic membrane suppliers serving Jalisco's municipal utility pilots. Distribution runs through refrigerated fleet operators capturing hospitality channel consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for membrane maintenance and chemical dosing are expanding faster than equipment sales, transforming capital expenditure relationships into recurring revenue streams across commercial and industrial segments.
For Market Incumbents: Fortify concession security in overdrawn aquifers through early permit renewal applications ahead of CONAGUA's tightening review cycles. Deepen backward integration into captive solar generation to insulate margin structures from electricity price volatility. Channel control through refrigerated fleet expansion represents the priority defensive lever against bulk delivery specialists aggregating institutional volume. For New Entrants and Emerging Players: Membrane maintenance service gaps in secondary markets like León and Celaya offer white-space entry points where certified operators concentrate in Mexico City and Monterrey. Northern border states present the most penetrable geography as cross-border logistics hubs expand workforce housing. A technical workforce training partnership with regional technical institutes provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-cap purified water operators with established bulk delivery subscriptions and multi-year service contracts. Long-term viability across the analysis window favors concession-secure operators in stressed basins over extraction-dependent bottlers facing permit scarcity. Acquisition targets should demonstrate documented compliance with Secretariat of Environment and Natural Resources discharge standards. The signal to watch is CONAGUA drought contingency declaration frequency as an inflection indicator for structural demand shifts toward formal certified channels.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Security Investment | Early permit renewal applications in Lerma-Chapala basin protect production capacity against CONAGUA allocation tightening. |
| Refrigerated Fleet Expansion | Captures hospitality channel consolidation as Cancún and Los Cabos hotel chains centralize procurement. |
| Solar Captive Generation | Insulates reverse osmosis operators from electricity price volatility eroding small commercial margins. |
| Membrane Maintenance Service Contracts | Transforms equipment sales into recurring revenue streams across Guadalajara and Puebla commercial kitchens. |
| Ceramic Membrane Technology Adoption | Reduces chlorine dependency for Jalisco state water utility pilots seeking operational risk transfer. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CONAGUA regional directors, bulk delivery fleet operators, hotel procurement officers, membrane maintenance technicians, and food processing plant engineers. Secondary validation drew from CONAGUA extraction permit databases, Secretariat of Environment and Natural Resources discharge compliance records, state water utility infrastructure disclosures, and customs data on filtration equipment imports. Bottom-up volume estimates triangulated against top-down basin allocation models.
Across the analysis window, the forecasting framework modeled product format segmentation, end-use application intensity, delivery infrastructure type, and seasonal demand variability specific to drought contingency protocols. CAGRs were derived from trajectory fitting against documented concession renewal timelines and manufacturing cluster expansion patterns. Key inputs included maquiladora employment density projections and municipal network contamination event frequency.
Underlying assumptions cover stable CONAGUA regulatory enforcement intensity and continued manufacturing foreign direct investment concentration in northern states, with deviation risk concentrated in accelerated drought declaration frequency or informal producer enforcement surges. Revision becomes warranted when basin-level extraction quota reductions exceed historical contingency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Middle East and Africa Water Sink Market
Water Management
Water Free Urinals Market
Water Management
Water Trading Market
Water Management
Water Utility Services Market
Water Management
Water Filters Market
Water Management
Smart Water Management Market
Water Management
France Water Consumption Market
Water Management
Chile Water Consumption Market
Water Management
Spain Water Consumption Market
Water Management
Global Water Market
Water Management
Asia-Pacific Water Sink Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
North America Water Sink Market
Water Management
NRW Smart Leak Management Market
Water Management
Smart Water Network Market
Water Management
Atmospheric Water Generator (AWG) Market