
 Global Water Market | 2026-2036
Global Water Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Market Outlook
Municipal water reuse is shifting toward industrial offtake as manufacturing clusters face withdrawal limits. Xylem leverages its digital monitoring portfolio to anchor premium positioning in smart network deployments. Veolia competes through operational contracts spanning full water cycle management across four continents. Suez differentiates with membrane bioreactor specialization serving food and beverage processors.
Global water encompasses the extraction, treatment, distribution, and reclamation of freshwater and processed water for human consumption, industrial processes, and agricultural irrigation, typically requiring turbidity below 1 NTU for potable supply and total dissolved solids management for boiler feed applications. Its primary purpose is sustaining public health, economic output, and ecosystem integrity through reliable quality and quantity assurance. Wastewater treatment commands the largest revenue pool given capital intensity and regulatory compliance burdens, while desalinated water represents the fastest-growing product type as coastal megacities exhaust conventional sources. Reverse osmosis technology leads membrane-based desalination capacity additions, though UV treatment gains share in disinfection segments where chemical residual restrictions apply.
The EPA enforces maximum contaminant levels under the Safe Drinking Water Act, compelling municipal upgrades to filtration and disinfection infrastructure. REACH and the EU Drinking Water Directive impose substance-by-substance quality standards that reshape chemical treatment formulations across European supply chains. China's MEE administers surface water quality grading that restricts industrial discharge into designated functional zones. Stakeholders must monitor regulatory divergence between jurisdictions to align capital deployment with compliance timelines and technology selection.
Market Dynamics
Industrial withdrawal limits across China's Yangtze River Delta are forcing municipal utilities to redirect treated effluent toward manufacturing clusters, compressing the traditional potable-first hierarchy and accelerating membrane-based reuse infrastructure deployment.
Growth Catalysts
- EU Drinking Water Directive revision:Tightened contaminant thresholds in Europe are compelling filtration upgrades across municipal networks, expanding addressable demand for advanced oxidation and activated carbon systems.
- Informal settlement network expansion:Southeast Asian utilities are extending piped coverage to previously unserved urban peripheries, creating greenfield demand for compact treatment and distribution infrastructure.
- Reverse osmosis cost compression:Membrane manufacturing scale economies and energy recovery device improvements are reducing desalination unit costs, enabling coastal megacity adoption where conventional sources are exhausted.
Market Restraints
- Membrane supply concentration:High-performance polyamide thin-film composite production concentrates among a limited supplier base in East Asia, creating vulnerability to logistics disruptions and input price volatility.
- Energy intensity of desalination:Seawater reverse osmosis remains electricity-intensive, exposing operators to power price fluctuations that compress project returns in markets without subsidized industrial tariffs.
- Brine disposal constraints:Coastal discharge regulations under MEE functional zoning in China and similar frameworks elsewhere limit concentrate management options, adding permitting complexity and cost.
Strategic Opportunities
- Industrial offtake contracting:Manufacturing clusters facing withdrawal limits present long-term offtake agreements for reclaimed water, shifting municipal asset economics toward guaranteed industrial revenue streams.
- Digital twin integration:Convergence of hydraulic modeling with real-time sensor networks enables predictive maintenance and energy optimization, creating service revenue layers beyond equipment supply.
- UV-LED disinfection adoption:Mercury-free ultraviolet systems are penetrating food and beverage processing and pharmaceutical applications where chemical residual restrictions apply, opening premium positioning.
Industry Challenges
- Cross-connection control certification:Backflow prevention assembly testing and maintenance requires specialized technician credentials that lag installation growth, creating compliance bottlenecks in expanding service territories.
- Legacy SCADA integration:Municipal utilities operate decades-old control architectures that resist seamless connection to cloud-based analytics platforms, complicating smart network deployment timelines.
- PFAS destruction technology scale-up:Emerging contaminant remediation requires thermal or advanced oxidation processes that remain capital-intensive at municipal scale, stretching ratepayer-funded upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Market |
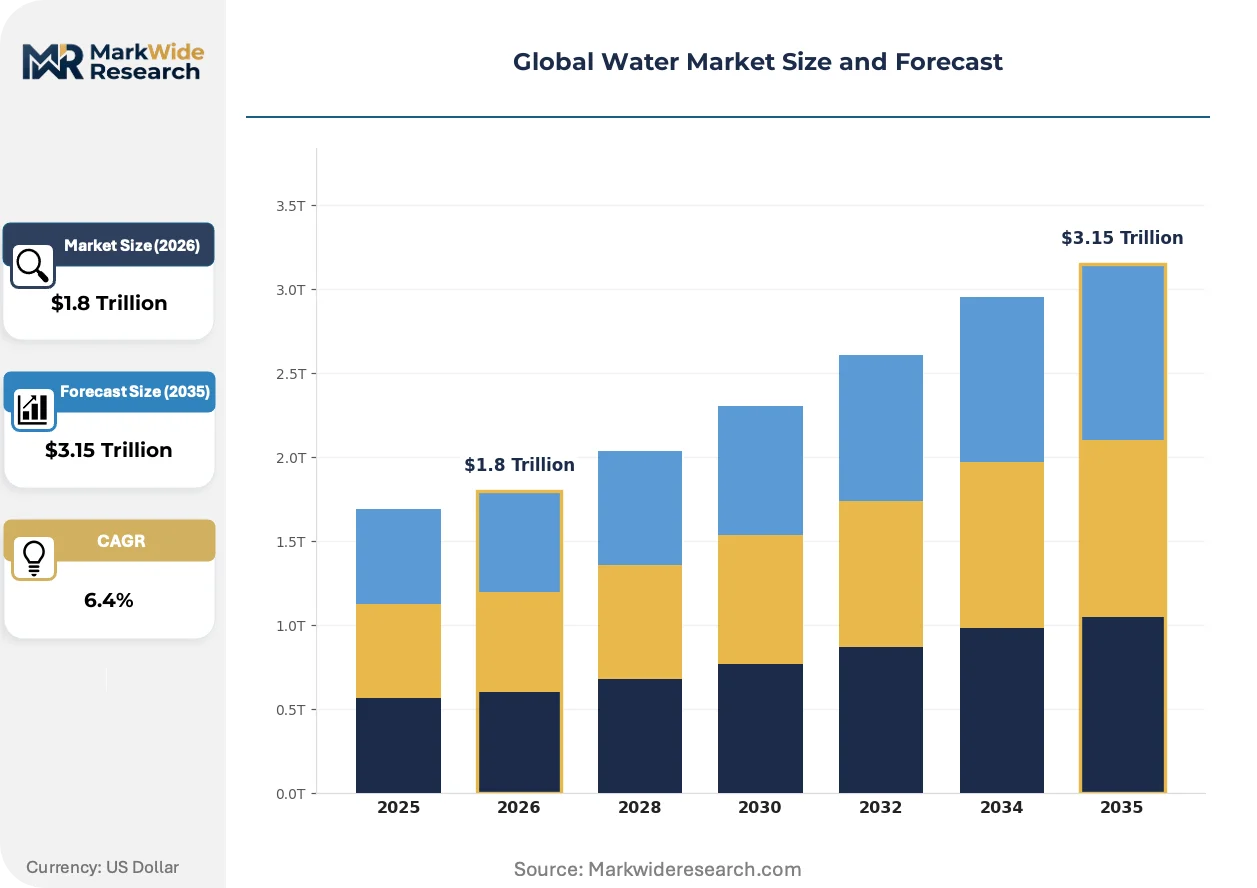
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $3.15 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinking Water, Wastewater, Desalinated Water, Industrial Water End User: Households, Municipalities, Industries, Agriculture Treatment Technology: Filtration, Reverse Osmosis, UV Treatment, Chemical Treatment Distribution Channel: Direct Supply, Retail, Online Sales, Wholesale |
| Companies Covered | Xylem, Severn Trent, American Water Works Company, Essential Utilities, Companhia de Saneamento Basico do Estado de Sao Paulo-SABESP, Veolia, United Utilities Group, VA Tech Wabag, Suez, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Market Strategic Shifts
Membrane technology advancement and regulatory contaminant scrutiny are converging to reshape treatment train configurations, with digital monitoring layers increasingly bundled as standard rather than premium offerings across municipal and industrial procurement.
Containerized reverse osmosis systems are overtaking permanent civil-structure desalination in coastal industrial zones and island municipalities. Mining operations in Chile and data center developers in Singapore are adopting modular configurations that slash commissioning timelines from years to months. This shift is compressing the traditional engineering-procurement-construction model and elevating equipment suppliers into integrated solution architects.
REACH substance-by-substance quality standards are reshaping chemical treatment formulations across European supply chains. The European Chemicals Agency's candidate list expansion is restricting coagulant and disinfectant byproduct profiles, forcing reformulation investments by water chemical suppliers. Municipal utilities in Germany and France are responding by diversifying supplier bases and tightening incoming material certification protocols.
Performance-based operating contracts are displacing traditional capital-sale models in municipal procurement across Australia and the Middle East. Suez and Veolia are anchoring long-term concession structures that transfer operational risk to private operators while municipalities retain asset ownership. This reconfiguration is most visible in Saudi Arabia's independent water and power projects and Victoria's desalination operating agreements, where availability payments dominate revenue structures.
Global Water Market Segmentation
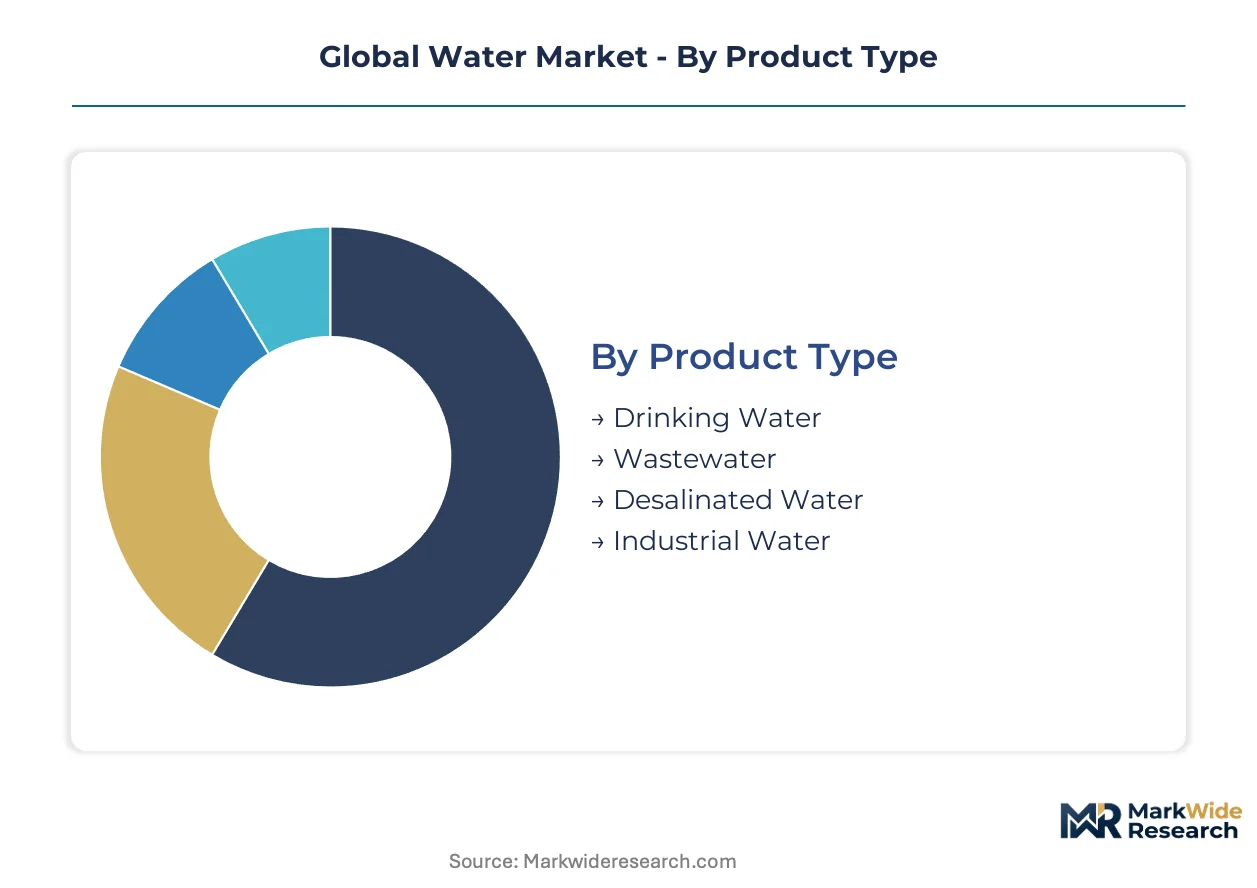
Segmentation reveals how water infrastructure investment fragments across distinct value pools and operational requirements. Treatment intensity, regulatory exposure, and customer concentration vary sharply by product type and end-use, reshaping vendor specialization and margin structures.
Product Type:
Standalone water products command dedicated infrastructure and discrete regulatory frameworks, while embedded categories integrate into broader industrial or municipal systems.
- Wastewater:Combines sewage collection, biological treatment, and tertiary polishing to meet discharge permits or reuse standards. Municipal utilities in China's Yangtze River Delta face MEE functional zoning mandates that accelerate membrane-based tertiary upgrades for industrial offtake.
- Desalinated Water:Seawater or brackish source conversion through reverse osmosis or thermal distillation, producing sub-500 mg/L TDS output. Coastal megacities in Saudi Arabia and Singapore exhaust conventional sources, expanding modular containerized capacity where civil-structure timelines fail.
- Drinking Water:Potable supply meeting WHO guidelines and national standards, typically sub-1 NTU turbidity. Treatment trains prioritize pathogen elimination and residual disinfection across piped distribution networks.
- Industrial Water:Process, cooling, and boiler feed supplies with application-specific purity grades. Semiconductor fabs and power plants drive ultra-pure and demineralized specifications.
Volume placements concentrate in Wastewater; the faster expansion belongs to Desalinated Water.
End User:
Customer concentration and procurement sophistication separate centralized bulk buyers from fragmented retail consumption.
- Industries:Manufacturing clusters negotiate long-term offtake agreements with guaranteed volume and quality specifications. Withdrawal limits across China's Yangtze River Delta compress supply security, redirecting municipal reclaimed water toward electronics and automotive plants.
- Municipalities:Public utilities manage integrated catchment-to-tap systems under ratepayer-funded capital cycles. EU Drinking Water Directive revisions tighten contaminant thresholds, compelling filtration upgrades across German and French networks.
- Households:Residential consumption spans piped utility supply, point-of-use treatment, and packaged alternatives. Informal settlement network expansion in Indonesia and Philippines creates greenfield demand for compact treatment.
- Agriculture:Irrigation withdrawals dominate freshwater consumption volumes, facing allocation restrictions and salinity management challenges in arid zones.
Revenue concentration sits with Municipalities; Industries are climbing the fastest as manufacturing water stress intensifies.
Treatment Technology:
Technology selection tracks source water quality, target contaminant profiles, and energy-chemical trade-offs.
- Reverse Osmosis:Pressure-driven membrane separation rejecting dissolved salts, organics, and pathogens. Coastal industrial zones and island municipalities adopt containerized configurations that compress commissioning timelines from years to months.
- Filtration:Granular media or membrane barriers removing particulates and microorganisms. Municipal utilities deploy advanced oxidation and activated carbon systems to meet EU tightened thresholds.
- UV Treatment:Ultraviolet irradiation disrupting pathogen DNA without chemical residuals. Food and beverage processors adopt UV-LED mercury-free systems where discharge restrictions apply.
- Chemical Treatment:Coagulation, disinfection, and pH adjustment using aluminum salts, chlorine, or alternative oxidants. REACH substance-by-substance standards force reformulation investments across European supply chains.
Installed base dominance belongs to Filtration; Reverse Osmosis shows the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects product bulk, urgency, and relationship intensity requirements.
- Direct Supply:Long-term concession contracts and availability-based operating agreements. Suez and Veolia anchor Saudi independent water projects and Victoria desalination structures.
- Wholesale:Bulk transfer between utilities, industrial parks, and agricultural districts. China's water rights trading pilots facilitate inter-basin transfers under MEE supervision.
- Retail:Packaged and point-of-use products through commercial outlets. Urban household penetration drives bottled and dispenser-based segments.
- Online Sales:E-commerce platforms for replacement membranes, filters, and residential treatment systems. Aftermarket consumables concentrate here.
Contract value aggregates in Direct Supply; Online Sales are gaining share fastest in aftermarket consumables.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate industrial water reuse infrastructure investment as manufacturing clusters exhaust withdrawal quotas. China's MEE functional zoning restricts discharge into designated water bodies, redirecting municipal treated effluent toward electronics and automotive plants. Singapore's Jurong Island petrochemical complex anchors Southeast Asia's largest industrial water recycling facility.
China
Yangtze River Delta manufacturing clusters face MEE-administered withdrawal limits that compress supply security for semiconductor fabs. The MEE surface water quality grading system designates functional zones where industrial discharge faces escalating restrictions. Shanghai and Suzhou municipal utilities redirect tertiary-treated effluent toward electronics plants, accelerating membrane bioreactor deployments.
United States
EPA Safe Drinking Water Act enforcement compels municipal filtration upgrades in legacy rust-belt distribution networks. Maximum contaminant level revisions for emerging contaminants drive activated carbon and advanced oxidation procurement across Great Lakes states. California's Central Valley agricultural districts confront groundwater sustainability mandates that restrict irrigation allocations.
Germany
REACH substance-by-substance standards reshape coagulant and disinfectant formulations across Rhine-Ruhr industrial corridors. The EU Drinking Water Directive revision tightens threshold limits for microplastics and PFAS precursors, compelling Ruhrverband and other utilities to diversify chemical supplier bases. Bavarian municipalities deploy advanced oxidation for pharmaceutical metabolite removal.
Saudi Arabia
Independent water and power projects concentrate desalination capacity along the Red Sea coast under availability-based concession structures. The Saline Water Conversion Corporation oversees procurement frameworks that transfer operational risk to private operators. Jubail Industrial City anchors the kingdom's largest integrated water-power complex serving petrochemical clusters.
Singapore
NEWater facilities supply reclaimed water to Jurong Island semiconductor and pharmaceutical plants under long-term offtake agreements. The Public Utilities Board's Four National Taps strategy diversifies supply sources through advanced membrane reclamation. Tuas Nexus integrates waste-to-energy with water treatment in the city-state's western industrial zone.
Global Water Market Competitive Environment
Top-tier vendors anchor multi-decade concession contracts, while mid-tier equipment suppliers compete on modular system integration. The vendor base stratifies across operational risk-bearing concessionaires, technology-agnostic EPC contractors, and component-specialized membrane fabricators. Strategic archetypes include full-cycle operators, digital monitoring integrators, and containerized system packagers. Competitive moves center on performance-based contracting displacement of capital sales and predictive maintenance service layering.
Among French-based full-cycle operators, Veolia and Suez occupy positions spanning municipal concession and industrial outsourcing contracts. Xylem exemplifies the digital monitoring archetype through sensor-network and hydraulic modeling integration. These three anchors represent distinct competitive vectors: operational risk absorption, technology platform bundling, and smart infrastructure deployment.
| Leading Market Players |
|---|
| Xylem |
| Severn Trent |
| American Water Works Company |
| Essential Utilities |
| Companhia de Saneamento Basico do Estado de Sao Paulo-SABESP |
| Veolia |
| United Utilities Group |
| VA Tech Wabag |
| Suez |
| Others |
Value Chain & Pricing Dynamics
Backward integration into membrane manufacturing anchors both supply security and pricing power for tier-one desalination contractors, compressing margins for equipment-only vendors who source polyamide thin-film composites from concentrated East Asian suppliers.
Pricing Analysis
Short lead-time premiums command substantial markups in containerized reverse osmosis procurement, where mining operations in Chile and data center developers in Singapore pay availability premiums against 18-24 month civil-structure alternatives. Three-tier pricing structure across premium, standard, and economy levels separates full-service concession operators from modular equipment suppliers and aftermarket consumables vendors. Cost compression in standard-tier membrane systems is intensifying because energy recovery device improvements and manufacturing scale economies are eroding incumbent technology premiums. Municipal utilities exhibit highest price sensitivity due to ratepayer-funded capital cycles, while semiconductor fabs demonstrate lowest sensitivity given ultra-pure water specifications that override cost considerations.
Supply Chain Analysis
Direct-to-municipal channels anchor hyperscale project demand, with Suez and Veolia operating integrated engineering-procurement-construction arms that bypass traditional distributor networks. High-performance polyamide thin-film composite production concentrates in Japan, South Korea, and China, creating geographic supply concentration that amplifies logistics disruption vulnerability. Membrane manufacturing draws from specialized petrochemical feedstocks, precision coating equipment, and proprietary interfacial polymerization chemistries. Single-source vulnerability runs through the limited qualified supplier base for seawater reverse osmosis energy recovery devices. Distribution runs through long-term concession contracts and availability-based operating agreements that transfer operational risk to private operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
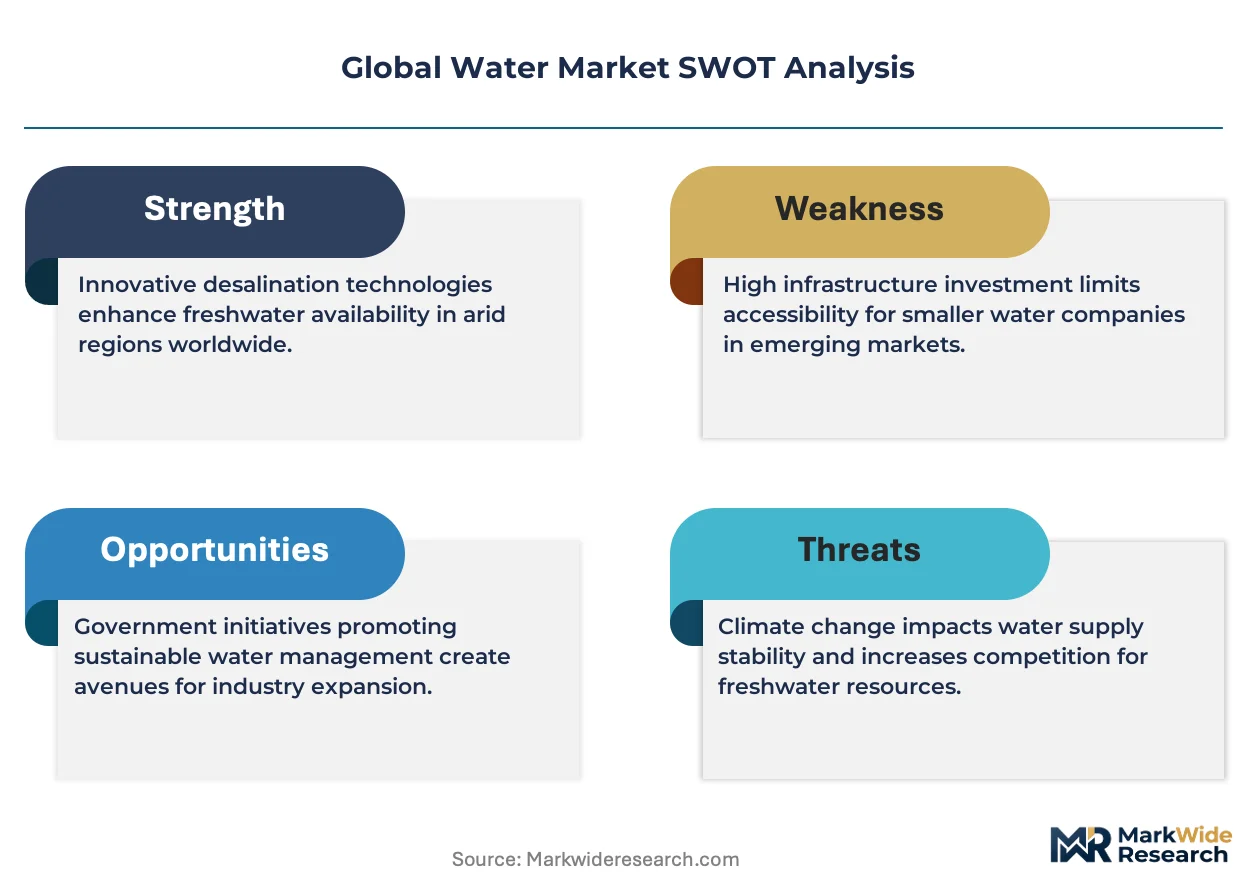
This market reads as a cost-of-compliance story: the EU Drinking Water Directive revision tightens contaminant thresholds for microplastics and PFAS precursors, erecting capital-intensive barrier-to-entry moats that favor incumbent operators with diversified chemical supplier bases and advanced oxidation infrastructure already deployed.
For Market Incumbents: Anticipate membrane supply concentration risk by qualifying secondary polyamide thin-film composite sources outside East Asia, while accelerating digital twin integration to anchor predictive maintenance service revenues that resist pure-equipment commoditization. Defensive consolidation should target containerized system packagers in coastal industrial zones to capture modular deployment growth displacing civil-structure timelines. For New Entrants and Emerging Players: UV-LED mercury-free disinfection systems offer technology-first wedge positioning in food and beverage processing and pharmaceutical applications where chemical residual restrictions apply. White-space targets include informal settlement network expansion across Indonesia and Philippines for compact treatment infrastructure, and industrial offtake contracting in China's Yangtze River Delta where withdrawal limits redirect municipal effluent toward manufacturing clusters. Go-to-market should emphasize performance-based operating contracts that transfer availability risk from municipal ratepayers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-cycle operators seeking digital monitoring capabilities and regional concession footprints. Long-term viability favors vendors with integrated operational risk-bearing contracts rather than pure equipment exposure. Acquisition target archetype: mid-tier membrane system integrators with demonstrated project execution in Saudi independent water projects or Australian desalination operating agreements. Signal to watch is MEE functional zoning enforcement intensity across Chinese industrial corridors, which accelerates membrane-based reuse infrastructure deployment and redirects capital flows toward compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Operating Contract | Veolia and Suez anchor Saudi independent water projects under availability payment structures that transfer operational risk. |
| Digital Twin Integration | Xylem bundles sensor networks with hydraulic modeling to create predictive maintenance revenue layers beyond equipment supply. |
| Containerized System Deployment | Modular reverse osmosis configurations compress commissioning timelines from years to months for Chilean mining and Singapore data centers. |
| Backward Integration into Membrane Manufacturing | Captive polyamide thin-film composite production insulates tier-one contractors from East Asian supply concentration vulnerability. |
| UV-LED Disinfection Scale-Up | Mercury-free ultraviolet systems penetrate food and beverage processing where REACH substance-by-substance standards restrict chemical residuals. |
Study Parameters
Multi-period observation of membrane capacity additions, MEE functional zoning enforcement patterns, and EU Drinking Water Directive implementation timelines anchored the trend analysis, supplemented by interviews with municipal utility planning officers, desalination project developers, membrane technology R&D directors, and chemical treatment procurement leads. Secondary validation drew from EPA Safe Drinking Water Act filings, MEE surface water quality grading disclosures, ECHA candidate list expansions, and independent water project procurement databases. Bottom-up project pipeline assessment and top-down regulatory impact modeling were triangulated to cross-verify investment flow estimates.
Input-output matrices mapped treatment technology adoption against regulatory compliance deadlines, industrial withdrawal limit enforcement, and coastal megacity source exhaustion patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user concentration, treatment technology performance tier, and distribution channel relationship intensity. CAGRs were derived from regression analysis of historical capacity deployment correlated with regulatory milestone timing. Industry-specific forecast inputs incorporated energy recovery device efficiency curves and membrane replacement cycle economics.
Several conditions sit outside the modeled scope, including sovereign debt distress impacts on municipal capital cycles, breakthrough non-membrane desalination technology commercialization, and abrupt PFAS destruction technology cost reductions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial water demand elasticity. Periodic stress-testing of base assumptions is recommended against MEE zoning expansion velocity and EU Drinking Water Directive revision implementation delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Mexico Water Consumption Market
Water Management
Water Trading Market
Water Management
Smart Water Network Market
Water Management
Water Utility Services Market
Water Management
Chile Water Consumption Market
Water Management
Water Filters Market
Water Management
Smart Water Management Market
Water Management
Municipal Water Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Spain Water Consumption Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Asia-Pacific Water Sink Market
Water Management
North America Water Sink Market
Water Management
Water Free Urinals Market
Water Management
France Water Consumption Market
Water Management
Middle East and Africa Water Sink Market