
 Water Free Urinals Market | 2026-2036
Water Free Urinals Market Size, Share, and Industry Trends Forecast 2026-2036
Water Free Urinals Market Intelligence
WaterSense-certified specification tiers is collapsing the gap between premium and standard product lines across the water free urinals market. Falcon Water Technologies leverages proprietary cartridge technology to sustain differentiation in high-traffic commercial environments. Kohler Co. anchors its position through extensive distribution networks and brand recognition among institutional buyers. Sloan Valve Company competes on manufacturing scale, while URIMAT Schweiz AG specializes in European-engineered designs with advanced odor-sealing mechanisms.
Water free urinals function as plumbing fixtures that operate without flush water, typically employing sealed cartridges with lighter-than-air trap fluids or one-way valve membranes to block sewer gases while allowing waste passage; these systems reduce water consumption to zero liters per use versus conventional models requiring up to six liters. Wall-mounted configurations dominate commercial specifications due to space efficiency and cleaning access, while retrofits represent the fastest-growing installation category as building owners seek LEED certification without full restroom reconstruction. Ceramic materials lead the material mix for durability and aesthetic alignment with premium commercial interiors, though stainless steel variants occupy niche positions in high-abuse environments such as transportation terminals.
EPA WaterSense labeling shapes product eligibility for federal procurement and rebate programs across the United States, while the EU Green Deal and national building efficiency codes in Germany and France mandate water reduction targets that directly specify waterless fixtures. California Title 24 building standards and Texas municipal conservation ordinances create localized demand accelerators that manufacturers must navigate for market access. Stakeholders should monitor evolving state-level plumbing code amendments and cartridge replacement service models as determinants of long-term customer lifetime value and competitive positioning.
Market Dynamics
Water conservation mandates in drought-prone jurisdictions are compressing specification timelines for commercial restroom retrofits, forcing building operators to choose between cartridge-based and valve-membrane systems under accelerated procurement cycles.
Growth Catalysts
- California Title 24:Building standards in California mandate water reduction targets that directly specify waterless fixtures for new commercial construction and major renovations.
- Stadium retrofits:Sports venue operators across Texas and Arizona are replacing conventional fixtures during offseason maintenance windows to secure utility rebates.
- LEED certification pathways:The U.S. Green Building Council awards points for water efficiency that accelerate water free urinal specification in office and hospitality projects.
Market Restraints
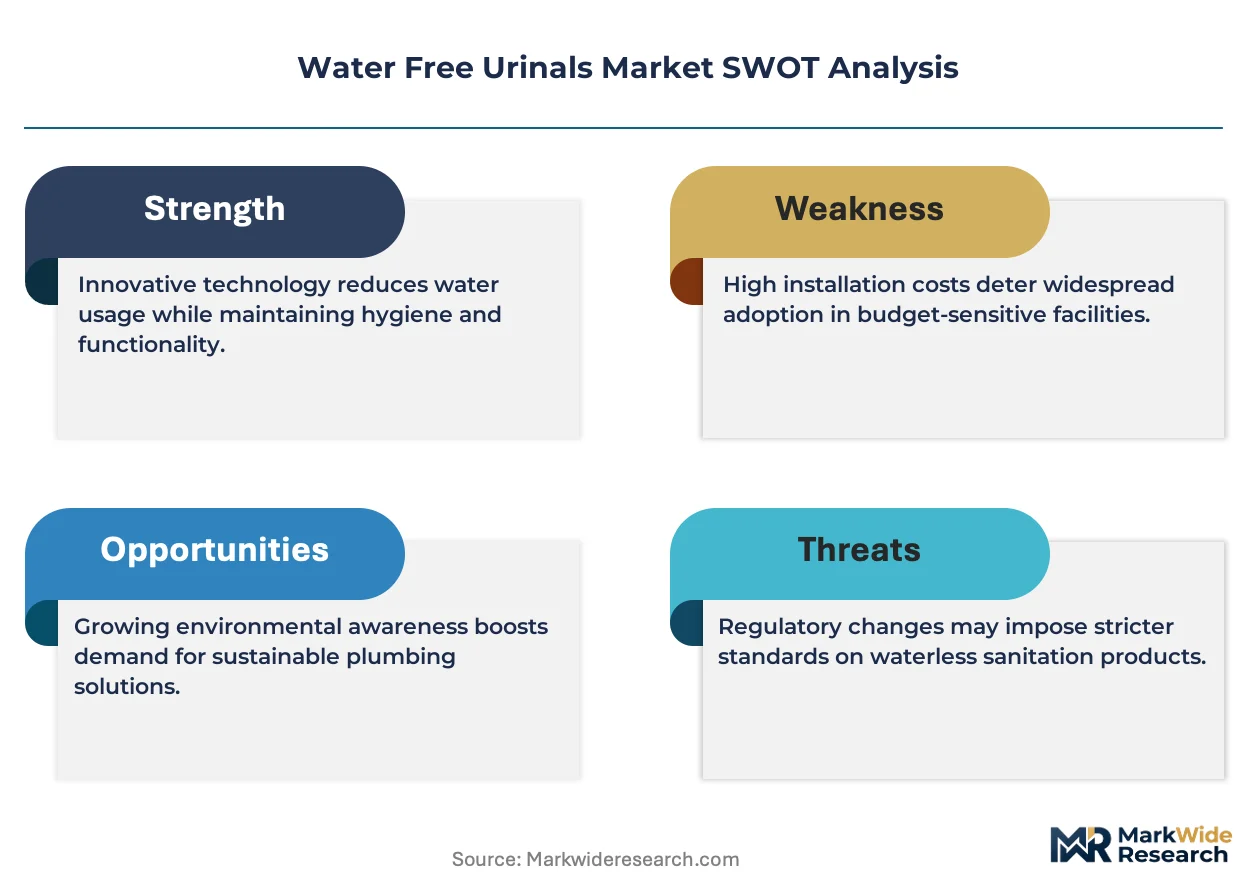
- Cartridge replacement costs:Ongoing consumable expenses for sealed trap fluid cartridges create lifetime cost uncertainty versus one-time fixture purchases.
- Plumber training gaps:Licensed tradespeople in older metropolitan areas lack familiarity with odor-seal maintenance protocols, slowing installation velocity.
- Code variance friction:Municipal plumbing inspectors in jurisdictions without waterless fixture precedent apply inconsistent interpretation of IPC and UPC amendments.
Strategic Opportunities
- German building efficiency codes:The EU Green Deal and national standards in Germany mandate water reduction targets that create specification pull for European-engineered systems.
- Airport terminal expansions:Hub renovation projects in the United Arab Emirates and Saudi Arabia specify waterless fixtures to reduce operational water burden in arid climates.
- Service bundling models:Manufacturers can capture recurring revenue through cartridge subscription programs tied to facility management contracts.
Industry Challenges
- Legacy drain compatibility:Aging building infrastructure with cast iron drainage and inadequate slope complicates retrofit installations and triggers costly plumbing modifications.
- Standardization delays:Inconsistent ASME and CSA testing protocols for odor-seal longevity create specification uncertainty among institutional buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Free Urinals Market |
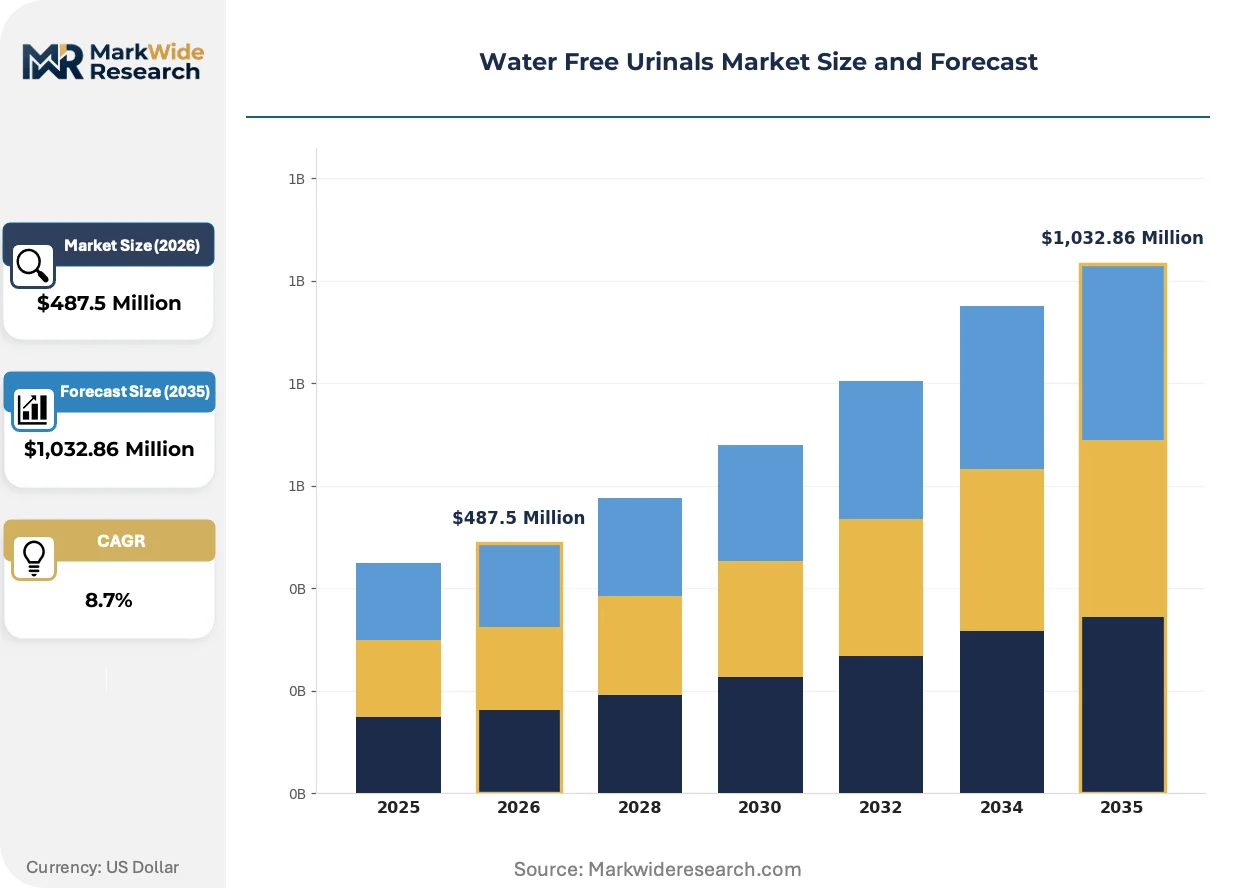
| Market Size in 2026 | $487.5 Million |
| Market Size in 2035 | $1,032.86 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Standing, Portable, Custom Designs End User: Commercial Buildings, Educational Institutions, Airports, Public Restrooms Material: Ceramic, Plastic, Stainless Steel, Composite Materials Installation Type: New Installations, Retrofits, DIY Kits, Professional Installations |
| Companies Covered | Falcon Water Technologies, Kohler Co., Zurn Industries, Waterless Co. Inc., URIMAT Schweiz AG, Villeroy & Boch AG, Duravit AG, Sloan Valve Company, Hindware Homes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Free Urinals Market Strategic Shifts & Innovations
Product engineering is splitting between disposable cartridge systems and permanent valve-membrane designs, each path carrying distinct implications for manufacturer revenue models and facility operator maintenance burdens.
Biodegradable trap fluid formulations are bifurcating the sealed-cartridge segment. These plant-derived alternatives replace petroleum-based sealants to meet corporate sustainability procurement criteria. Large office landlords in California and New York specify biodegradable fluids for tenant-facing environmental reporting. The shift is compressing margins for conventional cartridge suppliers while opening premium pricing tiers for bio-based certification.
EPA WaterSense labeling expansion is tightening eligibility criteria for federal procurement and municipal rebate programs. Manufacturers must submit third-party performance data on odor-seal longevity and drain line protection. Commercial building operators in Texas and Florida increasingly filter specification shortlists to WaterSense-certified products exclusively, marginalizing uncertified competitors from public-sector opportunities.
Facility management outsourcing is consolidating purchasing authority for restroom fixtures under national service providers. These multi-site operators standardize across property portfolios to simplify maintenance training and spare parts inventory. Water free urinal selection now flows through procurement teams at Aramark, Sodexo, and Compass Group rather than individual building engineers, compressing vendor diversity and favoring suppliers with national service networks.
Water Free Urinals Market Segmentation
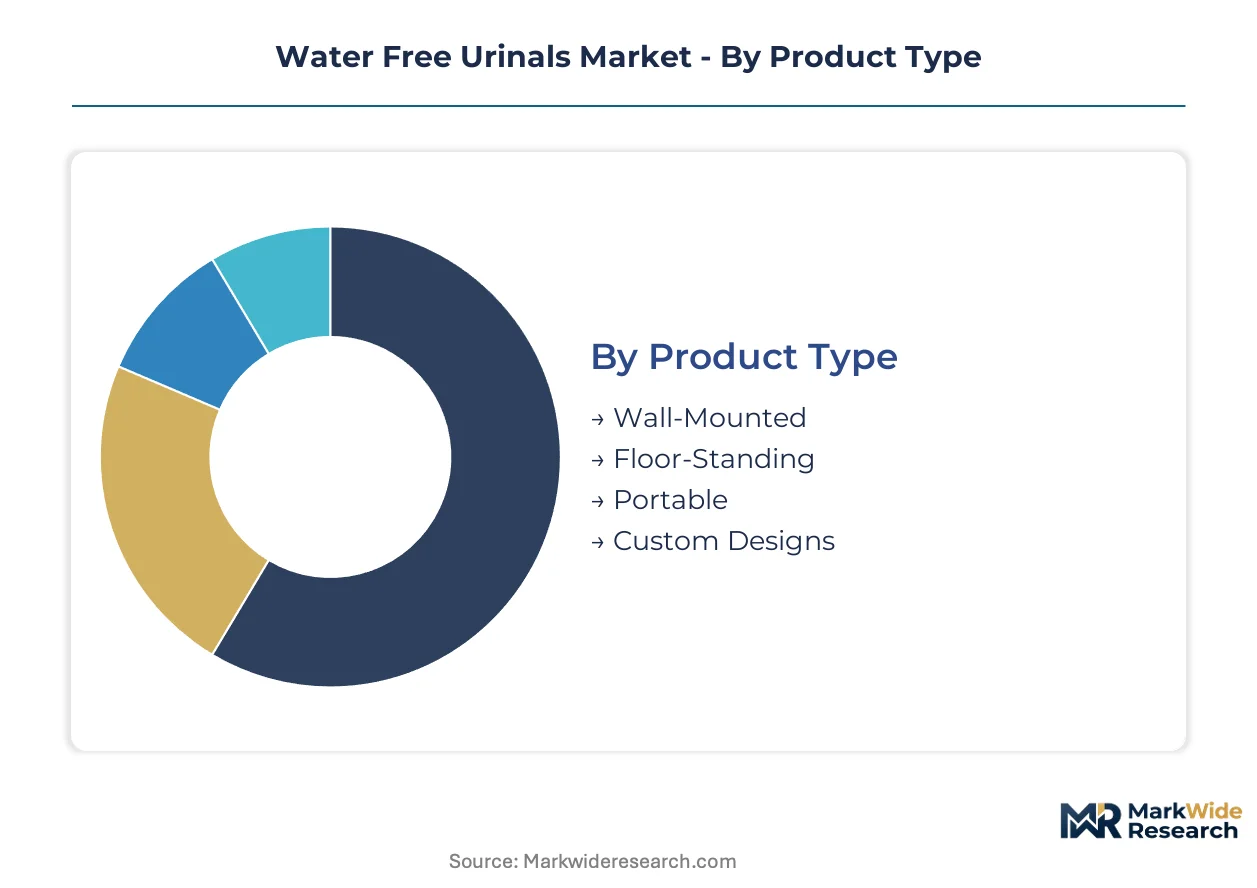
Water free urinal segmentation reveals distinct procurement pathways where facility managers, contractors, and institutional buyers prioritize different performance attributes. Channel dynamics vary sharply between new construction specifications and aftermarket retrofit decisions.
Product Type:
Distribution channels diverge sharply by mounting configuration, with commercial contractors sourcing wall-mounted units through plumbing wholesalers while portable variants flow through janitorial supply catalogs.
- Wall-Mounted:Space-efficient configurations attach directly to vertical surfaces with concealed drainage connections. Demand concentrates in California office towers and Texas stadium renovations where Title 24 compliance and utility rebate programs drive specification. Falcon Water Technologies and Kohler Co. dominate this channel through specification-grade distribution networks.
- Floor-Standing:Freestanding pedestal designs accommodate slab-mounted drainage without wall reinforcement. Sports venues in Arizona and hospitality projects in Florida specify these for high-traffic durability. This segment carries higher freight costs but simplifies installation in buildings with structural wall limitations.
- Portable:Self-contained mobile units serve temporary event infrastructure and construction sites. Event rental companies in Nevada and festival operators in Georgia drive seasonal demand spikes. These units bypass permanent plumbing entirely through sealed waste containment systems.
- Custom Designs:Architect-specified variants match interior aesthetics for premium hospitality and corporate headquarters. Manhattan luxury developments and Dubai commercial towers commission these for brand-aligned restroom environments.
Wall-mounted configurations dominate installed base. Portable units are where expansion concentrates for temporary infrastructure applications.
End User:
Volume tiers separate institutional buyers with centralized procurement from fragmented commercial operators making site-level decisions.
- Commercial Buildings:Office landlords and retail property managers specify water free urinals for LEED point accumulation and operational cost reduction. Class-A towers in Chicago and Houston lead adoption through sustainability-driven tenant demands. This segment generates the highest cartridge replacement revenue through multi-year service contracts.
- Airports:Hub terminal operators prioritize odor-seal reliability and vandal resistance over upfront cost. Dallas-Fort Worth International Airport and Denver International Airport retrofits demonstrate specification pull for stainless steel variants in high-abuse environments. Extended dwell times amplify water savings calculations versus conventional fixtures.
- Educational Institutions:University facilities departments balance budget constraints against maintenance simplicity. State university systems in California and Texas aggregate purchasing through cooperative contracts. K-12 districts lag due to custodial staff training limitations.
- Public Restrooms:Municipal park and transit authority installations face vandalism and theft exposure. Cities with water scarcity mandates in New Mexico and Colorado specify these despite higher lifecycle costs. Procurement flows through public works departments with extended bid cycles.
Commercial buildings dominate installed base. Airports are climbing the fastest for specification-grade retrofits.
Material:
Cost structure and durability requirements split procurement between premium ceramic specifications and utilitarian alternatives.
- Ceramic:Vitreous china surfaces provide aesthetic alignment with upscale commercial interiors and superior stain resistance. Corporate headquarters in New York and hospitality chains in Miami specify these for tenant-facing installations. This material commands price premiums through design-conscious specifier influence.
- Stainless Steel:Brushed or polished finishes withstand impact and graffiti removal in transportation terminals and correctional facilities. Chicago Transit Authority and Port Authority of New York and New Jersey installations demonstrate specification pull. Higher material costs offset reduced replacement frequency.
- Plastic:Polymer composites reduce unit weight and shipping expense for budget-constrained projects. Modular office construction and temporary facilities in Texas and Florida specify these for cost minimization. UV degradation limits outdoor applications.
- Composite Materials:Engineered stone and resin blends balance weight reduction with surface durability. Emerging specifications in sustainable building projects seek recycled content credentials. Limited production scale constrains availability.
Ceramic dominates installed base. Stainless steel is gaining share fastest for high-abuse environment specifications.
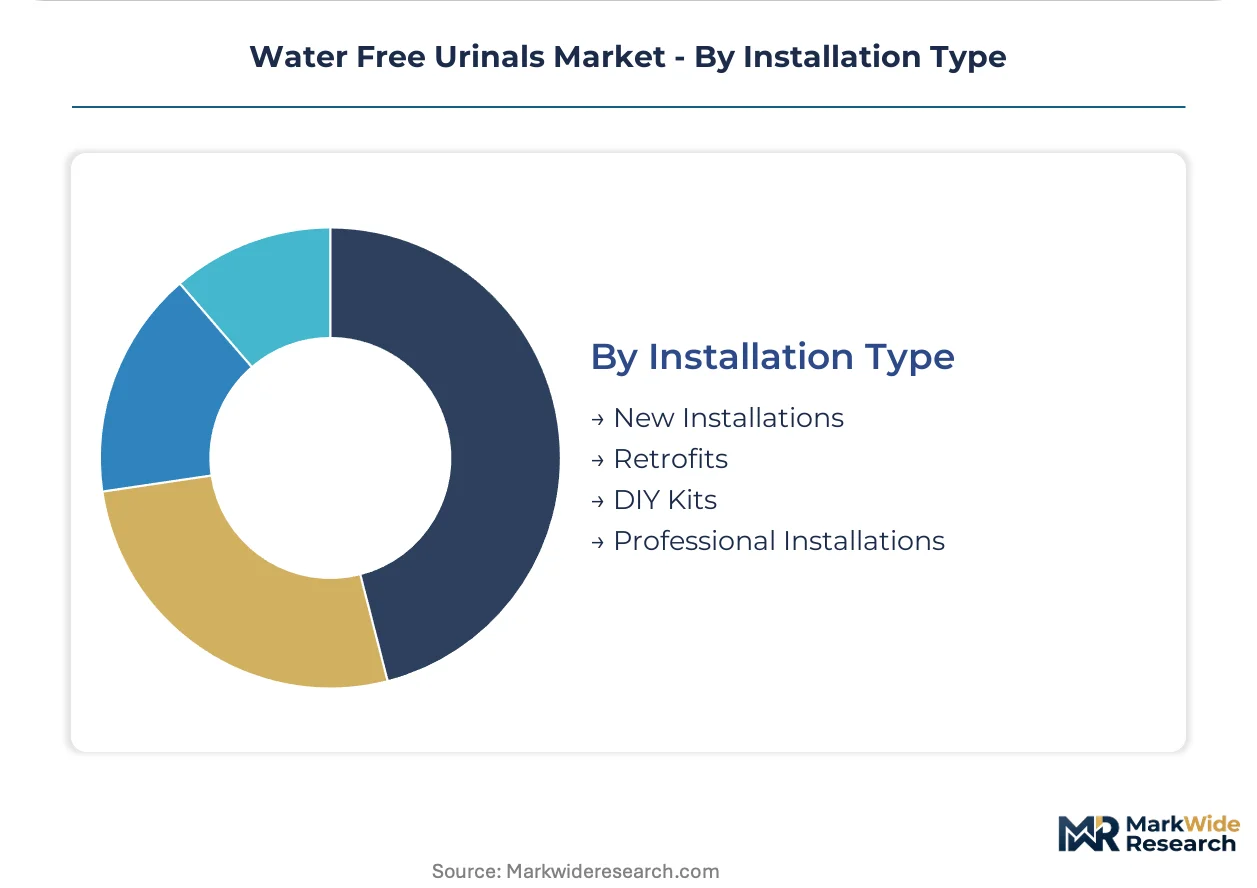
Installation Type:
Customer capability and project timeline determine whether units flow through professional contractor channels or direct-to-facility supply.
- Retrofits:Existing building modifications require drain line assessment and potential slope correction. California Title 24 triggered renovations and Texas municipal rebate programs concentrate demand here. Professional installation dominates due to odor-seal calibration complexity.
- New Installations:Ground-up construction allows optimized drain routing and fixture placement. Commercial developers in Arizona and Nevada specify these during core-and-shell phases. Plumbing contractors bundle specification with broader restroom packages.
- Professional Installations:Licensed plumber deployment ensures code compliance and warranty validation. Institutional buyers mandate this channel for risk transfer. Service bundling with cartridge subscription programs is emerging.
- DIY Kits:Pre-configured packages target small commercial operators and religious facilities with in-house maintenance staff. Limited adoption due to odor-seal calibration requirements and code inspection variability.
Retrofits dominate installed base. New installations are where expansion concentrates for greenfield commercial development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in water free urinals tilt toward import dependence in water-stressed regions lacking domestic manufacturing scale. Export capacity concentrates in Germany, Switzerland, and the United States where engineering standards and certification infrastructure support outbound shipment.
United States
California Title 24 building standards and Texas municipal conservation ordinances drive specification volume. EPA WaterSense labeling determines eligibility for federal procurement and utility rebate programs. Dallas-Fort Worth International Airport and Denver International Airport anchor demand for stainless steel variants in high-traffic retrofits.
Germany
The EU Green Deal and national building efficiency codes mandate water reduction targets that specify waterless fixtures for commercial construction. REACH compliance requirements shape trap fluid formulation standards. Engineering clusters in North Rhine-Westphalia and Baden-Württemberg concentrate manufacturing of European-designed systems with advanced odor-sealing mechanisms.
United Arab Emirates
Hub terminal expansions at Dubai International Airport and Abu Dhabi International Airport specify waterless fixtures to reduce operational water burden in arid climates. MOHAP building codes increasingly reference water efficiency targets for public infrastructure. NEOM development projects in the northwest region incorporate conservation fixtures in smart city construction.
Saudi Arabia
Giga-project construction under Vision 2030 creates specification pull for waterless restroom systems in hospitality and commercial developments. SFDA building product registration requirements influence import sourcing decisions. Riyadh and the Eastern Province concentrate demand from airport renovations and corporate headquarters construction.
India
Bureau of Indian Standards water efficiency guidelines and state-level municipal conservation programs accelerate adoption in commercial buildings. Maharashtra and Karnataka lead specification through LEED-certified office developments in Mumbai and Bangalore. Hindware Homes anchors domestic manufacturing capacity for cost-sensitive institutional procurement.
Water Free Urinals Market Key Industry Players
Concentration sits with diversified plumbing fixture conglomerates and specialized water conservation technology developers. The vendor base splits between multinational bathroom product manufacturers with established distribution networks and focused innovators competing on cartridge engineering. Two strategic archetypes dominate: specification-grade system integrators bundling installation with maintenance contracts, and component specialists supplying sealed trap technologies to third-party assemblers. Competitive moves center on geographic expansion through local manufacturing partnerships and technology licensing agreements for biodegradable sealant formulations.
Among North American specialists, Falcon Water Technologies and Waterless Co. Inc. exemplify the engineering-focused archetype with proprietary sealing mechanisms. Sloan Valve Company anchors the diversified industrial segment with manufacturing scale and institutional channel access. European positioning is occupied by URIMAT Schweiz AG and Villeroy & Boch AG, representing Swiss precision engineering and German bathroom fixture heritage respectively. These five entities collectively illustrate the geographic and technological bifurcation shaping competitive dynamics.
| Leading Market Players |
|---|
| Falcon Water Technologies |
| Kohler Co. |
| Zurn Industries |
| Waterless Co. Inc. |
| URIMAT Schweiz AG |
| Villeroy & Boch AG |
| Duravit AG |
| Sloan Valve Company |
| Hindware Homes |
| Others |
Cost & Logistics Intelligence
Manufacturing scale at German and Swiss engineering clusters compresses unit economics for sealed-cartridge systems while establishing price floors for biodegradable trap fluid variants. Capacity utilization at North American ceramic foundries shapes margin structures across wall-mounted specifications, with EPA WaterSense certification tiers creating discrete pricing bands that resist commoditization.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the water free urinals market. Price differentiation rests on EPA WaterSense certification grade and cartridge subscription bundling, with certified systems commanding measurable premiums over uncertified alternatives. Pricing pressure stems from biodegradable fluid formulations compressing margins for petroleum-based sealant suppliers. Municipal procurement offices exhibit highest price sensitivity due to extended bid cycles, while airport terminal operators prioritize odor-seal reliability over upfront cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes complicate inbound logistics for ceramic vitreous china sourced from manufacturing clusters in Germany and China. Geographic supply concentration centers on Germany, Switzerland, and the United States for precision-engineered sealing mechanisms, while India anchors cost-sensitive ceramic production. Raw material dependencies include petroleum-based and plant-derived trap fluids, vitreous china, and stainless steel alloys. Single-source vulnerability for proprietary cartridge formulations creates structural risk. Distribution runs through plumbing wholesalers for commercial contractors and direct facility management contracts for national service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Title 24 mandates and EU Green Deal water efficiency targets are accelerating specification velocity beyond historical retrofit cycles, positioning water free urinals as a regulatory-driven infrastructure disruption.
For Market Incumbents: Consolidate cartridge replacement service networks to lock in recurring revenue streams before facility management outsourcing further concentrates purchasing authority. Acquire biodegradable trap fluid formulation capabilities to defend margin position against sustainability-driven procurement criteria. Vertical integration into trap fluid chemistry reduces exposure to petroleum-based supply cost volatility. For New Entrants and Emerging Players: Aftermarket cartridge subscription gaps in the K-12 educational segment offer white-space expansion where custodial training limitations have slowed incumbent penetration. Portable unit rental networks for temporary event infrastructure remain underdeveloped relative to permanent fixture saturation. A direct-to-facility cartridge replenishment platform bypasses wholesale channel capture by established distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cartridge-subscription specialists with facility management contract integration. Long-term viability favors engineering-focused archetypes with proprietary sealing intellectual property over pure-play assemblers. Watch state-level plumbing code amendment velocity as the signal indicating specification acceleration or regulatory friction.| Strategic Initiative | Industry Significance |
|---|---|
| Cartridge Subscription Platform Launch | Captures recurring revenue from Texas and California municipal rebate program participants. |
| Biodegradable Trap Fluid Certification | Unlocks premium pricing tiers for corporate sustainability procurement in New York and California. |
| Facility Management Partnership | Secures standardized specification across Aramark and Sodexo multi-site property portfolios. |
| German Manufacturing Scale-Up | Positions production capacity for EU Green Deal-mandated water efficiency code compliance. |
| Airport Terminal Retrofit Specialization | Addresses high-abuse environment demand from Dallas-Fort Worth and Denver International Airport expansions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities directors at Class-A commercial towers, plumbing contractors specializing in Title 24 retrofits, procurement managers at national airport authorities, and cartridge replacement service technicians. Secondary validation drew from EPA WaterSense certification databases, California Energy Commission building standard filings, EU Green Deal implementation progress reports, and customs trade data on ceramic fixture imports. Bottom-up unit economics triangulated against top-down construction spending forecasts across the analysis window.
Across the modeling period, volume projections incorporated mounting configuration splits, end-use segment penetration curves, and material substitution dynamics between ceramic and stainless steel variants. CAGRs were derived from fitted growth curves calibrated to regulatory mandate implementation timelines and utility rebate program enrollment trajectories. Industry-specific inputs included cartridge replacement frequency data from high-traffic commercial installations and odor-seal longevity testing protocols under ASME standards.
Underlying assumptions cover sustained enforcement of California Title 24 and Texas municipal conservation ordinances, with deviation risk concentrated in municipal plumbing inspector training gaps and inconsistent IPC amendment interpretation. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Mexico Water Consumption Market
Water Management
Spain Water Consumption Market
Water Management
Global Water Market
Water Management
France Water Consumption Market
Water Management
Chile Water Consumption Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Water Filters Market
Water Management
Middle East and Africa Water Sink Market
Water Management
NRW Smart Leak Management Market
Water Management
Water Utility Services Market
Water Management
Municipal Water Market
Water Management
Asia-Pacific Water Sink Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Smart Water Network Market
Water Management
Smart Water Management Market
Water Management
North America Water Sink Market