
 Water Trading Market | 2026-2036
Water Trading Market Size, Share, and Industry Trends Forecast 2026-2036
Water Trading Market Outlook
The EU Water Framework Directive is shifting demand toward transparent, exchange-traded water rights across member states with stressed river basins. Veolia leverages its integrated utility footprint to anchor trading operations in France and Southern Europe. Xylem specializes in digital metering infrastructure that underpins volume verification for spot-market transactions. American Water competes through regulatory relationships that ease permit-transfer approvals in eastern US watersheds.
Water trading encompasses the legal transfer of quantified water-use entitlements between holders through bilateral negotiation or organized exchange platforms, typically measured in acre-feet or megalitres with delivery obligations tied to specific infrastructure nodes. The mechanism reallocates scarce freshwater resources from lower-value to higher-value economic uses without requiring new supply development. Spot market transactions dominate liquidity in regions with transparent price discovery, while forward contracts are gaining structural share among agricultural buyers seeking irrigation cost certainty across growing seasons. Recycled water represents the fastest-growing source category as industrial offtakers in water-stressed manufacturing clusters pursue ESG-aligned supply alternatives.
The US EPA enforces Clean Water Act standards that define tradable pollutant loads intersecting with water rights, while Australia's MDBA administers basin-scale caps that create scarcity-driven exchange dynamics. The EU Green Deal's nature restoration requirements are tightening abstraction permits and expanding the addressable pool of tradeable entitlements. Stakeholders must monitor how groundwater sustainability agencies in California and comparable jurisdictions translate cutback mandates into transferable credit architectures.
Market Dynamics
Groundwater sustainability mandates in California's Central Valley are compressing supply availability and forcing agricultural holders toward spot-market liquidity, while Australia's Murray-Darling Basin Authority tightens extraction caps that entrench scarcity pricing across entitlement exchanges.
Growth Catalysts
- EU Water Framework Directive:Abstraction limits in stressed river basins across France, Spain, and Italy are converting static permits into tradeable assets, expanding the addressable pool of transferable entitlements.
- Recycled water infrastructure:Industrial clusters in water-stressed manufacturing zones are pursuing ESG-aligned supply alternatives, creating new source categories for market participation.
- Chronic drought patterns:Australia's agricultural irrigation districts are expanding participation in entitlement exchanges as surface water reliability deteriorates across the Murray-Darling Basin.
Market Restraints
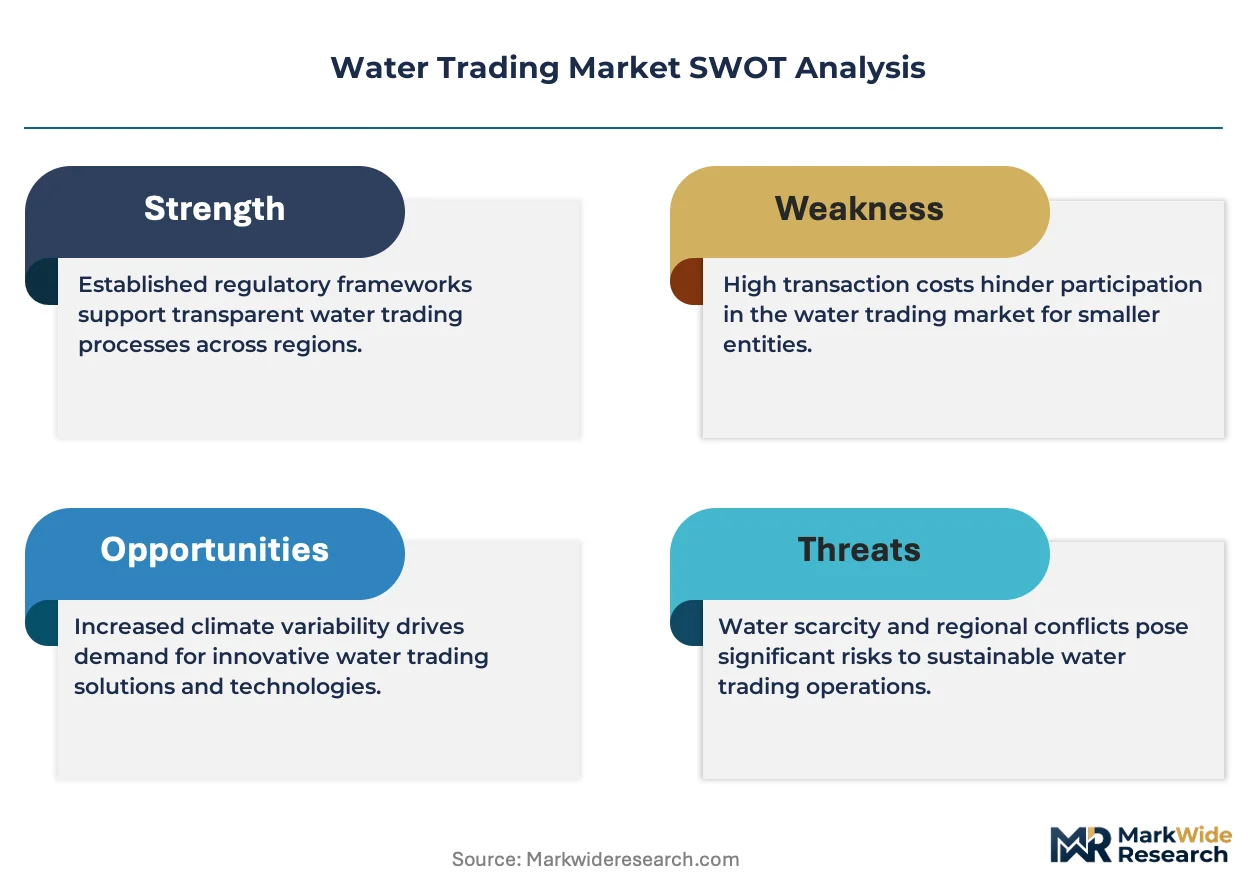
- Measurement infrastructure costs:Digital metering and telemetry systems required for volume verification impose capital burdens that exclude smaller agricultural holders from exchange participation.
- Regulatory fragmentation:Divergent state-level groundwater sustainability agency rules in California create jurisdictional friction that slows permit-transfer approvals across county boundaries.
- Hydrological uncertainty:Climate-driven variability in snowpack and runoff undermines forward contract pricing, compressing the maturity horizon for hedging instruments.
Strategic Opportunities
- EU Green Deal nature restoration:Tightening abstraction permits in member states with degraded aquatic ecosystems will expand tradeable entitlement volumes beyond current basin caps.
- Convergence of blockchain and IoT metering:Immutable transaction records paired with real-time flow monitoring are enabling peer-to-peer trading platforms outside traditional exchange infrastructure.
- Industrial water-as-a-service models:Manufacturing offtakers in Gujarat and Tamil Nadu are piloting subscription-based access to treated wastewater, opening non-agricultural demand channels.
Industry Challenges
- Hydrological modeling expertise:Shortages of professionals capable of integrating surface-groundwater interaction models with market pricing algorithms constrain platform development.
- Legacy entitlement reconciliation:Pre-existing riparian and appropriative rights in western US watersheds create title ambiguity that complicates clearinghouse settlement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Trading Market |
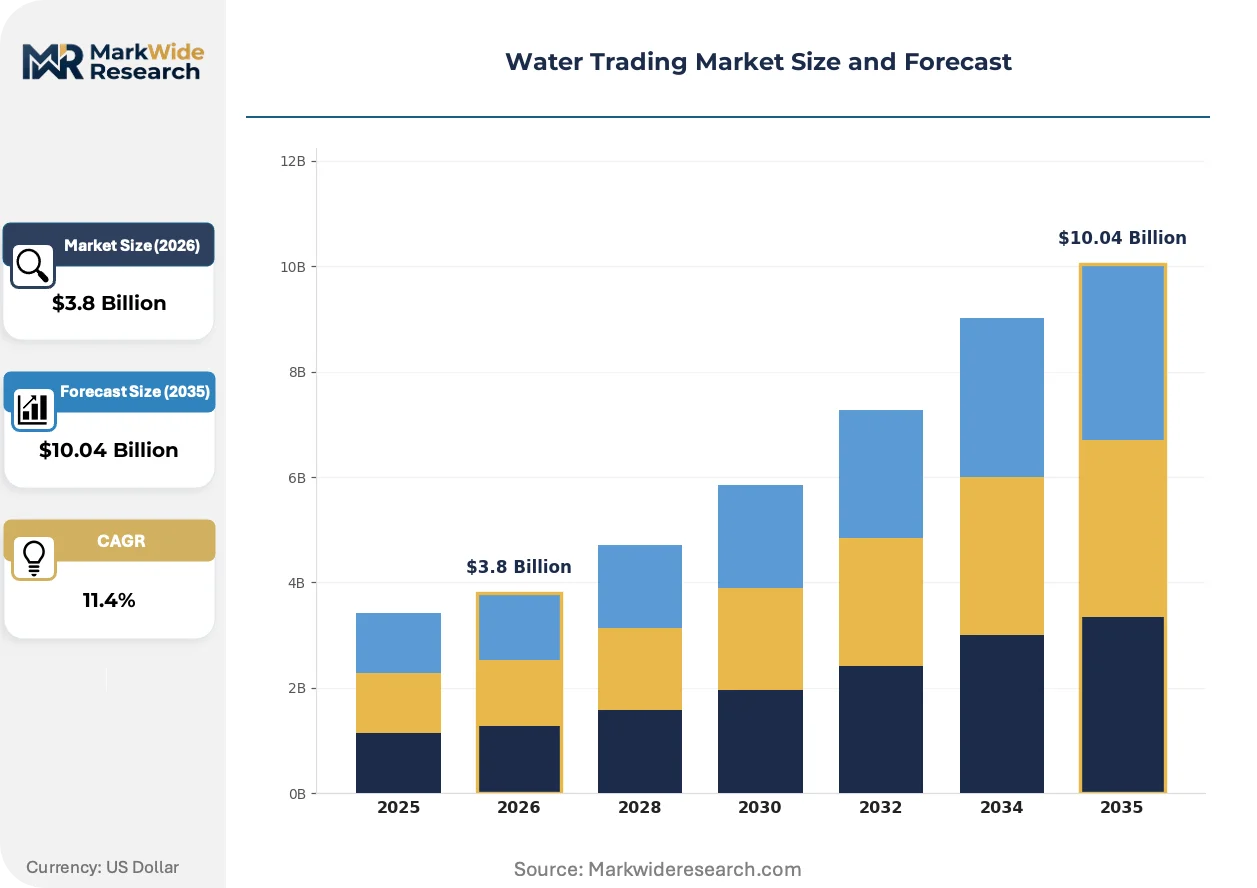
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Spot Market, Forward Contract, Option Contract, Futures Market Water Source: Groundwater, Surface Water, Desalinated Water, Recycled Water Usage Type: Agricultural, Industrial, Recreational, Municipal Regulatory Framework: Nationwide Policy, Regional Agreements, Local Regulations, Market-Based Mechanisms |
| Companies Covered | American Water, Veolia, Xylem, Consolidated Water, Essential Utilities, California Water Service, American States Water, United Utilities Group, Kurita Water Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Trading Market Strategic Shifts
Digital infrastructure is penetrating water allocation systems, converting opaque bilateral negotiations into transparent, exchange-traded mechanisms with real-time price discovery and automated settlement.
Blockchain-enabled smart contracts are automating the execution of conditional water transfers tied to verified flow measurements at specific infrastructure nodes. Agricultural water user associations in Australia's southern connected system are piloting these instruments to reduce counterparty risk and accelerate settlement cycles. The technology is automating the reconciliation of delivery obligations against actual extractions, compressing dispute resolution timelines from months to days.
The EU Green Deal's nature restoration requirements are tightening abstraction permits and expanding the addressable pool of tradeable entitlements across member states with stressed river basins. Industrial utilities in France and Spain are responding by acquiring long-term forward positions to secure cost certainty for manufacturing operations. This regulatory pressure is accelerating the migration from administrative allocation to market-based reallocation mechanisms.
Spot procurement through digital exchanges is displacing traditional bilateral contracting among agricultural buyers in California's Central Valley. Growers in Fresno and Kern counties are fragmenting their water sourcing across multiple short-term transactions rather than locking into seasonal supply agreements. This behavioral shift is most visible among specialty crop operators facing volatile irrigation cost structures under groundwater sustainability mandates.
Water Trading Market Segmentation
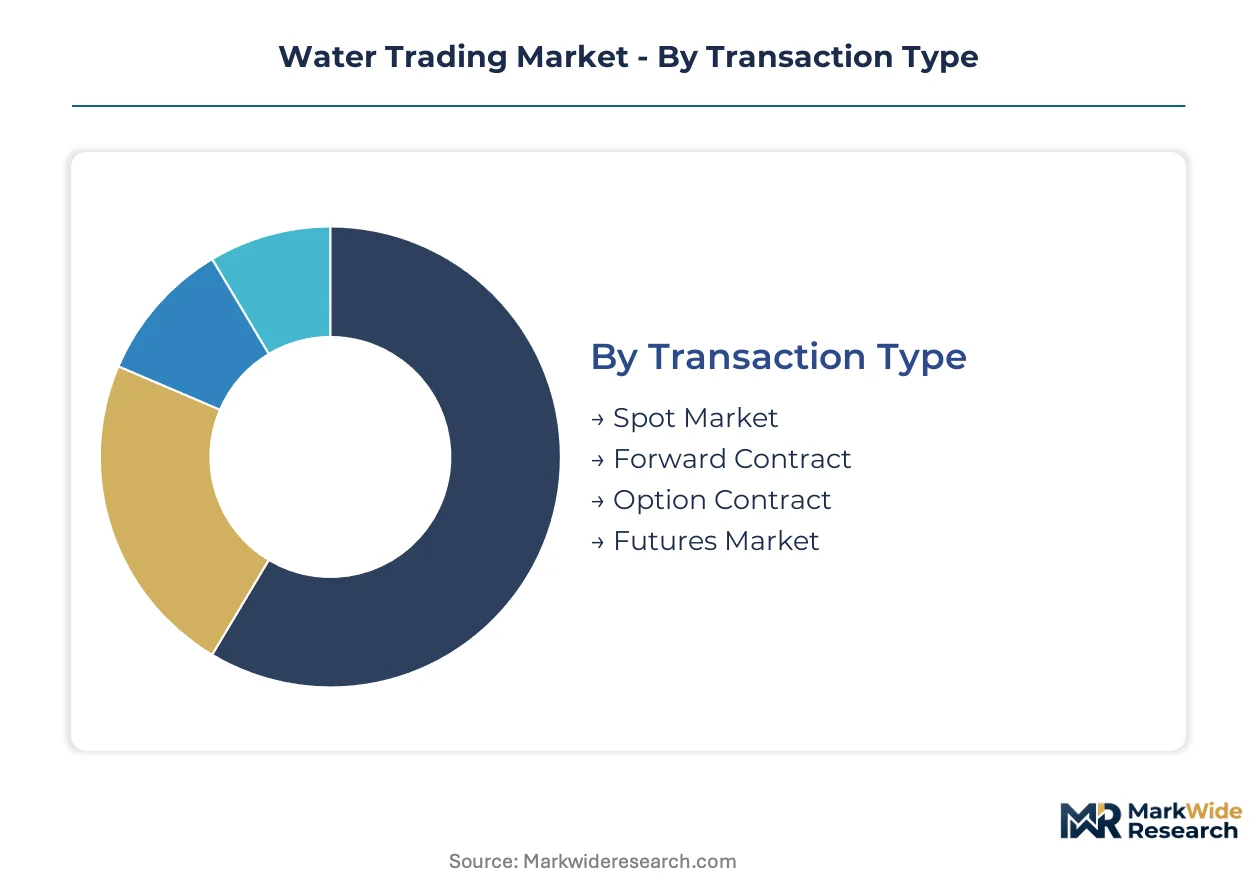
Water trading segmentation reveals how transaction structure, source availability, and regulatory jurisdiction determine platform design and pricing mechanics. Buyers select instruments based on delivery certainty needs, hydrological risk exposure, and compliance obligations across fragmented governance systems.
Transaction Type:
Buyers choose instruments based on price volatility tolerance and operational planning horizons.
- Spot Market:Immediate-delivery transactions settled at prevailing exchange rates enable rapid reallocation during drought stress. California's Central Valley specialty crop operators fragment procurement across multiple short-term purchases to manage volatile irrigation costs under groundwater sustainability mandates.
- Forward Contract:Fixed-price agreements for future delivery provide cost certainty across growing seasons. French and Spanish industrial utilities acquire long-term forward positions to secure manufacturing water supply under tightening EU Green Deal abstraction limits.
- Option Contract:Right-but-not-obligation instruments hedge against supply interruption without full capital commitment. Australian irrigation districts deploy these during uncertain Murray-Darling Basin allocation announcements.
- Futures Market:Standardized exchange-traded instruments enable price discovery and risk transfer without physical delivery obligation. Emerging liquidity concentrates in basin-specific contracts tied to infrastructure nodes.
Spot Market leads on scale; Forward Contract leads on momentum.
Water Source:
Source selection hinges on quality specifications, infrastructure access, and ESG disclosure requirements.
- Groundwater:Aquifer-extracted volumes face intensifying sustainability caps. California's Central Valley agricultural holders confront compressed availability as groundwater sustainability agencies translate cutback mandates into transferable credit architectures.
- Surface Water:River and reservoir allocations dominate established trading systems. Australia's Murray-Darling Basin Authority administers basin-scale extraction caps that entrench scarcity pricing across entitlement exchanges.
- Desalinated Water:Energy-intensive coastal supply serves industrial clusters with zero freshwater alternative. Spanish and Italian facilities supply manufacturing zones with stressed river basin access.
- Recycled Water:Treated wastewater volumes expand fastest as industrial offtakers pursue ESG-aligned alternatives. Manufacturing clusters in Gujarat and Tamil Nadu pilot subscription-based treated wastewater access.
Surface Water leads on scale; Recycled Water climbs the fastest.
Usage Type:
End-use differentiation drives contract duration, quality standards, and delivery reliability terms.
- Agricultural:Irrigation demand dominates volume flows with seasonal concentration and weather-contingent flexibility requirements. Australian irrigation districts expand exchange participation as surface water reliability deteriorates across the Murray-Darling Basin.
- Industrial:Manufacturing offtakers prioritize supply continuity and quality consistency for process integration. French industrial utilities secure long-term positions ahead of tightening EU abstraction permits.
- Recreational:Environmental and amenity flows command premium pricing for guaranteed minimum instream volumes. Basin authorities acquire these rights to satisfy nature restoration requirements.
- Municipal:Urban utilities blend multiple sources to meet public health standards and drought resilience targets. California cities diversify procurement across spot and forward markets.
Agricultural leads on scale; Industrial leads on momentum.
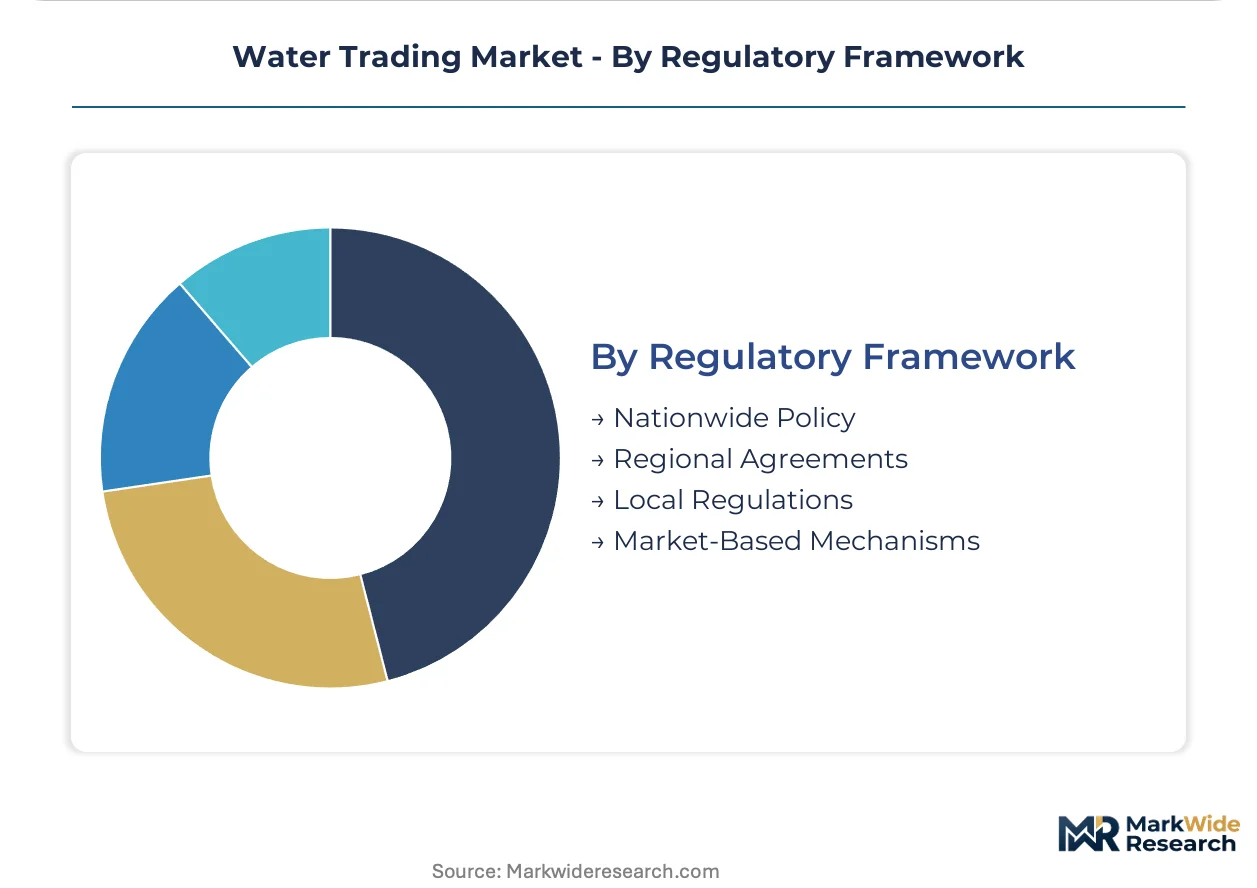
Regulatory Framework:
Governance architecture determines entitlement transferability, verification requirements, and market access rules.
- Nationwide Policy:Uniform federal standards reduce jurisdictional friction and expand addressable trading pools. Australia's Commonwealth Water Act establishes basin-scale caps enabling exchange liquidity.
- Regional Agreements:Interstate or international compacts coordinate shared basin management. EU Water Framework Directive converts static permits into tradeable assets across stressed river basins in France, Spain, and Italy.
- Local Regulations:County and municipal rules create granular constraints on permit transfers. California's groundwater sustainability agencies generate divergent county-level rules that slow cross-boundary approvals.
- Market-Based Mechanisms:Explicit trading platforms with transparent price discovery replace administrative allocation. Chile's water markets operate under this framework with constitutionally protected private rights.
Regional Agreements lead on scale; Market-Based Mechanisms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water trading emerged at scale in Australia's Murray-Darling Basin during the 1980s before spreading to Chile's constitutionally protected private rights systems and California's drought-stressed agricultural corridors. Today's market architecture reflects these pioneering jurisdictions while expanding into new regulatory environments.
United States
California's Central Valley specialty crop operators fragment procurement across spot markets as groundwater sustainability agencies translate cutback mandates into transferable credit architectures. The EPA enforces Clean Water Act standards that define tradable pollutant loads intersecting with water rights. Fresno and Kern counties exhibit the most visible behavioral shift toward short-term transactions.
Australia
Agricultural irrigation districts expand exchange participation as surface water reliability deteriorates across the Murray-Darling Basin. The Commonwealth Water Act establishes basin-scale caps enabling exchange liquidity through the Murray-Darling Basin Authority. Southern connected system water user associations pilot blockchain-enabled smart contracts to accelerate settlement cycles.
France
Industrial utilities acquire long-term forward positions to secure manufacturing water supply under tightening EU Green Deal abstraction limits. The EU Water Framework Directive converts static permits into tradeable assets across stressed river basins. Veolia leverages its integrated utility footprint to anchor trading operations in Southern Europe.
Spain
Industrial clusters with zero freshwater alternative rely on energy-intensive coastal desalination facilities serving manufacturing zones with stressed river basin access. The EU Water Framework Directive tightens abstraction limits in member states with degraded aquatic ecosystems. Barcelona and Valencia manufacturing corridors respond by securing forward contract positions.
India
Manufacturing offtakers in Gujarat and Tamil Nadu pilot subscription-based access to treated wastewater, opening non-agricultural demand channels. The country's national water regulator oversees emerging market-based allocation pilots in water-stressed manufacturing zones. Ahmedabad and Chennai industrial clusters drive recycled water infrastructure development.
Water Trading Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light platform developers for margin capture in water trading ecosystems. The vendor base organizes around three tiers: integrated utilities with regulatory relationships, technology providers supplying verification infrastructure, and specialized water service companies. Dominant competitive moves include strategic partnerships between metering technology firms and exchange operators, plus backward integration by utilities into digital trading platform development.
Within the integrated utility tier, Veolia and American Water exemplify archetypes leveraging regulatory footprints to ease permit-transfer approvals. Xylem occupies a position representing technology-first entrants specializing in digital metering infrastructure that underpins volume verification for spot-market transactions. These three anchors demonstrate how geographic regulatory depth and technical verification capability constitute distinct competitive moats in market development.
| Leading Market Players |
|---|
| American Water |
| Veolia |
| Xylem |
| Consolidated Water |
| Essential Utilities |
| California Water Service |
| American States Water |
| United Utilities Group |
| Kurita Water Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into digital metering infrastructure anchors supply positions for verification-dependent spot-market transactions while simultaneously capturing margin from telemetry hardware deployment. California's groundwater sustainability agencies and Australia's Murray-Darling Basin Authority both reward participants with verified flow data, compressing price discovery timelines and elevating platform operator pricing power.
Pricing Analysis
Transaction-based pricing per megalitre or acre-foot dominates spot-market liquidity, with forward contracts layering fixed-price premiums for seasonal delivery certainty. Price differentiation hinges on hydrological reliability grades and infrastructure node access costs, with headworks-adjacent entitlements commanding substantial premiums. Cost compression in agricultural spot procurement is intensifying as specialty crop operators fragment purchases across multiple short-term transactions. Municipal utilities exhibit the lowest price sensitivity due to public health mandates, while Fresno County almond growers demonstrate acute sensitivity to irrigation cost volatility.
Supply Chain Analysis
ISO-standard flow meter certification and telemetry system qualification gates entry for hardware suppliers serving exchange verification requirements. Component manufacturing concentrates in Germany, China, and the United States for pressure sensors, data loggers, and satellite uplink modules. The ecosystem rests on semiconductor inputs, precision machining capacity, and cloud computing infrastructure for real-time settlement. Single-source vulnerability concentrates in satellite telemetry providers serving remote basin monitoring. Distribution runs through integrated utility procurement channels and specialized water technology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in verification infrastructure deployment as regulatory mandates for transparent flow measurement proliferate across stressed watersheds. Premium-tier migration toward blockchain-enabled settlement platforms rewards early movers with recurring SaaS revenue capture.
For Market Incumbents: Acquire digital metering technology portfolios to secure captive supply of verification hardware essential for exchange participation. Consolidate regional water user association relationships before groundwater sustainability agencies finalize transferable credit architectures. Threat substitution from peer-to-peer blockchain platforms demands preemptive platform integration investments. Certification investment in ISO-standard telemetry systems represents the critical defensive lever. For New Entrants and Emerging Players: Begin with recycled water infrastructure-as-a-service models in Gujarat and Tamil Nadu manufacturing corridors, where subscription pricing penetrates faster than entitlement exchanges. White-space opportunity concentrates in industrial offtaker segments pursuing ESG-aligned supply alternatives. Go-to-market execution should anchor on pilot subscriptions with anchor manufacturing tenants before scaling to multi-facility networks. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented county-level groundwater sustainability agency rules create jurisdictional friction that slows permit-transfer approvals. Long-term viability favors platform operators with regulatory relationship depth spanning multiple basin authorities. Acquisition target archetype: asset-light exchange developers with deployed IoT metering networks and established utility partnerships. The signal to watch is EU member state transposition of nature restoration requirements into explicit tradeable entitlement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Settlement Platform | Smart contract automation compresses dispute resolution from months to days across Australia's southern connected system. |
| Backward Integration into Telemetry Hardware | Captive sensor manufacturing secures margin capture from California's groundwater sustainability mandate-driven verification demand. |
| Recycled Water Infrastructure Partnership | Subscription models in Gujarat and Tamil Nadu open non-agricultural demand channels for manufacturing clusters. |
| Regulatory Relationship Consolidation | Multi-basin authority access eases permit-transfer approvals before county-level rule fragmentation hardens. |
| Forward Contract Liquidity Provision | Long-term position-taking by French and Spanish utilities secures manufacturing supply under tightening EU abstraction limits. |
Study Parameters
Coverage spans the United States, Australia, France, Spain, and India, with primary inputs from each market's regulatory and operational stakeholders. Primary interviews incorporated water exchange operators, groundwater sustainability agency officials, irrigation district managers, and industrial utility procurement leads. Secondary validation drew from EPA enforcement records, Murray-Darling Basin Authority allocation announcements, EU Water Framework Directive implementation documents, and state-level groundwater sustainability plans. Bottom-up transaction volume aggregation triangulated against top-down basin-scale cap analysis.
Rate-of-change decomposition separated volume growth from price appreciation across the projection horizon. Segmentation dimensions modeled include transaction type, water source, usage category, and regulatory framework cluster. CAGRs were derived from basin-specific entitlement allocation trajectories, drought frequency projections, and regulatory tightening schedules. Industry-specific inputs incorporated snowpack variability indices, groundwater depletion rates, and EU nature restoration timeline assumptions.
Several conditions sit outside the modeled scope, including extreme climate events exceeding historical hydrological variability, constitutional challenges to water rights frameworks, and technological disruption from unproven desalination cost curves. Forecasts reflect documented assumptions about regulatory implementation pacing and infrastructure deployment timelines. A model refresh is warranted upon material change in EU member state abstraction permit conversion schedules or California groundwater sustainability agency credit architecture finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Mexico Water Consumption Market
Water Management
Smart Water Management Market
Water Management
Water Free Urinals Market
Water Management
Municipal Water Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Smart Water Network Market
Water Management
Chile Water Consumption Market
Water Management
Global Water Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Water Filters Market
Water Management
France Water Consumption Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
North America Water Sink Market
Water Management
Spain Water Consumption Market
Water Management
NRW Smart Leak Management Market
Water Management
Water Utility Services Market