
 Water Filters Market | 2026-2036
Water Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Water Filters Market Intelligence
Production capacity expansion for membrane materials in Southeast Asia is rebalancing the global supply chain for key filtration components. Pentair leverages its extensive distribution network to address both residential and commercial building applications. A. O. Smith Corporation competes on technology, particularly with its integrated reverse osmosis systems for household end users. Meanwhile, Brita sustains its market position through strong brand recognition in pitcher and faucet-mounted filter categories, targeting household consumers directly.
A water filter is a device that removes impurities from water using a physical barrier, a chemical process, or a biological process. These systems often utilize materials like activated carbon, which has a specific micropore structure for adsorbing chemical contaminants. Residential applications continue to account for the largest share of unit sales, primarily through point-of-use systems. The commercial food & beverage application represents a high-margin opportunity, requiring advanced reverse osmosis and ultraviolet technologies to meet stringent safety and quality standards.
In the United States, the EPA establishes enforceable standards for drinking water contaminants, which directly influences filter performance requirements. Concurrently, the European Union’s Drinking Water Directive sets strict quality parameters, governing market access for certified products across member states. Future competitive advantage will hinge on the development of filters capable of effectively removing emerging contaminants such as microplastics and per- and polyfluoroalkyl substances (PFAS).
Market Dynamics
The market's technical trajectory is defined by the urgent need to address emerging contaminants. The detection of per- and polyfluoroalkyl substances (PFAS) and microplastics in water supplies is compelling a fundamental shift in filtration technology performance requirements and certification standards.
Growth Catalysts
- Regulatory Mandates:The EU's Drinking Water Directive compels food and beverage operators to install advanced filtration to meet strict purity standards.
- National Water Policies:Government initiatives in India to improve public health are accelerating the adoption of residential point-of-use water filter systems.
- Material Innovation:Advances in activated carbon and membrane science enable the effective removal of specific chemical contaminants, meeting higher performance demands.
Market Restraints
- System Cost:The high upfront investment for reverse osmosis systems presents a significant adoption barrier for price-sensitive residential consumers.
- Component Sourcing:Global dependence on Southeast Asia for membrane material production creates a concentrated point of failure in the supply chain.
- Technical Efficacy Gaps:Conventional filters struggle with the energy-intensive removal of certain dissolved solids, limiting their effectiveness in specific water conditions.
Strategic Opportunities
- Emerging Contaminant Focus:Filters certified for removing PFAS and microplastics meet a critical, scientifically validated consumer demand for enhanced safety.
- IoT Integration:Smart filters with sensors create opportunities for subscription models based on real-time performance data and automated cartridge replacement.
- New Market Development:Significant volume growth is available by targeting underpenetrated residential markets in Latin America where water quality is a concern.
Industry Challenges
- Certification Hurdles:The lengthy and costly process of achieving NSF/ANSI certification for new products can delay market entry and consume significant R&D resources.
- Consumer Education Gap:Overcoming public misinformation requires clearly communicating the performance differences between technologies like activated carbon and reverse osmosis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Filters Market |
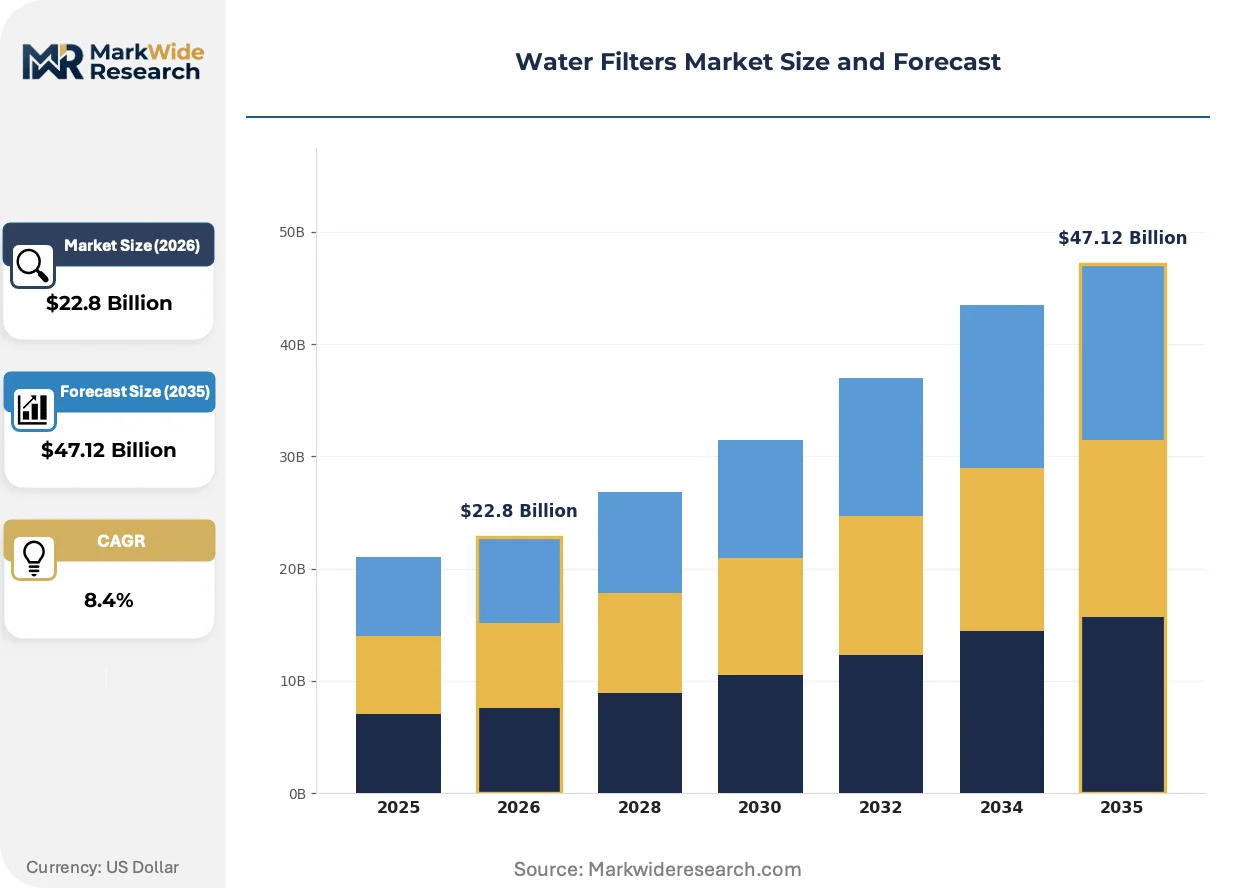
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Reverse Osmosis, Ultraviolet, Ceramic, Ion Exchange, Mechanical Technology: Membrane Filtration, Adsorption, UV Sterilization, Electrochemical, Nanofiltration, Ultrafiltration Application: Residential, Commercial Buildings, Food & Beverage, Pharmaceutical, Agriculture, Hospitality End User: Households, Office Complexes, Manufacturing Units, Educational Institutions, Laboratories, Healthcare Facilities |
| Companies Covered | Pentair, A. O. Smith Corporation, Culligan International, 3M Company, Veolia, Brita, Coway, Whirlpool Corporation, BWT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Filters Market Strategic Shifts & Innovations
A fundamental reorientation from aesthetic filtration toward health-critical purification defines the market's innovation trajectory. The need to neutralize invisible threats like viruses and industrial chemicals is forcing a complete re-evaluation of filter performance, certification, and technology.
Smart filter cartridges incorporate embedded sensors to provide real-time data on water quality and filter lifespan. Residential and light commercial users are adopting these systems to gain greater control over their water safety. This technology is modularizing filtration, enabling component-level upgrades and data-driven replacement cycles instead of whole-unit replacement.
The US EPA's establishment of enforceable limits for per- and polyfluoroalkyl substances (PFAS) in drinking water is a pivotal regulatory development. This action compels manufacturers to re-engineer and validate filtration media specifically for PFAS chemical reduction. The residential point-of-use segment is most impacted, with product certification becoming a key competitive differentiator.
Movement from one-time hardware sales to recurring revenue models is gaining traction for replacement components. This shift favors subscription services that automatically ship new cartridges, often bypassing traditional brick-and-mortar retail channels. The trend is most pronounced in the North American and European markets for pitcher and under-sink filter systems.
Water Filters Market Segmentation
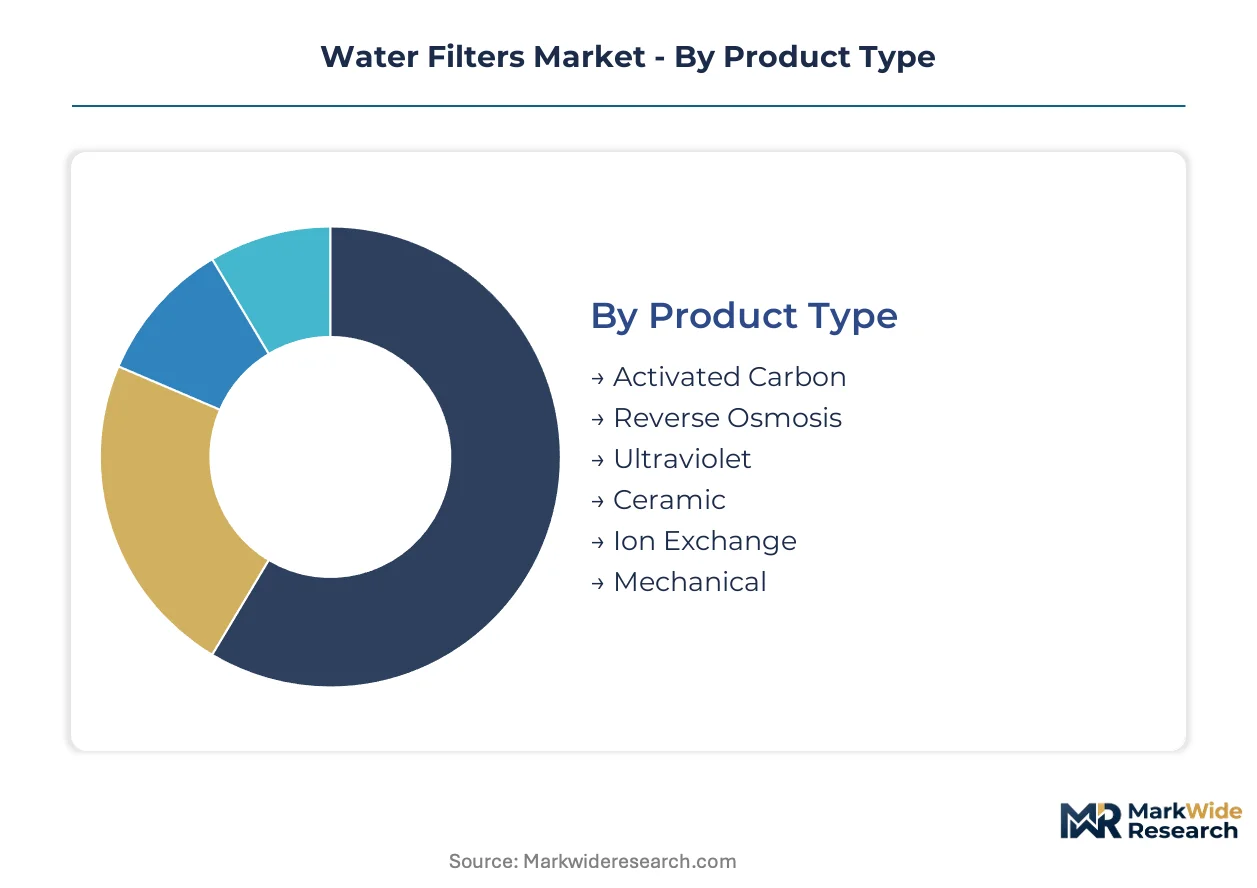
Understanding the Water Filters market structure requires a detailed breakdown of its diverse components. This segmentation highlights the various product types, underlying technologies, and critical applications driving demand. Analyzing these distinctions reveals specific market opportunities and compliance challenges for manufacturers.
Product Type:
The need for specific certifications, such as NSF/ANSI standards or EU Drinking Water Directive compliance, heavily influences product type selection across end-user segments.
- Activated Carbon:These filters utilize porous carbon to adsorb organic compounds, chlorine, and other taste-and-odor impurities from water. Demand is strong in residential point-of-use systems, driven by consumer preference for improved water aesthetics.
- Reverse Osmosis:This technology employs a semi-permeable membrane to remove dissolved solids, salts, and microscopic contaminants through pressure. Commercial food & beverage applications require these systems for stringent purity standards, especially in regions with hard water.
- Ultraviolet:UV filters use germicidal lamps to inactivate bacteria, viruses, and other pathogens without chemicals, finding use in healthcare facilities.
- Ceramic:These filters use a porous ceramic medium to physically block sediment, bacteria, and protozoa, common in point-of-use residential systems in India.
- Ion Exchange:Ion exchange resins remove dissolved ionic contaminants like hardness minerals and heavy metals, crucial for industrial process water.
- Mechanical:Mechanical filters physically block larger particles like sediment and rust, serving as pre-filters in multi-stage filtration systems.
Leading the category by volume: Activated Carbon. Growing fastest: Reverse Osmosis.
Technology:
Each filtration technology addresses distinct contaminant profiles and operational requirements, dictating its suitability for various applications from household use to industrial processes.
- Membrane Filtration:This broad category includes microfiltration, ultrafiltration, nanofiltration, and reverse osmosis, separating particles based on pore size. Pharmaceutical and food & beverage sectors heavily rely on membrane systems for sterile processing.
- Adsorption:Adsorptive technologies, primarily activated carbon, remove contaminants by binding them to a porous surface, effective for chemical removal. Residential point-of-use systems widely adopt adsorption for chlorine and organic compound reduction.
- UV Sterilization:This non-chemical disinfection method uses ultraviolet light to destroy microorganisms, vital for pathogen control in water treatment.
- Electrochemical:Electrochemical methods use electric current to remove dissolved solids and contaminants, offering advanced treatment for specific industrial wastewaters.
- Nanofiltration:Nanofiltration membranes remove multivalent ions and larger organic molecules, used for water softening and color removal.
- Ultrafiltration:Ultrafiltration membranes effectively remove suspended solids, bacteria, and viruses, serving as pretreatment for reverse osmosis systems.
High-margin opportunities exist within Membrane Filtration due to specialized applications. Adsorption technologies offer cost-effective solutions for broader consumer markets.
Application:
The diverse range of applications reflects varying water quality demands, from basic potability in households to ultra-pure requirements in specialized industries.
- Residential:This segment includes point-of-use and point-of-entry systems for homes, addressing drinking water quality and appliance protection. Consumer education on emerging contaminants like PFAS is a key driver for this segment.
- Commercial Buildings:Filters in commercial settings serve offices, schools, and retail spaces for drinking water, HVAC systems, and food service. Regulatory compliance for public health standards drives system upgrades in this sector.
- Food & Beverage:This application demands high-purity water for product formulation and sanitation, necessitating advanced filtration like reverse osmosis.
- Pharmaceutical:Ultra-pure water is critical for drug manufacturing and laboratory processes, requiring multi-stage, validated filtration systems.
- Agriculture:Water filtration in agriculture supports irrigation systems and livestock drinking water, preventing equipment fouling and improving animal health.
- Hospitality:Hotels and restaurants use filters for guest drinking water, ice machines, and kitchen operations to ensure quality and safety.
Residential applications represent the largest unit sales volume. Food & Beverage presents high-margin opportunities due to stringent purity requirements.
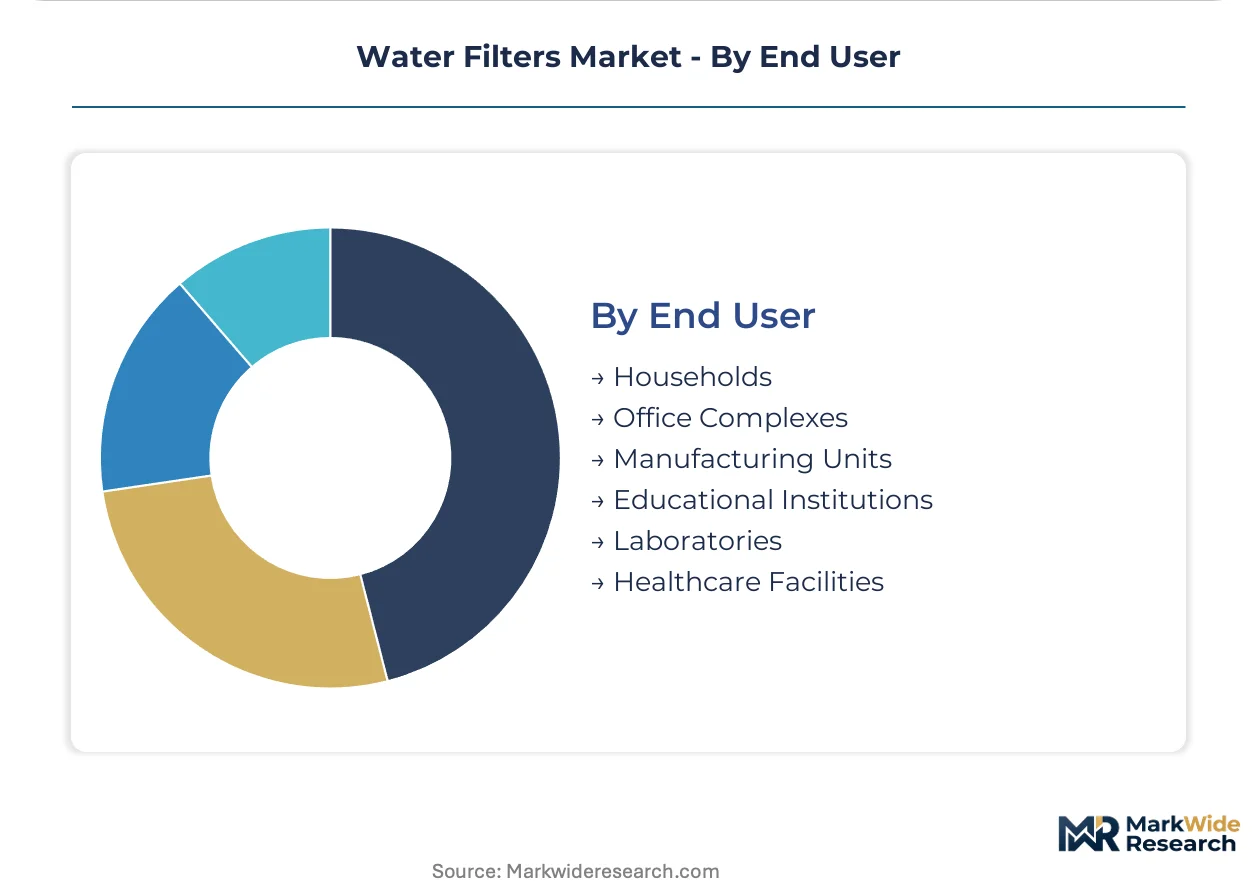
End User:
End-user categories exhibit distinct purchasing behaviors and regulatory pressures, influencing filter adoption rates across different geographic markets.
- Households:Individual consumers purchasing filters for drinking, cooking, and general home use constitute the largest end-user group. Government initiatives in India are accelerating the adoption of point-of-use systems in this segment.
- Office Complexes:These users require filtration for drinking fountains, coffee machines, and facility water, often driven by employee wellness programs. Smart filter integration for maintenance alerts gains traction in modern office environments.
- Manufacturing Units:Industrial facilities use filtered water for process applications, equipment protection, and wastewater treatment, adhering to environmental discharge limits.
- Educational Institutions:Schools and universities install filters for drinking water safety and laboratory use, responding to public health concerns.
- Laboratories:Research and testing laboratories demand highly purified water for experiments and reagent preparation, often requiring specialized systems.
- Healthcare Facilities:Hospitals and clinics require sterile water for medical procedures, dialysis, and patient safety, necessitating robust filtration and disinfection.
Households represent a mature but expanding segment, particularly in emerging markets. Laboratories demonstrate demand for high-performance, specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for membrane materials in Vietnam anchors the water filters market across Southeast Asia, influencing global supply dynamics. This region, alongside key demand markets, drives product innovation and regulatory compliance. Governments and private entities are investing in water infrastructure to address public health concerns and industrial purity requirements.
India
Government initiatives to improve public health are accelerating the adoption of residential point-of-use water filter systems in India. The Bureau of Indian Standards (BIS) sets quality benchmarks for drinking water, influencing product development. Urban centers like Mumbai and Bangalore demonstrate concentrated demand for ceramic and activated carbon filters due to varied water quality challenges.
United States
The urgent need to remove emerging contaminants like PFAS and microplastics drives demand for advanced filtration in the United States. The US EPA establishes enforceable standards for drinking water, compelling manufacturers to innovate. Research hubs in California and Massachusetts lead in developing new membrane technologies and sensor-integrated smart filter systems.
Germany
Stringent purity standards in the commercial food and beverage sector drive demand for advanced reverse osmosis systems in Germany. The European Union’s Drinking Water Directive governs market access for certified products, ensuring high quality. Industrial clusters in Bavaria and North Rhine-Westphalia focus on specialized filtration solutions for diverse manufacturing processes.
Vietnam
Vietnam's expanding production capacity for membrane materials rebalances the global supply chain for key filtration components. Local environmental regulations influence manufacturing practices and material sourcing within the country. Ho Chi Minh City and Hanoi serve as significant hubs for manufacturing operations and export logistics, supporting regional and global markets.
China
Rapid industrialization and urban population growth drive demand for both residential and industrial water filtration solutions in China. China's GB standards for drinking water quality influence product design and performance requirements. The Yangtze River Delta region, including cities like Shanghai, exhibits a high concentration of water treatment solution providers and end-users.
Water Filters Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue enhanced purification for emerging contaminants and smart filter integration. The market structure exhibits a tiered consolidation, with a few large players holding significant distribution advantages. Strategic partnerships for technology licensing and geographic expansion are common competitive moves among market participants.
Within the brand-focused tier, Brita sustains its market position through strong brand recognition in pitcher and faucet-mounted filter categories. Pentair leverages its extensive distribution network to address both residential and commercial building applications, exemplifying a scale-driven strategy. A. O. Smith Corporation occupies a technology-centric position, particularly with its integrated reverse osmosis systems for household end users.
| Leading Market Players |
|---|
| Pentair |
| A. O. Smith Corporation |
| Culligan International |
| 3M Company |
| Veolia |
| Brita |
| Coway |
| Whirlpool Corporation |
| BWT |
| Others |
Cost & Logistics Intelligence
A polymer resin index for membrane materials directly influences manufacturing costs, cascading through the supply chain into distinct pricing tiers for water filtration systems. This cost structure impacts end-user affordability and manufacturer profitability across diverse product categories.
Pricing Analysis
Warranty and service bundling often differentiate premium water filter products, unbundling installation from ongoing maintenance. The dominant pricing model combines per-unit transactional sales for hardware with subscription services for replacement cartridges. Price differentiation drivers include certification levels like NSF/ANSI standards and brand recognition. Pricing pressure stems from the proliferation of cost-effective activated carbon alternatives for basic filtration needs. Residential consumers, particularly in emerging markets, exhibit the highest price sensitivity, while pharmaceutical and food & beverage applications prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asia for membrane material production, particularly in Vietnam. The supply chain for water filters draws heavily from China for general manufacturing and India for certain ceramic filter components. Raw material dependencies include specialized membrane polymers and activated carbon granules. Geopolitical tensions impacting key manufacturing hubs present a structural supply chain risk. Distribution runs through established networks for commercial applications and increasingly through direct-to-consumer channels for residential point-of-use systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water filters market reads as a consolidation play, driven by escalating regulatory mandates for emerging contaminant removal that strain smaller manufacturers. This environment favors larger entities with robust R&D budgets and certification capabilities.
For Market Incumbents:
Acquire specialized filtration technology firms to integrate advanced PFAS and microplastic removal capabilities. Expand subscription models for filter cartridge replacements, securing recurring revenue streams against competitive pressure from generic alternatives. Invest heavily in NSF/ANSI certification for new product lines, leveraging this as a key differentiator. Control distribution channels to maintain market share against agile direct-to-consumer brands.
For New Entrants and Emerging Players:
Begin with highly targeted solutions for emerging contaminants, offering certified performance against PFAS or microplastics. Focus on underpenetrated residential markets in Latin America, where water quality concerns are growing. Develop smart filter integration for commercial buildings, appealing to facility managers seeking automated maintenance and real-time data. A go-to-market angle emphasizing scientifically validated purification for specific health threats creates a distinct value proposition.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers targeting mid-sized innovators with proprietary membrane technologies. Long-term viability for this market remains strong, driven by essential infrastructure needs over a 5-10 year horizon. Seek companies with strong intellectual property in advanced filtration media or established subscription-based revenue models. The signal to watch is the expansion of enforceable contaminant limits by major regulatory bodies like the US EPA and EU.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Membrane Materials | Increases supply chain resilience and reduces dependence on concentrated regional production. |
| R&D Investment in PFAS/Microplastic Technology | Addresses critical emerging contaminant challenges and meets evolving regulatory standards. |
| IoT Integration for Smart Filters | Enables data-driven maintenance, automated replacements, and new subscription service models. |
| Subscription Model Rollout for Cartridges | Secures recurring revenue streams and fosters long-term customer loyalty. |
| Geographic Expansion into Underpenetrated Markets | Captures significant volume growth in regions with increasing water quality concerns. |
Research Approach
Industry reports, government publications from the US EPA and EU, and academic journals formed the secondary backbone of this analysis. This foundational research was complemented by primary interviews with R&D directors, procurement managers, regulatory compliance officers, and distribution channel partners. The study employed a rigorous bottom-up and top-down triangulation approach to validate all market figures.
Historical trendline analysis established baseline growth trajectories across the water filters market. The analytical framework extrapolated these patterns, correlating them with macroeconomic indicators over the projection horizon. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from these market size estimates, incorporating water quality index data and infrastructure investment trends as key forecast inputs.
Underlying measurement precision varies by segment; established residential product categories carry tighter precision than nascent emerging contaminant solutions. Forecasts reflect assumptions regarding regulatory enforcement and material science advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
NRW Smart Leak Management Market
Water Management
Water Utility Services Market
Water Management
Global Water Market
Water Management
Water Trading Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Water Free Urinals Market
Water Management
Smart Water Network Market
Water Management
Middle East and Africa Water Sink Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Chile Water Consumption Market
Water Management
Municipal Water Market
Water Management
North America Water Sink Market
Water Management
Smart Water Management Market
Water Management
France Water Consumption Market
Water Management
Mexico Water Consumption Market
Water Management
Atmospheric Water Generator (AWG) Market