
 North America Water Sink Market | 2026-2036
North America Water Sink Market Size, Share, and Industry Trends Forecast 2026-2036
North America Water Sink Market Analytics
Aftermarket service revenue and replacement part ecosystems is tilting margin pools away from pure hardware sales toward recurring service relationships. Kohler Co. extends its advantage through captive distribution networks and proprietary mounting systems that lock in repeat purchases. Elkay Manufacturing Company anchors its position in the commercial segment through NSF-certified fabrication capacity and direct contractor relationships. Franke Kitchen Systems, LLC differentiates via European design heritage translated for North American dimensional standards.
North America water sinks are bowl-shaped fixtures engineered from stainless steel, ceramic, composite, or cast iron, typically measuring 22 to 36 inches in width, designed for food preparation, hand washing, and utensil cleaning in residential and commercial environments. Undermount and farmhouse configurations command premium positioning due to countertop integration complexity and aesthetic differentiation, while stainless steel dominates volume through durability and cost efficiency. The residential usage segment absorbs the majority of unit demand, though commercial installations generate higher per-unit margins through specification-grade materials and code-compliant drainage systems.
EPA WaterSense specifications and the US Department of Energy appliance standards constrain flow rates and fixture performance, compelling manufacturers to redesign basins and aerators for compliance without functional compromise. California Title 20 and Texas administrative codes on plumbing efficiency create a patchwork of state-level requirements that shape regional product assortments and inventory strategies. Stakeholders must monitor municipal green building ordinances in fast-growing Sun Belt metros, where local amendments frequently exceed federal baselines and determine specification eligibility for large-scale developments.
Market Dynamics
Residential kitchen renovation cycles and EPA WaterSense compliance mandates are compressing product development timelines while fragmenting regional inventory requirements across the US and Canada.
Growth Catalysts
- California Title 20 efficiency standards:Water flow restrictions below 1.8 gallons per minute are forcing basin redesigns that differentiate compliant product lines in the largest US state market.
- Composite material substitution:Granite and quartz composite sinks are displacing cast iron in mid-premium residential renovations due to weight reduction and color consistency.
- Sun Belt housing starts:Texas, Florida, and Arizona construction permits are outpacing national averages, concentrating demand for builder-grade stainless steel configurations.
Market Restraints
- Sheet steel cost volatility:Nickel and chromium input prices fluctuate with stainless steel mill capacity constraints in Ontario and Pennsylvania.
- Fabrication labor concentration:NSF-certified commercial sink welding capacity clusters in Wisconsin and Illinois, creating geographic supply risk.
- Cast iron weight penalties:Freight cost differentials versus composites limit distribution radius for enameled products from Tennessee foundries.
Strategic Opportunities
- Canadian provincial green building codes:British Columbia and Ontario municipal amendments exceed federal baselines, creating specification entry points for low-flow aerator integration.
- Commercial foodservice specification:NSF/ANSI 2 and 3 certified fabrication for restaurants and healthcare facilities commands margin premiums above residential tiers.
- Direct-to-contractor digital platforms:Bypassing traditional distribution through Procore-integrated procurement portals reduces channel cost for multi-unit developers.
Industry Challenges
- Cross-border certification lag:CSA Group testing timelines for Canadian market entry extend 8-14 weeks behind US EPA WaterSense approval cycles.
- Mounting system interoperability:Proprietary clip and rail designs from major manufacturers fragment installation training and service technician certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Water Sink Market |
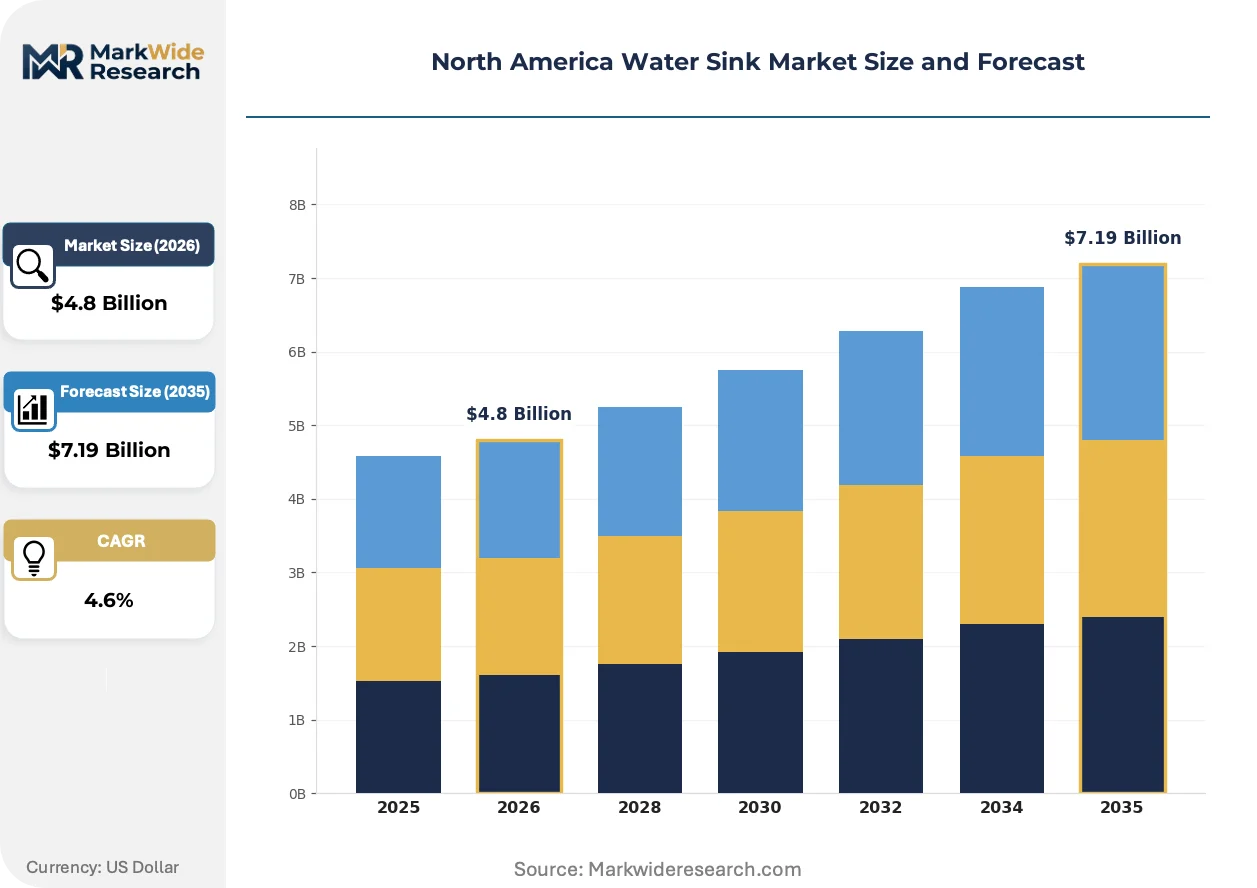
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undermount Sink, Drop-In Sink, Vessel Sink, Farmhouse Sink Material: Stainless Steel, Ceramic, Composite, Cast Iron Usage: Residential, Commercial, Industrial, Outdoor Installation Type: Wall-Mounted, Freestanding, Integrated, Drop-In |
| Companies Covered | Kraus USA, American Standard Brand, Kohler Co., Blanco America, Inc., Franke Kitchen Systems, LLC, Elkay Manufacturing Company, Ruvati, Moen Incorporated, ROHL LLC., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Water Sink Market Evolving Landscape
Material science advances and regulatory patchwork compliance are fragmenting product portfolios while digital specification tools compress the design-to-installation cycle for commercial and residential channels.
Touchless sensor faucet integration is migrating from commercial healthcare and foodservice installations into premium residential kitchen specifications. High-end renovation contractors in California and Texas are specifying battery-backed solenoid systems as standard. This convergence is compressing the traditional separation between commercial-grade durability expectations and residential aesthetic preferences.
EPA WaterSense labeling requirements and California Energy Commission appliance standards are tightening flow-rate testing protocols for basin-and-faucet combinations. Manufacturers must now certify integrated systems rather than standalone components, raising R&D overhead. The residential replacement segment bears the heaviest compliance burden as retrofit compatibility constraints multiply.
Builder procurement teams are consolidating specification authority through centralized purchasing platforms that bypass traditional distributor relationships. Multi-family developers in Florida and Arizona are mandating SKU rationalization across their portfolios, favoring manufacturers with configurable product families. This concentration is squeezing regional fabricators dependent on custom specification relationships.
North America Water Sink Market Segmentation
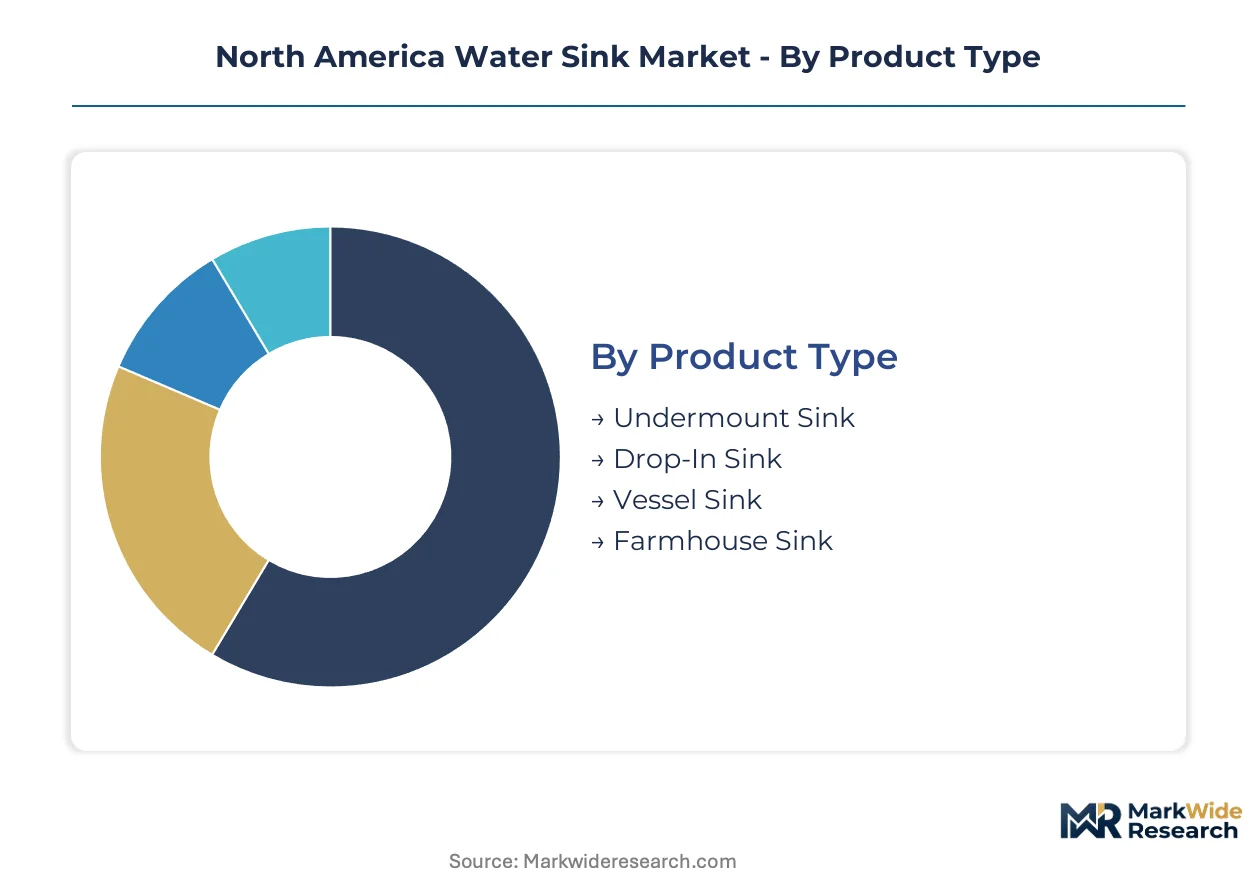
Aftermarket service intensity varies sharply across water sink configurations, with undermount and farmhouse styles generating recurring revenue through proprietary mounting hardware replacement. Material selection drives warranty exposure and field service frequency, reshaping how manufacturers structure regional service networks.
Product Type:
After-sales service intensity peaks with countertop-integrated configurations that demand specialized technician training and captive parts ecosystems.
- Undermount Sink:Seamless countertop integration requires precision fabrication and proprietary clip systems. California and Texas renovation contractors specify these for premium kitchen retrofits where EPA WaterSense compliance adds installation complexity.
- Farmhouse Sink:Apron-front design with exposed basin face demands reinforced cabinetry and custom drainage alignment. Sun Belt housing developers in Florida and Arizona specify these for luxury single-family segments where aesthetic differentiation commands price premiums.
- Drop-In Sink:Self-rimming edge simplifies installation with minimal cabinet modification. Builder-grade multi-family projects in Texas favor these for cost-controlled specifications.
- Vessel Sink:Above-counter bowl sits atop vanity surface with exposed plumbing connections. Boutique hospitality renovations in California specify these for guest bathroom visual impact.
Undermount holds the largest share; momentum sits with farmhouse configurations.
Material:
Cost tier stratification aligns with freight economics and regional fabrication capacity, compressing margin structures for heavy cast iron versus lightweight composites.
- Stainless Steel:Chromium-nickel alloy construction dominates volume through Ontario and Pennsylvania mill proximity. Sun Belt builder markets absorb these for cost efficiency and NSF compliance in commercial foodservice.
- Composite:Granite or quartz resin blend reduces weight versus cast iron while maintaining thermal mass. California residential renovations specify these for color consistency with engineered stone countertops.
- Ceramic:Vitreous china firing delivers non-porous surface for hygiene-critical applications. Healthcare facility specifications in Texas favor these for infection control protocols.
- Cast Iron:Enameled steel core with porcelain coating adds substantial freight cost penalties. Tennessee foundry output concentrates in regional distribution radius due to weight-based logistics constraints.
Stainless steel commands volume leadership; composites gain share fastest in mid-premium renovations.
Usage:
Application context determines specification grade, code compliance burden, and per-unit margin capture across installation environments.
- Residential:Single-family and multi-family installations absorb majority unit demand through kitchen and bath replacement cycles. California Title 20 efficiency mandates reshape product assortments for retrofit compatibility.
- Commercial:Foodservice, hospitality, and healthcare installations require NSF/ANSI certification and specification-grade drainage. Per-unit margins exceed residential tiers through code-compliant fabrication.
- Industrial:Heavy-duty basins for manufacturing and laboratory environments prioritize chemical resistance and structural load capacity.
- Outdoor:Weather-resistant construction for residential patios and commercial entertainment venues demands freeze-thaw durability.
Residential absorbs unit volume; commercial generates margin concentration.
Installation Type:
Customer type fragmentation separates professional contractor specifications from retail consumer purchases, with diverging channel economics and service attachment rates.
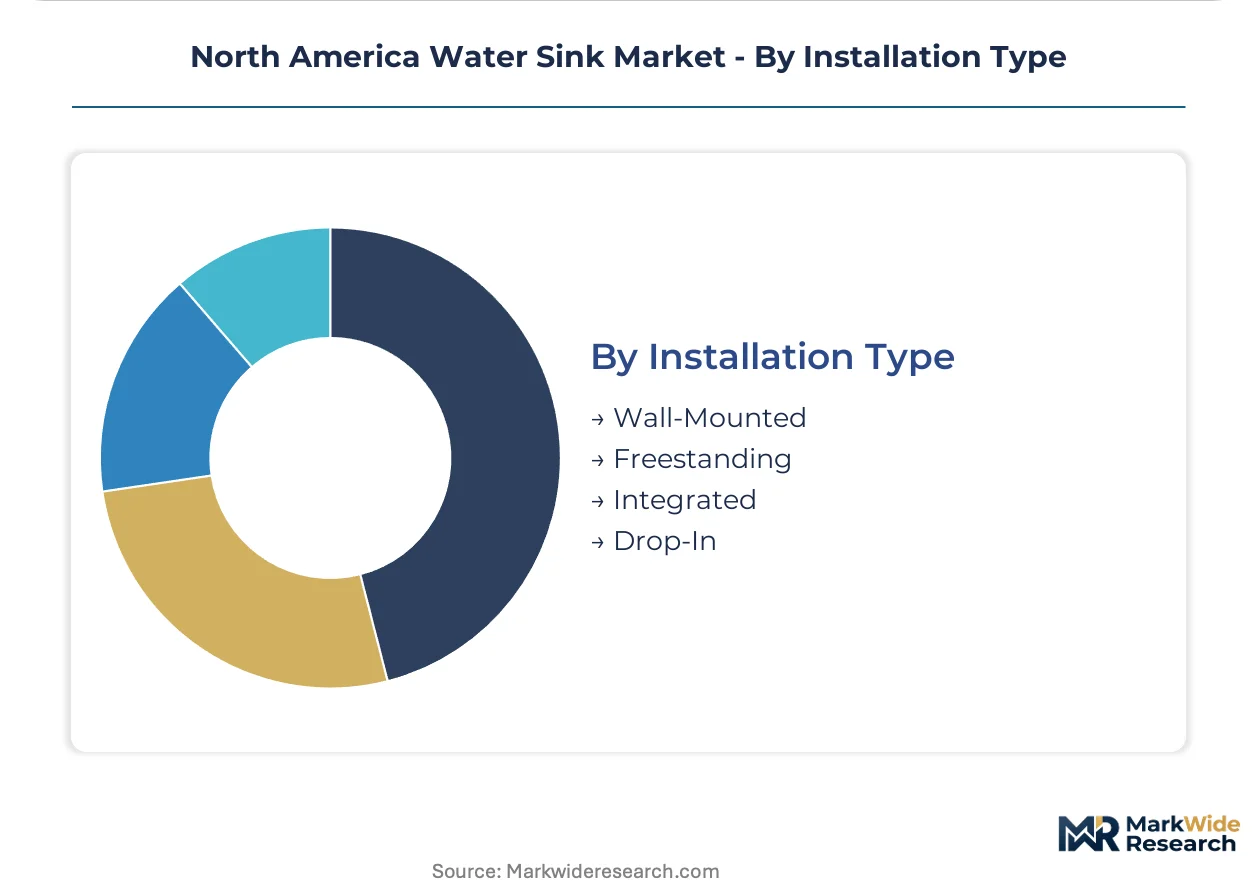
- Wall-Mounted:Suspended basin with concealed carrier system maximizes floor clearance. Commercial restrooms in healthcare and education facilities specify these for accessibility compliance and cleaning efficiency.
- Freestanding:Pedestal or leg-supported design eliminates cabinet requirement. Residential powder rooms in older housing stock favor these for space-constrained retrofits.
- Integrated:Solid-surface countertop with molded basin creates seamless monolithic appearance. High-end California kitchen renovations specify these through custom fabricator networks.
- Drop-In:Rim-supported installation suits replacement scenarios with existing cabinet infrastructure. Big-box retail channels move these for consumer self-installation.
Drop-in dominates replacement velocity; integrated climbs fastest in custom renovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with US residential renovation cycles driving premium fixture demand while Canadian provincial codes accelerate low-flow adoption and Mexican industrial clusters serve cross-border supply chains.
United States
California Title 20 mandates and Texas administrative codes on plumbing efficiency fragment regional product assortments. EPA WaterSense certification requirements compress development timelines for integrated basin-and-faucet systems. Sun Belt metro construction in Phoenix, Dallas, and Miami concentrates builder-grade stainless steel procurement through centralized purchasing platforms.
Canada
British Columbia and Ontario municipal green building amendments exceed federal baselines, creating specification entry points for low-flow aerator integration. CSA Group testing timelines extend market entry cycles behind US approval windows. Ontario mill proximity anchors stainless steel fabrication capacity serving both domestic and US export demand.
Mexico
Cross-border manufacturing clusters in Nuevo León and Baja California supply component fabrication for US assembly operations. Local residential construction in Mexico City Metro and Guadalajara absorbs mid-tier drop-in configurations. Freight corridors through Laredo and Tijuana concentrate enameled cast iron distribution for southwestern US markets.
North America Water Sink Market Competitive Landscape
Capability concentration sits with specialized fabricators holding NSF-certified welding capacity; scale advantage sits with diversified plumbing fixture conglomerates commanding captive distribution networks. The vendor base separates into three functional tiers: European design heritage players, North American mill-proximate fabricators, and full-line plumbing conglomerates. Competitive moves cluster around proprietary mounting system development and direct-to-contractor digital platform construction.
Among diversified plumbing conglomerates, Kohler Co. and Moen Incorporated exemplify scale-driven portfolio breadth spanning residential and commercial specification tiers. Elkay Manufacturing Company anchors the commercial fabrication segment through NSF-certified capacity concentrated in upper Midwest industrial corridors. Franke Kitchen Systems, LLC represents European design heritage translation for North American dimensional and regulatory requirements.
| Leading Market Players |
|---|
| Kraus USA |
| American Standard Brand |
| Kohler Co. |
| Blanco America, Inc. |
| Franke Kitchen Systems, LLC |
| Elkay Manufacturing Company |
| Ruvati |
| Moen Incorporated |
| ROHL LLC. |
| Others |
Value Network & Pricing Analysis
Laredo-Tijuana freight corridors concentrate enameled cast iron distribution cost dynamics, amplifying price differentiation between Tennessee foundry output and Ontario stainless steel mill proximity while compressing margins for heavy-material configurations across southwestern US builder markets.
Pricing Analysis
Long-term offtake contracts dominate builder-grade stainless steel procurement through centralized multi-family developer platforms, while spot purchasing persists for custom fabrication orders. Price differentiation separates NSF-certified commercial tiers from residential grades, with California Title 20 compliance adding certification cost premiums. Pricing pressure intensifies in cast iron segments as freight economics erode distribution radius competitiveness against composite substitutes. Multi-family developers in Texas and Florida exhibit highest price sensitivity; luxury single-family renovators in California show lowest.
Supply Chain Analysis
Chromium-nickel feedstock draws from Ontario and Pennsylvania mill capacity, with composite resin inputs sourcing from Asian chemical processors. Raw material dependencies center on nickel price volatility, stainless steel coil availability, and granite-quartz composite precursor chemicals. Supply chain risk concentrates in single-source NSF-certified welding capacity clustering Wisconsin and Illinois. Distribution runs through captive networks for major conglomerates and independent fabricator-direct channels for regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across California Title 20, Texas administrative codes, and Canadian provincial amendments fragments specification requirements, creating niche entry points for compliance-specialized fabricators and digital specification platforms.
For Market Incumbents: Insulate margin pools by deepening captive distribution control through Procore-integrated procurement portals and proprietary mounting system ecosystems that lock replacement hardware demand. Counter composite substitution threats with stainless steel weight-reduction engineering and NSF-certified capacity expansion in upper Midwest welding clusters. Prioritize vertical integration into Ontario mill relationships for raw material cost stability.
For New Entrants and Emerging Players: Pursue specification gaps in Canadian provincial green building code compliance, where CSA Group testing lag creates 8-14 week entry windows behind US EPA WaterSense approvals. Target British Columbia and Ontario municipal amendments exceeding federal baselines for low-flow aerator integration partnerships. Enter through direct-to-contractor digital platforms bypassing traditional distributor markups.
For Investors and Strategic Acquirers: NSF-certified commercial fabrication specialists with concentrated upper Midwest welding capacity represent prime acquisition targets for margin expansion through specification-grade pricing power. Long-term viability hinges on regulatory compliance capability rather than pure scale. Watch California Energy Commission appliance standard tightening as inflection signal for integrated system certification overhead.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mounting System Development | Captive replacement parts ecosystems lock recurring revenue streams for undermount and farmhouse configurations. |
| NSF-Certified Welding Capacity Expansion | Wisconsin and Illinois fabrication clusters command margin premiums through commercial foodservice specification access. |
| Direct-to-Contractor Digital Platform Launch | Procore-integrated procurement portals bypass distributor costs for Sun Belt multi-family developer concentration. |
| Composite Material R&D Investment | Granite-quartz resin blends displace cast iron weight penalties while maintaining thermal mass for California renovations. |
| CSA Group Certification Fast-Track | Accelerated Canadian market entry captures British Columbia and Ontario green building code specification windows. |
Research Methodology
Cross-validation between distributor procurement data and municipal building permit records anchors the qualitative findings in observable demand patterns. Primary interviews with kitchen renovation contractors, commercial foodservice specification writers, NSF certification auditors, and multi-family developer procurement officers combine with secondary validation through EPA WaterSense certification databases, California Energy Commission appliance standard filings, and Ontario mill production disclosures. Bottom-up unit demand modeling triangulates against top-down construction spending allocations.
Calibration against historical replacement cycle patterns and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product configuration type, material grade tier, installation environment, and regional regulatory cluster. CAGRs derive from installed base aging curves and housing start correlations. Industry-specific forecast inputs incorporate nickel price futures and municipal green building ordinance adoption rates.
Macroeconomic conditions sit as an overlay; deviation in residential construction lending rates and stainless steel input costs would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and cross-border certification timeline stability. Cross-checking against American Iron and Steel Institute production data and NAHB renovation spending indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Spain Water Consumption Market
Water Management
Mexico Water Consumption Market
Water Management
Water Free Urinals Market
Water Management
Water Utility Services Market
Water Management
France Water Consumption Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Chile Water Consumption Market
Water Management
Smart Water Network Market
Water Management
Water Filters Market
Water Management
NRW Smart Leak Management Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Water Trading Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Municipal Water Market
Water Management
Smart Water Management Market
Water Management
Global Water Market