
 Mobile Water Treatment Services Market | 2026-2036
Mobile Water Treatment Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Water Treatment Services Market Insights
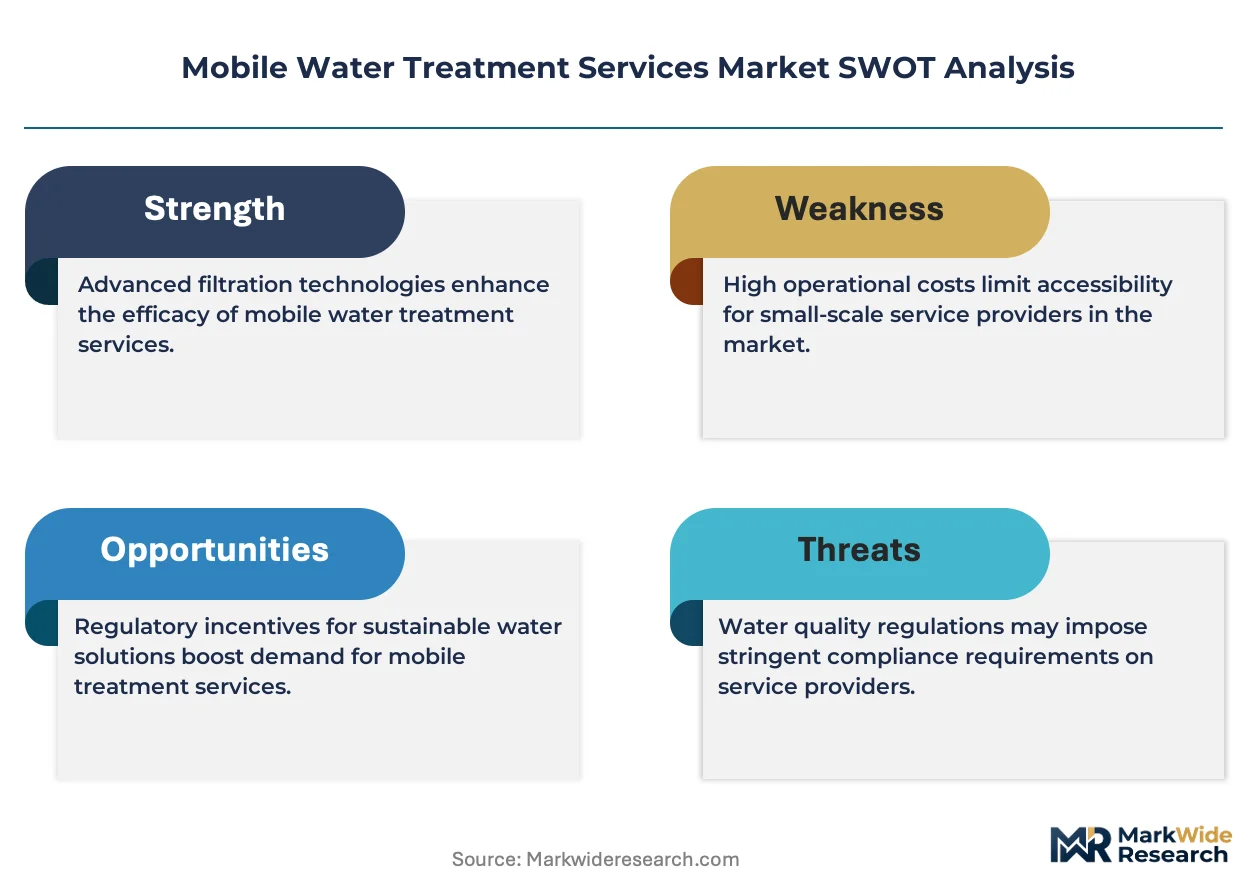
North American shale field expansion is reshaping deployment patterns for mobile water treatment fleets. Veolia Water Technologies leverages its fleet scale across the Permian and Bakken formations to sustain contract renewal rates. SUEZ Water Technologies & Solutions anchors its position through integrated chemical supply and mobile unit bundling. Evoqua Water Technologies differentiates with rapid-response trailer systems designed for industrial emergency deployment.
Mobile water treatment services encompass transportable, skid-mounted or trailer-based systems that deliver on-site purification, filtration, and chemical conditioning without permanent infrastructure installation. These units typically process flows from 50 to 5,000 gallons per minute using membrane arrays, ion exchange vessels, or ultraviolet disinfection trains to meet discharge permits or process water specifications. Reverse osmosis dominates service type revenue due to its versatility across brackish groundwater, produced water, and boiler makeup applications. Membrane technology leads the technology dimension with widening adoption of ceramic and polymeric ultrafiltration pretreatment stages that reduce chemical consumption and extend downstream reverse osmosis membrane life. Municipalities represent the most mature end user segment with predictable seasonal demand, while industrial emergency response applications command premium pricing due to uptime guarantees and 24-hour mobilization requirements.
The EPA enforces effluent limitation guidelines that mandate zero liquid discharge or advanced treatment at power generation and chemical manufacturing facilities, directly stimulating mobile unit rentals during compliance upgrades. OSHA confined space and chemical handling standards govern worker exposure during mobile system deployment and regeneration operations, shaping training and equipment design requirements. State-level water rights frameworks in Texas, Colorado, and California create permitting complexity that favors established service providers with regulatory navigation capabilities. Stakeholders must monitor evolving produced water recycling mandates and emerging PFAS treatment standards that will redefine mobile system technical specifications and competitive positioning.
Market Dynamics
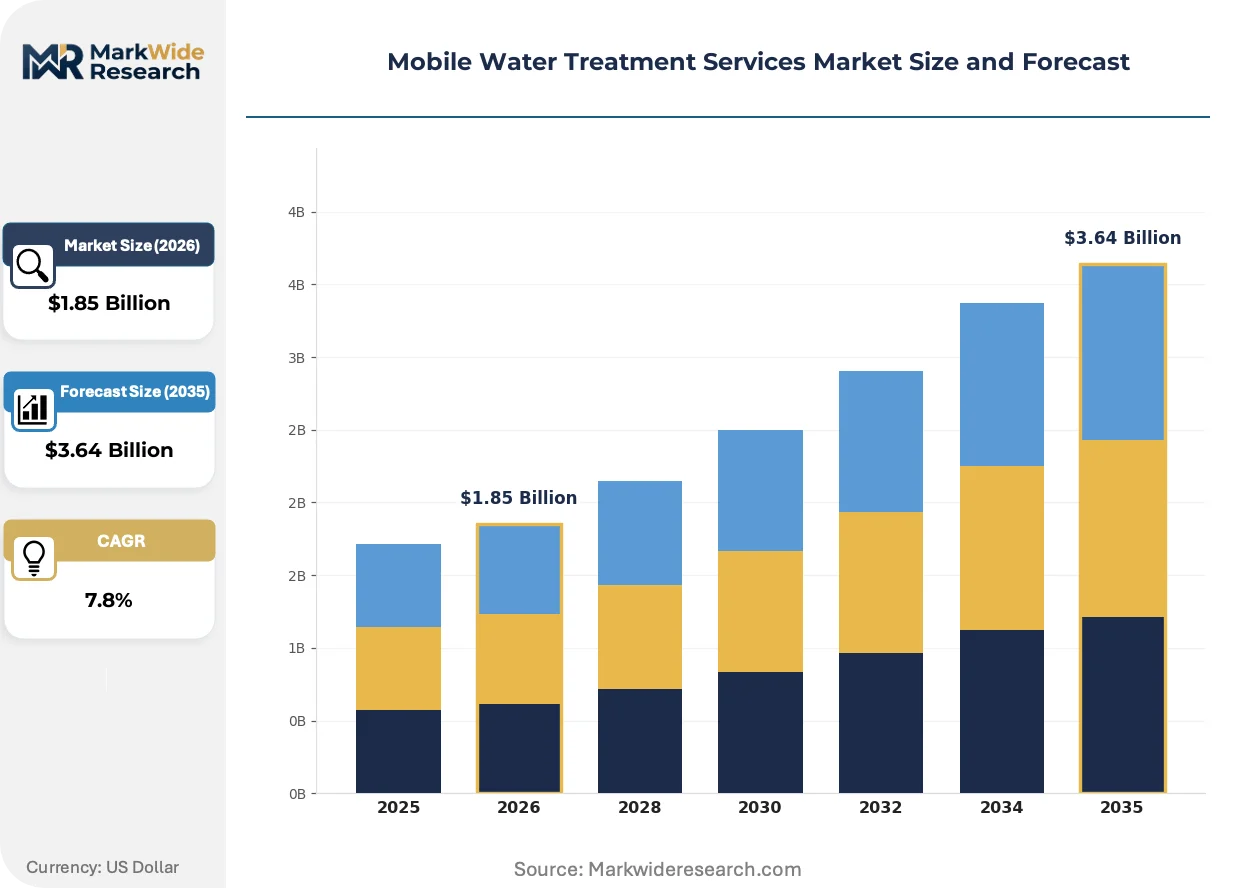
The EPA's tightened effluent limitation guidelines for steam electric power generation are forcing utilities toward on-site compliance investments, compressing deployment timelines for mobile reverse osmosis fleets and elevating rental contract values.
Growth Catalysts
- Zero Liquid Discharge Mandates:The EPA's ELG rules for power generation facilities mandate advanced treatment, compelling utilities to rent mobile units during permanent infrastructure upgrades.
- Permian Basin Fracturing Demand:Hydraulic fracturing operations in Texas and New Mexico require high-volume mobile filtration for produced water management, sustaining fleet utilization rates.
- Membrane Technology Advancement:Ceramic and polymeric ultrafiltration pretreatment stages reduce chemical consumption and extend reverse osmosis membrane life, lowering total operating costs.
Market Restraints
- Specialized Skilled Labor Scarcity:OSHA confined space and chemical handling standards require certified technicians for mobile system deployment, constraining fleet expansion speed.
- State Water Rights Fragmentation:Permitting complexity across Texas, Colorado, and California creates regulatory friction that favors incumbents with established compliance navigation capabilities.
- Mobile-First Substitution Risk:Modular permanent plants with faster installation timelines threaten rental demand for long-term industrial water treatment contracts.
Strategic Opportunities
- PFAS Treatment Standards:Emerging federal and state mandates for per- and polyfluoroalkyl substances removal will redefine mobile system technical specifications and create upgrade cycles.
- Emergency Response Premium Pricing:Industrial uptime guarantees and 24-hour mobilization requirements command pricing multiples above municipal seasonal contracts.
- Produced Water Recycling Mandates:Texas and New Mexico regulatory frameworks are evolving toward mandatory recycling thresholds, expanding addressable volume for mobile treatment providers.
Industry Challenges
- Cross-State Permitting Velocity:Water rights frameworks vary across jurisdictions, forcing operators to maintain redundant regulatory expertise and delaying deployment timelines.
- Legacy System Integration Complexity:Mobile units must interface with existing boiler feedwater and cooling tower infrastructure, requiring custom engineering that compresses margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Water Treatment Services Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Filtration, Ion Exchange, Reverse Osmosis, UV Treatment Technology: Membrane Technology, Activated Carbon, Chemical Treatment, Advanced Oxidation End User: Municipalities, Industries, Construction, Events Application: Emergency Response, Water Supply, Wastewater Treatment, Desalination |
| Companies Covered | Veolia Water Technologies, SUEZ Water Technologies & Solutions, Xylem, Evoqua Water Technologies, Pall Corporation, Aquatech International, MPW Industrial Services, Culligan Industrial Water, Fluence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Water Treatment Services Market Trends and Innovations
Digital monitoring architectures and membrane material science are compressing the trade-off between treatment performance and operational flexibility, enabling predictive maintenance models that shift cost structures.
Remote telemetry and cloud-based performance analytics are virtualizing the traditional service model. Power generation utilities now demand real-time membrane flux monitoring and automated chemical dosing adjustments. This capability is virtualizing the role of on-site technicians, compressing labor costs while extending equipment runtime between service intervals.
The EPA's effluent limitation guidelines for steam electric power generation are mandating specific contaminant removal thresholds. Facilities must achieve numeric limits for selenium, mercury, and total dissolved solids. Coal-fired plants in the Ohio River Valley are responding with extended mobile unit rentals during permanent treatment system construction.
Asset-light contracting is displacing capital purchase preferences among mid-size industrial water users. Chemical manufacturing facilities now favor operational expenditure models with guaranteed output specifications. This shift is most visible in the Gulf Coast petrochemical corridor, where hurricane-driven emergency response requirements have normalized rental-first procurement.
Mobile Water Treatment Services Market Segmentation
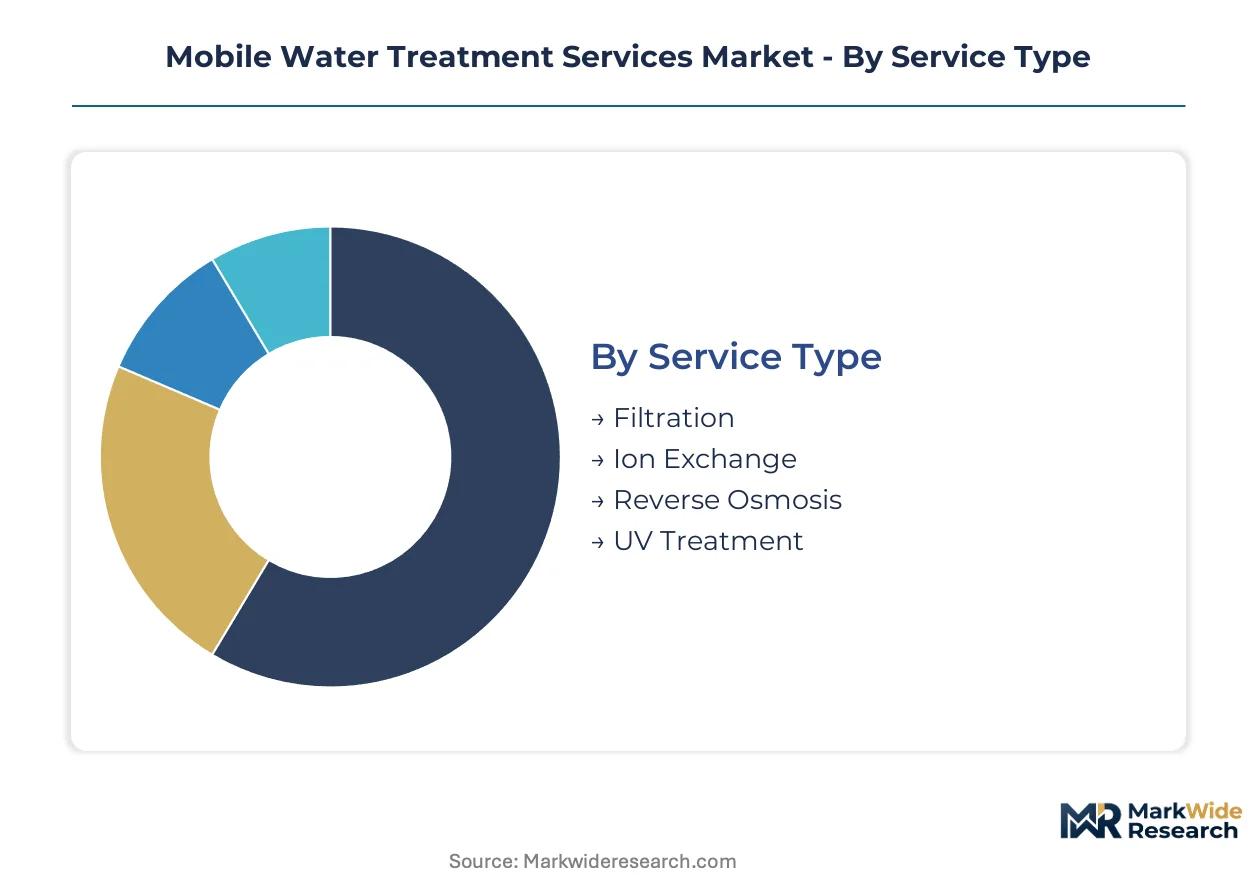
Segmentation in mobile water treatment services reveals distinct procurement rhythms and margin profiles. Contract duration varies dramatically across service types and end users, from seasonal municipal rentals to multi-year industrial emergency retainers.
Service Type:
Reverse osmosis commands the longest deployment cycles while filtration services turn over fastest due to lower capital commitment and simpler mobilization.
- Reverse Osmosis:Mobile RO units process brackish groundwater, produced water, and boiler makeup through semi-permeable membrane arrays achieving dissolved solids rejection above 95%. Power generation utilities in Texas and New Mexico deploy these for extended compliance-driven rentals during permanent infrastructure construction.
- Filtration:Portable media filtration systems remove suspended solids through sand, anthracite, or multimedia vessels sized for 50 to 5,000 gallons per minute. Permian Basin hydraulic fracturing operations drive rapid-turn rentals for produced water pretreatment ahead of deep injection or recycling.
- Ion Exchange:Regenerable resin vessels target specific ionic contaminants including hardness, heavy metals, and nitrates for boiler feedwater conditioning.
- UV Treatment:Ultraviolet disinfection trains provide pathogen inactivation without chemical residuals for municipal supplemental supply and event water security.
Reverse osmosis anchors the volume base while filtration gains share at the steepest rate.
Technology:
Membrane-based approaches occupy the premium cost tier while chemical treatment dominates mid-market procurement through lower upfront capital requirements.
- Membrane Technology:Ceramic and polymeric ultrafiltration pretreatment stages reduce chemical consumption and extend downstream reverse osmosis membrane life. EPA effluent limitation guidelines for selenium and mercury removal drive adoption at coal-fired power facilities in the Ohio River Valley.
- Chemical Treatment:Coagulation, flocculation, and pH adjustment systems deliver rapid deployment for construction dewatering and temporary municipal supply. Gulf Coast petrochemical corridors favor operational expenditure models with guaranteed output specifications.
- Activated Carbon:Granular activated carbon vessels adsorb organic compounds, chlorine, and emerging contaminants including PFAS precursors.
- Advanced Oxidation:Hydroxyl radical generation through ozone/UV or peroxide catalysis destroys recalcitrant organics and pharmaceutical residues.
Membrane technology captures the highest contract values while chemical treatment expands most quickly through asset-light procurement preferences.
End User:
Industrial customers generate the most volatile demand spikes while municipalities provide predictable seasonal baseload.
- Industries:Manufacturing, refining, and power generation facilities rent mobile units during compliance upgrades, turnaround maintenance, or emergency infrastructure failure. OSHA confined space certification requirements constrain technician supply, elevating pricing for 24-hour mobilization guarantees.
- Municipalities:Cities and water districts deploy seasonal capacity for drought supplementation, main break response, and festival water security. Texas and Colorado state water rights frameworks create permitting complexity that favors established providers.
- Construction:Dewatering and dust suppression applications require high-volume, short-duration filtration for site runoff management.
- Events:Temporary water supply for sports venues, concerts, and disaster relief shelters demands rapid deployment with minimal site preparation.
Municipalities anchor the volume base while industrial emergency response climbs the fastest.
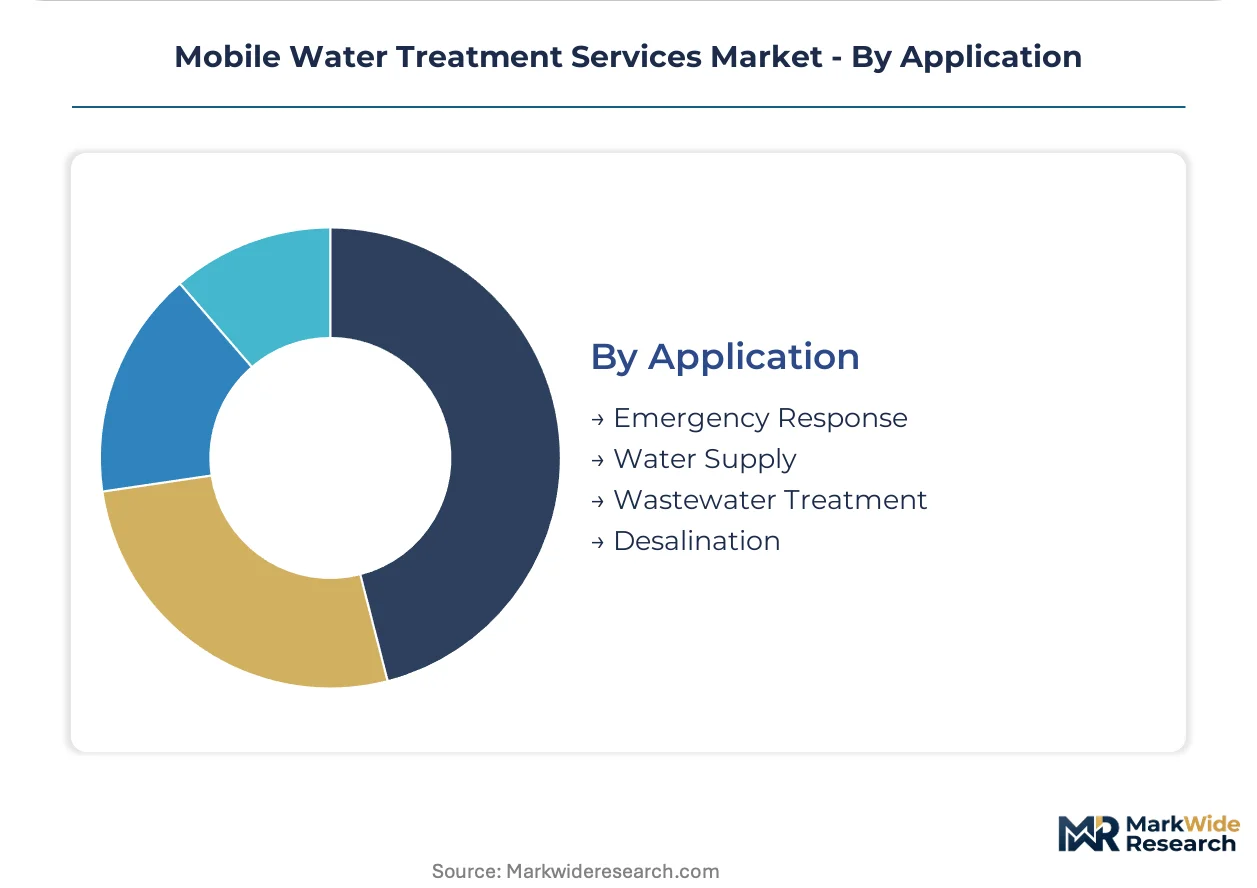
Application:
Emergency response commands premium pricing multiples while water supply applications scale through recurring municipal procurement.
- Emergency Response:Hurricane-driven infrastructure failures and industrial accidents require immediate mobilization with uptime guarantees. Gulf Coast petrochemical corridors have normalized rental-first procurement following repeated storm seasons.
- Water Supply:Temporary potable water production for municipalities, military bases, and remote facilities employs reverse osmosis and UV disinfection trains. California groundwater basin management plans stimulate seasonal demand.
- Wastewater Treatment:Mobile biological and membrane bioreactor systems achieve discharge permit compliance during plant upgrades or capacity constraints.
- Desalination:Seawater and brackish groundwater conversion serves coastal industrial facilities and island communities through energy-intensive reverse osmosis configurations.
Water supply anchors the volume base while emergency response gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines for steam electric power generation anchor demand concentration in the United States, while hydraulic fracturing expansion in the Permian Basin sustains fleet utilization rates across North American shale formations.
United States
Coal-fired power plants in the Ohio River Valley deploy mobile reverse osmosis units for selenium and mercury removal mandated by EPA effluent rules. OSHA confined space certification requirements constrain technician supply, elevating pricing for 24-hour mobilization guarantees. The Permian Basin spanning Texas and New Mexico concentrates hydraulic fracturing demand where produced water recycling thresholds are tightening.
Canada
Oil sands operations in Alberta require mobile filtration for process water management and tailings pond treatment. Health Canada guidelines for mining effluent quality shape procurement specifications for remote site deployment. The Athabasca oil sands region sustains seasonal demand peaks tied to extraction schedules and environmental compliance windows.
Germany
Chemical manufacturing clusters along the Rhine River rent mobile units during plant turnaround maintenance and emergency response scenarios. REACH regulation compliance for industrial discharge standards drives specification rigor in membrane system selection. The BASF-Ludwigshafen chemical complex anchors recurring demand for guaranteed-output contracting models.
China
Coal power plants in Shanxi and Inner Mongolia provinces deploy mobile treatment during flue gas desulfurization wastewater system upgrades. Ministry of Ecology and Environment (MEE) standards for zero liquid discharge at thermal power facilities compress deployment timelines. The Yangtze River Delta industrial corridor generates concentrated demand from petrochemical and electronics manufacturing facilities.
Saudi Arabia
Desalination plant maintenance cycles and industrial city expansion drive mobile unit rentals for temporary process water supply. The Saudi Food and Drug Authority (SFDA) and national water regulator set quality benchmarks for potable water production. Jubail Industrial City and Yanbu petrochemical complexes represent high-value contract concentrations for rapid-response trailer systems.
Mobile Water Treatment Services Market Competitive Landscape
Integrated service conglomerates and specialized mobility providers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: full-service environmental conglomerates with fleet scale advantages, technology-originated specialists with membrane engineering depth, and regional mobility operators with rapid-deployment logistics. Competitive dynamics center on contract bundling with chemical supply and geographic fleet positioning near shale basins.
Among full-service environmental conglomerates, Veolia Water Technologies and SUEZ Water Technologies & Solutions exemplify the integrated-chemical-supply archetype that sustains renewal rates through bundled service contracts. Evoqua Water Technologies occupies a position within the rapid-response specialist tier, anchoring premium pricing for industrial emergency deployment scenarios. These three entities represent contrasting strategic postures: fleet scale versus chemical integration versus mobilization velocity.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ Water Technologies & Solutions |
| Xylem |
| Evoqua Water Technologies |
| Pall Corporation |
| Aquatech International |
| MPW Industrial Services |
| Culligan Industrial Water |
| Fluence Corporation |
| Others |
Pricing and Supply Chain Analysis
The I-10 corridor connecting Houston to Midland anchors fleet logistics cost dynamics for mobile water treatment providers, concentrating supply-side power among operators with Permian Basin positioning while forcing three-tier pricing stratification across emergency response, seasonal municipal, and long-term industrial contract tiers.
Pricing Analysis
Price spreads between Gulf Coast petrochemical corridors and Appalachian shale regions exceed 40% for equivalent reverse osmosis capacity, reflecting mobilization distance and technician certification scarcity. Contract structures favor operational expenditure models with guaranteed output specifications, particularly among chemical manufacturing facilities seeking hurricane-driven emergency coverage. Price differentiation hinges on 24-hour mobilization guarantees and OSHA confined space certification tiers, with municipal seasonal contracts showing highest price sensitivity and industrial emergency retainers demonstrating lowest. Pricing pressure stems from modular permanent plant alternatives compressing long-term rental margins.
Supply Chain Analysis
Membrane module contract manufacturing concentrates in the United States, Germany, and Japan, with ceramic ultrafiltration elements sourced from specialized foundries in Bavaria and Nagoya. Raw material dependencies span polymeric membrane substrates, pressure vessel alloys, and regenerable ion exchange resins. Single-source vulnerability runs through ceramic membrane supply chains where qualified alternative suppliers require 18-month qualification cycles. Distribution feeds from regional fleet depots positioned near shale basins, with trailer-mounted systems pre-staged in Texas, North Dakota, and Pennsylvania to compress deployment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity constrains fleet expansion velocity, creating defensive moats for incumbents with established OSHA-compliant workforces while fragmenting competitive access for capital-backed entrants lacking operational depth.
For Market Incumbents: Harden position through backward integration into membrane regeneration capabilities and captive technician training academies. Veolia and SUEZ fleet scale advantages are vulnerable to modular permanent plant substitution; anchor renewal rates by bundling chemical supply with mobile unit deployment. Prioritize Permian Basin fleet density to capture produced water recycling mandate volume. For New Entrants and Emerging Players: Pursue white-space concentration in PFAS treatment trailer systems ahead of federal mandate finalization. Texas and New Mexico produced water recycling thresholds create penetrable demand among mid-size hydraulic fracturing operators underserved by integrated conglomerates. Lead with rapid-response logistics and 4-hour mobilization guarantees versus incumbent 24-hour baselines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane engineering specialists with ceramic ultrafiltration IP and established EPA compliance navigation capabilities. Long-term viability rests on PFAS treatment upgrade cycles and produced water recycling infrastructure gaps across North American shale formations. Monitor EPA effluent limitation guideline enforcement velocity and state-level recycling mandate adoption as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Treatment Technology Integration | Positions providers for EPA mandate compliance ahead of 2025-2026 regulatory finalization windows. |
| Technician Certification Academy Buildout | Addresses OSHA confined space scarcity constraining fleet expansion across Permian and Bakken basins. |
| Produced Water Recycling Infrastructure Partnership | Captures volume from Texas Railroad Commission recycling threshold mandates for hydraulic fracturing operators. |
| Membrane Regeneration Capability Acquisition | Reduces operating cost exposure to single-source ceramic module suppliers in Germany and Japan. |
| Emergency Response Retainer Portfolio Expansion | Secures premium pricing multiples through hurricane-driven Gulf Coast petrochemical corridor demand normalization. |
Research Methodology
Initial hypotheses were tested against primary input from mobile fleet operations directors, EPA regulatory compliance officers, Permian Basin hydraulic fracturing procurement leads, and ion exchange resin technical specialists, then refined through secondary validation against EPA effluent limitation guideline dockets, Texas Railroad Commission produced water recycling filings, SEC 10-K disclosures from listed water treatment providers, and OSHA confined space incident databases. Bottom-up unit deployment estimates triangulated against top-down addressable volume calculations.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, membrane technology tier, end-user industry vertical, and regional shale basin concentration. CAGRs derived from fleet utilization rate trajectories and contract value escalation patterns, incorporating EPA enforcement timeline assumptions and state water rights permitting velocity as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in oilfield activity levels, interest rate environments affecting capital expenditure preferences, and tariff exposure on imported membrane modules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement cadence and produced water recycling mandate adoption. Quarterly review of EPA consent decree filings, state legislative session outcomes, and fleet expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Water Purification Tablets Market