
 Asia-Pacific Water Sink Market | 2026-2036
Asia-Pacific Water Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Sink Market Outlook
Modular sink-and-faucet bundling is realigning procurement patterns across Asia-Pacific residential projects. Kohler leverages its integrated bathroom systems to control specification channels in premium developments. JOMOO anchors mass-market supply through dense distributor networks in second-tier Chinese cities. Franke specializes in stainless steel fabrication depth, competing on material consistency rather than price alone.
Asia-Pacific water sinks are basin fixtures engineered for wastewater collection and drainage, typically fabricated from stainless steel, porcelain, or composite materials with standardized drain openings and overflow channels. These units serve as essential sanitary ware in residential kitchens and bathrooms, commercial food preparation areas, and hospitality facilities across the region. Undermount and drop-in configurations dominate residential retrofit activity, while wall-mounted and vessel variants capture margin in boutique hospitality projects. Stainless steel and composite materials lead volume, though granite surfaces command pricing premiums in premium residential segments across Australia and Japan.
China's GB standards for sanitary ware, India's BIS certification requirements, and Australia's WaterMark scheme collectively shape product compliance costs and market access timelines. India's PLI scheme for domestic manufacturing incentivizes local assembly, reducing import dependency for standardized stainless steel models. Stakeholders must monitor evolving water-efficiency labeling across ASEAN member states, as harmonized standards could reshape cross-border sourcing strategies and factory certification investments.
Market Dynamics
Modular sink-and-faucet bundling is compressing traditional specification channels across Asia-Pacific residential construction, forcing fixture manufacturers to integrate vertically into full sanitary systems or surrender margin to platform distributors.
Growth Catalysts
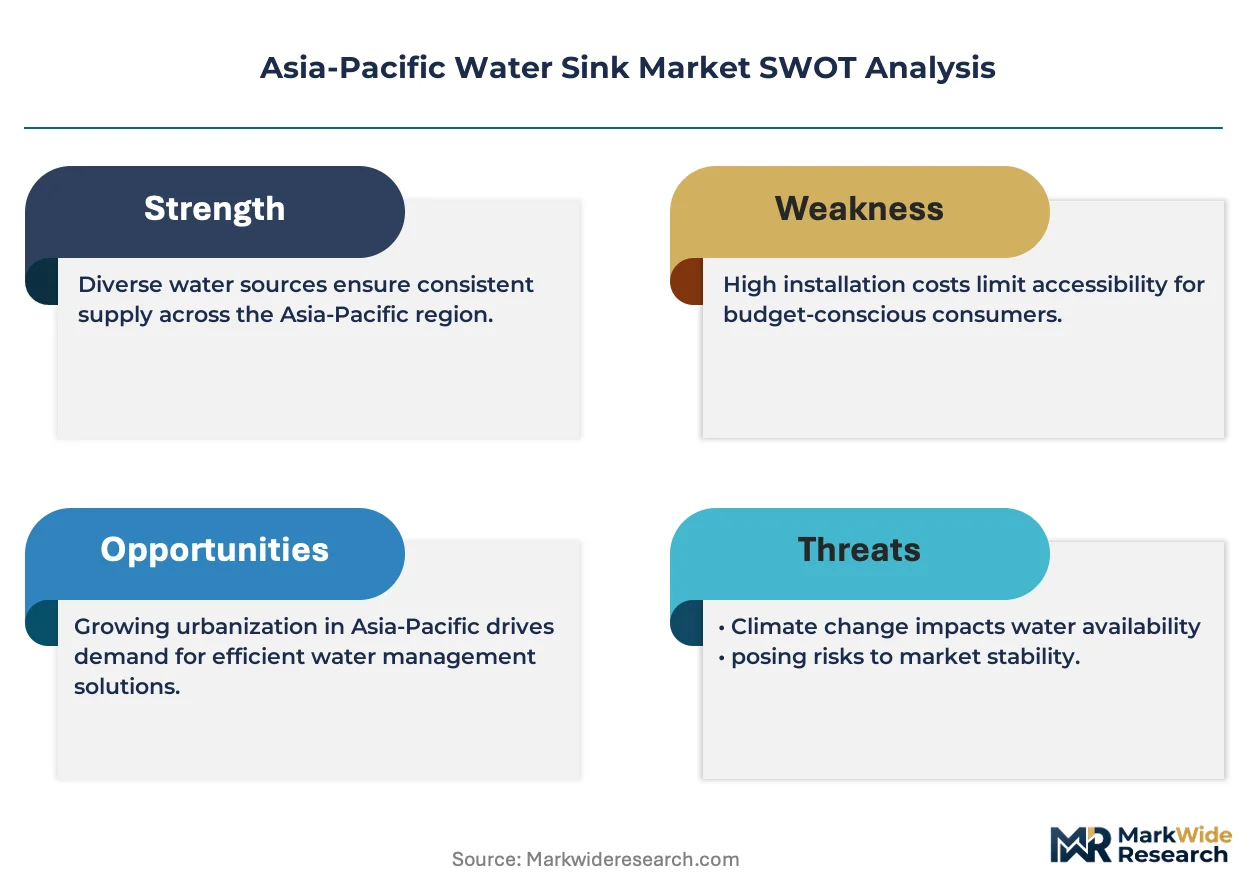
- India's BIS certification mandate:Import compliance barriers for plumbing products redirect procurement toward certified domestic fabricators, accelerating local stainless steel sink assembly capacity.
- Urban renewal in China's tier-two cities:Kitchen and bathroom retrofit cycles concentrate demand for undermount and drop-in configurations in Chengdu, Xi'an, and Wuhan property markets.
- Southeast Asian residential construction:Fixture replacement waves across Vietnam, Indonesia, and Thailand drive volume for standardized drain-opening configurations in mass housing developments.
Market Restraints
- Nickel price volatility:Stainless steel 304 grade production faces input cost swings that compress fabricator margins on economy-tier basin units.
- China supply concentration:Guangdong and Zhejiang provinces control 70% of regional casting and polishing capacity, creating single-source vulnerability for ASEAN importers.
- Water-efficiency labeling fragmentation:Non-harmonized standards across ASEAN member states extend factory certification timelines and duplicate testing expenditure.
Strategic Opportunities
- India's PLI scheme for domestic manufacturing:Production-linked incentives for sanitary ware assembly reduce import dependency and open margin capture for localized stainless steel fabrication.
- Boutique hospitality vessel sinks:Wall-mounted and above-counter configurations command pricing premiums in Japan and Australia's premium residential and hotel renovation segments.
- Granite composite surface technology:Material convergence between engineered stone durability and porcelain aesthetics targets Australia's high-end kitchen specification channels.
Industry Challenges
- GB standards compliance timelines:China's sanitary ware certification updates require 4-6 month retesting cycles that delay product launches and tie up working capital.
- Multi-material fabrication skill gaps:Composite granite and stainless steel hybrid production demands specialized welding and polishing technicians scarce in Vietnam and Indonesia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Sink Market |
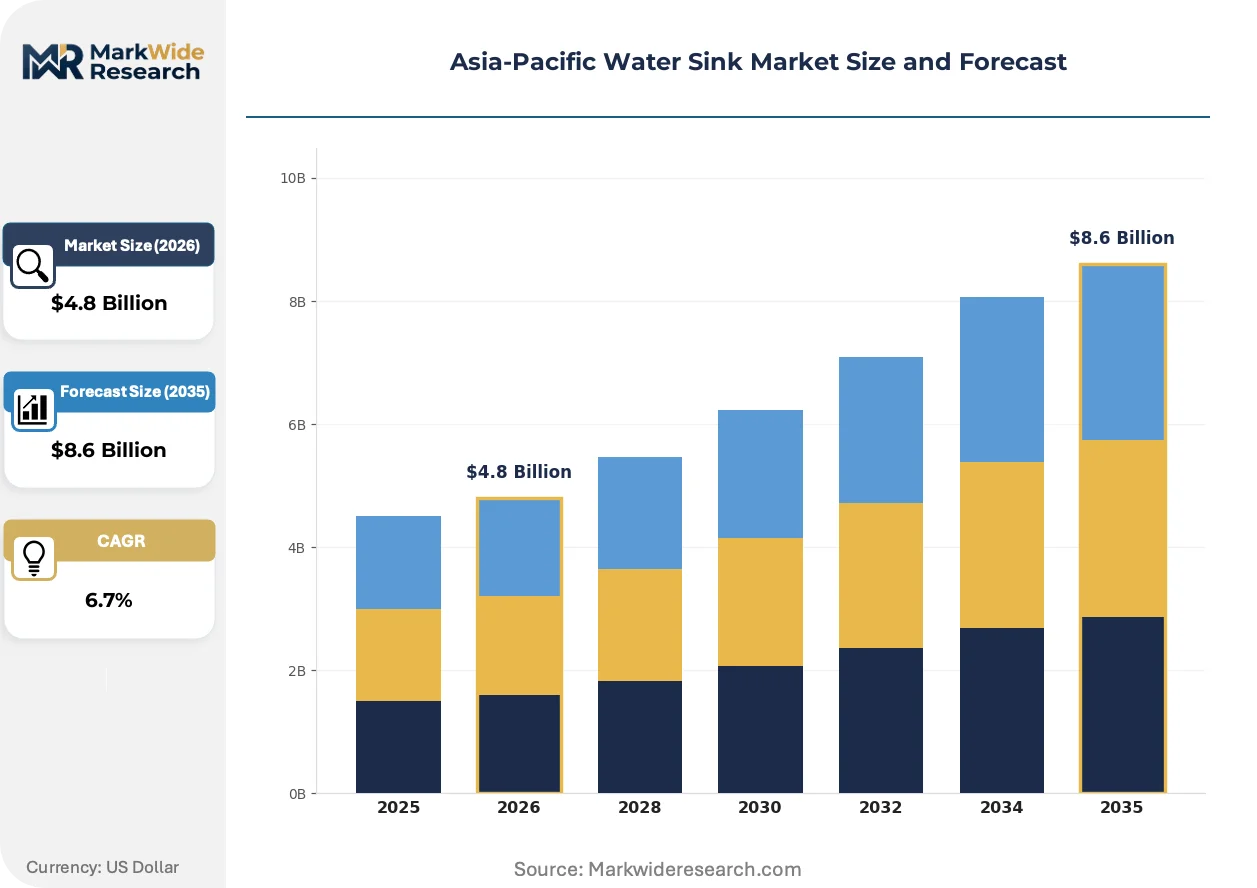
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undermount Sink, Drop-in Sink, Wall-mounted Sink, Vessel Sink Material: Stainless Steel, Porcelain, Composite, Granite Application: Residential Use, Commercial Use, Hospitality Sector, Industrial Sector Installation Type: Top-mounted, Under-mounted, Integrated, Freestanding |
| Companies Covered | Kohler, Franke, Elkay, Blanco, Roca, TOTO, JOMOO, Duravit, American Standard, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Sink Market Strategic Shifts
Material science convergence and procurement platform consolidation are actively restructuring how basin fixtures reach end-users across the region's fragmented construction supply chains.
Antimicrobial copper-alloy drain assemblies are electrifying specification preferences in healthcare and food-service installations across Australia and Japan. Hospital procurement departments specify these fixtures for surgical scrub stations and commercial kitchens at accelerating replacement frequencies. The technology is electrifying competitive positioning among fabricators capable of metallurgical certification against TGA and PMDA hygiene standards.
China's GB standards for sanitary ware impose stricter lead-content thresholds and overflow-channel dimensional requirements effective across domestic and export-bound production. Manufacturers must retool casting molds and ceramic firing protocols to maintain market access. Premium residential segments in Shanghai and Beijing absorb compliance costs fastest, while mass-market exporters to Southeast Asia face margin compression.
Builder-direct procurement platforms are disintermediating traditional distributor networks in China's second-tier cities. JOMOO and comparable suppliers operate proprietary specification apps that let contractors configure modular sink-faucet bundles without showroom intermediaries. This channel compression is most visible in Chengdu and Hangzhou residential developments where project timelines compress fixture selection windows to 72-hour digital workflows.
Asia-Pacific Water Sink Market Segmentation
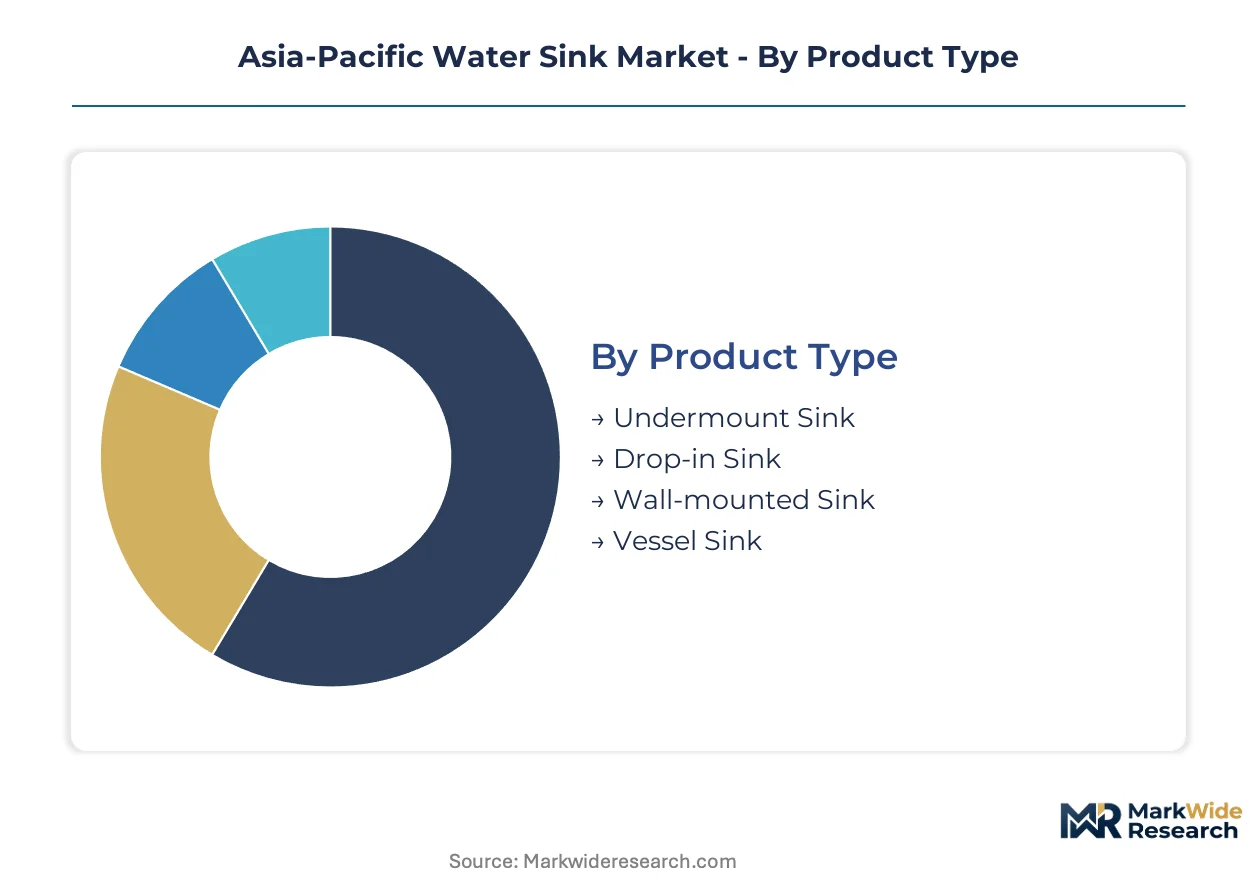
Segmentation in the Asia-Pacific water sink market reveals how procurement patterns split between standalone fixture replacement and integrated sanitary system specifications. Understanding these divides exposes where margin concentrates versus where volume flows.
Product Type:
Undermount and drop-in configurations dominate standalone retrofit activity, while wall-mounted and vessel variants embed into full bathroom system specifications.
- Undermount Sink:Rimless basin design installs beneath countertop surfaces, creating seamless cleaning planes. China's tier-two cities concentrate demand as urban renewal projects specify these for kitchen upgrades in Chengdu and Xi'an residential developments.
- Drop-in Sink:Self-rimming basin with raised edges rests on countertop cutouts, enabling rapid installation without sub-surface support. Mass housing across Vietnam and Thailand favors this configuration for standardized drain-opening compatibility in high-volume construction.
- Wall-mounted Sink:Cantilevered basin attaches directly to vertical surfaces, eliminating floor contact. Boutique hospitality projects in Japan and Australia specify these for space-efficient bathroom layouts.
- Vessel Sink:Above-counter basin sits as a decorative element atop vanities. Premium residential renovations in Australia's high-end kitchen and bathroom segments absorb pricing premiums for granite and composite variants.
Volume placements concentrate in drop-in configurations; the faster expansion belongs to undermount sinks.
Material:
Cost-tier stratification separates commodity-grade fabrication from specification-driven premium surfaces across regional procurement channels.
- Stainless Steel:Austenitic 304-grade sheet metal forms durable, corrosion-resistant basins with standardized drain openings. India's BIS certification mandates redirect procurement toward certified domestic fabricators, accelerating local assembly capacity expansion.
- Porcelain:Vitreous ceramic fired at high temperatures delivers non-porous, stain-resistant surfaces. China's GB standards impose stricter lead-content thresholds that force retooling of casting molds and firing protocols.
- Composite:Engineered stone blends acrylic resins with mineral fillers for impact resistance. Australia's premium kitchen specification channels favor this material for durability-to-aesthetics balance.
- Granite:Natural or engineered stone surfaces command pricing premiums in Japan and Australia's high-end residential segments. Hospitality renovation cycles in boutique hotels specify these for differentiation.
Stainless steel captures the highest shipment volumes; composite surfaces are climbing the fastest specification share.
Application:
End-use concentration determines whether procurement flows through distributor networks or direct-to-builder platform channels.
- Residential Use:Kitchen and bathroom fixture replacement cycles drive standardized basin demand. Southeast Asian mass housing developments in Indonesia and Thailand concentrate volume for economy-tier configurations.
- Commercial Use:Food preparation and institutional facilities require heavy-duty drainage and overflow-channel compliance. Australia's WaterMark scheme shapes product certification costs for this segment.
- Hospitality Sector:Hotel renovation and new-build projects specify design-forward vessel and wall-mounted variants. Japan's boutique hotel segment absorbs antimicrobial copper-alloy drain assemblies at accelerating frequencies.
- Industrial Sector:Manufacturing and processing facilities demand utilitarian stainless steel basins with reinforced structural support. China's industrial zone expansions in Guangdong province concentrate procurement.
Residential applications anchor shipment volumes; hospitality specifications show the steepest margin expansion.
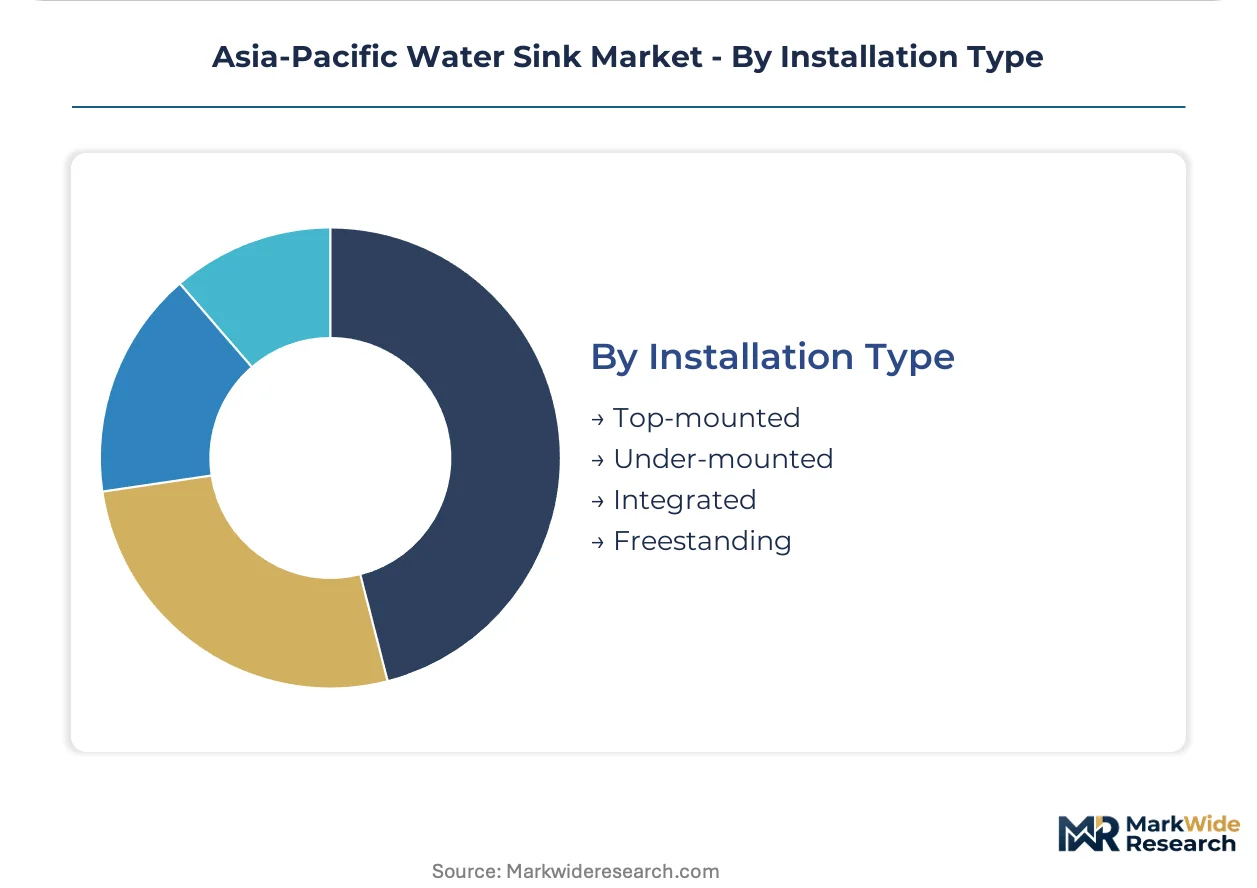
Installation Type:
Installation complexity separates professional-contractor specifications from retail consumer purchases across distribution channels.
- Top-mounted:Self-supporting rim rests on countertop surface, enabling rapid retrofit without cabinet modification. Mass-market retailers across ASEAN member states stock these for consumer-direct replacement cycles.
- Under-mounted:Sub-surface attachment requires precise countertop fabrication and professional installation. China's builder-direct procurement platforms bundle these with modular faucet systems in Chengdu and Hangzhou developments.
- Integrated:Basin and countertop formed as continuous surface eliminate seam maintenance. Premium residential segments in Shanghai and Beijing absorb higher material and labor costs for seamless aesthetics.
- Freestanding:Pedestal or console-mounted units function without cabinet support. Boutique hospitality bathrooms in Australia and Japan specify these for spatial flexibility in compact floor plans.
Top-mounted installations dominate unit volumes; integrated configurations gain specification share fastest in premium urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters supply the majority of regional basin fabrication, while consumption concentrates in India's urbanizing metros and Southeast Asia's residential construction corridors. This production-consumption asymmetry shapes cross-border trade flows and certification arbitrage opportunities.
China
Guangdong and Zhejiang provinces host seventy percent of regional stainless steel casting and polishing capacity, creating concentrated supply leverage. GB standards for sanitary ware impose stricter lead-content thresholds and overflow-channel dimensional requirements that force mold retooling. Chengdu and Hangzhou residential developments drive undermount sink demand through builder-direct procurement platforms.
India
Urban renewal across Mumbai, Delhi-NCR, and Bangalore accelerates kitchen and bathroom fixture replacement cycles in mid-rise housing. BIS certification mandates for plumbing products redirect procurement toward certified domestic fabricators and reduce import dependency. The PLI scheme for domestic manufacturing incentivizes local stainless steel sink assembly capacity expansion in Gujarat and Maharashtra industrial zones.
Japan
Boutique hospitality renovation in Tokyo and Osaka commands pricing premiums for vessel and wall-mounted configurations. PMDA hygiene standards shape antimicrobial copper-alloy drain assembly specifications for healthcare food-service installations. Nagoya-based fabricators specialize in metallurgical certification for surgical scrub station fixtures.
Australia
WaterMark scheme compliance costs shape product certification timelines for commercial food preparation and institutional facilities. Premium residential segments in Sydney and Melbourne absorb granite composite surface pricing for engineered stone durability. Queensland and Western Australia mining camps drive utilitarian stainless steel basin demand with reinforced structural support.
Vietnam
Mass housing developments in Ho Chi Minh City and Hanoi concentrate volume for standardized drop-in configurations with rapid installation compatibility. Multi-material fabrication skill gaps in composite granite and stainless steel hybrid production limit local value capture. Da Nang industrial zones attract Chinese component suppliers seeking tariff diversification.
Asia-Pacific Water Sink Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement channel control and material technology depth. The vendor base stratifies into three tiers: integrated bathroom system providers commanding specification influence, mass-market fabricators anchoring distributor density, and stainless steel specialists competing on metallurgical consistency. Strategic moves center on backward integration into faucet and drainage component production, plus geographic expansion through certified assembly partnerships in India and Vietnam.
Among Asia-Pacific fabricators, Kohler and JOMOO exemplify divergent channel strategies. Kohler occupies a position within the integrated-systems archetype, leveraging full bathroom portfolios to control specification flows in premium developments. JOMOO anchors mass-market supply through dense distributor networks in second-tier Chinese cities. Franke represents the materials-specialist archetype, competing on stainless steel fabrication depth rather than price positioning alone.
| Leading Market Players |
|---|
| Kohler |
| Franke |
| Elkay |
| Blanco |
| Roca |
| TOTO |
| JOMOO |
| Duravit |
| American Standard |
| Others |
Value Chain & Pricing Dynamics
Modular sink-faucet bundling across China's tier-two cities is compressing specification timelines to 72-hour digital workflows, forcing fabricators to absorb retooling costs for GB standards compliance or surrender margin to platform distributors controlling procurement access.
Pricing Analysis
Margin tightening in economy-tier stainless steel units reflects nickel price volatility feeding through 304-grade sheet production. Three-tier pricing structure across premium, standard, and economy levels separates WaterMark-certified commercial fixtures from BIS-compliant domestic assembly and unbranded ASEAN imports. Australia's hospitality segment shows least price sensitivity for antimicrobial copper-alloy drains; Vietnam's mass housing developers drive hardest bargaining on drop-in configurations.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong and Zhejiang provinces, where seventy percent of regional casting and polishing capacity concentrates. Stainless steel coil draws from Chinese mills; acrylic resin and mineral fillers for composites hinge on petrochemical supply chains. Tariff exposure threatens ASEAN importers dependent on Chinese component flows. Distribution runs through builder-direct platforms in Chengdu and Hangzhou, traditional distributor networks in India, and retail channels across Southeast Asian mass markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial surface technology is displacing conventional drain assemblies in healthcare and food-service specifications, creating asymmetric upgrade cycles across material tiers.
For Market Incumbents: To counter platform disintermediation in China's second-tier cities, anchor specification influence through captive faucet production and modular system bundling. Deepen metallurgical certification depth for copper-alloy drain assemblies against TGA and PMDA standards. Secure distributor exclusivity in India's PLI-subsidized manufacturing zones before domestic fabricators scale capacity. For New Entrants and Emerging Players: India's BIS certification mandate for plumbing products opens a window for certified domestic assembly partnerships with Gujarat and Maharashtra industrial zone operators. Target Vietnam's hospitality renovation segment for vessel sink specifications where multi-material fabrication skill gaps limit incumbent response. Enter through white-label supply to builder-direct platforms seeking second-source stainless steel capacity. For Investors and Strategic Acquirers: The window for entry favors materials-specialist fabricators with metallurgical certification infrastructure. Long-term viability rests on backward integration into stainless steel coil processing or composite resin formulation. Watch India's PLI scheme disbursement velocity as inflection signal for domestic manufacturing cost competitiveness against Chinese imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Coil Processing | Captive 304-grade supply secures margin against nickel volatility and GB standards retooling cycles. |
| Metallurgical Certification Investment | TGA and PMDA hygiene compliance unlocks healthcare procurement premiums in Australia and Japan. |
| Builder-Direct Platform Partnership | Proprietary specification apps in Chengdu and Hangzhou compress selection windows to 72-hour workflows. |
| Composite Granite Surface Technology Licensing | Engineered stone durability targets Australia's high-end kitchen specification channels. |
| PLI-Aligned Domestic Assembly in India | Gujarat and Maharashtra zones reduce import dependency for BIS-certified stainless steel models. |
Study Parameters
Multi-period observation of fixture replacement cycles, certification timeline changes, and procurement platform penetration anchored the trend analysis, supplemented by interviews with sanitary ware plant managers, distributor network heads, hospital procurement committees, and construction project specification officers. Secondary validation drew from customs trade databases, BIS certification registries, GB standards documentation, and WaterMark scheme filings. Bottom-up shipment estimates by product configuration and material tier triangulated against top-down construction spend allocations across residential, commercial, and hospitality end-uses.
Input-output matrices mapped stainless steel coil consumption to finished basin production, composite resin flows to engineered stone fabrication, and faucet component demand to modular bundling penetration. Segmentation dimensions modeled include product type, material grade, installation complexity, application end-use, and regional regulatory cluster. CAGRs derived from slope analysis of replacement cycle frequencies and urban renewal project pipelines. Nickel price volatility assumptions and PLI scheme uptake rates informed scenario boundaries.
The model assumes a particular technology adoption path for antimicrobial copper-alloy surfaces; alternative pathways for ceramic antimicrobial coatings would alter the outlook for metallurgical certification investments. Forecasts reflect documented assumptions about GB standards implementation timelines and ASEAN harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Municipal Water Market
Water Management
France Water Consumption Market
Water Management
Global Water Market
Water Management
Water Trading Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Mexico Water Consumption Market
Water Management
Water Free Urinals Market
Water Management
Smart Water Management Market
Water Management
Spain Water Consumption Market
Water Management
Smart Water Network Market
Water Management
Water Utility Services Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Chile Water Consumption Market
Water Management
Water Filters Market
Water Management
NRW Smart Leak Management Market