
 NRW Smart Leak Management Market | 2026-2036
NRW Smart Leak Management Market Size, Share, and Industry Trends Forecast 2026-2036
NRW Smart Leak Management Market Analytics
Polymer composites are replacing traditional metal housings in acoustic leak detection sensors, which is expanding deployment flexibility and lowering installation costs for utility operators. Xylem Inc. leverages its vertical integration into pump and analytics systems to bundle leak detection with pressure management. ABB Ltd anchors its position through electromagnetic flow metering paired with edge-computing diagnostics. TaKaDu Limited specializes in cloud-based event management software that correlates network anomalies across heterogeneous sensor fleets.
NRW Smart Leak Management encompasses sensor hardware, communication infrastructure, and analytics platforms designed to identify, locate, and quantify fluid losses in pressurized distribution networks, typically achieving leak detection sensitivity down to fractions of a liter per second through acoustic signature analysis or pressure transient monitoring. The primary commercial purpose is to reduce non-revenue water—the difference between water entering distribution and water billed to customers—thereby recovering lost utility income and deferring capital-intensive pipe replacement. Acoustic technology dominates installed base volume due to proven performance in metallic pipes, though optical methods are gaining traction in plastic and composite materials where traditional listening devices underperform. Cloud-based deployment is expanding fastest as utilities prioritize centralized visibility across geographically dispersed networks, while on-premise systems retain strongholds among security-conscious industrial facilities and municipalities with limited broadband access.
The US Environmental Protection Agency and the European Union's Drinking Water Directive both mandate measurable leakage reduction targets, compelling utilities to adopt certified smart monitoring systems or face penalty structures and infrastructure investment orders. China's Ministry of Ecology and Environment enforces dual carbon goals that indirectly pressure water utilities to improve distribution efficiency and reduce energy waste from over-pumping compensatory volumes. Stakeholders must weigh interoperability standards against vendor lock-in risks as procurement shifts toward integrated platform contracts spanning sensors, connectivity, and predictive analytics.
Market Dynamics
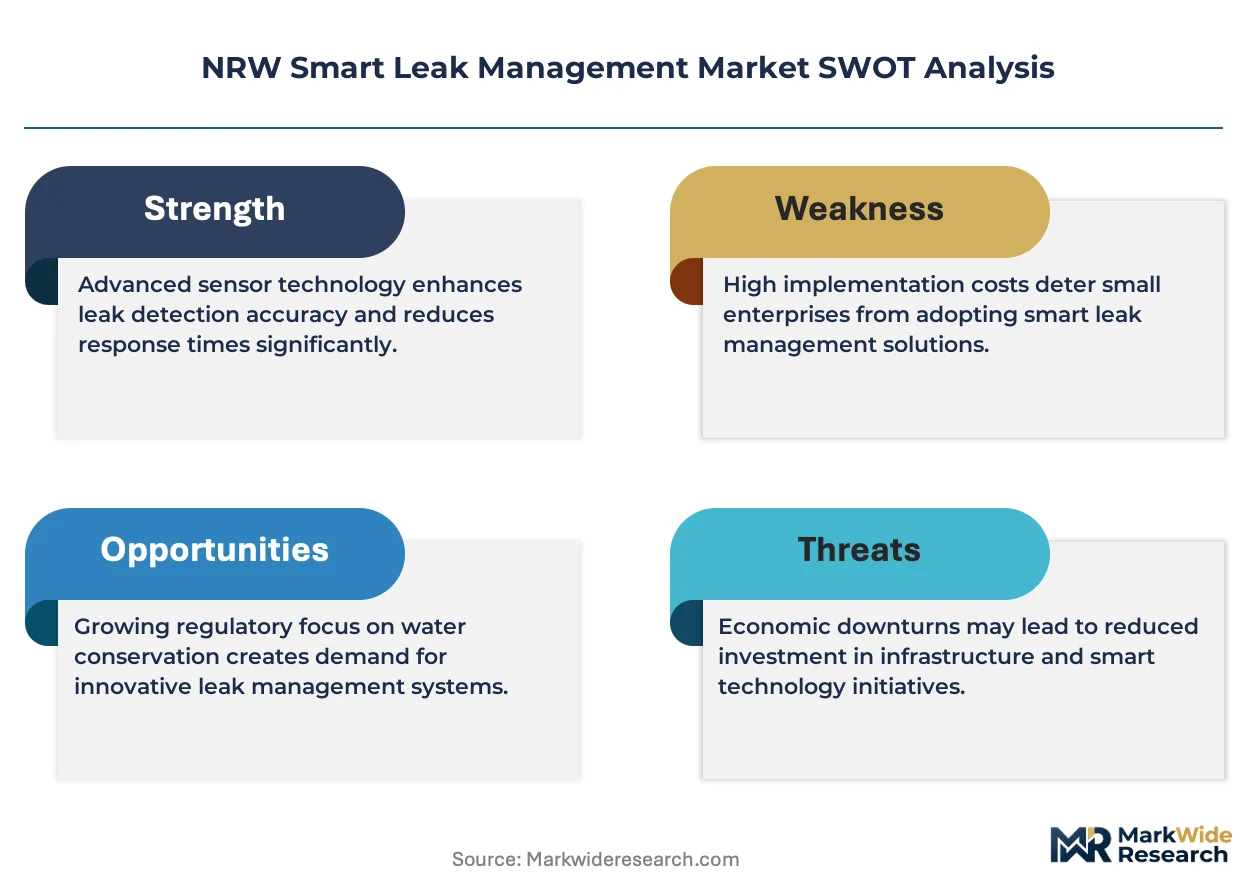
Utilities face mounting pressure from the European Union's Drinking Water Directive revisions to slash leakage rates below 10% of distributed volume, forcing accelerated replacement of passive monitoring with sensor networks that stream acoustic and pressure data to cloud analytics platforms.
Growth Catalysts
- EU Drinking Water Directive:Binding leakage reduction targets compel municipal utilities across Germany, France, and Italy to certify smart monitoring systems or face penalty structures and mandated infrastructure investment orders.
- Acoustic sensor miniaturization:Polymer composite housings displace metal enclosures, cutting installation costs and enabling retrofit deployment in dense urban trenching environments.
- Germany's pipe replacement cycle:Aging cast-iron distribution networks in North Rhine-Westphalia and Bavaria drive concentrated demand for correlating leak detection hardware.
Market Restraints
- Semiconductor supply concentration:Edge-computing sensor modules depend on Taiwan-based foundry capacity, exposing deployment timelines to geopolitical disruption risks.
- Plastic pipe acoustic opacity:Polyethylene and PVC materials absorb pressure-wave signatures, degrading detection sensitivity and forcing utilities toward costlier optical or thermal alternatives.
- Broadband access gaps:Rural municipalities in eastern Germany and southern Italy lack fiber connectivity, delaying cloud-platform adoption and extending on-premise system lifecycles.
Strategic Opportunities
- Cloud-platform bundling:Analytics vendors can wedge into utility procurement cycles by offering sensor-agnostic software subscriptions that correlate heterogeneous hardware fleets.
- China's dual carbon goals:MEE enforcement pressures water utilities to cut energy waste from over-pumping, creating regulatory tailwind for pressure-management integration.
- AI-driven predictive maintenance:Machine learning models trained on historical burst patterns enable shift from reactive repair to preemptive pipe segment replacement.
Industry Challenges
- Cyber-physical security certification:Utilities must navigate IEC 62443 compliance timelines for networked sensors, delaying deployment and inflating project contingency budgets.
- Legacy SCADA integration friction:Proprietary protocols in decades-old control systems resist API standardization, forcing costly middleware development for unified network visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NRW Smart Leak Management Market |
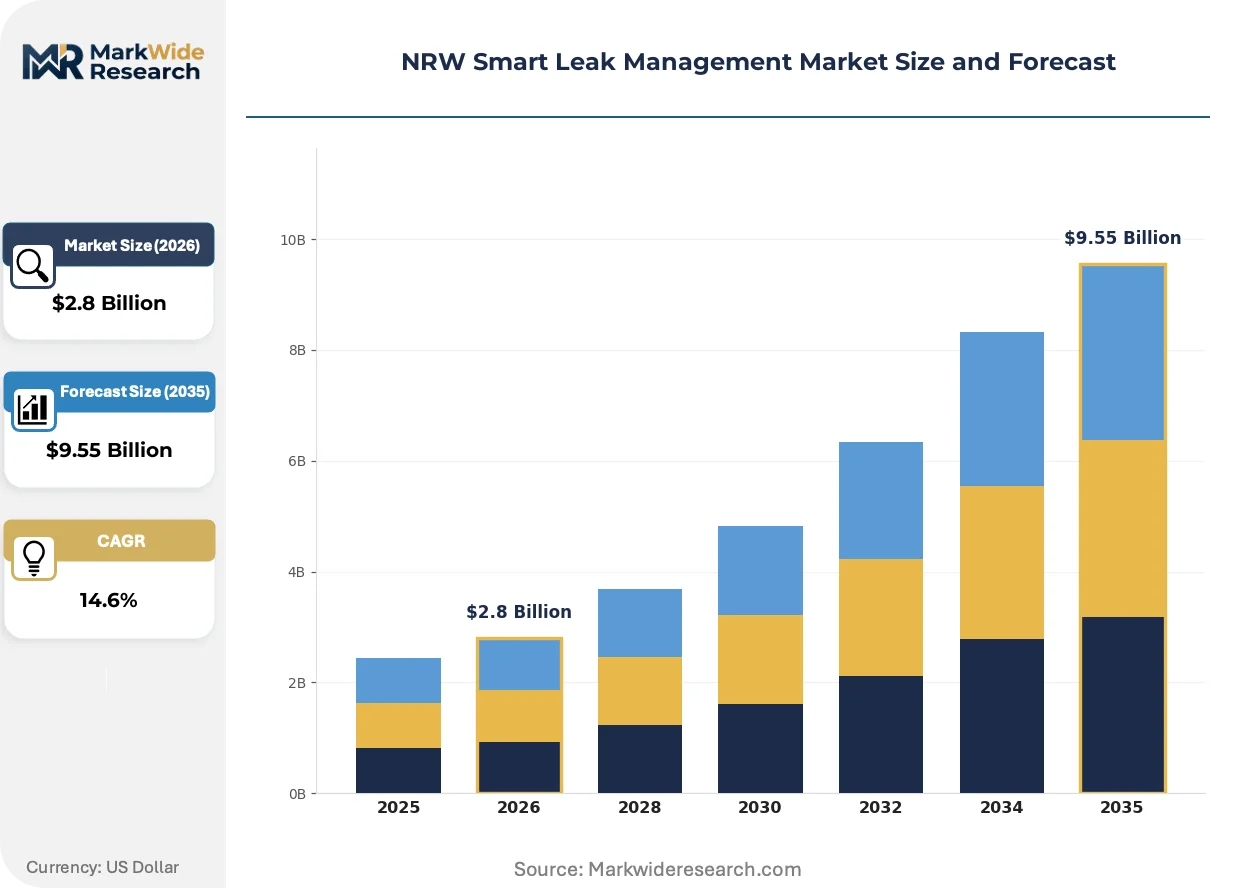
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Electromagnetic, Acoustic, Optical Application: Water Supply, Oil Pipelines, HVAC Systems, Wastewater Management End User: Municipalities, Industrial Facilities, Commercial Buildings, Residential Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Honeywell International Inc., ABB Ltd, Suez Group, Itron Inc., Arad Group, Siemens AG, Hitachi Ltd, Xylem Inc., TaKaDu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NRW Smart Leak Management Market Evolving Landscape
Sensor hardware, connectivity infrastructure, and predictive software are collapsing into unified platform contracts that displace point-solution procurement. This convergence is compressing vendor margins while elevating interoperability standards as the primary competitive battleground.
Acoustic leak detection is converging with satellite-based synthetic aperture radar interferometry, enabling utilities to validate underground pipe distress signals against ground deformation measurements. European water authorities in the Netherlands and United Kingdom are piloting fused data streams to prioritize excavation crews. This technology pairing is compressing the diagnostic phase from weeks to days, reducing street-disruption costs and liability exposure.
REACH chemical restrictions on sensor electronics are forcing manufacturers to reformulate potting compounds and conformal coatings. Industrial consequence includes accelerated validation cycles for new material suppliers. German and French component vendors are responding by vertically integrating polymer synthesis to protect delivery schedules.
Municipal procurement departments are consolidating sensor, connectivity, and analytics spend into single-source framework agreements. Distributors and system integrators lose standalone hardware margins as utilities negotiate direct platform licenses. This consolidation is most visible in Scandinavian markets where Stockholm and Copenhagen water authorities have issued consolidated smart-network tenders exceeding 10-year terms.
NRW Smart Leak Management Market Segmentation
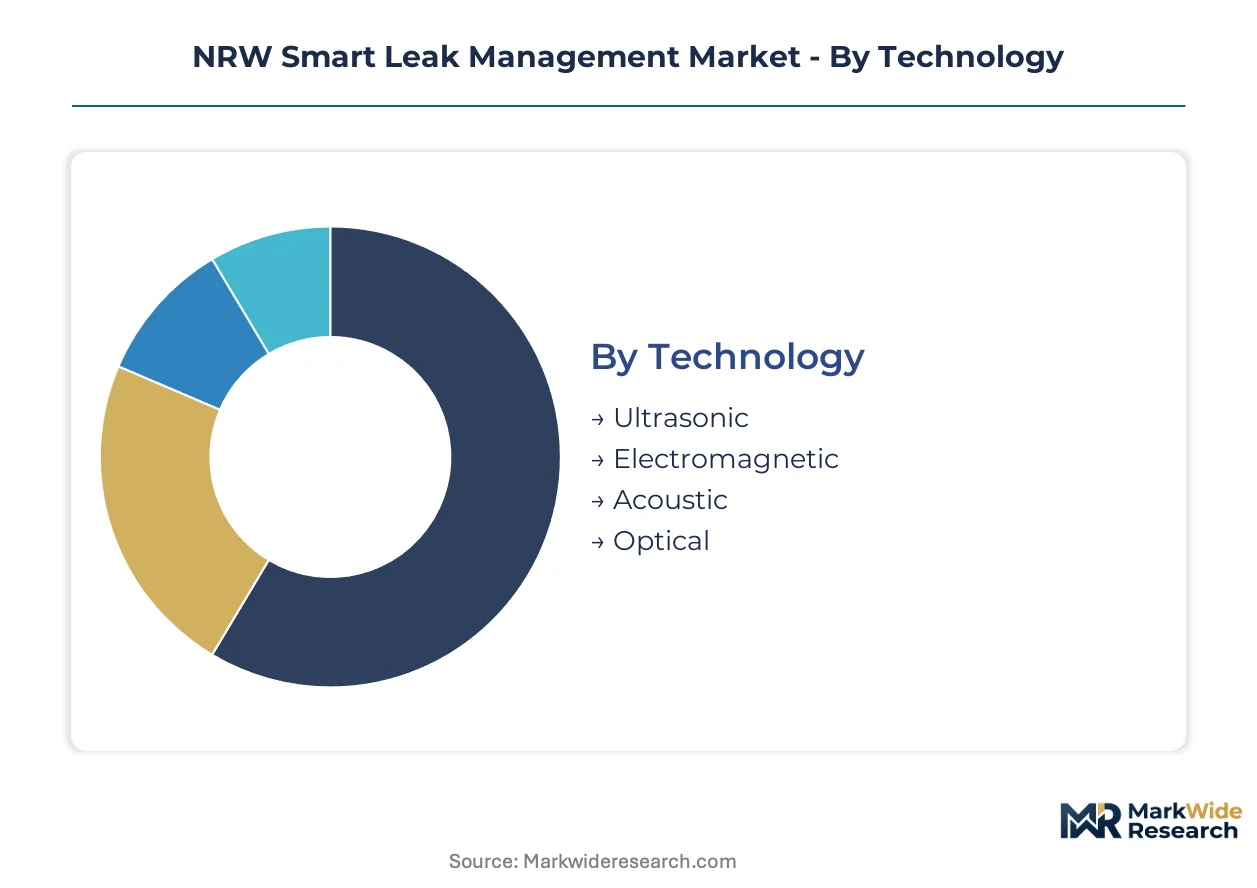
Segmentation in NRW Smart Leak Management reveals how technology choices, infrastructure constraints, and procurement authority shape vendor access and pricing power. Utility operators prioritize detection sensitivity and integration complexity differently across water, oil, and thermal fluid networks.
Technology:
Detection modality determines hardware cost, installation labor, and maintenance cadence across pressurized distribution networks.
- Acoustic:Pressure-wave listening devices analyze fluid turbulence signatures through contact or non-contact sensors. German municipal utilities in North Rhine-Westphalia deploy correlating loggers on cast-iron trunk mains where metallic transmission preserves signal fidelity.
- Ultrasonic:Time-of-flight and Doppler sensors measure flow velocity differentials to infer leakage rates. Demand concentrates in industrial facilities requiring custody-transfer accuracy for chemical and petroleum products where regulatory reporting mandates precision.
- Electromagnetic:Faraday-effect flow meters detect volumetric anomalies without pipe penetration. Water authorities in the Netherlands favor this approach for large-diameter transmission lines where internal access is impractical.
- Optical:Fiber-optic distributed temperature and vibration sensing penetrates polyethylene and PVC materials that absorb acoustic energy. Deployment is climbing fastest in Scandinavian districts with extensive plastic pipe replacement programs.
Acoustic leads on scale; optical gains share fastest where plastic pipe prevalence degrades traditional methods.
Application:
Fluid type and network pressure dictate sensor specification, certification requirements, and software analytics complexity.
- Water Supply:Municipal potable distribution networks drive procurement volume through regulatory leakage reduction mandates. EU Drinking Water Directive enforcement compels German, French, and Italian utilities to certify smart monitoring systems or face penalty structures.
- Wastewater Management:Gravity-fed and pressurized sewer networks require corrosion-resistant housings and methane-safe electronics. Industrial pretreatment facilities in the Netherlands deploy continuous monitoring to comply with discharge permits.
- Oil Pipelines:Hydrocarbon leak detection demands explosion-proof certification and sub-second alarm latency. Pipeline operators in Germany integrate pressure-point analysis with SCADA for trunk line surveillance.
- HVAC Systems:Closed-loop thermal distribution in commercial buildings prioritizes energy efficiency over volumetric loss recovery. Facility managers in France specify battery-powered wireless sensors for retrofit deployment in historic building stock.
Water supply dominates procurement volume; wastewater management expands most quickly under tightening environmental discharge rules.
End User:
Procurement authority and technical staff capacity determine platform complexity preferences and service contract structures.
- Municipalities:Public water utilities issue framework agreements spanning sensors, connectivity, and analytics. Stockholm and Copenhagen authorities have consolidated smart-network tenders exceeding decade-long terms.
- Industrial Facilities:Manufacturing and energy plants require integration with existing process control systems. Chemical processors in Germany specify IEC 62443-compliant devices for cyber-physical security certification.
- Commercial Buildings:Property management groups prioritize rapid installation and minimal disruption. French facility operators favor wireless acoustic loggers for multi-tenant retrofit projects.
- Residential:Single-family and small multi-family buildings drive demand for consumer-grade leak alarms. Italian insurers mandate installation in high-risk zones to limit water damage claims.
Municipalities anchor procurement scale; industrial facilities command premium pricing for integration complexity.
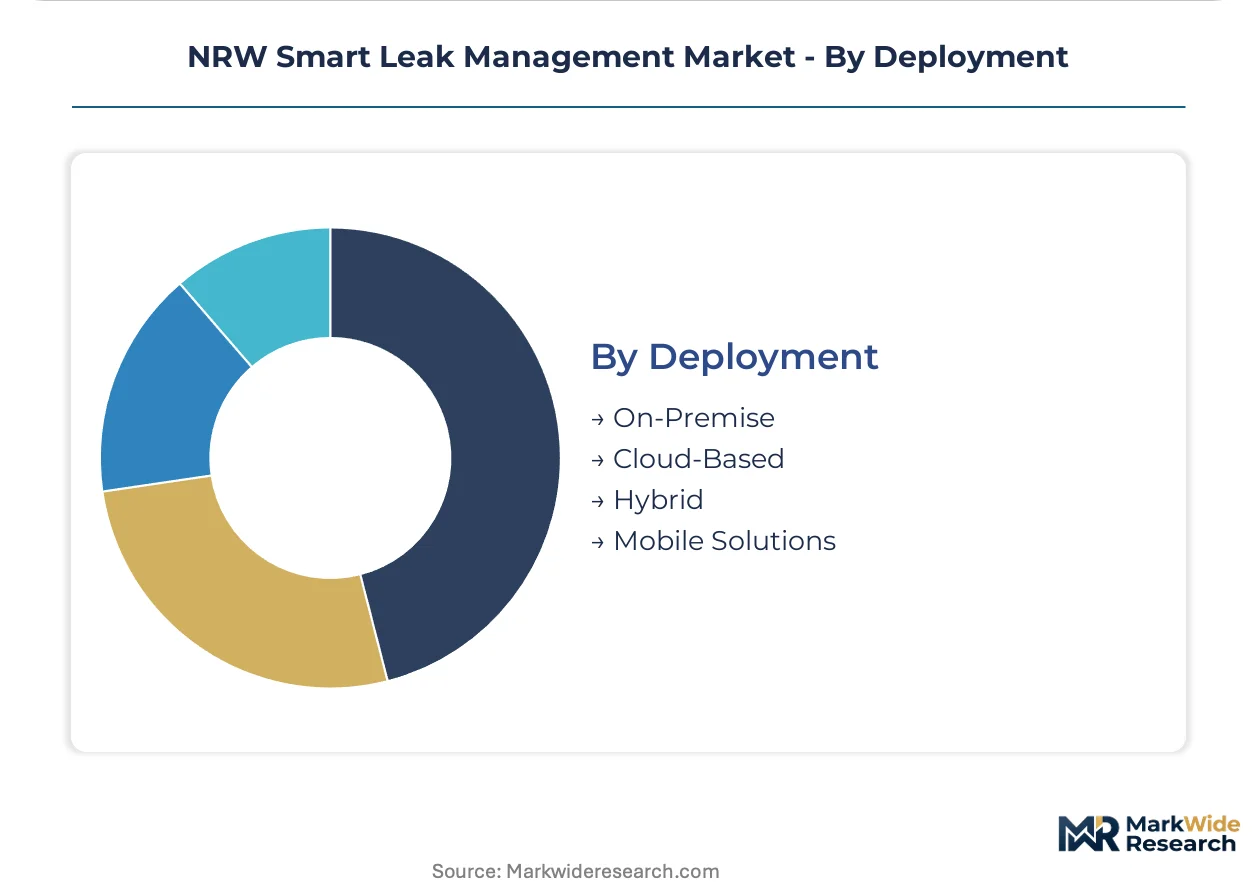
Deployment:
Infrastructure ownership and connectivity availability determine architecture choices between centralized, distributed, and field-responsive systems.
- Cloud-Based:Centralized data lakes enable cross-network correlation and predictive analytics. Scandinavian utilities prioritize this model for geographically dispersed asset portfolios.
- On-Premise:Local servers retain data sovereignty and operate without external connectivity. German industrial facilities specify this architecture for critical infrastructure protection compliance.
- Hybrid:Edge processing with cloud synchronization balances latency and analytical depth. Dutch water authorities pilot this approach for real-time burst detection with historical trend analysis.
- Mobile Solutions:Smartphone-connected portable devices support spot-checking and emergency response. Italian utility crews deploy correlating smartphone apps for rapid leak localization in dense urban environments.
Cloud-based deployment captures the steepest expansion trajectory; on-premise retains strongholds among security-conscious operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's aging municipal water infrastructure anchors procurement volume for acoustic sensor networks and cloud analytics platforms across Europe. Regulatory pressure from Brussels and national leakage targets concentrate replacement cycles in industrialized regions with century-old cast-iron distribution systems.
Germany
North Rhine-Westphalia and Bavaria drive demand through accelerated pipe replacement programs targeting pre-1960 cast-iron networks. The EU Drinking Water Directive mandates leakage reduction below 10% of distributed volume, compelling utilities to certify smart monitoring systems. Stuttgart's water authority issued consolidated framework agreements spanning sensors, connectivity, and predictive analytics.
France
Paris and Lyon metropolitan utilities prioritize retrofit deployment in dense urban trenching environments where polymer composite sensor housings reduce installation costs. ANSM and environmental regulators enforce discharge permit compliance that indirectly pressures distribution efficiency improvements. The Île-de-France region concentrates pilot programs for satellite-based ground deformation validation of leak signals.
United Kingdom
Thames Water and United Utilities deploy correlating acoustic loggers across Victorian-era trunk mains in Greater London and northwest England. Ofwat's leakage performance commitments impose financial penalties for missed reduction targets. Manchester's smart network tender exemplifies decade-long consolidated procurement spanning hardware, software, and maintenance services.
Netherlands
Randstad water authorities favor electromagnetic flow metering for large-diameter transmission lines where internal access proves impractical. REACH chemical restrictions on sensor electronics accelerate validation cycles for reformulated potting compounds. Amsterdam pilots hybrid edge-cloud architectures for real-time burst detection with historical trend analysis.
Italy
Rome and Milan utilities face broadband access gaps that delay cloud-platform adoption in southern regions, extending on-premise system lifecycles. The Ministry of Ecological Transition aligns leakage reduction with national water security objectives. Italian insurers mandate consumer-grade leak alarms in high-risk zones to limit water damage claims.
NRW Smart Leak Management Market Competitive Landscape
Global majors compete with regional champions across platform integration depth and utility procurement scale. The vendor base organizes into three tiers: diversified industrial conglomerates with captive water divisions, pure-play sensor manufacturers with analytics partnerships, and software specialists with sensor-agnostic cloud platforms. Consolidation pressures intensify as municipal procurement shifts toward single-source framework agreements spanning hardware, connectivity, and predictive maintenance.
Within the diversified industrial tier, Honeywell International Inc. and Siemens AG exemplify scale-driven positioning through building automation and infrastructure technology portfolios. ABB Ltd anchors the electromagnetic metering segment with edge-computing diagnostics integration. Xylem Inc. occupies a distinctive position bundling leak detection with pressure management through backward integration into pump systems. TaKaDu Limited represents the software-native archetype, specializing in cloud-based event management that correlates anomalies across heterogeneous sensor fleets deployed by disparate hardware vendors.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd |
| Suez Group |
| Itron Inc. |
| Arad Group |
| Siemens AG |
| Hitachi Ltd |
| Xylem Inc. |
| TaKaDu Limited |
| Others |
Value Network & Pricing Analysis
Municipal procurement consolidation into decade-long framework agreements is forcing sensor manufacturers to absorb upfront hardware costs in exchange for recurring SaaS revenue, compressing project-based margins while elevating subscription pricing power for analytics vendors.
Pricing Analysis
Input-cost pass-through from semiconductor foundry capacity constraints and polymer composite raw materials is intensifying pricing pressure on hardware tiers. Pricing stratifies across premium-certified, standard-compliant, and economy-basic tiers, with differentiation driven by IEC 62443 cyber-physical certification grade and bundled predictive maintenance service levels. Cost compression in the economy tier reflects aggressive Asian manufacturer entry, while premium pricing holds firm among security-conscious German industrial facilities. Municipal utilities exhibit highest price sensitivity due to public budget cycles; oil pipeline operators show lowest sensitivity given explosion-proof certification mandates.
Supply Chain Analysis
Dual-sourcing requirements from European water utilities are fragmenting component procurement across Taiwan for edge-computing modules, Germany for polymer composite housings, and China for battery cell assemblies. The supply chain draws from specialized MEMS microphone foundries, lithium-polymer cell manufacturers, and conformal coating formulators. Single-source vulnerability concentrates in Taiwan-based semiconductor fabrication, exposing deployment timelines to geopolitical disruption. Distribution runs through authorized system integrators who bundle hardware installation with software commissioning for municipal framework contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NRW Smart Leak Management Market functions as a regulatory compounder where EU Drinking Water Directive leakage reduction mandates below 10% create irreversible procurement cycles for certified monitoring systems.
For Market Incumbents: Deploy backward integration into polymer composite housing production to defend margin position against REACH chemical restriction compliance costs. Sensor-agnostic cloud platform licensing represents a critical lever to retain utility relationships as procurement shifts from point hardware to integrated system contracts. Threat from pure-play software specialists correlating heterogeneous sensor fleets demands accelerated API standardization investment. For New Entrants and Emerging Players: Rural municipalities in eastern Germany and southern Italy lacking fiber broadband access constitute the most penetrable buyer archetype for hybrid edge-cloud architectures with intermittent connectivity tolerance. White-space concentration in satellite-based ground deformation validation for leak signal triangulation offers differentiated entry against acoustic-only incumbents. Go-to-market execution should prioritize direct pilot contracts with under-digitized water authorities bypassing consolidated framework tenders. For Investors and Strategic Acquirers: Asymmetric upside sits with sensor-agnostic analytics platforms possessing trained machine learning models on historical burst pattern databases across heterogeneous pipe materials. Long-term viability centers on recurring SaaS revenue visibility exceeding hardware replacement cycles. Acquisition target archetype: software-native event management specialists with utility reference contracts in multiple EU member states. Signal to watch: consolidation of 10-year municipal framework agreements into single-source awards eliminating distributor intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Agnostic Platform Integration | Enables correlation across heterogeneous hardware fleets deployed by disparate municipal utilities. |
| Backward Integration into Polymer Synthesis | Protects delivery schedules against REACH chemical restrictions on conformal coatings and potting compounds. |
| Hybrid Edge-Cloud Architecture Deployment | Addresses broadband access gaps delaying cloud adoption in rural German and Italian municipalities. |
| IEC 62443 Cyber-Physical Certification | Unlocks procurement eligibility for security-conscious industrial facilities and critical infrastructure operators. |
| Satellite SAR Interferometry Partnership | Compresses diagnostic timelines from weeks to days through fused ground deformation and acoustic signal validation. |
Research Methodology
Bottom-up municipal utility procurement modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with water authority planning officers, smart network procurement managers, SCADA integration specialists, and aftermarket service directors combined with secondary validation from EU Drinking Water Directive implementation reports, national statistics office water loss databases, and customs trade data for acoustic sensor components. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Input-output matrices mapping sensor hardware unit economics against SaaS subscription renewal rates drive volume and value projections across the analysis window. Segmentation dimensions modeled include detection modality, deployment architecture, end-user procurement authority, and regional regulatory enforcement intensity. CAGRs derive from utility capital expenditure cycle analysis and smart meter penetration benchmarks. Industry-specific forecast inputs incorporate pipe replacement program timelines and broadband infrastructure rollout schedules.
Underlying measurement precision varies by segment; cloud-based deployment and acoustic technology categories carry tighter precision than emerging optical methods. Forecasts reflect assumptions on EU member state transposition timelines for Drinking Water Directive leakage targets. Deviation in semiconductor foundry capacity allocation or Taiwan geopolitical stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
North America Water Sink Market
Water Management
Water Filters Market
Water Management
Global Water Market
Water Management
Chile Water Consumption Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Water Utility Services Market
Water Management
France Water Consumption Market
Water Management
Water Free Urinals Market
Water Management
Spain Water Consumption Market
Water Management
Mexico Water Consumption Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Municipal Water Market
Water Management
Smart Water Network Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Water Trading Market
Water Management
Asia-Pacific Water Sink Market